
 Oilfield Power Generation Market | 2026-2036
Oilfield Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Power Generation Market Analytics
Tier 4 Final compliance is redrawing procurement priorities across the oilfield power generation landscape. Caterpillar Inc sustains manufacturing scale across its large-engine foundry network, giving it leverage in the 11-20 MW and over-20 MW classes where offshore platforms cluster. Cummins Inc differentiates through its modular power plant architecture, allowing operators to scale from 1 MW drilling camps to 20 MW production facilities without platform redesign. Baker Hughes navigates the energy transition by integrating its gas turbine portfolio with carbon capture-ready power island configurations.
Oilfield power generation encompasses prime movers, generator sets, and auxiliary power systems engineered to deliver continuous or standby electrical output in hydrocarbon extraction environments, typically operating at 480V to 13.8kV with ambient temperature ratings from minus 40°C to plus 50°C. Natural gas gensets now lead the power source category as associated gas capture economics improve at the wellhead, while diesel retains dominance in remote exploration drilling where pipeline connectivity remains absent. The 6-10 MW capacity band represents the fastest-growing segment, driven by pad drilling configurations that consolidate multiple wells under centralized power rather than deploying discrete units per wellbore.
The EPA enforces Tier 4 Final and NSPS OOOO standards that limit NOx and particulate emissions from oilfield engines, compelling operators to adopt selective catalytic reduction or face permitting restrictions in ozone non-attainment zones. API RP 14F and NFPA 30B provide electrical installation and fuel storage safety benchmarks that shape equipment specification for offshore and onshore deployments alike. Stakeholders must weigh the capital cost of emissions-compliant prime movers against the operational flexibility of dual-fuel architectures as flared gas regulations tighten across major producing jurisdictions.
Market Dynamics
The EPA's Tier 4 Final emissions mandate is compressing the viable prime mover pool for onshore drilling contractors, forcing rapid capital redeployment toward after-treatment systems and dual-fuel architectures.
Growth Catalysts
- Associated Gas Capture Economics:Wellhead flaring regulations in Texas and North Dakota now make on-site power generation from captured gas cost-competitive with diesel logistics.
- Pad Drilling Consolidation:Multi-well pad configurations in the Permian Basin concentrate power demand, favoring centralized 6-10 MW installations over distributed smaller units.
- EPA Tier 4 Final Compliance Deadlines:Non-attainment zone permitting restrictions are accelerating engine fleet turnover toward cleaner-burning natural gas and dual-fuel systems.
Market Restraints
- Steel and Rare Earth Input Volatility:Generator set manufacturing faces margin pressure from fluctuating electrical steel and permanent magnet material costs.
- Specialized Technician Scarcity:After-treatment system maintenance requires certified SCR and DPF technicians concentrated in Gulf Coast service hubs.
- Diesel Infrastructure Lock-In:Remote exploration sites in Alaska and Canadian oil sands lack pipeline connectivity, perpetuating liquid fuel dependence.
Strategic Opportunities
- Flared-Gas-to-Power in the Bakken:North Dakota's gas capture mandates create captive fuel supply for mobile power units at drilling sites.
- Carbon Capture-Ready Power Islands:Integration of gas turbines with post-combustion capture systems opens offshore platform retrofit potential.
- Modular Microgrid Architectures:Containerized battery-genset hybrids enable rapid deployment in West Texas without permanent infrastructure.
Industry Challenges
- After-Treatment Integration Complexity:SCR and DPF retrofits on legacy engine platforms demand recalibration of fuel maps and cooling systems.
- Emissions Certification Timelines:EPA and CARB verification processes for new engine families extend product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Power Generation Market |
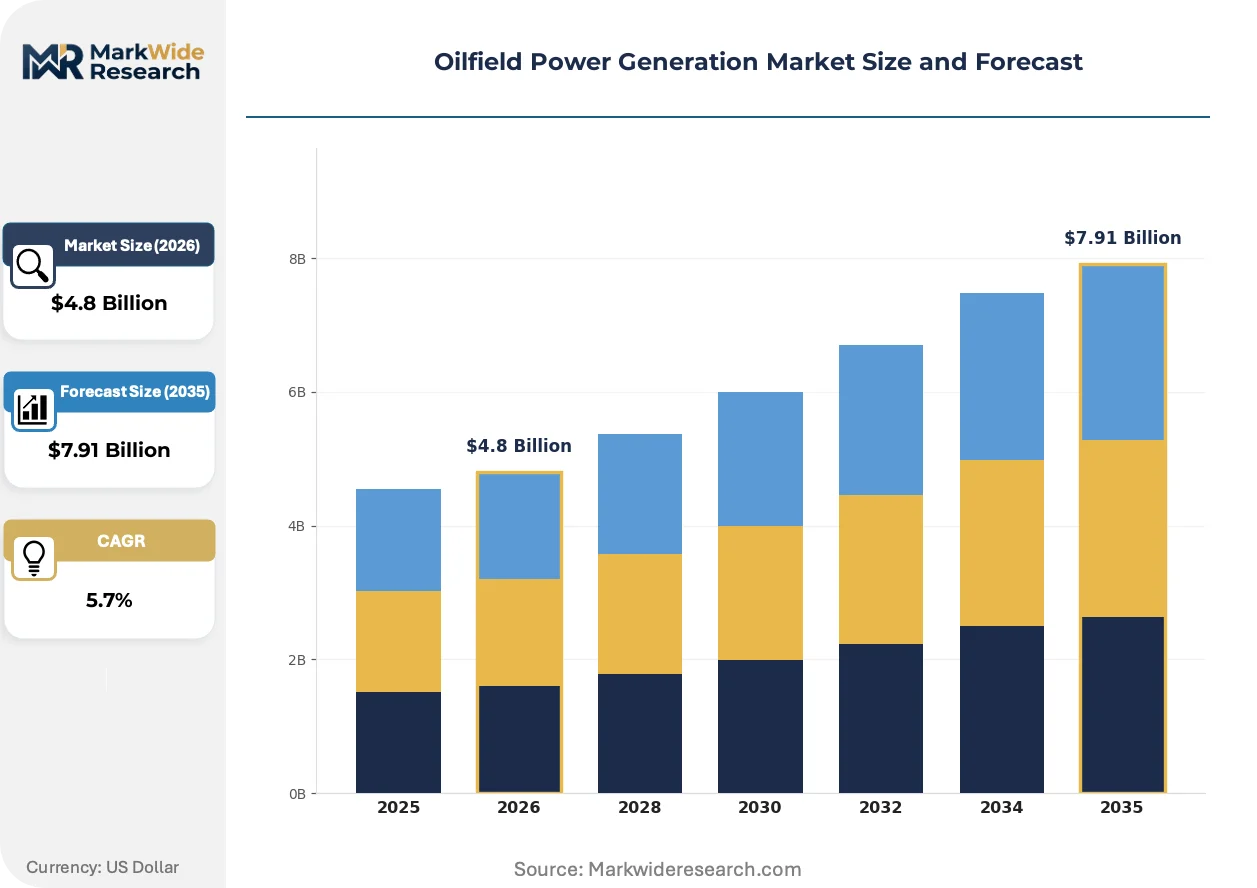
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Natural Gas, Diesel, Biogas, Renewable Energy Installation Type: Onshore, Offshore, Permanent, Mobile Capacity: 1-5 MW, 6-10 MW, 11-20 MW, Over 20 MW Application: Drilling, Production, Refining, Compression |
| Companies Covered | Kohler Power, Schlumberger, Caterpillar Inc, Baker Hughes, Halliburton, Cummins Inc, GE Power, Weatherford International, Generac Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Power Generation Market Evolving Landscape
Dual-fuel engine technology is compressing the traditional diesel-natural gas boundary, while digital load management systems enable real-time optimization of multi-source power islands.
Modular power plant architectures are decomposing the conventional fixed-capacity generator procurement model. Shale operators in the Eagle Ford and Delaware Basin now specify scalable 1-20 MW building blocks rather than purpose-built installations. This flexibility is decomposing capital commitment timelines and allowing production-scale power to track drilling program phasing.
REACH chemical restrictions and the EU Green Deal's methane intensity benchmarks are reshaping equipment export requirements for European oilfield service contractors. Manufacturers serving North Sea platforms must now document full lifecycle carbon footprints for power generation assets. The 11-20 MW offshore segment is responding with integrated gas turbine and heat recovery configurations.
Power-as-a-service contracting is displacing capital purchase models among independent exploration companies. Providers like Aggreko and APR Energy now own and operate mobile power assets, charging per-kWh rates that bundle fuel, maintenance, and emissions compliance. This shift is most visible in the Permian Basin, where private equity-backed drillers prioritize balance sheet flexibility over equipment ownership.
Oilfield Power Generation Market Segmentation
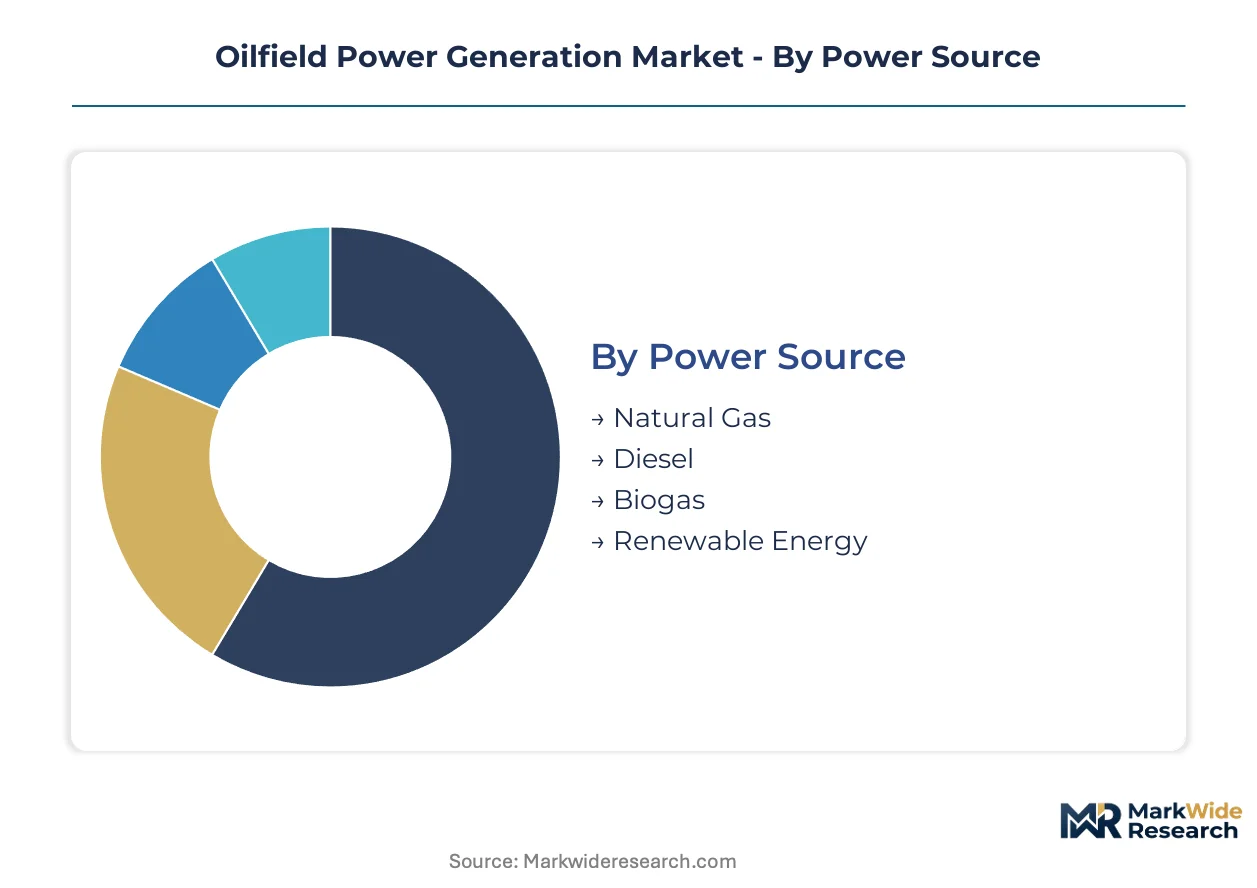
Oilfield power procurement decisions fragment across fuel availability, mobility requirements, and emissions jurisdiction. Equipment specification varies sharply between Permian Basin pad drilling and North Sea platform operations, with regulatory thresholds determining prime mover eligibility.
Power Source:
EPA Tier 4 Final and the EU Green Deal's methane intensity benchmarks create divergent compliance pathways for each fuel category, with natural gas capturing regulatory preference in connected basins.
- Natural Gas:Associated gas capture economics at the wellhead now rival diesel logistics costs in Texas and North Dakota. EPA flaring restrictions and pipeline proximity drive procurement toward gas-fired gensets in the Permian Basin, where dual-fuel capability provides operational hedge against supply interruptions.
- Diesel:Retains dominance in remote exploration zones lacking pipeline infrastructure, particularly Alaskan North Slope and Canadian oil sands operations. Tier 4 Final after-treatment requirements—SCR and DPF systems—add capital burden but preserve operational flexibility where gas connectivity remains absent.
- Biogas:Landfill and anaerobic digester methane streams find niche application in California's Central Valley oilfields under CARB LCFS credit mechanisms.
- Renewable Energy:Solar-battery hybrids penetrate West Texas microgrids where ERCOT pricing volatility and flared gas displacement incentives align.
Natural Gas handles the majority of throughput; Renewable Energy is the fastest mover on share.
Installation Type:
Capital commitment horizons and relocation frequency separate procurement patterns, with mobility premiums traded against infrastructure permanence.
- Onshore:Pad drilling consolidation in the Delaware Basin concentrates power demand at fixed locations, favoring skid-mounted or containerized installations over truly mobile trailer sets. Surface lease terms and water disposal proximity dictate siting flexibility.
- Offshore:Platform-based installations in the Gulf of Mexico and North Sea demand explosion-proof enclosures, marine-grade coatings, and crane-lift modularization. ABS and DNV certification requirements extend procurement cycles.
- Permanent:Centralized power islands at production facilities achieve economies through heat recovery integration and long-term maintenance contracts.
- Mobile:Power-as-a-service providers deploy trailer-mounted units to exploratory drilling programs, transferring balance sheet risk from E&P operators to rental fleets.
Onshore absorbs the greatest installed base; Mobile installations are expanding most quickly as private equity-backed drillers prioritize capital efficiency.
Capacity:
Well count per pad and artificial lift requirements scale power demand, with mid-range capacities capturing pad drilling economics.
- 6-10 MW:Multi-well pad configurations consolidate drilling, completion, and early production power under centralized units. Permian Basin operators specify this band to avoid redundant mobilization costs across phased development.
- 11-20 MW:Offshore platforms and large-scale thermal EOR projects in California's Kern County demand sustained high-output prime movers with redundancy margins.
- 1-5 MW:Single-well exploration and workover rigs in scattered shale plays retain discrete unit deployment.
- Over 20 MW:Integrated gas turbine power islands serve central processing facilities in Norway's Johan Sverdrup field and similar megaprojects.
6-10 MW carries the dominant share of new orders; 11-20 MW shows the steepest expansion trajectory in offshore retrofit cycles.
Application:
Load profile characteristics—continuous base load versus cyclical peak demand—determine engine sizing and fuel strategy.
- Drilling:Top drive, mud pump, and drawworks loads impose severe transient demands, favoring dual-fuel engines with rapid load-following capability. Power-as-a-service penetration is highest here.
- Production:Artificial lift—ESP and gas lift systems—requires reliable continuous power, driving preference for natural gas baseload units with diesel backup.
- Refining:Cogeneration configurations exploit waste heat for process steam, with capacity bands typically exceeding 20 MW.
- Compression:Gas gathering and reinjection compressors in the Bakken and Marcellus run dedicated gensets sized to mechanical load rather than electrical export.
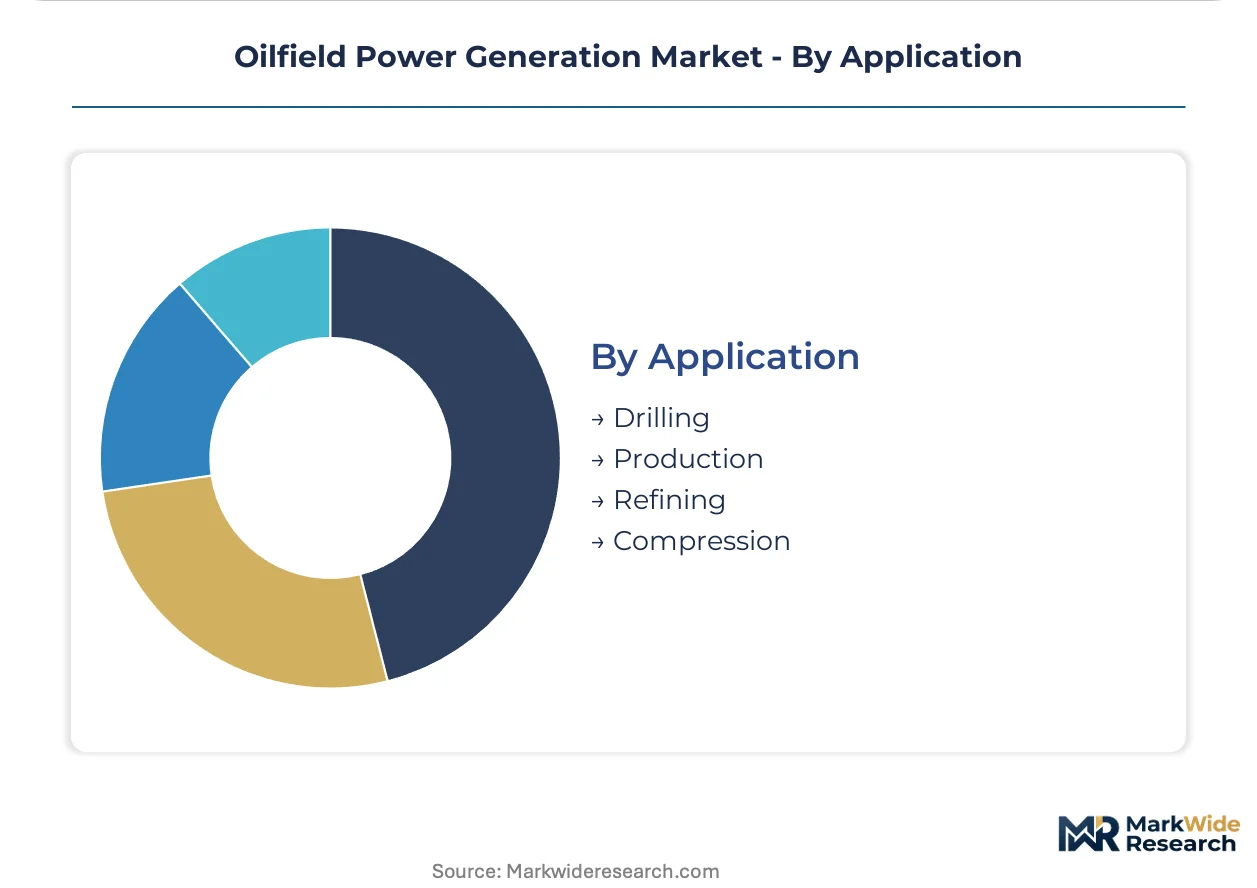
Production accounts for the largest installed capacity; Drilling is gaining share fastest through rental fleet expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in oilfield power generation equipment tilt heavily toward manufacturing concentration in the United States and Germany, while demand absorption clusters in hydrocarbon-rich basins across North America and the Middle East. Equipment flows track drilling activity cycles, with modular genset shipments rising to Permian Basin operators and offshore turbine packages heading to North Sea platforms.
United States
Pad drilling consolidation in the Permian Basin and Eagle Ford Shale concentrates demand for 6-10 MW centralized power installations. EPA Tier 4 Final enforcement in ozone non-attainment zones accelerates fleet turnover toward dual-fuel and natural gas systems. Midland-Odessa anchors the highest density of mobile power-as-a-service deployments, with rental fleets tracking rig counts across West Texas.
Norway
Offshore platform electrification and carbon capture integration drive demand for 11-20 MW gas turbine power islands in the North Sea. The EU Green Deal's methane intensity benchmarks reshape procurement specifications for equipment serving Johan Sverdrup and similar megaprojects. Stavanger clusters engineering expertise for subsea power distribution and platform retrofit cycles.
Saudi Arabia
Gas turbine demand for central processing facilities rises with offshore field development in the Arabian Gulf. The country's national oil company prioritizes captive power efficiency in its long-term supply agreements. Dhahran concentrates technical specification authority for power island configurations across the Eastern Province production corridor.
Canada
Remote oil sands operations in Alberta perpetuate diesel dependence where pipeline connectivity remains absent, preserving liquid fuel generator demand. Provincial methane regulations for upstream operations tighten wellhead gas capture requirements. Fort McMurray anchors the largest concentration of off-grid power installations in the Athabasca basin.
United Arab Emirates
Offshore artificial island development and sour gas processing expansion drive demand for high-reliability prime movers in extreme ambient conditions. Federal emissions frameworks for industrial facilities tighten NOx permitting thresholds. Abu Dhabi concentrates procurement decision-making for power generation assets serving Upper Zakum and related megaprojects.
Oilfield Power Generation Market Competitive Landscape
Concentration sits with diversified industrial conglomerates that span engine manufacturing, oilfield services, and power systems integration. The vendor base stratifies across three tiers: full-spectrum prime mover manufacturers with foundry-scale production, modular power plant architects emphasizing configurability, and rental fleet operators monetizing assets through power-as-a-service contracting. Dominant competitive moves include vertical integration into after-treatment system manufacturing and strategic partnerships for carbon capture-ready power island development.
Among diversified engine and power system manufacturers, Caterpillar Inc, Cummins Inc, and Baker Hughes occupy positions that exemplify distinct archetypes. Caterpillar Inc represents scale-driven manufacturing depth across large-engine classes. Cummins Inc anchors modular architecture specialization that enables capacity scaling without platform redesign. Baker Hughes exemplifies energy transition positioning through integrated gas turbine and carbon capture system configurations. These three entities collectively illustrate how procurement priorities around emissions compliance, operational flexibility, and transition readiness reshape competitive positioning.
| Leading Market Players |
|---|
| Kohler Power |
| Schlumberger |
| Caterpillar Inc |
| Baker Hughes |
| Halliburton |
| Cummins Inc |
| GE Power |
| Weatherford International |
| Generac Power Systems |
| Others |
Value Network & Pricing Analysis
ABS and DNV certification regimes gate both supplier qualification and price differentiation simultaneously in offshore oilfield power generation, forcing manufacturers to absorb marine-grade engineering costs that tier pricing across compliant and non-compliant equipment pools. Tier 4 Final compliance timelines in the United States compress procurement cycles, concentrating buyer leverage toward certified suppliers while diesel-gas fuel arbitrage reshapes total cost of ownership calculations across basins.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bundle prime mover supply with after-treatment system maintenance and fuel management services. Price differentiation stems from EPA certification tier and volume scale, with multi-unit pad drilling contracts commanding standard-tier rates while single-well exploration rigs absorb premium pricing for mobile deployment flexibility. Pricing pressure stems from electrical steel input volatility, with margins tightening most acutely in the 1-5 MW trailer-mounted segment where rental fleet operators compete aggressively on per-kWh rates. Private equity-backed drillers exhibit highest price sensitivity, prioritizing power-as-a-service opex models over capital-intensive equipment ownership.
Supply Chain Analysis
Extended lead times for SCR catalyst substrates and marine-grade electrical enclosures signal inventory strain across Tier 1 supplier networks. Manufacturing concentrates in the United States, Germany, and Japan, with large-engine foundries in Peoria and Mannheim anchoring high-capacity production for 11-20 MW offshore units. Supply chains rest on rare earth permanent magnets, high-grade electrical steel, and specialized SCR ceramic cores. Single-source vulnerability concentrates in permanent magnet supply from concentrated mining jurisdictions. Distribution runs through OEM-direct channels for permanent installations and rental fleet aggregators for mobile power-as-a-service deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pad drilling consolidation and flared-gas capture economics position this market in early-cycle expansion, with associated gas-to-power adoption creating sustained equipment replacement demand across Permian Basin operators.
For Market Incumbents: Secure backward integration into after-treatment system manufacturing to defend margins against commodity input volatility and specialized technician scarcity. Expand Gulf Coast service hub capacity to capture maintenance revenue from Tier 4 Final retrofit cycles, while accelerating dual-fuel platform certification to preempt emerging modular power plant architects.
For New Entrants and Emerging Players: EPA Tier 4 Final fast-track certification unlocks entry into the 6-10 MW pad drilling segment where incumbent lead times extend 12-18 months. Target West Texas power-as-a-service contracts as the most penetrable white space, leveraging containerized battery-genset hybrid architectures to bypass permanent infrastructure requirements and capture private equity-backed driller demand.
For Investors and Strategic Acquirers: EPA Tier 4 Final enforcement deadlines reshape the acquisition landscape toward carbon capture-ready power island developers and SCR/DPF retrofit specialists. Long-term viability centers on energy transition positioning across the 5-10 year horizon, with gas turbine integration capabilities and offshore platform electrification expertise defining premium target archetypes. Monitor North Dakota gas capture mandate compliance rates as the signal for Bakken basin equipment demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Platform Certification | EPA Tier 4 Final compliance unlocks Permian Basin procurement eligibility for blended natural gas-diesel architectures. |
| After-Treatment System Integration | SCR and DPF captive manufacturing secures margin control against rare earth ceramic supply volatility. |
| Power-as-a-Service Fleet Expansion | Per-kWh contracting transfers balance sheet risk from E&P operators to rental providers in West Texas. |
| Carbon Capture-Ready Power Island Development | Post-combustion capture integration opens Norwegian North Sea platform retrofit and Johan Sverdrup upgrade cycles. |
| Gulf Coast Service Hub Capacity Buildout | Certified technician concentration addresses SCR/DPF maintenance scarcity and captures recurring revenue streams. |
Research Methodology
Operator-level perspectives from drilling contractors, power-as-a-service fleet managers, E&P procurement directors, and after-treatment system technicians anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA engine certification databases, FERC power project filings, and ABS/DNV marine equipment registries. Bottom-up rig count and power demand modeling triangulated against top-down generator set production and trade flow analysis.
Sensitivity analysis tested forecast robustness across fuel price volatility scenarios, emissions regulation enforcement intensity, and pad drilling penetration rates. Segmentation dimensions spanned power source, installation type, capacity tier, and application across the projection horizon. CAGRs derived from equipment replacement cycle analysis, drilling activity correlations, and associated gas capture economics trajectory. Industry-specific inputs included wellhead flaring volume data and power-as-a-service contract penetration rates.
Decision-makers should treat outputs as directional under sustained Tier 4 Final enforcement and pad drilling consolidation assumptions; material deviation in emissions policy stringency or unconventional drilling economics would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Subsea Power Grid System Market
Power Generation
Combined Cycle Gas Turbine Market
Power Generation
Global Black Start Generator Market
Power Generation
Steam Turbine Market
Power Generation
Marine Power Plant Market
Power Generation
Global Gas Turbines Market
Power Generation
Peaking Power Plant Market
Power Generation
Europe Thermal Power Market
Power Generation
North America Distributed Power Generation Market
Power Generation
Power Generation Technologies Market
Power Generation
Distributed Power Generation Market
Power Generation
Venezuela Power Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
Brazil Power Plant EPC Market