
 US Water & Wastewater Valves Market | 2026-2036
US Water & Wastewater Valves Market Size, Share, and Industry Trends Forecast 2026-2036
US Water & Wastewater Valves Market Insights
The Gulf Coast manufacturing corridor is reconfiguring valve supply chains for water infrastructure resilience. Emerson Electric Co. leverages automation integration across electric actuation lines. Flowserve Corporation anchors heavy industrial applications with specialized corrosion-resistant alloys. Mueller Water Products, Inc. dominates municipal procurement channels through extensive distributor networks.
Water and wastewater valves are mechanical devices engineered to control, isolate, or regulate fluid flow in pressurized piping systems, typically constructed with pressure ratings from 150 to 2500 PSI and seal configurations meeting AWWA C500 standards for buried service. These valves serve critical functions in potable water distribution, sewage collection, and treatment plant process control. Butterfly valves lead municipal installations due to lower torque requirements and compact vault footprints. Stainless steel material grades capture premium specification work where chloride resistance justifies higher unit costs. Electric actuation is displacing manual operators in remote monitoring architectures.
EPA enforcement of revised Lead and Copper Rule provisions is accelerating full-lead-service-line replacement schedules across utilities. AWWA standards and NSF/ANSI 61 certifications define product eligibility for federally funded water infrastructure grants. State revolving fund administrators in California and New York are layering local Buy America compliance atop federal requirements. Stakeholders must track how IIJA disbursement timelines intersect with foundry capacity constraints and qualified domestic supplier lists.
Market Dynamics
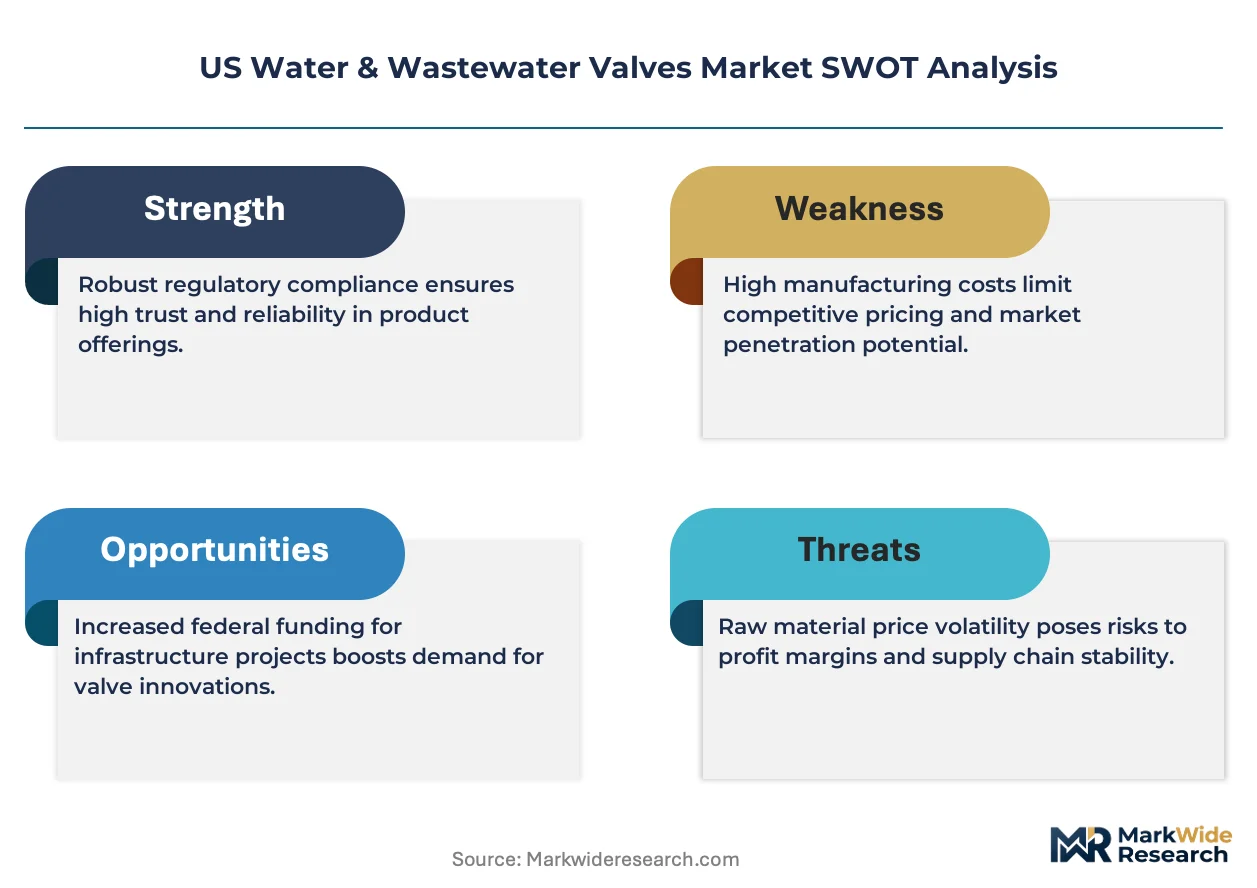
EPA Lead and Copper Rule revisions are compressing replacement timelines for lead service lines, forcing utilities to accelerate procurement of compliant valve materials while foundry capacity struggles to match disbursement velocity from IIJA infrastructure grants.
Growth Catalysts
- IIJA Grant Disbursement:Federal infrastructure funding is unlocking deferred replacement programs across municipal utilities, particularly in legacy systems with century-old gate valve inventories.
- Texas and Florida Urbanization:Rapid population growth in Houston, Dallas-Fort Worth, Miami-Dade, and Tampa Bay is straining distribution networks and triggering valve capacity expansion projects.
- Electric Actuation Migration:SCADA integration requirements are displacing manual operators in remote monitoring architectures, creating specification pull for smart valve packages.
Market Restraints
- Domestic Foundry Bottlenecks:Qualified US iron and ductile iron casting capacity is concentrated in a handful of Great Lakes region suppliers, creating procurement queue risks.
- Buy America Compliance Layering:State revolving fund administrators in California and New York are imposing stricter domestic content thresholds atop federal requirements, disqualifying some imported components.
- Chloride-Induced Corrosion:Coastal Florida and Gulf Coast utilities face accelerated degradation of standard cast iron bodies, forcing premature replacement cycles.
Strategic Opportunities
- Great Lakes Valve Replacement Wave:Municipal utilities across Michigan, Ohio, and Wisconsin are launching decade-long programs to replace aging gate and check valve infrastructure.
- NSF/ANSI 61 Certification Arbitrage:Smaller fabricators can capture specification work by achieving drinking water contact certifications that unlock federally funded project eligibility.
- Stainless Steel Premium Tiers:Super-duplex and 316L grades are penetrating coastal desalination and brackish water applications where chloride resistance justifies unit cost premiums.
Industry Challenges
- AWWA C500 Certification Timelines:Third-party testing for buried service seal configurations extends product launch cycles by 8-14 months, compressing competitive response windows.
- Legacy System Integration Friction:Electric actuation retrofits into 1950s-era valve vaults require custom adapter kits and civil modifications, inflating installed costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Water & Wastewater Valves Market |
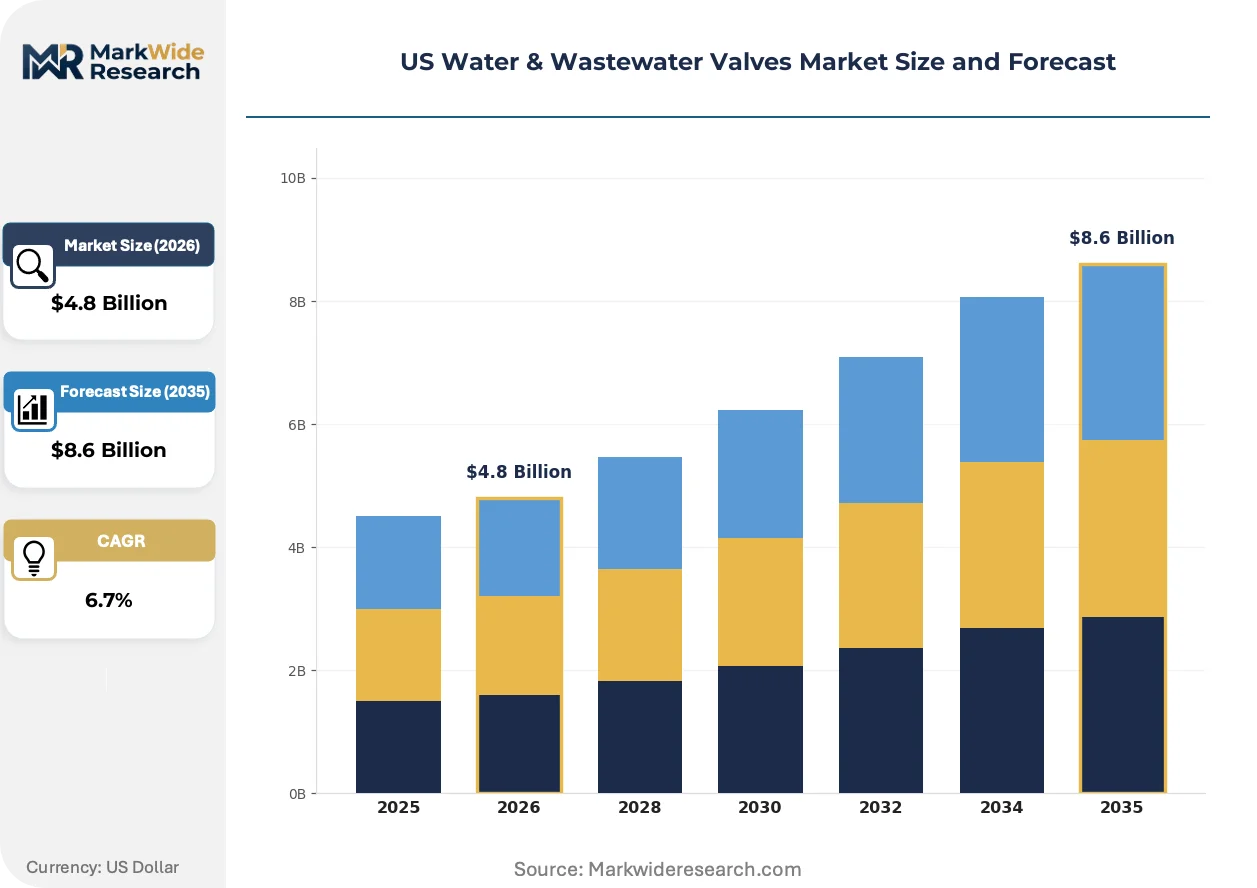
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valves, Globe Valves, Check Valves, Butterfly Valves End User: Municipal, Industrial, Residential, Irrigation Material: Cast Iron, Stainless Steel, PVC, Brass Actuation Type: Manual, Electric, Pneumatic, Hydraulic |
| Companies Covered | AMERICAN Cast Iron Pipe Company, American Valve Inc., Ari Valve Corporation, Emerson Electric Co., Flowserve Corporation, Crane Holdings, Baker Hughes Company, Schlumberger Limited, Mueller Water Products, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Water & Wastewater Valves Market Trends and Innovations
Digital valve positioners and predictive maintenance algorithms are restructuring how utilities manage distribution network reliability, shifting capital deployment from reactive replacement toward condition-based intervention.
Advanced polymer seat materials with PTFE-impregnated elastomers are extending butterfly valve cycle life in abrasive raw water intake applications. Arizona and Nevada water treatment authorities are specifying these compounds for Colorado River sourcing facilities. The technology is rendering obsolete traditional Buna-N seals in high-silt environments.
EPA enforcement of revised Lead and Copper Rule provisions is mandating full lead-service-line replacement rather than partial repairs. This regulatory compression is eliminating repair clamp specifications from municipal procurement lists. Texas and Florida utilities are front-loading valve replacement schedules to synchronize with street excavation coordination.
Consolidated procurement through regional water authority cooperatives is displacing individual municipal bidding processes. The Southern California Water Committee and similar multi-utility purchasing alliances are negotiating master valve supply agreements with volume-tier pricing. This concentration is most visible in California's state revolving fund project pipelines.
US Water & Wastewater Valves Market Segmentation
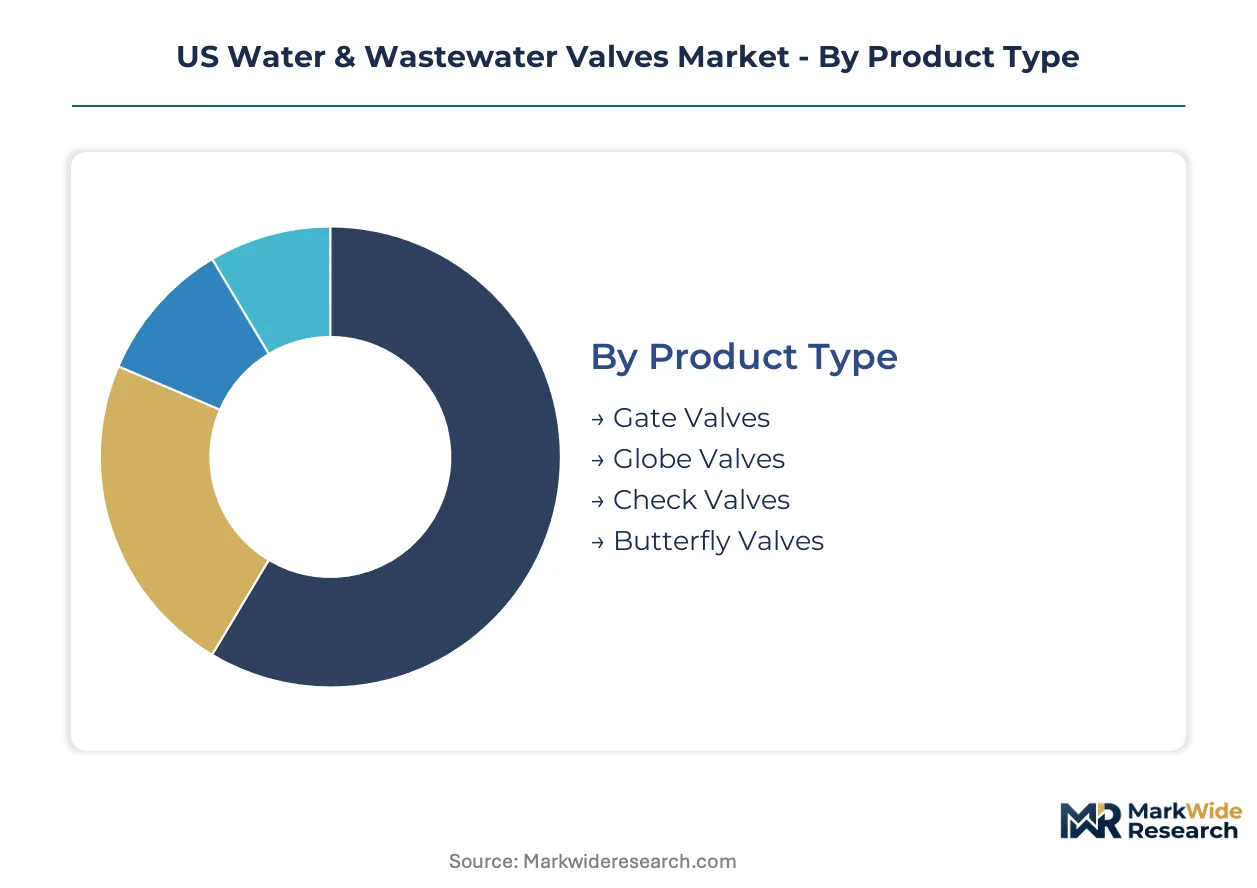
Valve specification in US water infrastructure follows distinct procurement pathways shaped by pressure ratings, burial depth, and regulatory compliance tiers. Segment boundaries determine which fabricators qualify for federal grant eligibility and which installation contractors carry specialized actuator integration capabilities.
Product Type:
Application requirements across distribution networks, treatment facilities, and collection systems create divergent valve performance specifications.
- Gate Valves:Parallel or wedge-disc designs rated for 150-2500 PSI deliver positive shutoff in buried potable water mains. Municipal utilities across the Great Lakes region are replacing century-old inventories through IIJA-funded programs, compressing procurement timelines against foundry capacity constraints.
- Butterfly Valves:Compact disc-and-liner configurations minimize vault footprints and torque requirements for large-diameter transmission lines. Texas and Florida utilities specify these for rapid urbanization projects where excavation costs dominate installed economics.
- Globe Valves:Throttling precision suits treatment plant process control loops with frequent modulation cycles.
- Check Valves:Swing and silent configurations prevent backflow in pump station discharge headers.
Gate valves command the established base. The steepest expansion runs through butterfly valve specifications.
End User:
Customer type determines certification thresholds, contract structures, and maintenance protocol sophistication.
- Municipal:Utilities operating under EPA Lead and Copper Rule compliance face accelerated replacement schedules for lead service line adjacent infrastructure. AWWA C500 certification and NSF/ANSI 61 drinking water contact approval are mandatory for federal grant eligibility.
- Industrial:Power generation and chemical processing facilities specify corrosion-resistant alloys for high-cycle process isolation. Flowserve and Emerson anchor this segment through specialized metallurgy and automation integration capabilities.
- Residential:Single-family and multi-unit developments drive demand for compact brass and PVC service line valves.
- Irrigation:Agricultural and golf course applications prioritize cost-efficient manual actuation in non-potable distribution.
Municipal procurement dominates volume concentration. Industrial retrofit cycles are expanding most quickly.
Material:
Corrosion resistance, pressure rating, and unit economics trade off across substrate selection for buried and exposed service.
- Cast Iron:Ductile iron bodies with epoxy coatings satisfy AWWA standards for buried water mains at lowest unit cost. Domestic foundry capacity concentrates in Great Lakes region suppliers, creating procurement queue risks for large-diameter orders.
- Stainless Steel:316L and super-duplex grades penetrate coastal Florida and Gulf Coast applications where chloride-induced corrosion degrades standard cast iron. Desalination and brackish water treatment facilities justify premium unit costs through extended replacement cycles.
- PVC:Thermoplastic construction eliminates corrosion concerns in corrosive soil conditions and electrical interference zones.
- Brass:Lead-free alloys meet NSF/ANSI 61 requirements for residential service line and fixture connections.
Cast iron retains the volume base. Stainless steel specifications are gaining share fastest.
Actuation Type:
Control architecture sophistication separates manual heritage installations from networked smart infrastructure deployments.
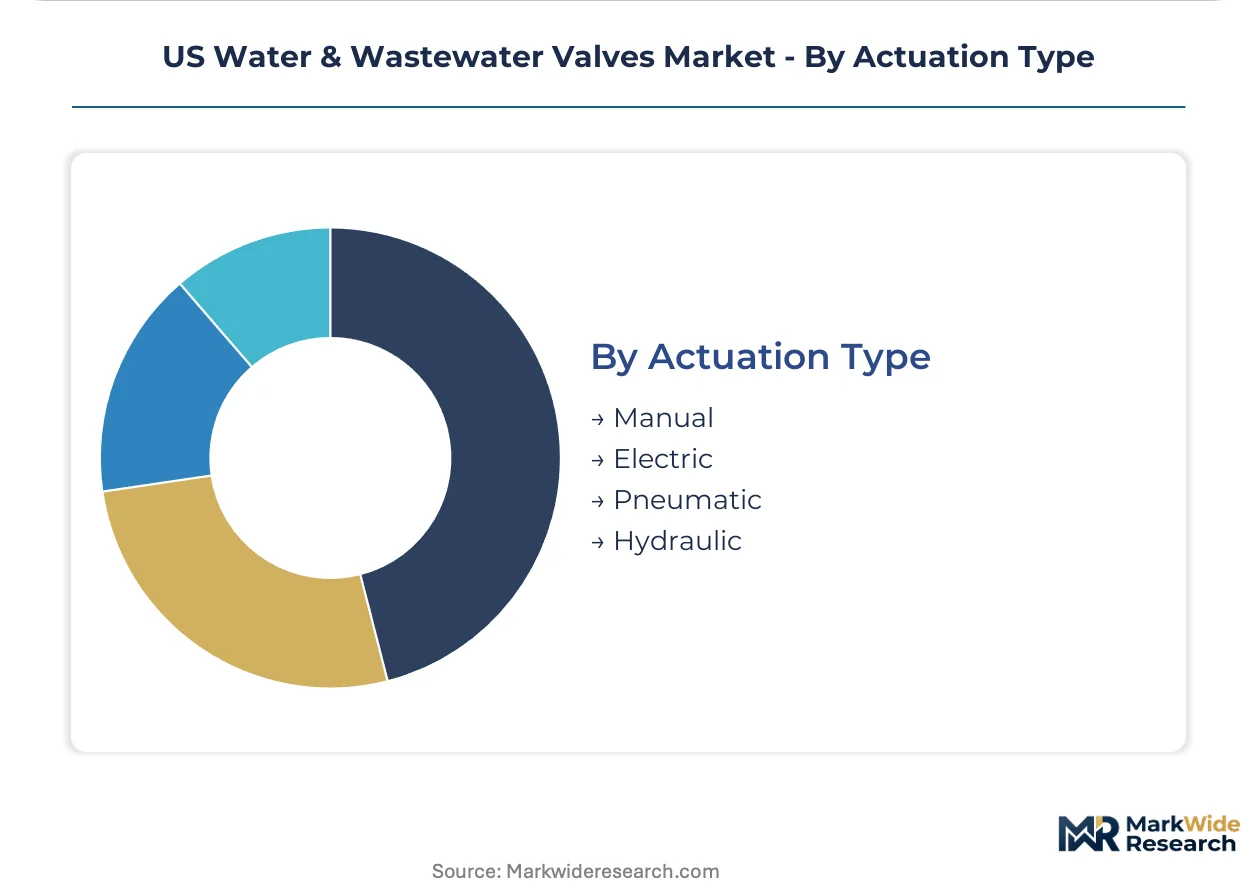
- Manual:Handwheel and nut operators dominate legacy vault installations where SCADA retrofit costs exceed replacement economics. Legacy system integration friction inflates installed costs for 1950s-era infrastructure.
- Electric:Motorized actuators with position feedback enable remote monitoring and pressure management optimization. Mueller Water Products and Emerson Electric capture specification pull through SCADA-compatible packages.
- Pneumatic:Compressed air systems serve industrial process control with rapid cycle requirements.
- Hydraulic:High-force applications in large-diameter isolation and emergency shutdown systems.
Manual actuation holds the installed base. Electric migration is accelerating most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes-St. Lawrence Seaway system anchors North American valve procurement, with the Illinois Waterway and Mississippi River tributaries underwriting distribution logistics for heavy cast iron shipments to interior utilities.
Great Lakes Region
Michigan, Ohio, and Wisconsin utilities operate century-old gate valve inventories requiring wholesale replacement. EPA Lead and Copper Rule enforcement is compressing procurement timelines against domestic foundry capacity. The Milwaukee-Chicago manufacturing corridor concentrates ductile iron casting operations serving municipal rehabilitation programs.
Texas Triangle
Houston, Dallas-Fort Worth, and San Antonio water authorities face distribution network strain from 2.5 million annual population inflows. IIJA infrastructure grants are unlocking valve capacity expansion projects synchronized with street excavation coordination. The Gulf Coast petrochemical complex generates parallel industrial demand for corrosion-resistant alloy specifications.
Florida Peninsula
Miami-Dade and Tampa Bay utilities confront chloride-induced corrosion accelerating cast iron degradation cycles. State revolving fund administrators impose Buy America compliance layering atop federal requirements. The Orlando-Kissimmee corridor is front-loading butterfly valve specifications for rapid urbanization projects.
California Coast
Los Angeles and San Francisco Bay Area water districts specify NSF/ANSI 61 certified components for Colorado River sourcing facilities. Southern California Water Committee consolidated procurement is displacing individual municipal bidding through master supply agreements. The Central Valley irrigation districts drive secondary demand for cost-efficient manual actuation.
Northeast Corridor
New York and Philadelphia legacy systems require electric actuation retrofits into 1950s-era valve vaults with custom adapter kits. State revolving fund administrators layer stricter domestic content thresholds than federal baselines. The Boston metropolitan water authority is synchronizing lead service line replacement with adjacent valve infrastructure.
US Water & Wastewater Valves Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and casting. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with automation integration capabilities, dedicated water infrastructure fabricators with municipal procurement channel dominance, and specialized corrosion-resistant alloy foundries serving coastal applications. Competitive dynamics center on foundry capacity expansion to match IIJA disbursement velocity and electric actuation technology licensing for SCADA-compatible retrofit packages.
Among US-based industrial conglomerates, Emerson Electric Co. and Flowserve Corporation occupy positions spanning automation integration and heavy industrial specifications. Mueller Water Products, Inc. exemplifies the municipal-focused archetype through extensive distributor network penetration. These three anchors illustrate how competitive positioning diverges between system-level platform provision and component-tier foundry specialization.
| Leading Market Players |
|---|
| AMERICAN Cast Iron Pipe Company |
| American Valve Inc. |
| Ari Valve Corporation |
| Emerson Electric Co. |
| Flowserve Corporation |
| Crane Holdings |
| Baker Hughes Company |
| Schlumberger Limited |
| Mueller Water Products, Inc. |
| Others |
Pricing and Supply Chain Analysis
The Illinois Waterway and Mississippi River freight corridors carry heavy ductile iron castings from Great Lakes foundries to Texas and Florida utilities at rates that compress margins for smaller fabricators while enabling volume-tier discounts for consolidated procurement alliances. This logistics cost dynamic concentrates pricing power among distributors with captive barge contracts and multi-state municipal relationships.
Pricing Analysis
Volume-discount tiering separates master supply agreement holders from spot purchasers in municipal procurement. Pricing stratifies across NSF/ANSI 61 certified premium grades, standard AWWA C500 compliant mid-tiers, and economy cast iron for non-potable irrigation. Cost compression in standard grades intensifies as California and New York utilities layer Buy America compliance atop federal thresholds. Residential service line contractors exhibit highest price sensitivity; coastal desalination facilities show lowest.
Supply Chain Analysis
Scrap steel and pig iron feedstock costs hinge on Great Lakes region foundry capacity concentrated in Wisconsin, Ohio, and Michigan. Ductile iron casting, electric actuator assemblies, and polymer seal compounds constitute critical component inputs. Single-source vulnerability runs through qualified domestic iron casting capacity for large-diameter valve bodies. Distribution runs through regional water authority cooperatives and specialized municipal distributors rather than direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Lead and Copper Rule enforcement is compressing replacement timelines into a narrow procurement window, creating high-growth disruption for suppliers with certified domestic capacity and electric actuation integration capabilities.
For Market Incumbents: Insulate municipal channel relationships through captive foundry capacity expansion in the Milwaukee-Chicago corridor and accelerated NSF/ANSI 61 certification for legacy product lines. Threat from consolidated procurement alliances demands volume-tier pricing flexibility and SCADA-compatible retrofit packages for 1950s-era vault infrastructure. For New Entrants and Emerging Players: Build out stainless steel fabrication capabilities for chloride-resistant coastal applications in Florida and Gulf Coast markets where super-duplex grades command premium positioning. The most penetrable white space sits in electric actuation adapter kits for manual valve retrofits, with go-to-market through specialized waterworks distributors serving mid-size utilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming water infrastructure divisions lacking IIJA grant eligibility certification. Long-term viability centers on domestic foundry assets with qualified supplier status and electric actuation technology licensing. Watch EPA disbursement velocity against foundry backlog queues as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Captures IIJA-funded municipal procurement wave across Great Lakes rehabilitation programs. |
| Electric Actuation Licensing | Enables SCADA integration for remote monitoring architectures displacing manual operators. |
| NSF/ANSI 61 Certification Investment | Unlocks federal grant eligibility for drinking water contact specifications. |
| Regional Cooperative Partnership | Secures volume-tier pricing through Southern California Water Committee master agreements. |
| Stainless Steel Grade Expansion | Penetrates coastal desalination and brackish water applications with chloride-resistant alloys. |
Research Methodology
Desk research of AWWA technical standards, EPA regulatory filings, and state revolving fund disbursement records preceded structured interviews with municipal water utility procurement directors, foundry operations managers, and electric actuator integration specialists. Primary fieldwork with distributor network heads and IIJA grant administrators combined with secondary validation against customs data for ductile iron imports and SEC disclosures from publicly traded valve manufacturers. Bottom-up unit economics triangulated against top-down infrastructure spending forecasts.
Assumptions held IIJA disbursement timelines, foundry capacity expansion rates, and EPA enforcement intensity as fixed parameters while varying electric actuation adoption curves and stainless steel penetration rates across coastal geographies. Segmentation modeling spanned product type, material grade, actuation architecture, and end-user procurement channel. CAGRs derived from utility capital expenditure surveys and replacement cycle analysis. Forecast inputs incorporated lead service line replacement schedules and chloride-induced corrosion degradation rates.
Practitioners should monitor foundry backlog queues, state Buy America compliance layering, and electric actuator component lead times for early signals of procurement constraint or pricing inflection. Forecasts reflect these documented assumptions and risk factors including tariff exposure on specialty alloys and qualified supplier list revisions. Cross-checking against EPA state revolving fund disbursement dashboards and AWWA utility capital spending surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Gate Impellers Market
Valves
Aerospace Valves Market
Valves
Lined Valves Market
Valves
Pressure Control Equipment Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
Steam Trap Market
Valves
Explosion Proof Solenoid Valves Market
Valves
Oil Drain Valves Market
Valves
Curb Valves Market
Valves
Total Containment Vessels Market
Valves
Actuators and Valves Market
Valves
United States Valves Market
Valves
Air Vent Heads Market
Valves
Global Check Valve Market
Valves
China Explosion-Proof Equipment Market