
 Europe Medium Voltage Switchgear Market | 2026-2036
Europe Medium Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medium Voltage Switchgear Market Insights
Utility procurement consolidation across Central Europe is rebalancing supplier relationships toward integrated solution providers. ABB Ltd. leverages its installed base across Nordic transmission networks to sustain long-term service contracts. Siemens AG anchors German manufacturing scale while Hitachi Energy competes on digital switchgear integration with utility asset-management platforms.
Europe medium voltage switchgear encompasses electrical apparatus rated between 1 kV and 52 kV designed to interrupt fault currents, isolate circuits, and protect distribution infrastructure through vacuum or SF6 interruption mechanisms. These assemblies serve primary functions in grid substations, industrial power distribution, and renewable energy interconnection points where arc containment and operational reliability are critical. Air insulated switchgear occupies the mature volume tier across established European utilities with standardized footprint requirements, while gas insulated switchgear retains premium positioning in dense urban substations where land scarcity commands compact designs. Digital switchgear within smart grids deployments is capturing accelerated investment as remote monitoring and predictive diagnostics reduce outage duration and operational expenditure for network operators.
EU Green Deal carbon-neutrality mandates, REACH chemical restrictions on SF6 handling, and CE marking under the EU AI Act for grid-automation systems collectively reshape product-design priorities and compliance costs for manufacturers accessing European markets. ECHA oversight of fluorinated gas phase-down timelines is forcing accelerated R&D into vacuum-interruption and solid-insulation alternatives before regulatory prohibitions tighten. Stakeholders must monitor F-Gas Regulation revision trajectories and national implementation variances to align product-portfolio transitions with enforcement calendars and utility tender specifications.
Market Dynamics
SF6 phase-down mandates under the EU F-Gas Regulation are compressing product-development cycles and forcing manufacturers to redesign insulation architectures around vacuum interruption and solid-dielectric alternatives.
Growth Catalysts
- Offshore wind interconnection:German and Danish North Sea wind farms require specialized switchgear for subsea cable landing points and grid integration hubs.
- EU Green Deal electrification targets:Industrial heat pumps and EV charging infrastructure are expanding distribution network capacity requirements across France and Spain.
- Data center load clustering:Hyperscale facilities in Frankfurt and Amsterdam are driving utility-scale substation upgrades with redundant medium voltage feeds.
Market Restraints
- Copper and aluminum price volatility:Busbar and conductor material costs fluctuate with commodity markets, compressing margin visibility on long-delivery contracts.
- SF6 gas handling certification scarcity:Qualified technicians for legacy gas-insulated equipment maintenance are concentrating in Germany and Austria.
- REACH compliance cost escalation:Extended producer responsibility for fluorinated gas containment is adding documentation and end-of-life recovery burdens.
Strategic Opportunities
- Polish grid modernization:EU cohesion funds are financing distribution automation retrofits in secondary cities and industrial zones.
- Digital twin convergence:Switchgear-embedded sensors fused with utility SCADA platforms enable predictive maintenance revenue streams.
- CE marking under EU AI Act:Autonomous fault-detection algorithms in smart switchgear create first-mover certification advantages for integrated solution providers.
Industry Challenges
- Vacuum interrupter engineering talent scarcity:Specialized arc physics and ceramic metallization expertise is retiring faster than training pipelines replenish.
- Legacy SF6 asset stranded value:Utilities face write-down pressure on installed gas-insulated bases before regulatory prohibitions tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medium Voltage Switchgear Market |
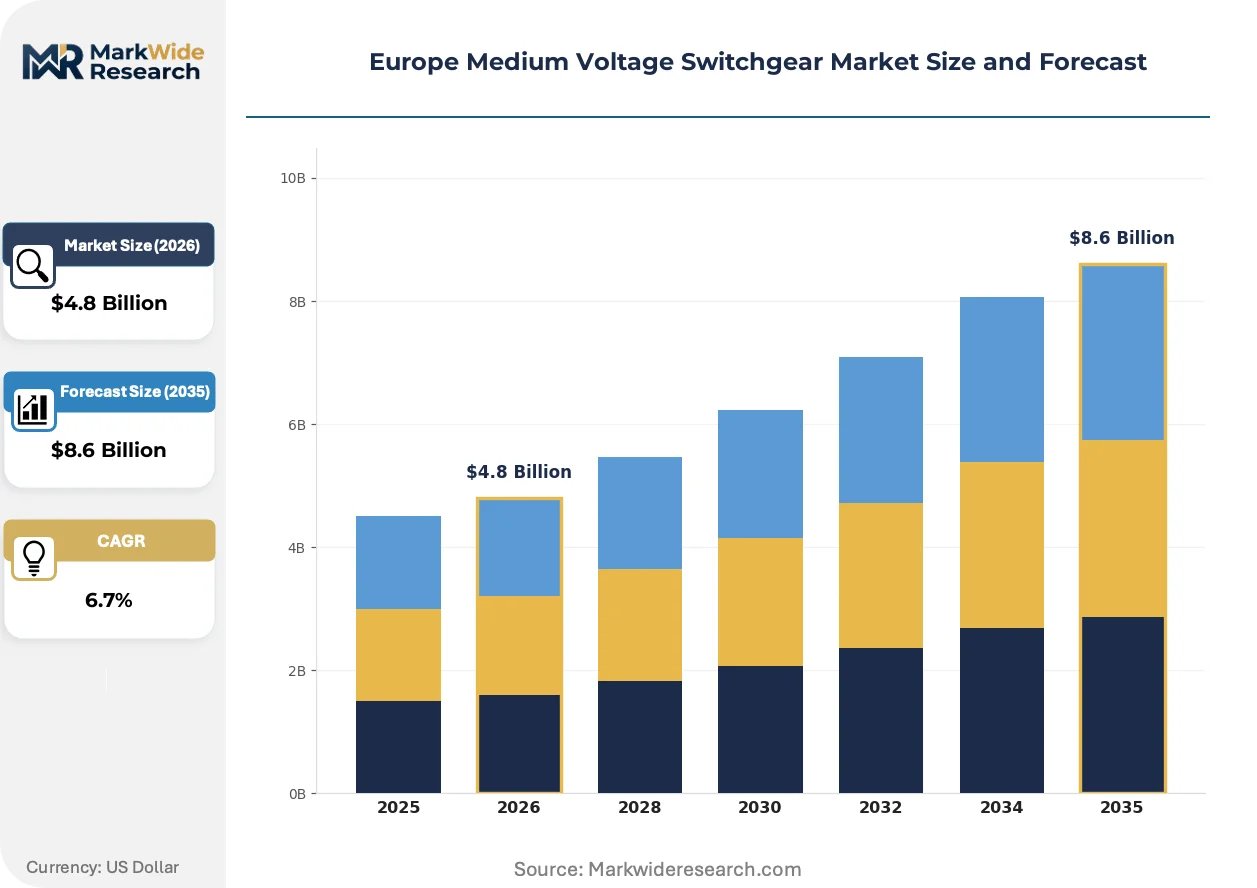
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Insulated Switchgear, Gas Insulated Switchgear, Hybrid Switchgear, Compact Switchgear Technology: Digital Switchgear, Smart Grids, Conventional Switchgear, Modular Solutions End User: Utilities, Industrial Sector, Commercial Sector, Renewable Energy Installation Type: Indoor Installations, Outdoor Installations, Compact Installations, Retrofitting Services |
| Companies Covered | Eaton Corporation, Fuji Electric Co., Ltd., ABB Ltd., Toshiba Corporation, Hitachi Energy, Siemens AG, Mitsubishi Electric Corporation, Ormazabal, Schneider Electric, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medium Voltage Switchgear Market Trends and Innovations
Product architecture and procurement logic are diverging sharply as environmental compliance deadlines compress development timelines and digital capabilities become tender prerequisites rather than options.
Dry-air insulation systems are rewriting the competitive landscape for urban substation applications. These solid-dielectric designs eliminate gas handling entirely while maintaining compact footprints for dense European city centers. Municipal utilities in Stockholm and Copenhagen are specifying air-insulated switchgear for all new secondary substations. The technology is rewriting supplier qualification criteria as incumbents with vacuum-interruption heritage gain advantage over SF6-dependent portfolios.
The EU F-Gas Regulation revision is mandating accelerated SF6 phase-down timelines with quantitative reduction targets through 2030. Equipment manufacturers must now certify leak rates below 0.1% annually and establish take-back programs for end-of-life gas recovery. German transmission operators are responding by front-loading procurement of alternative insulation technologies ahead of anticipated supply bottlenecks.
Performance-based service agreements are displacing traditional equipment-plus-maintenance contracts across Nordic utilities. Network operators in Norway and Finland now compensate switchgear providers on availability metrics and outage reduction rather than unit sales. This restructuring concentrates purchasing power with integrated solution providers capable of remote diagnostics and predictive intervention.
Europe Medium Voltage Switchgear Market Segmentation
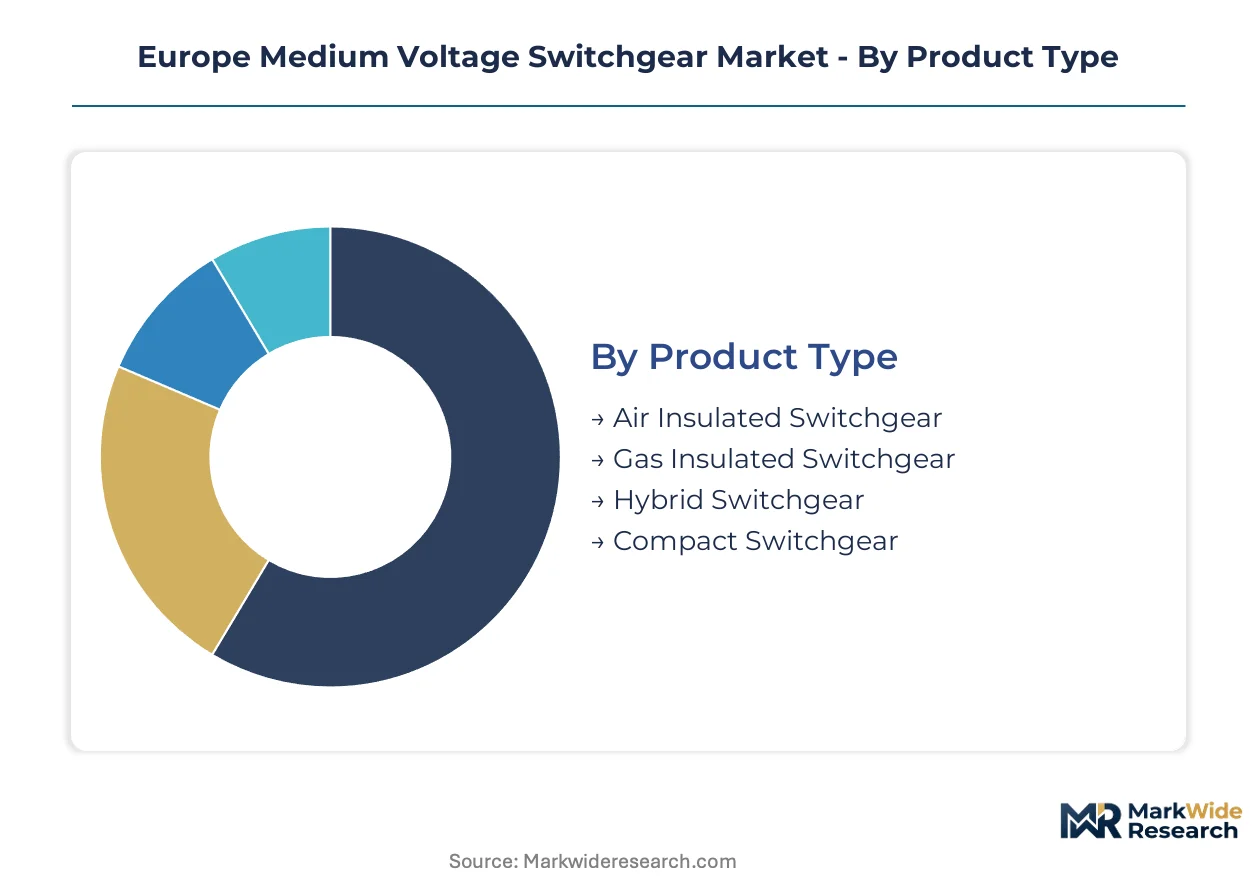
Medium voltage switchgear segmentation reveals how capital deployment, regulatory pressure, and grid modernization priorities fragment procurement patterns across European utilities and industrial buyers. Each dimension carries distinct margin profiles and vendor qualification thresholds.
Product Type:
Capital intensity varies sharply across insulation architectures, with gas-based systems demanding specialized manufacturing infrastructure and air-insulated designs spreading engineering costs across standardized platforms.
- Air Insulated Switchgear:Open-frame designs using ambient air as the primary dielectric medium with visible conductor arrangements. German municipal utilities in the Ruhr industrial belt specify these systems for secondary substations where maintenance access and lifecycle cost transparency outweigh footprint constraints.
- Gas Insulated Switchgear:Sealed pressure vessels containing SF6 or alternative fluorinated gases achieve dielectric strength at dramatically reduced physical scale. Dense urban substations in Paris and Milan command premium positioning for these compact assemblies despite escalating regulatory compliance burdens under ECHA phase-down mandates.
- Hybrid Switchgear:Combines air-insulated busbars with gas-insulated interrupting chambers to balance footprint reduction against gas containment complexity.
- Compact Switchgear:Factory-assembled modular units minimize on-site civil works and commissioning duration for distributed generation interconnection points.
Air Insulated Switchgear absorbs the bulk of installed capacity; Hybrid Switchgear is expanding most quickly as utilities hedge regulatory transition risk.
Technology:
Customer procurement criteria now bifurcate between asset-management integration capabilities and proven reliability in conventional electromechanical designs.
- Digital Switchgear:Embedded sensors, edge computing modules, and standardized communication protocols enable real-time condition monitoring and autonomous fault localization. Norwegian distribution network operators now mandate IEC 61850 compliance for all new secondary substation tenders, locking in remote diagnostics as a baseline requirement.
- Smart Grids:Grid-edge intelligence platforms coordinate switchgear operation with distributed energy resources, demand response signals, and voltage optimization algorithms. Spanish distribution utilities deploy these systems in solar-rich regions where bidirectional power flows strain conventional protection coordination.
- Conventional Switchgear:Electromechanical protection relays and manual operating mechanisms persist in cost-sensitive replacement cycles and developing market extensions.
- Modular Solutions:Skid-mounted or containerized assemblies accelerate deployment for temporary load centers and rapid industrial expansion projects.
Conventional Switchgear retains the largest installed base; Digital Switchgear is climbing the fastest as CE marking under the EU AI Act creates certification moats for early movers.
End User:
Volume concentration and margin structure diverge between regulated infrastructure operators and industrial buyers with captive reliability requirements.
- Utilities:Transmission and distribution network operators dominate procurement volume through framework agreements and multi-year capital programs. Polish distribution system operators channel EU cohesion funds into automation retrofits across secondary cities and rural industrial zones.
- Industrial Sector:Process industries, manufacturing clusters, and mining operations specify switchgear for internal power distribution with arc-flash containment and selective coordination priorities. Chemical complexes in the Port of Rotterdam demand explosion-proof enclosures and integrated motor control centers.
- Commercial Sector:Data centers, hospitals, and large retail complexes require redundant medium voltage feeds with transfer switching and power quality monitoring.
- Renewable Energy:Wind and solar project developers procure collector substation equipment for generation aggregation and grid code compliance.
Utilities absorb the bulk of installed capacity; Renewable Energy is gaining share fastest as offshore wind buildout accelerates in the German and Danish North Sea zones.
Installation Type:
Project delivery models and vendor risk allocation shift between greenfield civil works and brownfield asset replacement scenarios.
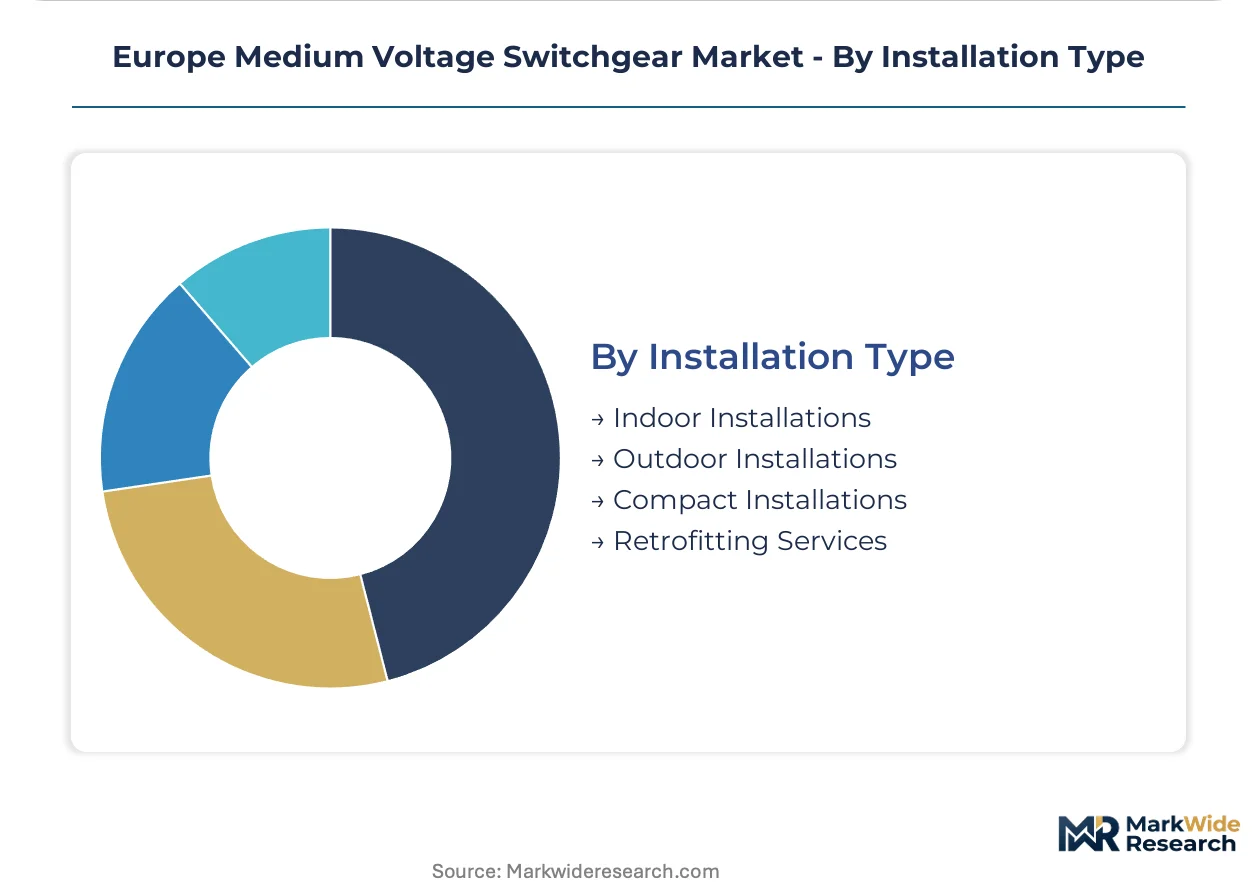
- Indoor Installations:Climate-controlled switchgear rooms in dedicated substation buildings protect equipment from environmental exposure and enable personnel access for maintenance. Amsterdam data center clusters drive demand for indoor redundant feeds with fire suppression integration.
- Outdoor Installations:Weatherproof enclosures and elevated platforms accommodate rural distribution networks and transmission substation extensions where land availability permits spatial expansion.
- Compact Installations:Pad-mounted or underground vault configurations minimize visual impact in urban environments and historical districts with aesthetic constraints.
- Retrofitting Services:Life extension programs replace obsolete interrupting mechanisms and protection systems while preserving civil infrastructure and cable terminations.
Indoor Installations absorb the bulk of installed capacity; Retrofitting Services is expanding most quickly as utilities face stranded asset pressure on legacy SF6-insulated bases before regulatory prohibitions tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities command the largest procurement volumes as offshore wind buildout and industrial electrification converge. French and Spanish grid operators follow with renewable interconnection mandates. Nordic markets pioneer performance-based service models. Polish distribution networks absorb EU cohesion funds for automation retrofits.
Germany
North Sea offshore wind farms and Ruhr industrial corridor electrification drive switchgear procurement at scale. The EU F-Gas Regulation accelerates SF6 phase-down timelines, forcing utilities to front-load alternative insulation purchases. Frankfurt data center clusters demand redundant medium voltage feeds with fire suppression integration.
France
Industrial heat pump deployment and EV charging infrastructure expand distribution network capacity requirements. ECHA oversight of fluorinated gas handling tightens leak-rate certification standards below 0.1% annually. Paris dense urban substations command premium positioning for compact gas-insulated designs despite regulatory burdens.
Spain
Solar-rich regions strain conventional protection coordination with bidirectional power flows from distributed generation. CE marking under the EU AI Act creates certification moats for smart grid automation vendors. Barcelona and Madrid utilities specify digital switchgear with IEC 61850 compliance as baseline tender requirements.
Poland
EU cohesion funds finance distribution automation retrofits across secondary cities and rural industrial zones. REACH extended producer responsibility adds documentation burdens for fluorinated gas containment. Silesian mining complexes and Łódź manufacturing belts specify arc-flash containment and selective coordination priorities.
Denmark
North Sea wind interconnection hubs require specialized switchgear for subsea cable landing points. Norwegian and Finnish performance-based service agreements displace traditional equipment-plus-maintenance contracts. Copenhagen municipal utilities specify air-insulated switchgear for all new secondary substations, eliminating gas handling entirely.
Europe Medium Voltage Switchgear Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital integration and alternative insulation architectures. The supplier base concentrates around integrated solution providers with long-term service contract capabilities. Three archetypes dominate: legacy electromechanical specialists, vacuum-interruption technology leaders, and digital-native platform vendors. Competitive moves center on portfolio diversification into predictive maintenance services and backward integration into vacuum interrupter manufacturing.
Among diversified industrial conglomerates, ABB Ltd. and Siemens AG occupy positions as archetype anchors for integrated solution provision. Hitachi Energy exemplifies the digital convergence tier with smart grid platform integration. Schneider Electric and Eaton Corporation represent the global-scale diversified tier with broad electrical infrastructure portfolios. Ormazabal anchors the regional specialist position with focused European manufacturing presence.
| Leading Market Players |
|---|
| Eaton Corporation |
| Fuji Electric Co., Ltd. |
| ABB Ltd. |
| Toshiba Corporation |
| Hitachi Energy |
| Siemens AG |
| Mitsubishi Electric Corporation |
| Ormazabal |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap German manufacturers anchor production capacity across Bavaria and Baden-Württemberg, concentrating supply discipline and sustaining premium pricing tiers for vacuum-interruption assemblies. Their long-tenured relationships with municipal utilities and transmission operators create pricing power that resists commodity-driven erosion.
Pricing Analysis
Volume concentrates in standardized air-insulated switchgear for secondary substations, while margins accrue to digital switchgear with IEC 61850 compliance and predictive diagnostics. Price differentiation rests on certification tier — CE marking under the EU AI Act commands premium positioning — and after-sales service bundling. Cost compression in copper and aluminum busbar materials is intensifying because commodity volatility compresses margin visibility on long-delivery framework agreements. Industrial buyers in chemical and mining sectors exhibit lowest price sensitivity due to arc-flash containment requirements; commercial data center developers show highest sensitivity as they optimize capex per megawatt.
Supply Chain Analysis
Regional distribution centers in Germany, Poland, and the Netherlands operate hub-and-spoke patterns feeding utility procurement across Central and Northern Europe. Manufacturing concentrates in Germany, Switzerland, and Spain, with vacuum interrupter ceramic metallization drawing from specialized Austrian and Czech suppliers. Supply chain risk centers on single-source vulnerability for SF6 gas handling certification, as qualified technicians concentrate in Germany and Austria. Distribution runs through direct OEM-to-utility channels for large transmission projects, with electrical distributors serving retrofit and commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as dry-air and solid-dielectric architectures displace SF6-insulated legacy equipment. Vacuum interruption with digital monitoring is replacing gas-based systems.
For Market Incumbents: Lock in long-term service contracts with Nordic utilities before performance-based availability agreements become standard tender requirements. SF6 phase-down mandates under the EU F-Gas Regulation threaten stranded value on installed gas-insulated bases; accelerate backward integration into vacuum interrupter manufacturing to secure ceramic metallization supply. Prioritize CE marking under the EU AI Act for autonomous fault-detection algorithms to build certification moats. For New Entrants and Emerging Players: Polish distribution system operators channeling EU cohesion funds represent an underserved buyer archetype with automation retrofit budgets and limited incumbent lock-in. Secondary cities and rural industrial zones in Silesia and Łódź offer white-space penetration with less competition from integrated solution providers. Target digital switchgear with IEC 61850 compliance as baseline specification, competing on deployment speed rather than installed base heritage. For Investors and Strategic Acquirers: Distressed-cycle entries favor vacuum-interruption technology specialists with captive ceramic metallization capabilities in Central European manufacturing corridors. Long-term viability hinges on portfolio positioning ahead of regulatory prohibitions tightening, with five-to-ten year windows favoring air-insulated and solid-dielectric alternatives over gas-dependent legacy assets. Watch ECHA F-Gas Regulation revision trajectories as the inflection signal for accelerated utility procurement front-loading.| Strategic Initiative | Industry Significance |
|---|---|
| SF6 Alternative Technology Licensing | Accelerates vacuum-interruption and solid-dielectric adoption ahead of ECHA phase-down deadlines. |
| Digital Twin Platform Integration | Fuses switchgear-embedded sensors with utility SCADA for predictive maintenance revenue streams. |
| EU AI Act CE Marking Pathway | Creates certification moats for autonomous fault-detection algorithms in smart grid deployments. |
| Backward Integration into Vacuum Interrupters | Secures captive supply of ceramic metallization components against engineering talent scarcity. |
| Performance-Based Service Agreement Expansion | Restructures Nordic utility relationships around availability metrics rather than unit sales. |
Research Methodology
Document review covered ECHA regulatory filings, EU F-Gas Regulation impact assessments, and utility tender specifications across Germany, France, and Spain, complemented by interviews with transmission network planners, distribution system operators, and switchgear procurement managers at industrial complexes. Secondary validation drew from IEC standards documentation, CE marking directives under the EU AI Act, and trade association technical bulletins. Bottom-up project pipelines and top-down macroeconomic indicators were triangulated to cross-check volume assumptions.
Historical capacity deployment patterns were cross-referenced against panel input from utility capital planning officers and EPC contractors to anchor growth trajectories across the projection horizon. Segmentation modeling incorporated insulation architecture, digital integration tier, end-user category, and installation type dimensions. CAGRs were derived from weighted scenario analysis across regulatory enforcement calendars and renewable interconnection buildout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA phase-down timeline acceleration and commodity price volatility in copper and aluminum. Forecasts reflect documented assumptions about regulatory enforcement calendars and utility procurement front-loading behavior. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Flanges Market
Valves
Pneumatic Positioner Market
Valves
Pipeline Pigging Equipment Market
Valves
Rupture Discs Market
Valves
Servo Valves Market
Valves
Hybrid Valve Market
Valves
Emergency Shutdown Valves Market
Valves
Mechanical Shaft Seal Market
Valves
Vacuum Insulated Pipe Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
Middle East and Africa Machined Seals Market
Valves
Butterfly Valves Market
Valves
APAC Valves Market
Valves
Mobile Hydraulic Valves Market
Valves
Static Seals Market
Valves
Global Plug Valve Market