
 Japan LNG Bunkering Market | 2026-2036
Japan LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
Japan LNG Bunkering Market Foresight
Long-term fuel supply contracts is rebalancing how Japanese ports monetize LNG infrastructure investments. Nippon Yusen Kabushiki Kaisha leverages its integrated shipping and energy trading arms to secure dedicated berth access at Yokohama and Nagoya. Chubu Electric Power Co., Inc. anchors its position through captive LNG terminal capacity at Chita and Kawagoe. Kawasaki Heavy Industries, Ltd. specializes in cryogenic pump and bunker vessel engineering for domestic shipyards.
Japan LNG bunkering denotes the transfer of liquefied natural gas at minus 162 degrees Celsius from shore terminals, bunker barges, or floating storage units into marine vessel fuel tanks, replacing conventional heavy fuel oil in propulsion and auxiliary engines. Shore-to-ship infrastructure dominates current capacity along the Pacific coast, while ship-to-ship transfer is expanding for deep-sea vessels unable to dock at constrained Japanese harbors. Merchant shipping commands the largest end user volume, though cruise lines represent the fastest-growing demand pool as international operators reroute Asia-Pacific itineraries through Japanese homeports.
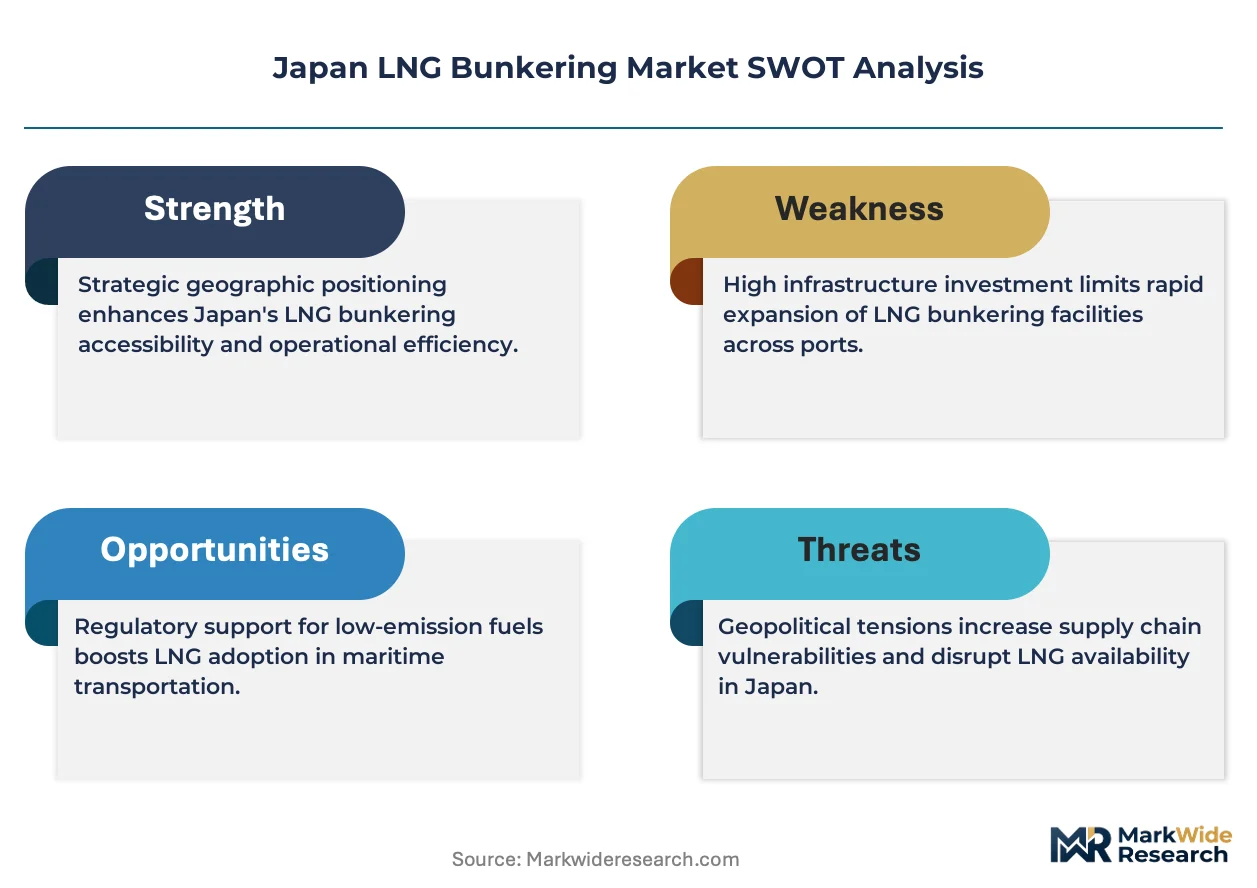
METI's port decarbonization directives, combined with IMO sulfur cap enforcement through the Japanese Ministry of Land, Infrastructure, Transport and Tourism, mandate emission reductions that only LNG and zero-carbon alternatives can satisfy. The International Maritime Organization's revised carbon intensity indicators will tighten progressively, forcing shipowners to demonstrate compliance through documented bunker fuel choices. Stakeholders must monitor hydrogen and ammonia co-firing trials at Nagoya and Kobe, as these pilots will determine whether LNG serves as a bridge fuel or faces premature displacement in Japanese maritime policy.
Market Dynamics
Dual-fuel vessel conversions at Keihin and Nagoya Bay are compressing berth availability and forcing port operators to sequence LNG infrastructure deployment around shipyard backlogs rather than demand forecasts.
Growth Catalysts
- METI Port Decarbonization Roadmap:The ministry's 2030 emission targets mandate LNG-compatible infrastructure at priority harbors, directing public capital toward cryogenic storage and bunker vessel procurement.
- IMO Sulfur Cap Enforcement:Japanese Ministry of Land, Infrastructure, Transport and Tourism inspections now document bunker fuel sulfur content, disqualifying conventional heavy fuel oil from coastal routes.
- Cruise Line Itinerary Rerouting:International operators are designating Yokohama and Kobe as homeports for Asia-Pacific circuits, creating concentrated demand spikes during seasonal turnaround windows.
Market Restraints
- Liquefaction Cost Structure:Domestic LNG procurement depends on long-term import contracts indexed to JCC pricing, exposing bunker suppliers to currency volatility against the yen.
- Berth Dimensional Constraints:Japanese harbors built for Panamax container traffic cannot accommodate Q-Max LNG carriers without dredging or offshore lightering, limiting economies of scale.
- Ammonia Co-Firing Pilots:Kobe and Nagoya hydrogen trials risk stranding LNG investments if maritime policy pivots to zero-carbon alternatives before infrastructure payback periods conclude.
Strategic Opportunities
- Ship-to-Ship Transfer Expansion:Deep-sea vessels unable to dock at constrained Japanese harbors require floating bunkering solutions, opening demand for purpose-built bunker barges.
- Chubu Electric Terminal Access:Captive regasification capacity at Chita and Kawagoe offers integrated suppliers downstream margin capture unavailable to pure-play bunker operators.
- JIS Cryogenic Equipment Certification:Standardized engineering approvals for pumps and vaporizers reduce vendor qualification timelines, accelerating domestic manufacturing scale-up.
Industry Challenges
- Cryogenic Engineering Talent Pipeline:Japanese maritime academies lack specialized curricula for minus 162 degrees Celsius fuel systems, forcing operators to recruit from Korean and Norwegian training programs.
- Bunker Vessel Capex Intensity:Each LNG bunker barge requires specialized tank geometry and reliquefaction units, with shipyard slots at Kawasaki and Imabari booked three years forward.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan LNG Bunkering Market |
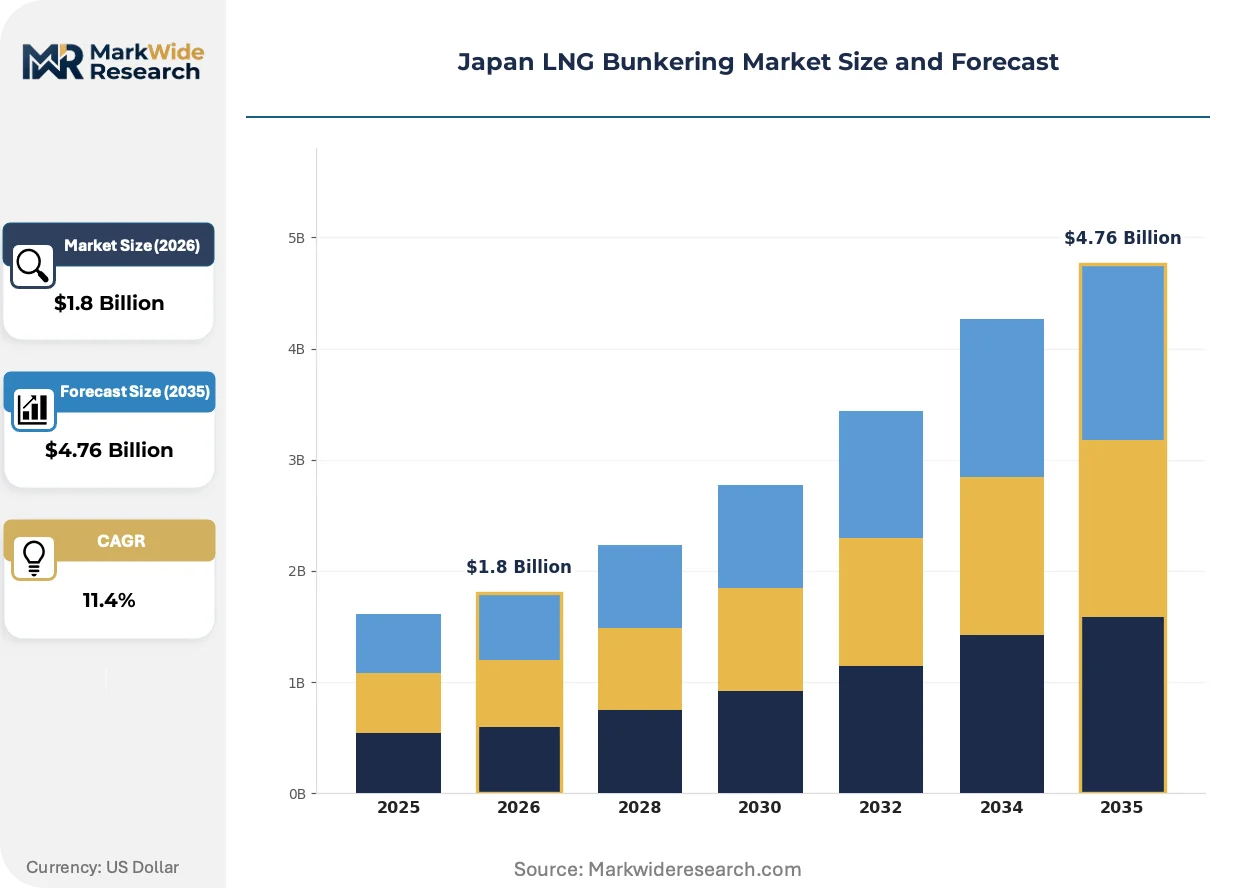
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Shipping, Terminal Operations, Offshore Support, Vessel Supply Technology: Floating Storage, Shore-to-Ship, Ship-to-Ship, LNG Fuel System End User: Merchant Shipping, Military, Fishing Vessels, Cruise Lines Distribution Channel: Direct Supply, Bunker Stations, LNG Terminals, Independent Suppliers |
| Companies Covered | Nippon Yusen Kabushiki Kaisha, Chubu Electric Power Co., Inc., Kawasaki Heavy Industries, Ltd., KEYS Bunkering West Japan Co., Ltd., Engie SA, Central LNG Marine Fuel Japan Corporation, Toyota Tsusho Corporation, Mitsubishi Shipbuilding Co., Ltd., Mitsui OSK Lines Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan LNG Bunkering Market Shifts & Advancements
Bunkering modality is bifurcating between shore-to-ship efficiency plays and ship-to-ship flexibility solutions, with technology choices locking in decade-long infrastructure commitments before fuel pathway clarity emerges.
Small-scale LNG liquefaction units are expanding into port hinterlands to reduce trucking distances from regional import terminals. Chita and Himeji operators are installing skid-mounted trains to serve coastal feeders. This distributed production model is compressing the radius of economically viable LNG bunkering beyond the Keihin industrial corridor.
METI's port decarbonization directives now require emission reduction plans as a condition of harbor operating licenses. Terminal operators must document fuel switching timelines and infrastructure investment schedules. Deep-sea shipping lines are responding by pre-booking dedicated berth windows at Yokohama and Nagoya to secure compliance documentation for IMO carbon intensity indicators.
Cruise operators are consolidating procurement through integrated fuel-service contracts rather than spot bunker purchases. International lines now require Japanese agents to bundle LNG supply with shore power connectivity and waste handling. This bundling is displacing independent bunker brokers from premium homeport rotations at Kobe and Yokohama.
Japan LNG Bunkering Market Segmentation
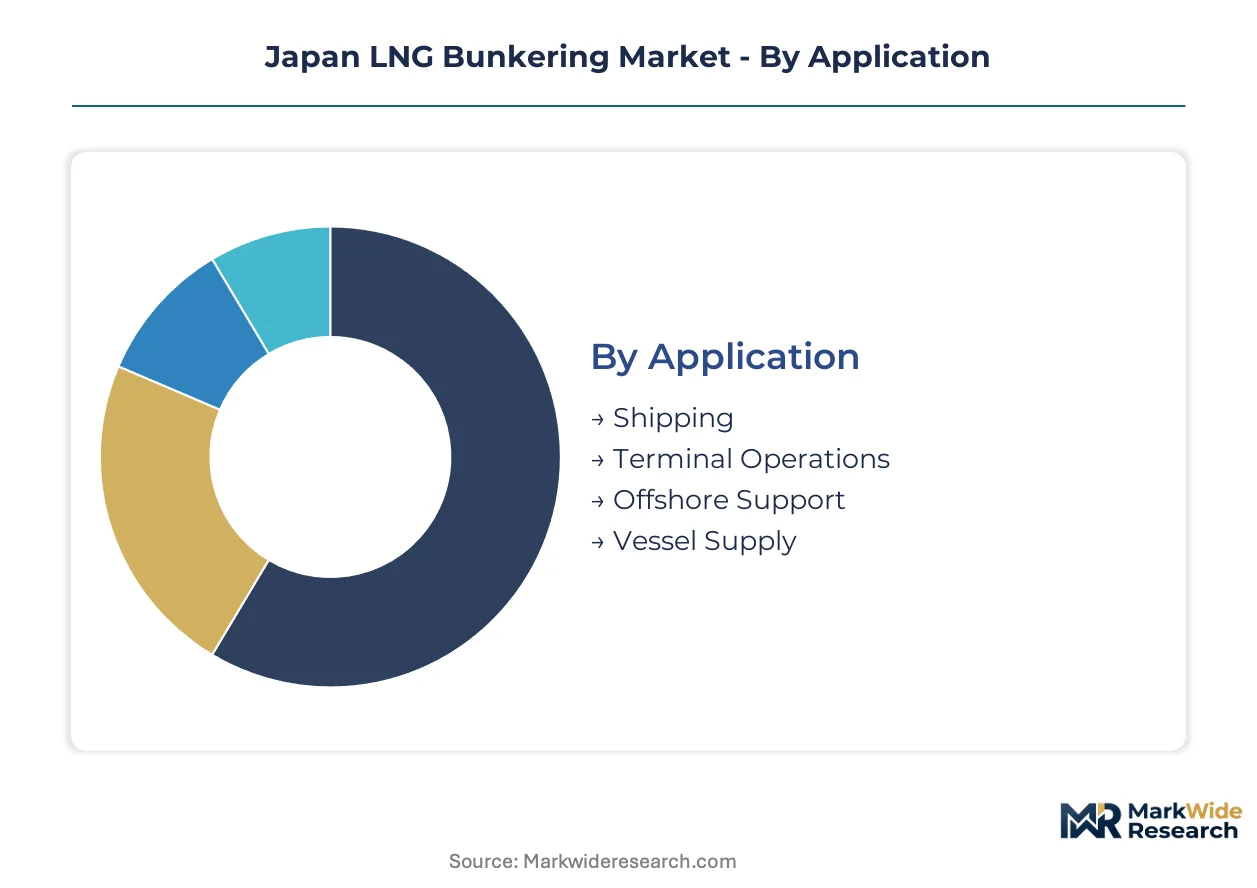
Japan LNG bunkering infrastructure investment decisions hinge on which vessel classes and transfer modalities command priority berthing windows. Port operators at Yokohama and Nagoya sequence capital deployment around segment-specific demand density and cryogenic handling requirements.
Application:
Volume concentrates in deep-sea vessel rotations, while premium margins attach to specialized offshore logistics requiring floating transfer capabilities.
- Shipping:Deep-sea container and bulk carriers dominate fuel offtake volumes at Keihin and Nagoya Bay terminals. NYK Line and MOL pre-book dedicated berth windows to secure IMO carbon intensity documentation for trans-Pacific routes.
- Terminal Operations:Port authorities monetize LNG infrastructure through throughput fees from captive regasification facilities. Chubu Electric's Chita terminal anchors this segment with integrated shore-to-ship capacity serving coastal feeders.
- Offshore Support:Supply vessels serving oil and gas platforms require ship-to-ship transfer at anchorage points outside constrained harbors.
- Vessel Supply:Coastal tug and barge operators source small-scale LNG through skid-mounted liquefaction units at Himeji and Chita.
Today's leader: Shipping. Tomorrow's challenger: Terminal Operations.
Technology:
Cost tiers separate capital-intensive floating storage from standardized shore-based systems, with hybrid configurations capturing mid-market flexibility premiums.
- Floating Storage:Offshore units enable Q-Max carrier lightering where harbor depth constraints block direct berthing. Kawasaki Heavy Industries engineers cryogenic pump systems for these floating configurations.
- Shore-to-Ship:Pipeline-connected dispensing dominates current capacity along the Pacific coast. METI's port decarbonization roadmap prioritizes this modality for emission compliance documentation at priority harbors.
- Ship-to-Ship:Bunker barges serve deep-sea vessels unable to dock at Japanese harbors. Purpose-built vessels with reliquefaction units command three-year forward shipyard slots at Imabari.
- LNG Fuel System:Onboard cryogenic tank and engine integration determines vessel retrofit economics. Dual-fuel conversions at Kawasaki and Nagoya shipyards compress berth availability.
Shore-to-Ship holds installed base dominance. Ship-to-Ship climbs the fastest as offshore transfer demand outstrips dock expansion timelines.
End User:
Customer type stratifies between high-volume contract shippers and spot-market cruise operators with opposing procurement patterns.
- Merchant Shipping:Container and bulk lines negotiate long-term fuel supply agreements bundling berth access with LNG procurement. Nippon Yusen Kabushiki Kaisha leverages integrated trading arms to secure dedicated terminal capacity.
- Cruise Lines:International operators reroute Asia-Pacific itineraries through Yokohama and Kobe homeports. Seasonal turnaround windows create concentrated demand spikes requiring bundled fuel-service contracts.
- Military:Maritime Self-Defense Force vessels source LNG through designated defense procurement channels.
- Fishing Vessels:Coastal fleet operators access small-scale LNG through regional liquefaction units at Himeji.
Merchant Shipping anchors revenue stability. Cruise Lines represent the steepest expansion trajectory as homeport designations multiply.
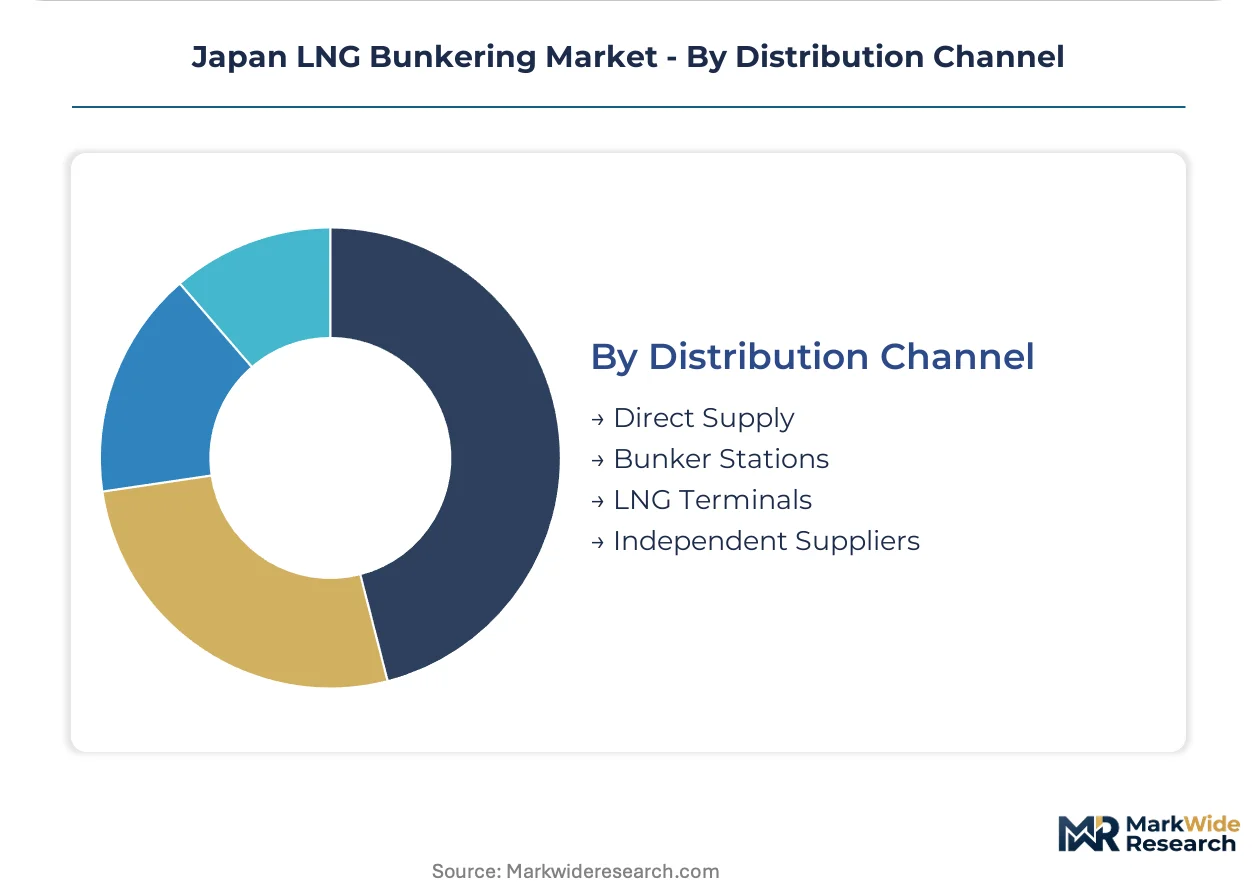
Distribution Channel:
Supply concentration favors integrated terminal operators over independent brokers, with direct relationships capturing margin downstream.
- LNG Terminals:Captive regasification capacity at Chita and Kawagoe offers integrated suppliers downstream margin capture unavailable to pure-play bunker operators.
- Direct Supply:Shipping lines contract directly with Chubu Electric and Tokyo Gas for fuel and berth coordination.
- Bunker Stations:Dedicated LNG dispensing facilities at Yokohama and Nagoya handle spot purchases from non-contracted vessels.
- Independent Suppliers:Brokerage models face displacement as cruise operators consolidate procurement through bundled fuel-service contracts.
LNG Terminals control infrastructure access. Direct Supply gains share as integrated procurement displaces spot brokerage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea outpaces Japan in ship-to-ship bunkering deployment, while Singapore maintains the largest LNG refueling throughput in Asia. European ports in Rotterdam and Hamburg set regulatory benchmarks that Japanese harbor authorities reference for METI compliance frameworks.
China
Yangtze River Delta container terminals drive coastal LNG demand for feeder vessels serving Shanghai and Ningbo. MIIT maritime decarbonization guidelines mandate dual-fuel compatibility at priority ports by 2027. Guangdong Province operators pilot ammonia co-firing at Shenzhen terminals alongside LNG infrastructure expansion.
South Korea
Busan Port Authority accelerates LNG bunkering to capture transshipment volume from Japanese competitors. MFDS maritime safety regulations align with IMO sulfur enforcement timelines. Ulsan shipyards convert dual-fuel tonnage for domestic lines, compressing regional berth availability.
Singapore
The Maritime and Port Authority licenses multiple LNG bunker suppliers to maintain hub status against emerging Northeast Asian rivals. Ship-to-ship transfer operations at anchorage points serve Q-Max vessels excluded from harbor berths. Jurong Island storage integration offers economies of scale unavailable to Japanese terminals.
Germany
Hamburg port operators deploy shore-to-ship LNG infrastructure to satisfy EU Green Deal maritime emission targets. KBA vessel certification requirements for cryogenic fuel systems influence Japanese engineering standards through ISO working groups. North Sea coastal feeders source small-scale LNG from Brunsbüttel liquefaction units.
Netherlands
Rotterdam's Gate terminal anchors European LNG bunkering with dedicated marine fuel loading facilities. REACH chemical safety protocols for cryogenic handling inform Japanese port operator training curricula. Maasvlakte expansion projects compete with Japanese harbor development for Korean and Chinese shipyard capacity.
Japan LNG Bunkering Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy traders capturing downstream margin while pure-play engineering firms dominate cryogenic equipment supply. The vendor base concentrates around three archetypes: captive terminal operators leveraging regasification assets, shipping conglomerates with integrated fuel trading arms, and specialized shipbuilders controlling bunker vessel construction slots. Consolidation pressures favor backward integration into LNG procurement over standalone bunkering service models. Strategic partnerships between terminal operators and shipyards lock in construction priority for purpose-built bunker barges.
Within the integrated energy tier, Chubu Electric Power Co., Inc. and Nippon Yusen Kabushiki Kaisha occupy positions that exemplify divergent approaches to market participation. Kawasaki Heavy Industries, Ltd. anchors the specialized engineering segment through cryogenic pump and bunker vessel design capabilities. These three entities represent the dominant competitive archetypes: captive infrastructure control, shipping-fuel vertical integration, and technical equipment supply.
| Leading Market Players |
|---|
| Nippon Yusen Kabushiki Kaisha |
| Chubu Electric Power Co., Inc. |
| Kawasaki Heavy Industries, Ltd. |
| KEYS Bunkering West Japan Co., Ltd. |
| Engie SA |
| Central LNG Marine Fuel Japan Corporation |
| Toyota Tsusho Corporation |
| Mitsubishi Shipbuilding Co., Ltd. |
| Mitsui OSK Lines Ltd. |
| Others |
Supply & Pricing Matrix
JCC-linked LNG import contracts cascade through Japanese bunker supply chains into three-tier pricing structures across premium, standard, and economy levels. Currency volatility against the yen compresses margins for independent operators lacking captive terminal capacity at Chita or Kawagoe.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for ship-to-ship transfer services across Northeast Asia. Contract-based long-term offtake dominates merchant shipping procurement, with price differentiation driven by volume scale and JIS cryogenic equipment certification tier. Cost compression in spot-market bunker purchases is intensifying because cruise operators now bundle fuel with shore power and waste handling services. Coastal feeder operators show highest price sensitivity, while deep-sea container lines pre-booking dedicated berth windows demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Chinese shipyards for specialized LNG bunker barge construction. Domestic supply chains draw from Australian LNG feedstock, Japanese cryogenic pump engineering, and Korean steel fabrication. Tariff exposure on imported reliquefaction units creates procurement risk for Imabari and Kawasaki shipyard slots. Distribution runs through captive terminal operators like Chubu Electric rather than independent brokerage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan LNG bunkering operates as a regulatory compounder where METI's 2030 port decarbonization targets mandate infrastructure deployment ahead of pure demand economics.
For Market Incumbents: Hedge ammonia co-firing displacement risk by securing hydrogen pilot participation at Nagoya and Kobe while extending LNG infrastructure payback periods through long-term cruise line bundling contracts. Backward integration into small-scale liquefaction at Himeji and Chita captures margin otherwise lost to regional import terminals. Prioritize JIS certification investment to accelerate domestic equipment procurement timelines against Korean competitors. For New Entrants and Emerging Players: Capture ship-to-ship transfer white space for deep-sea vessels excluded from constrained Japanese harbors by Q-Max dimensional limits. Target offshore support vessel segments at Keihin anchorage points where floating bunkering demand outstrips dock expansion timelines. Lead with purpose-built bunker barge construction partnerships at Imabari shipyard, securing forward slots before incumbent terminal operators lock capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with cryogenic engineering specialists possessing JIS-standardized pump and vaporizer platforms. Five-to-ten year viability hinges on whether LNG serves as bridge fuel or faces premature displacement by ammonia maritime policy. Watch Nagoya hydrogen co-firing trial outcomes as the critical inflection signal for infrastructure stranding risk versus extended demand runway.| Strategic Initiative | Industry Significance |
|---|---|
| Small-Scale Liquefaction Buildout | Skid-mounted units at Chita and Himeji compress economically viable bunkering radius beyond Keihin corridor. |
| Ship-to-Ship Transfer Fleet Expansion | Purpose-built bunker barges with reliquefaction units address Q-Max exclusion from Japanese harbor berths. |
| JIS Cryogenic Certification Program | Standardized engineering approvals reduce vendor qualification timelines for domestic pump manufacturing scale-up. |
| Integrated Fuel-Service Bundling | Cruise line contracts combining LNG, shore power, and waste handling displace independent bunker brokers at Kobe. |
| Hydrogen Co-Firing Pilot Participation | Early involvement in Nagoya and Kobe ammonia trials hedges against LNG infrastructure stranding risk. |
Research Methodology
Multiple input streams — terminal operator throughput disclosures, shipyard construction backlog tracking, and METI regulatory filing analysis — were reconciled with primary interviews across port authority planners, cryogenic equipment procurement leads, and LNG trading desk executives. Secondary validation drew from IMO sulfur enforcement documentation, JIS standards registries, and customs import data for cryogenic pump components. Bottom-up capacity modeling and top-down demand projection triangulation anchored volume estimates.
Data-stream reconciliation applied across the modeling period segmented by transfer modality, vessel class, and end-user procurement pattern. CAGRs were derived from infrastructure deployment timelines against dual-fuel fleet conversion schedules at Kawasaki and Nagoya shipyards. Forecast inputs incorporated berth availability constraints, JCC pricing volatility bands, and hydrogen pilot program progression rates.
Policy pivot toward ammonia maritime fuel, yen currency fluctuation against contract-indexed LNG imports, and shipyard slot availability compression are the dominant revision risks for infrastructure payback assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Pumpjack Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Well Test Market