
 Rising Stem Ball Valve Market | 2026-2036
Rising Stem Ball Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Rising Stem Ball Valve Market Insights
Modular valve-actuator bundling is consolidating procurement patterns across process industries. Emerson Electric Co. leverages integrated digital positioner packages to anchor premium positioning in offshore platforms. Flowserve Corporation competes through aftermarket service networks that sustain recurring revenue from installed bases. KITZ Corporation specializes in compact three-piece designs that dominate space-constrained retrofit applications across Asian refineries.
A rising stem ball valve incorporates a threaded stem extension that translates rotary ball motion into linear stem displacement, providing external visual confirmation of open or closed position without pressure boundary penetration; typical designs achieve bubble-tight shutoff per API 598 with metal-seated variants rated to 750°F. Flanged configurations command the largest installed base in hydrocarbon processing due to ANSI class pressure-temperature ratings and standardized face-to-face dimensions. Stainless steel material grades are displacing carbon steel in corrosive chemical processing environments where chloride stress cracking resistance governs specification. Oil and gas end users represent the most specification-intensive buyer segment, with fugitive emissions compliance under EPA Method 21 driving packing upgrades across existing installations.
API 6D pipeline valve standards and ISO 15848 fugitive emissions classifications shape product qualification requirements for market access across North American and European project pipelines. EPA New Source Performance Standards and the EU F-Gas Regulation are tightening leakage thresholds, forcing packing material transitions from PTFE to graphite composites. Buyers must monitor how NACE MR0175 sour service revisions and emerging hydrogen embrittlement test protocols reshape metallurgical specifications for energy transition infrastructure.
Market Dynamics
API 6D certification requirements and EPA fugitive emissions standards are compressing specification cycles across process industries, forcing buyers to retire legacy gate valve fleets ahead of planned replacement schedules.
Growth Catalysts
- EPA Method 21 compliance mandates:Fugitive emissions monitoring protocols are compelling oil and gas operators to upgrade packing systems across existing installations, creating replacement pull-through for rising stem designs with visible position indication.
- US Gulf Coast petrochemical corridor expansion:Turnaround schedules favor quarter-turn isolation valves that reduce maintenance windows and enable faster commissioning cycles.
- Graphite composite packing materials:PTFE displacement by high-temperature graphite composites extends service intervals beyond 5,000 cycles in steam and hydrocarbon applications.
Market Restraints
- Specialized foundry capacity concentration:Investment casting for ASTM A351 CF8M stainless steel bodies concentrates in select Asian supply basins, creating lead time vulnerability for North American project pipelines.
- API 6D certification timeline friction:Fire-safe testing and fugitive emissions qualification cycles extend product launch timelines by 18-24 months for new market entrants.
- Floating ball valve substitution:Lower-cost trunnion-mounted alternatives capture specification share in non-critical isolation applications where position indication is not mandatory.
Strategic Opportunities
- Hydrogen infrastructure buildout:NACE MR0175 sour service revisions and emerging hydrogen embrittlement test protocols create first-mover advantage for metallurgically qualified suppliers.
- Digital positioner convergence:Integration of HART protocol diagnostics with mechanical rising stem designs enables predictive maintenance contracts in offshore platform applications.
- EU F-Gas Regulation alignment:European leakage threshold tightening redirects specification standards toward low-emissions packing configurations that exceed baseline ISO 15848 Class BH requirements.
Industry Challenges
- Weld overlay technician scarcity:Hardfacing of Stellite 6 seats and Inconel 625 overlays requires certified welding procedures that outpace available skilled labor pools in North American fabrication shops.
- Legacy system integration complexity:Rising stem ball valves must interface with existing DCS architectures that lack native support for smart positioner feedback loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rising Stem Ball Valve Market |
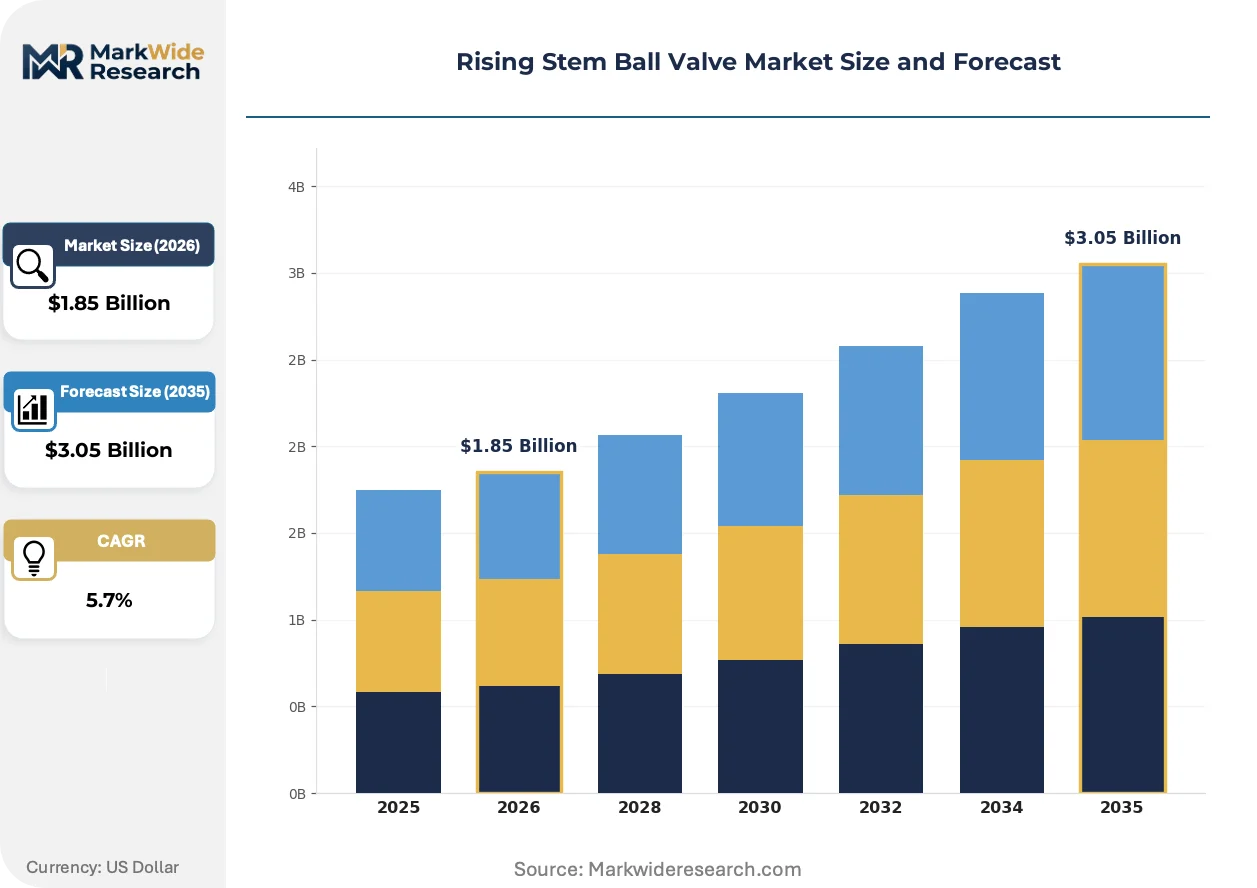
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Piece, Three-Piece, Flanged, Welded Material: Stainless Steel, Brass, Carbon Steel, PVC End User: Oil & Gas, Water Treatment, Power Generation, Chemical Processing Size: Small Diameter, Medium Diameter, Large Diameter, Extra Large Diameter |
| Companies Covered | Trillium Flow Technologies, IMI, Emerson Electric Co., Crane Company, Valmet, Flowserve Corporation, SCV Valve, KITZ Corporation, SLB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rising Stem Ball Valve Market Trends and Innovations
Material science advances and digital instrumentation integration are compressing the performance gap between mechanical reliability and predictive operational visibility across process isolation applications.
Metal-seated construction with tungsten carbide coatings is rewriting durability benchmarks for severe service applications. Refinery operators in the US Gulf Coast are specifying these variants for catalytic cracking unit slurry service where erosion resistance governs replacement cycles. The technology is compressing total cost of ownership calculations that previously favored softer seat materials with shorter lifespans.
EPA New Source Performance Standards are tightening permissible leakage thresholds for new valve installations across petrochemical facilities. The regulatory pressure is accelerating packing material transitions from conventional PTFE to graphite composite systems rated for 750°F continuous service. Oil and gas end users in Texas and Louisiana are front-loading these upgrades to avoid compliance penalties during scheduled inspections.
Integrated actuator-valve bundling is consolidating procurement patterns across engineering contractors executing lump-sum turnkey projects. EPC firms are specifying factory-assembled packages with pre-calibrated digital positioners to reduce field commissioning time and warranty exposure. This pattern is most visible in offshore platform projects where space constraints and weight limits favor pre-tested modular assemblies over site-built configurations.
Rising Stem Ball Valve Market Segmentation
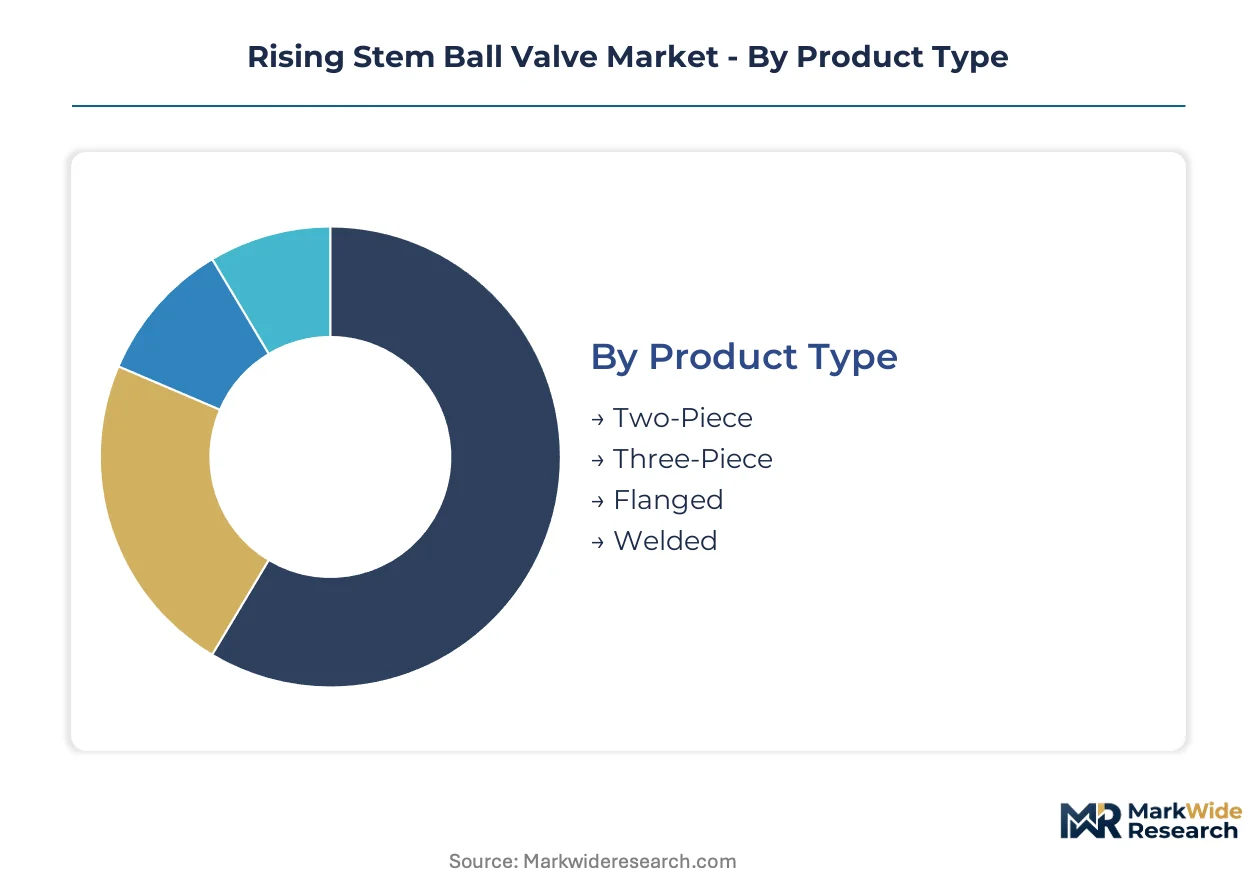
Rising stem ball valve specification patterns diverge sharply between high-volume replacement cycles and premium project-driven procurement. Understanding these segment boundaries clarifies where suppliers can anchor recurring revenue versus one-time engineering wins.
Product Type:
Volume concentrates in standardized configurations, while premium margins accrue to specialized designs requiring custom engineering.
- Flanged:ANSI class pressure-temperature ratings and standardized face-to-face dimensions dominate hydrocarbon processing procurement across Texas and Louisiana refineries. Water treatment utilities in California and Florida are expanding flanged procurement to replace aging gate valve infrastructure, driven by API 6D certification requirements and visible position indication mandates.
- Three-Piece:Compact designs with threaded or socket-weld end connections dominate space-constrained retrofit applications. Asian refineries specify these variants for catalyst regeneration skids where maintenance access is restricted and weight limits are stringent.
- Two-Piece:Cast body construction with integral end flanges serves general industrial isolation where cost sensitivity outweighs repairability requirements.
- Welded:Fully welded construction eliminates leak paths for buried pipeline service and cryogenic LNG applications requiring zero external emissions.
Today's leader: Flanged. Tomorrow's challenger: Three-Piece.
Material:
Corrosion resistance specifications are displacing carbon steel from chemical processing environments, redrawing procurement patterns by end-use severity.
- Stainless Steel:ASTM A351 CF8M grades provide chloride stress cracking resistance for offshore platform seawater systems and acid gas service. Investment casting capacity concentrates in select Asian supply basins, creating lead time vulnerability for North American project pipelines requiring rapid turnaround.
- Carbon Steel:WCC and LCC grades retain dominance in dry natural gas transmission where internal corrosion is minimal and cost pressure is acute.
- Brass:Lead-free alloys serve potable water distribution systems meeting NSF/ANSI 61 certification requirements.
- PVC:Thermoplastic construction handles low-pressure chemical transfer in semiconductor fabrication and pharmaceutical processing where metallic contamination must be eliminated.
Stainless steel commands specification intensity. Carbon steel retains volume dominance.
End User:
Oil and gas operators drive the most complex qualification requirements, while water treatment utilities generate predictable replacement demand.
- Oil & Gas:Fugitive emissions compliance under EPA Method 21 compels packing upgrades across existing installations. US Gulf Coast petrochemical corridor expansion favors quarter-turn isolation with faster commissioning cycles than gate valve alternatives.
- Water Treatment:Municipal utilities across the United States are accelerating procurement of flanged rising stem designs to replace aging infrastructure, prioritizing visible position indication for remote pump station monitoring.
- Chemical Processing:Chloride-bearing environments specify stainless steel variants resistant to stress corrosion cracking in caustic and acidic process streams.
- Power Generation:Steam service applications require graphite composite packing rated for continuous operation at elevated temperatures in combined cycle plants.
Oil and gas anchors premium pricing. Water treatment sustains replacement volume.
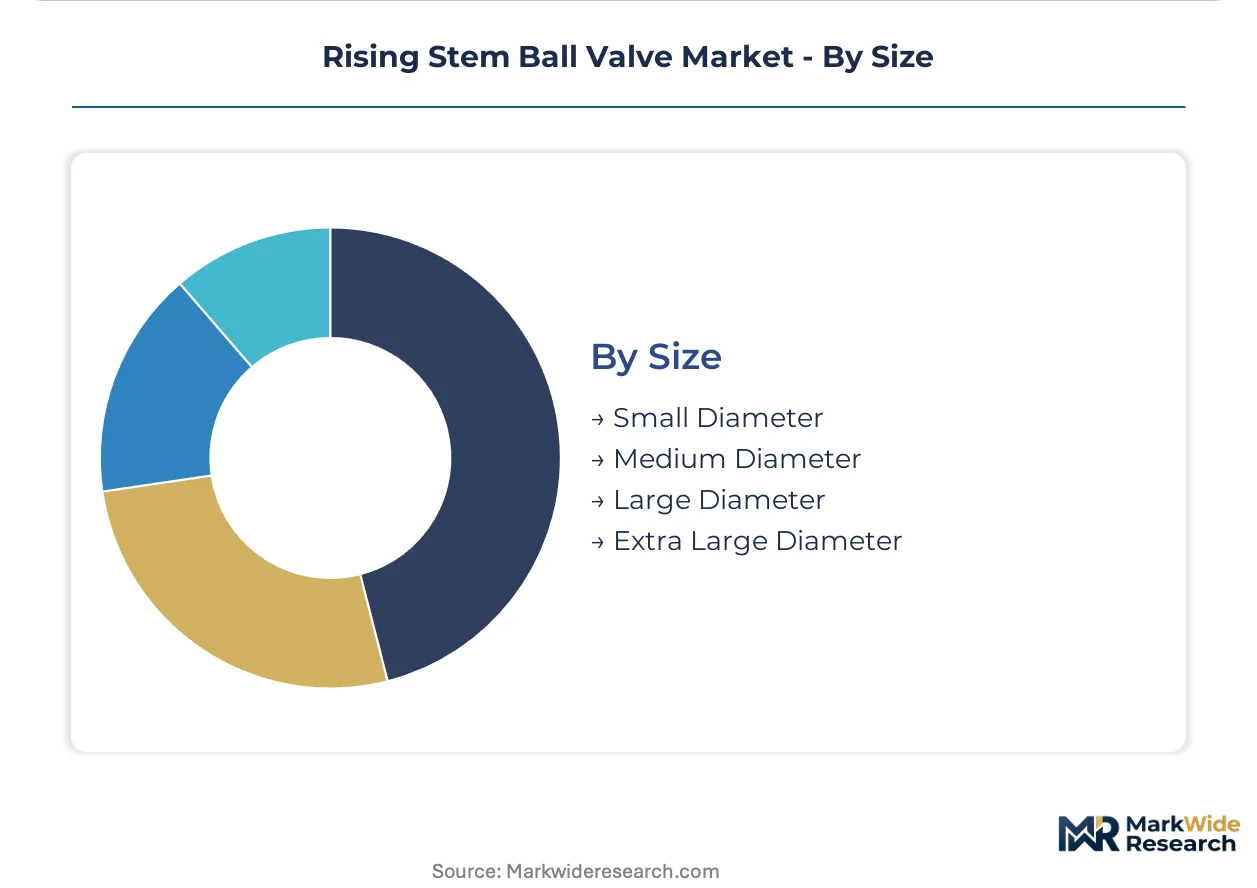
Size:
Large diameter specifications concentrate in pipeline transmission, while small diameter variants serve distributed instrumentation and sampling systems.
- Large Diameter:Trunnion-mounted construction with rising stem extensions serves mainline isolation in natural gas transmission networks. API 6D fire-safe testing and fugitive emissions qualification cycles extend product launch timelines for new entrants.
- Medium Diameter:Process unit isolation in refineries and chemical plants balances pressure containment with manageable actuator sizing for pneumatic and electric automation packages.
- Small Diameter:Instrument root valves and analyzer sampling systems require compact rising stem designs with precision flow control capability.
- Extra Large Diameter:Pipeline block valves for cross-country transmission require specialized foundry capacity and extended lead times for custom casting and machining.
Medium diameter captures project volume. Large diameter concentrates margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rising stem ball valve industry traces its commercial scaling to post-war American petrochemical infrastructure buildouts, with subsequent technology diffusion establishing fabrication clusters across Germany and Japan by the 1970s.
United States
EPA Method 21 compliance mandates and API 6D certification requirements are accelerating replacement cycles across Texas and Louisiana refineries. The Biden administration's Infrastructure Investment and Jobs Act directs federal procurement toward visible position indication systems for water treatment modernization. Houston anchors the Gulf Coast petrochemical corridor where turnaround schedules favor quarter-turn isolation valves over legacy gate designs.
Germany
Chemical processing demand for chloride-resistant stainless steel variants drives specification intensity across BASF and Bayer supply chains. The EU F-Gas Regulation tightens leakage thresholds for process equipment, redirecting procurement toward ISO 15848 Class BH-compliant packing configurations. The Ruhr industrial cluster and Ludwigshafen chemical complex concentrate engineering procurement for severe service applications.
China
State-backed refinery expansion along the Yangtze River Delta and Bohai Bay Rim generates volume demand for flanged configurations. MEE enforcement of fugitive emissions standards in the 14th Five-Year Plan period elevates qualification barriers for domestic suppliers. Ningbo and Shanghai fabrication hubs are scaling investment casting capacity for ASTM A351 CF8M stainless steel bodies.
Japan
Compact three-piece designs dominate space-constrained retrofit applications across Idemitsu and Eneos refinery catalyst regeneration skids. METI hydrogen infrastructure roadmaps are reshaping metallurgical specifications for energy transition projects. The Chubu region around Nagoya maintains specialized foundry capacity for high-integrity castings serving domestic and export markets.
Saudi Arabia
Aramco's Master Gas System expansion and Red Sea petrochemical megaprojects are specifying API 6D-certified isolation valves for sour service conditions. The Saudi Standards, Metrology and Quality Organization aligns local content requirements with international qualification protocols. The Eastern Province industrial cities of Jubail and Yanbu concentrate EPC procurement for integrated valve-actuator packages.
Rising Stem Ball Valve Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and aftermarket service depth. The vendor base stratifies between integrated industrial conglomerates with full-lifecycle service networks and specialized fabricators competing on lead time and customization. Three archetypes dominate: diversified flow control platforms with digital instrumentation integration, regional casting specialists with NACE-qualified metallurgical capabilities, and compact design innovators serving space-constrained retrofits. Consolidation pressure manifests through strategic partnerships bundling actuation and positioner technologies, while geographic expansion targets hydrogen infrastructure qualification in European and Middle Eastern project pipelines.
Within the diversified platform tier, Emerson Electric Co. and Flowserve Corporation occupy positions anchoring premium specification in offshore and severe service applications. KITZ Corporation exemplifies the compact design specialist archetype, with Japanese fabrication heritage supporting retrofit-focused engineering. These three names illustrate how competitive positioning splits between integrated solution breadth and targeted dimensional optimization.
| Leading Market Players |
|---|
| Trillium Flow Technologies |
| IMI |
| Emerson Electric Co. |
| Crane Company |
| Valmet |
| Flowserve Corporation |
| SCV Valve |
| KITZ Corporation |
| SLB |
| Others |
Pricing and Supply Chain Analysis
ASTM A351 CF8M stainless steel scrap indices cascade through foundry procurement contracts into three-tier pricing structures across premium, standard, and economy levels. API 6D certification costs and graphite composite packing material premiums stratify final valve pricing for oil and gas buyers against water treatment utilities with simpler specification requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates API 6D-certified severe service variants from general industrial configurations and commodity floating ball alternatives. Price differentiation centers on certification grade and after-sales service bundling, with integrated digital positioner packages commanding substantial premiums over bare valve procurement. Cost compression in the economy tier is intensifying because Asian foundry capacity expansion feeds lower-cost carbon steel variants into non-critical applications. Water treatment utilities exhibit the highest price sensitivity due to municipal budget constraints, while offshore platform operators prioritize qualification reliability over unit cost.
Supply Chain Analysis
Refurbishment flows for Stellite 6 seat hardfacing and actuator recalibration services create aftermarket revenue streams that anchor supplier-customer relationships beyond initial equipment sales. Investment casting capacity concentrates in China, Japan, and South Korea, with Ningbo and Shanghai fabrication hubs scaling ASTM A351 CF8M stainless steel body production. Raw material dependencies draw from nickel ore processing, graphite mining for packing composites, and specialty alloy feedstocks. Single-source vulnerability concentrates in certified weld overlay technician pools for Inconel 625 cladding procedures. Distribution runs through EPC contractor lump-sum turnkey procurement channels and direct OEM relationships with major refining operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rising stem ball valve market functions as a stable compounder anchored by EPA Method 21 compliance mandates that perpetuate replacement cycles across installed bases. Infrastructure aging and emissions tightening create predictable demand visibility regardless of cyclical capital expenditure fluctuations.
For Market Incumbents: Cement API 6D certification depth and aftermarket service network density as defensive moats against low-cost trunnion-mounted valve substitution. Expand captive investment casting capacity in North American fabrication shops to mitigate lead time vulnerability from Asian supply concentration. Prioritize hydrogen embrittlement test protocol qualification ahead of NACE MR0175 revision implementation to capture energy transition infrastructure specification.
For New Entrants and Emerging Players: Municipal water treatment utilities represent an underserved buyer archetype with accelerating procurement of flanged configurations for aging gate valve replacement. Target California and Florida utilities with visible position indication mandates as the most penetrable segment, leveraging standardized ANSI dimensions to bypass custom engineering barriers. Pursue direct contracting relationships with regional pump station operators rather than competing through EPC channels dominated by established suppliers.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional casting specialists possessing NACE-qualified metallurgical capabilities and existing API 6D fire-safe testing infrastructure. Long-term viability across the analysis window favors suppliers with backward integration into specialty alloy processing and certified welding procedure libraries. Monitor EPA enforcement intensity and MEE fugitive emissions standard alignment as the critical inflection indicator for replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| API 6D Certification Investment | Fire-safe testing and fugitive emissions qualification unlock specification access across Gulf Coast petrochemical projects. |
| Backward Integration into Investment Casting | Captive ASTM A351 CF8M stainless steel body production insulates margin from Asian foundry lead time volatility. |
| Digital Positioner Platform Integration | HART protocol diagnostics bundled with mechanical rising stem designs enable predictive maintenance contracts offshore. |
| Hydrogen Infrastructure Qualification | NACE MR0175 sour service revisions and hydrogen embrittlement protocols position suppliers for energy transition capex. |
| Aftermarket Service Network Expansion | Stellite 6 seat refurbishment and actuator recalibration sustain recurring revenue from installed base relationships. |
Research Methodology
Direct dialogue with plant engineers, maintenance directors at Texas and Louisiana refineries, EPC procurement leads, and aftermarket service heads anchored qualitative insight generation. Secondary validation drew from API certification registries, EPA enforcement action databases, FERC pipeline filings, and customs trade records for valve import flows. Bottom-up and top-down triangulation cross-checked unit shipment estimates against capital expenditure disclosures from major petrochemical operators.
Bottom-up modeling segmented volume and value across product type, material grade, end-use industry, and regional production hub dimensions throughout the forecast period. Top-down constraints applied macroeconomic filters and energy transition infrastructure spend trajectories. CAGRs were derived from regression analysis of replacement cycle timing, regulatory compliance deadlines, and project pipeline visibility. Industry-specific forecast inputs incorporated turnaround schedule density in the US Gulf Coast and MEE enforcement intensity timelines for Chinese domestic suppliers.
Inputs from API certification bodies and EPA regional enforcement offices were available through the study window; gaps in real-time EPC contractor procurement pipeline data introduce uncertainty bands around near-term volume projections. Forecasts reflect assumptions regarding regulatory timeline adherence and foundry capacity expansion schedules. Practitioners should monitor EPA Method 21 inspection frequency and NACE MR0175 revision publication for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Valve Grinder Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Industrial Safety Valves Market
Valves
Fin Tube Market
Valves
Railway Emergency Valves Market
Valves
North America Irrigation Valves Market
Valves
Asia-Pacific Medium Voltage Switchgear Market
Valves
Motorized Valves Market
Valves
Global Solenoid Valves Market
Valves
Valve Cover Gasket Market
Valves
Cathodic Protection Market
Valves
India Industrial Valves Market
Valves
Leak Detection Market
Valves
Emergency Shutdown Valves Market
Valves
China Explosion-Proof Equipment Market
Valves
Asia Pacific Pipeline Maintenance Market