
 Pneumatic Positioner Market | 2026-2036
Pneumatic Positioner Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Positioner Market Analysis
The pneumatic positioner market is repositioning around a widening split between premium smart positioners with embedded diagnostics and commodity analog units serving cost-sensitive replacement cycles. Emerson Electric Co. leverages its Plantweb digital ecosystem to anchor premium positioning in upstream oil and gas automation. ABB competes through integrated electropneumatic platforms that merge valve control with asset management software. Siemens specializes in SIL-certified safety instrumented systems that dominate European chemical processing installations.
A pneumatic positioner is a feedback-controlled device that modulates air pressure to a valve actuator to achieve precise stem positioning, typically operating with input signals of 3–15 psi or 4–20 mA and delivering air output up to 150 psi for throttling or on-off service. Its primary industrial purpose is to ensure accurate flow control in process loops where valve hysteresis, dead band, or packing friction would otherwise degrade loop performance. Smart positioner technology leads value generation by embedding HART or Foundation Fieldbus protocols that enable predictive maintenance and remote calibration, while analog pneumatic segments retain volume dominance in developing industrial bases where capital constraints limit digital migration. Electropneumatic technology captures the fastest structural expansion as facilities retrofit pneumatic infrastructures with electronic control layers without replacing existing valve bodies.
EPA New Source Performance Standards and OSHA Process Safety Management requirements in the United States mandate leak detection and mechanical integrity programs that elevate demand for positioners with diagnostic feedback. REACH substance restrictions and the EU F-Gas Regulation shape material selection and sealing technology for European deployments, while China's GB standards and MIIT industrial upgrading directives accelerate domestic substitution of imported analog units with digital domestic alternatives. Stakeholders must monitor how evolving cybersecurity standards for operational technology networks reshape firmware architecture and supplier certification requirements across major process industries.
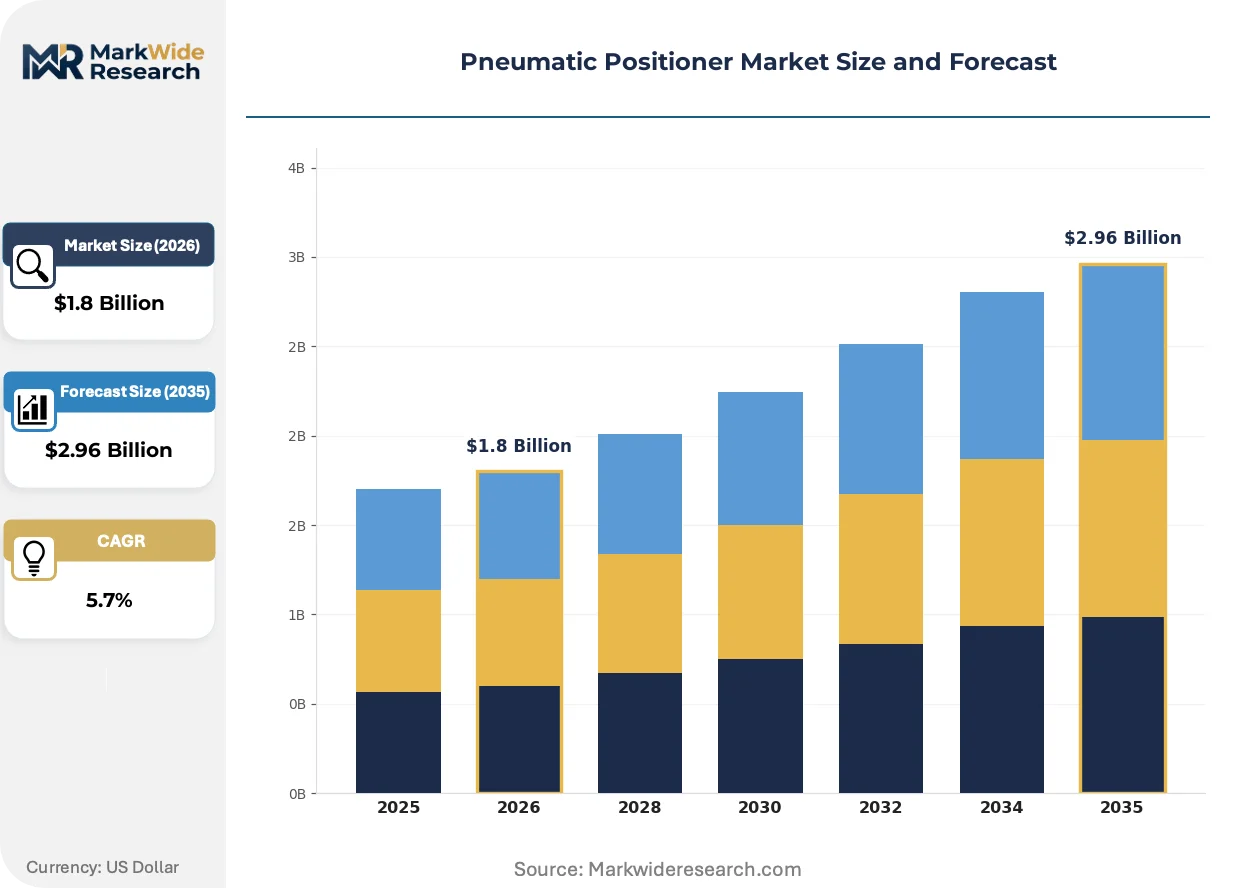
Market Dynamics
Electropneumatic retrofitting of existing valve infrastructures without actuator replacement is compressing replacement cycles and redrawing supplier relationships across process industries. This structural force is accelerating the displacement of standalone analog positioners by integrated digital systems that embed diagnostics directly into control loops.
Growth Catalysts
- EU F-Gas Regulation:Industrial decarbonization mandates in Germany and France are accelerating the phase-out of pneumatic-only positioners in favor of electropneumatic systems with lower fugitive emissions profiles.
- Upstream oil and gas automation:Remote valve diagnostics for offshore platforms and shale fields is driving smart positioner adoption where manual calibration access is prohibitively expensive.
- Ethylene cracker investments:The United States Gulf Coast petrochemical corridor is generating concentrated demand for high-reliability valve automation in mega-project greenfield construction.
Market Restraints
- Stainless steel and aluminum price volatility:Positioner housing and manifold material costs fluctuate with base metal commodity markets, squeezing margins on standard-grade analog units.
- Specialized casting concentration:Precision pneumatic manifold manufacturing concentrates in German and Japanese supplier bases, creating single-source vulnerabilities for tier-two positioner assemblers.
- Foundation Fieldbus protocol decline:Ethernet-APL and HART-IP adoption is rendering legacy digital positioner investments obsolete before full depreciation.
Strategic Opportunities
- India process industry upgrading:MIIT-aligned domestic manufacturers are substituting imported analog positioners with locally produced digital electropneumatic units in refinery and chemical expansions.
- Cybersecurity certification:IEC 62443 compliance for operational technology networks is creating premium positioning for suppliers with pre-certified firmware architectures.
- Predictive maintenance bundling:Valve control systems integrated with asset management software platforms are capturing service revenue streams previously captured by third-party maintenance contractors.
Industry Challenges
- SIL certification timelines:Safety instrumented system validation for chemical processing applications requires 18-24 month approval cycles that delay product launches and freeze development roadmaps.
- Legacy 3-15 psi infrastructure integration:Retrofitting smart positioners onto decades-old pneumatic actuators without stem position feedback creates calibration drift and diagnostic false-positive rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Positioner Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting, Double Acting, Smart Positioner, Standard Positioner Technology: Electropneumatic, Pneumatic, Digital, Analog End User: Oil & Gas, Chemical Processing, Water Treatment, Power Generation Installation: Panel Mounted, Field Mounted, Pipe Mounted, Rack Mounted |
| Companies Covered | Emerson Electric Co., ABB, Siemens, Flowserve Corporation, Schneider Electric, Azbil Corporation, SMC Corporation, Rotork plc, Christian Bürkert GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Positioner Market Emerging Trajectories
Digital protocol architectures are rewiring how positioner value is captured, shifting revenue from hardware replacement toward firmware-enabled diagnostics and remote calibration services. This transformation is compressing the traditional analog-digital substitution timeline.
HART-IP and Ethernet-APL physical layer technology is converging with legacy 4-20 mA control infrastructures to enable single-cable power and data transmission to field devices. Chemical processors in the Netherlands and Belgium are piloting these converged networks in brownfield installations. This convergence is collapsing the distinction between smart positioners and distributed I/O modules, forcing suppliers to compete on software integration rather than pneumatic performance alone.
EPA New Source Performance Standards for greenhouse gas emissions are mandating leak detection and repair programs that require continuous valve packing monitoring. United States refineries and petrochemical plants must install positioners with diagnostic feedback capabilities to satisfy mechanical integrity audit requirements. The regulation is elevating demand for electropneumatic units with embedded pressure sensors and stem position transmitters in the Gulf Coast and Midwest refining belts.
Aftermarket service unbundling is fragmenting the traditional positioner supply relationship. End-users in the United States and Germany are separating hardware procurement from calibration and maintenance contracts, awarding multi-year service agreements to specialized valve automation contractors rather than original equipment manufacturers. This pattern is most pronounced in specialty chemical and pharmaceutical processing where FDA Process Validation and EMA GMP requirements demand documented calibration traceability independent of hardware brand.
Pneumatic Positioner Market Segmentation
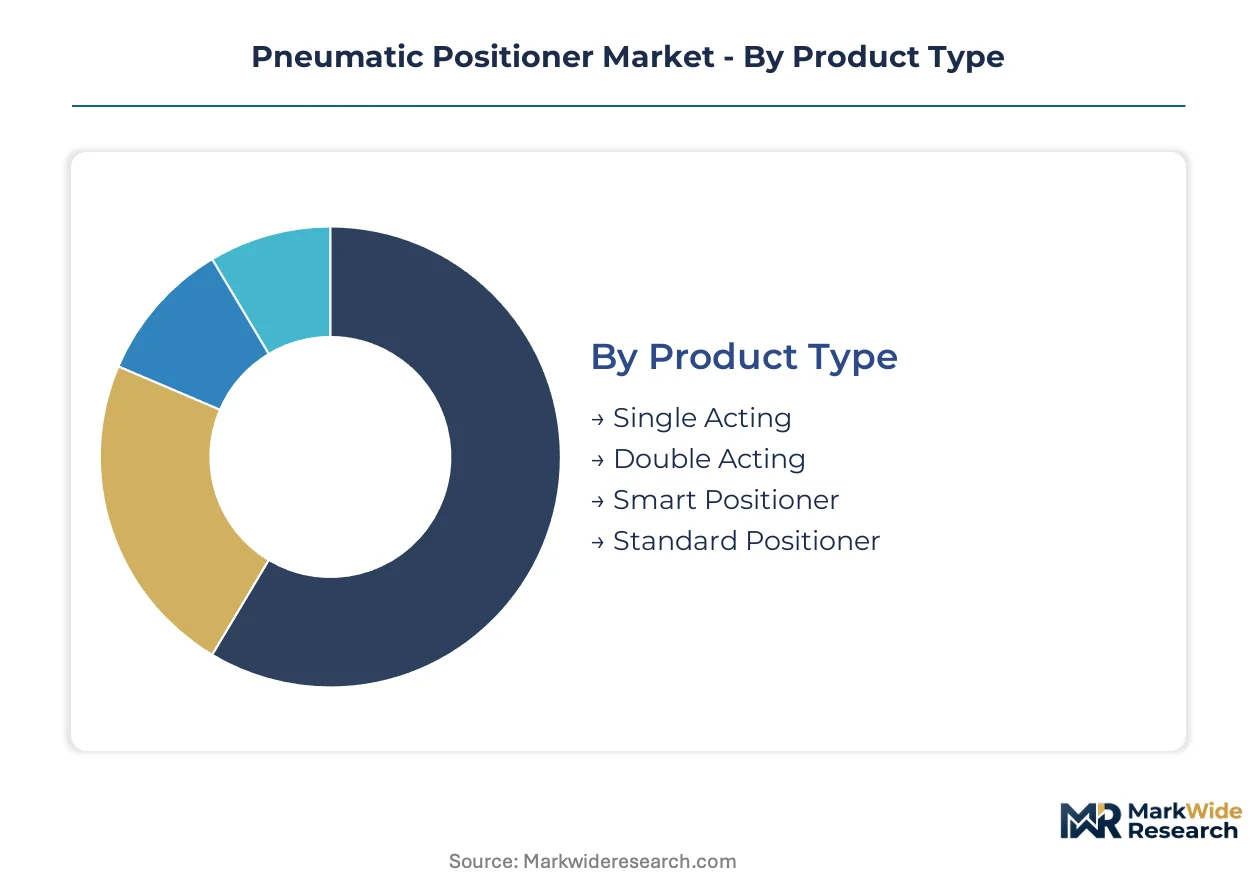
Pneumatic positioner segmentation reflects a market bifurcated between legacy pneumatic infrastructure and digital electropneumatic upgrades. Technology choice determines diagnostic capability, while installation configuration shapes procurement patterns across process industries.
Product Type:
Actuation mechanism and intelligence level define this axis, separating commodity replacement units from premium diagnostic-enabled systems.
- Smart Positioner:Embedded HART, Foundation Fieldbus, or Profibus protocols enable predictive maintenance algorithms and remote calibration. Demand concentrates in United States Gulf Coast ethylene crackers and LNG export terminals where OSHA Process Safety Management mandates continuous valve monitoring.
- Standard Positioner:Conventional 4-20 mA or 3-15 psi input devices without embedded diagnostics serve cost-sensitive replacement cycles. Procurement clusters in Indian refinery expansions and Chinese chemical processing where MIIT industrial upgrading directives accelerate domestic substitution of imported analog units.
- Single Acting:Spring-return designs for fail-safe applications in emergency shutdown systems.
- Double Acting:Air-to-air actuation for high-torque requirements in large valve automation.
Mature deployment sits with Standard Positioner. Newer deployment is concentrated in Smart Positioner.
Technology:
Signal conversion architecture determines integration depth with distributed control systems and asset management platforms.
- Electropneumatic:I/P converters translate electronic control signals into precise pneumatic pressure output. German chemical processors under EU F-Gas Regulation are retrofitting existing valve infrastructures without actuator replacement, compressing replacement cycles for these hybrid systems.
- Digital:Microprocessor-based position control with embedded pressure sensors and stem position feedback. Netherlands and Belgium chemical processors pilot HART-IP and Ethernet-APL converged networks in brownfield installations, collapsing distinctions between smart positioners and distributed I/O modules.
- Pneumatic:Pure 3-15 psi signal devices for isolated pneumatic control loops.
- Analog:Legacy electronic signal processing without firmware-based diagnostics.
Procurement volume clusters in Electropneumatic. Technology substitution is accelerating fastest in Digital.
End User:
Process intensity and safety criticality shape specification requirements across vertical applications.
- Oil & Gas:Upstream offshore platforms and shale fields require remote valve diagnostics where manual calibration access is prohibitively expensive. EPA New Source Performance Standards mandate leak detection and mechanical integrity programs that elevate demand for positioners with diagnostic feedback.
- Chemical Processing:SIL-certified safety instrumented systems dominate European installations under IEC 61511 requirements. Siemens specializes in these applications where 18-24 month validation cycles delay product launches.
- Water Treatment:Municipal and industrial wastewater facilities prioritize cost-optimized analog units.
- Power Generation:Combined cycle and thermal plants specify high-temperature-rated positioners for steam valve service.
Specification complexity peaks in Oil & Gas. Volume scale concentrates in Chemical Processing.
Installation:
Mounting configuration determines environmental protection ratings and maintenance accessibility.
- Field Mounted:Direct valve attachment with NEMA 4X or IP66 enclosures withstands offshore platform and refinery ambient conditions. United States refineries in the Midwest refining belt specify these for continuous valve packing monitoring under EPA greenhouse gas regulations.
- Panel Mounted:Centralized control room installation with pneumatic tubing runs to field actuators. Pharmaceutical processors in Germany separate hardware procurement from calibration contracts, awarding multi-year service agreements to specialized valve automation contractors for these centralized configurations.
- Pipe Mounted:Inline manifold attachment for compact skid-based systems.
- Rack Mounted:Dense instrumentation arrangements in offshore platform equipment rooms.
Aftermarket service fragmentation is most pronounced in Panel Mounted. Procurement standardization is advancing fastest in Field Mounted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Gulf Coast petrochemical corridor anchors regional demand concentration, with mega-project investments in ethylene crackers and LNG export terminals requiring high-reliability valve automation infrastructure.
United States
Upstream oil and gas automation drives smart positioner procurement across offshore platforms and shale fields where manual calibration access is prohibitively expensive. EPA New Source Performance Standards mandate leak detection and mechanical integrity programs that elevate demand for positioners with diagnostic feedback. Gulf Coast refineries and Midwest refining belt facilities install electropneumatic units with embedded pressure sensors to satisfy continuous valve packing monitoring requirements.
Germany
Industrial decarbonization mandates accelerate replacement of legacy analog units with digital electropneumatic systems across chemical processing installations. EU F-Gas Regulation shapes material selection and sealing technology for European deployments, compressing replacement cycles for hybrid valve control systems. Bavarian and North Rhine-Westphalian chemical clusters retrofit existing valve infrastructures without actuator replacement, generating concentrated demand for SIL-certified safety instrumented systems.
China
GB standards and MIIT industrial upgrading directives accelerate domestic substitution of imported analog units with digital domestic alternatives in refinery and chemical expansions. The country's national industrial regulator pushes process industry upgrading through standardized certification requirements. Yangtze River Delta and Pearl River Delta manufacturing zones concentrate procurement of locally produced digital electropneumatic units as foreign technology substitution advances.
India
MIIT-aligned domestic manufacturers substitute imported analog positioners with locally produced digital electropneumatic units across refinery and chemical expansion projects. The country's central industrial authority promotes domestic manufacturing through phased import substitution programs. Maharashtra and Gujarat industrial corridors concentrate demand for cost-optimized valve automation in petrochemical and specialty chemical greenfield construction.
Netherlands
Chemical processors pilot HART-IP and Ethernet-APL converged networks in brownfield installations, collapsing distinctions between smart positioners and distributed I/O modules. ECHA substance restrictions under REACH framework influence material compliance for sealing technology in European deployments. Rotterdam port industrial cluster and Antwerp corridor facilities drive pilot adoption of single-cable power and data transmission to field devices.
Pneumatic Positioner Market Vendor Landscape
Premium-margin players sit above commodity-margin players across diagnostic capability and protocol integration depth. The market structure consolidates around diversified industrial automation conglomerates with embedded valve control portfolios, while specialized pneumatic component suppliers occupy niche positions in safety-critical applications. Three archetypes dominate: integrated electropneumatic platform providers, SIL-certified safety system specialists, and commodity analog replacement suppliers. Competitive moves center on firmware-enabled service bundling and cybersecurity certification pre-positioning for IEC 62443 compliance.
Within the integrated platform tier, Emerson Electric Co. and ABB occupy positions that exemplify the convergence of valve control with asset management software ecosystems. Siemens anchors the safety-specialist archetype through its concentration in European chemical processing installations. These three companies represent the structural split between premium smart positioning with embedded diagnostics and commodity analog units serving cost-sensitive replacement cycles across global process industries.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| ABB |
| Siemens |
| Flowserve Corporation |
| Schneider Electric |
| Azbil Corporation |
| SMC Corporation |
| Rotork plc |
| Christian Bürkert GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
The smart-versus-analog bifurcation in pneumatic positioners generates divergent pricing architectures and supply chain footprints across process industries. Premium smart units with embedded HART protocols command value-based pricing tied to uptime guarantees and predictive maintenance outcomes, while commodity analog replacements compete on unit economics in cost-sensitive procurement cycles across Indian and Chinese refinery expansions.
Pricing Analysis
Value-based pricing anchored to valve uptime performance and reduced unplanned shutdowns dominates the premium smart positioner tier. Price differentiation stems from SIL certification grade and bundled firmware-enabled diagnostic services, with certified safety instrumented systems capturing substantial premiums over standard-grade units. Pricing pressure intensifies in the analog replacement segment as domestic Chinese and Indian manufacturers compress margins through localized production under MIIT industrial upgrading directives. Chemical processors in Germany and the United States Gulf Coast exhibit lowest price sensitivity due to regulatory mandates for continuous valve monitoring, while municipal water treatment facilities in emerging economies remain most price-constrained.
Supply Chain Analysis
Precision pneumatic manifold manufacturing rests on concentrated German and Japanese specialty casting suppliers, creating input dependencies for tier-two positioner assemblers. Raw material exposure centers on stainless steel and aluminum commodity price volatility for housings, alongside specialized elastomer seals subject to REACH substance restrictions. Single-source vulnerability in precision casting capacity represents the dominant structural risk, with limited qualified suppliers capable of meeting tolerance specifications for high-pressure pneumatic channels. Distribution runs through authorized industrial automation distributors and direct OEM relationships with major petrochemical and chemical processing EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized casting capacity constraints in precision pneumatic manifolds prop pricing power for integrated suppliers, sustaining margin premiums despite commodity pressure in analog segments.
For Market Incumbents: Anticipate displacement risk from Ethernet-APL protocol adoption rendering legacy Foundation Fieldbus investments obsolete, and defend position by deepening backward integration into precision casting capacity in Germany or Japan while accelerating IEC 62443 cybersecurity certification pre-positioning for operational technology networks. For New Entrants and Emerging Players: Launch via digital electropneumatic platforms targeting India's Maharashtra and Gujarat industrial corridors, where MIIT-aligned domestic substitution programs create white-space for locally certified alternatives to imported analog units, with service bundling as the primary go-to-market wedge against established hardware-centric suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with SIL-certified safety system specialists given accelerating chemical processing automation mandates under EU F-Gas Regulation and OSHA Process Safety Management requirements, with long-term viability hinging on firmware-enabled service revenue attachment rates; watch cybersecurity certification velocity as the inflection signal for competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive supply of pneumatic manifolds mitigates single-source vulnerability from German and Japanese suppliers. |
| IEC 62443 Certification Program | Pre-certified firmware architectures unlock premium positioning in United States Gulf Coast petrochemical installations. |
| Predictive Maintenance Platform Launch | Software bundling captures service revenue previously won by third-party valve automation contractors in Germany. |
| Domestic Manufacturing Scale-Up in India | Localized production under MIIT directives substitutes imported analog units in refinery expansions. |
| Ethernet-APL Protocol Migration | Converged power-data transmission aligns with Netherlands and Belgium brownfield pilot networks. |
Methodological Framework
Independent corroboration across positioner OEM technical directors, petrochemical plant maintenance managers, and industrial automation distributor principals underwrites the qualitative findings. Primary fieldwork combined structured interviews with aftermarket service heads and EPC procurement leads alongside secondary validation through customs trade data, SEC 10-K filings of listed automation conglomerates, and process industry association technical reports. Bottom-up unit demand estimates triangulated against top-down process industry capital expenditure patterns.
Comparable historical reference periods anchored the projection horizon to observed substitution timelines between analog and electropneumatic technologies. The analytical framework modeled segmentation across actuation mechanism, signal conversion architecture, end-use vertical, and mounting configuration, with CAGRs derived from fitted technology diffusion curves and regulatory mandate implementation schedules. Forecast inputs incorporated EPA New Source Performance Standards enforcement trajectories and EU F-Gas Regulation phase-out timelines.
Stainless steel commodity price volatility, cybersecurity standard revision cycles, and protocol architecture obsolescence are the dominant revision risks. Forecasts reflect documented assumptions on technology substitution rates and regulatory implementation cadence. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Valves in Oil and Gas Industry Market
Valves
Blow - Off Valves Market
Valves
Rupture Discs Market
Valves
Ball Valves Market
Valves
Safety Valve Market
Valves
Valve Sack Market
Valves
Pipeline Pigging Valves Market
Valves
Global Valve Positioners Market
Valves
Construction Valve Seat Insert Market
Valves
Valve Cover Gasket Market
Valves
Lined Valves Market
Valves
Servo Valves Market
Valves
Compressor Valves Market
Valves
Water Draw Off Valves Market
Valves
Industrial Safety Valves Market
Valves
Insulation Flanges Market