
 Air Jet Ejectors Market | 2026-2036
Air Jet Ejectors Market Size, Share, and Industry Trends Forecast 2026-2036
Air Jet Ejectors Market Analytics
Stainless steel alloys is realigning cost-performance trade-offs for air jet ejectors operating in corrosive process environments. SMC Corporation leverages extensive pneumatic component portfolios to dominate Asian factory automation channels. Parker Hannifin Corporation anchors North American distribution through integrated motion and control system bundling. Graham Corporation specializes in engineered vacuum solutions for chemical and petrochemical process intensity.
An air jet ejector converts pressurized gas kinetic energy into suction force through a converging-diverging nozzle and venturi throat, typically achieving vacuum levels of 1–100 mbar absolute without moving mechanical parts. Multi-stage ejector configurations lead industrial vacuum applications where deeper suction and reduced steam consumption determine total cost of ownership. High-pressure ejectors represent the fastest-growing product category as oil and gas operators retrofit sulfur recovery and flare gas recovery units with more efficient vacuum generation equipment.
EPA New Source Performance Standards and EU F-Gas Regulation shape demand by restricting vented process gases and mandating leak-tight vacuum system designs across chemical processing and pharmaceutical manufacturing. OSHA process safety management requirements and ISO 5167 flow measurement standards further constrain equipment specification and installation protocols in US industrial facilities. Buyers must weigh material upgrade costs against extended service intervals and regulatory compliance exposure when selecting between standard alloy and premium corrosion-resistant ejector configurations.
Market Dynamics
Stainless steel alloy substitution is compressing the total cost of ownership calculus for corrosive-service ejector installations across chemical processing and offshore hydrocarbon recovery.
Growth Catalysts
- EU F-Gas Regulation:Mandates for leak-tight vacuum architectures are forcing sulfur recovery unit retrofits across German and Dutch petrochemical corridors.
- Electronics manufacturing clustering:East Asian semiconductor fabrication expansion is driving multi-stage ejector demand for wafer handling vacuum systems.
- Cast iron displacement:High-pressure process environments are accelerating stainless steel adoption in flare gas recovery and offshore platform applications.
Market Restraints
- Alloy cost volatility:Nickel and molybdenum price swings in stainless steel feedstocks compress margin predictability for engineered ejector fabricators.
- Specialized foundry concentration:Precision casting capacity for venturi throats concentrates in German and Japanese supplier networks, creating single-source vulnerability.
- Mechanical vacuum pump substitution:Liquid ring and dry screw technologies are capturing mid-range vacuum applications below 50 mbar where energy efficiency dominates selection criteria.
Strategic Opportunities
- Indian chemical corridor expansion:Gujarat and Maharashtra state industrial zones are greenfielding capacity with stricter emissions baselines than legacy European installations.
- Pharmaceutical lyophilization:Freeze-drying process intensification is opening demand for hygienic-design ejectors with FDA-validated cleanability protocols.
- ISO 5167 flow measurement convergence:Integrated nozzle-venturi designs with embedded differential pressure sensing are enabling predictive maintenance service contracts.
Industry Challenges
- Computational fluid dynamics expertise scarcity:Converging-diverging nozzle optimization for multi-stage configurations requires specialized simulation talent concentrated in aerospace and turbine sectors.
- Legacy steam system integration:Retrofitting high-efficiency ejectors into existing boiler and condensate networks demands custom engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Jet Ejectors Market |
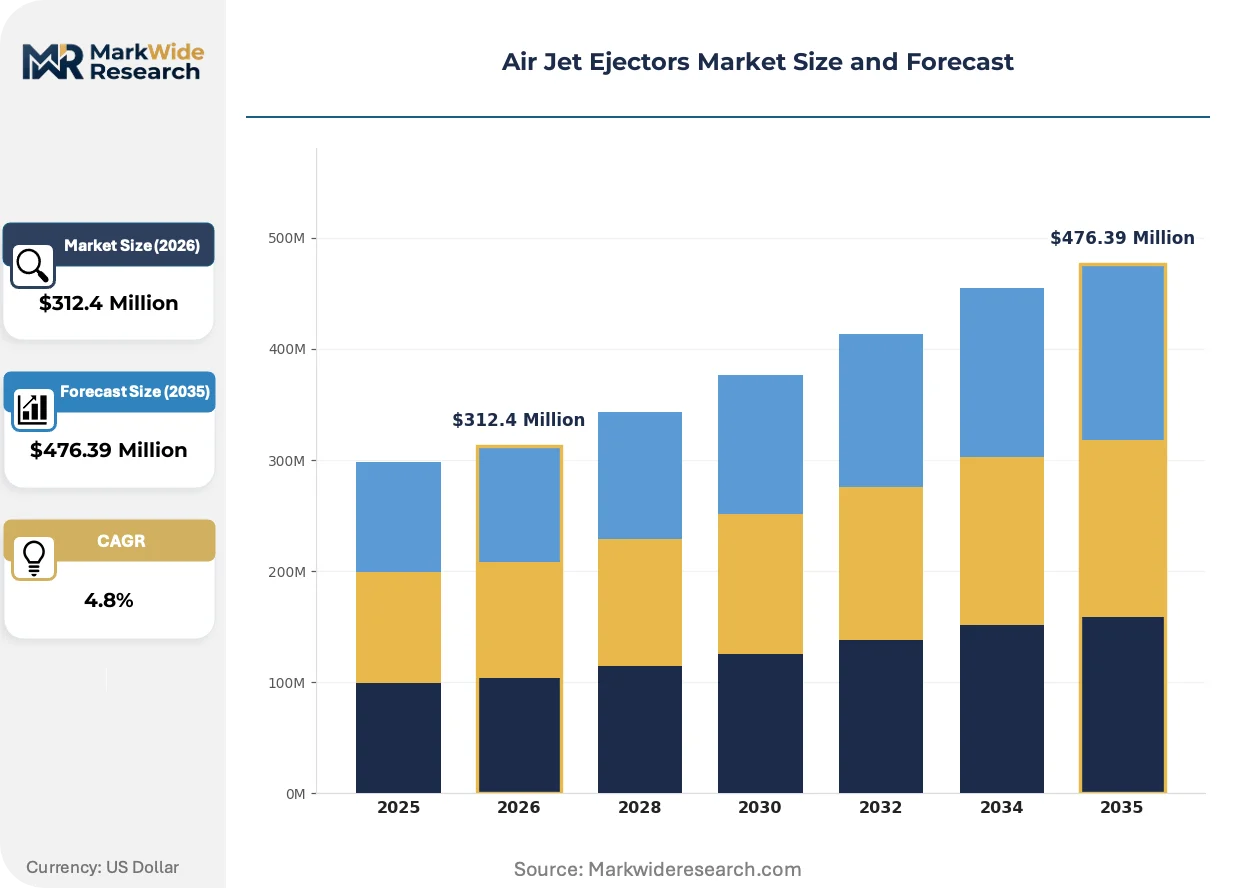
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Ejectors, Multi-Stage Ejectors, High-Pressure Ejectors, Variable Area Ejectors Application: Vacuum Systems, Fluid Transport, Chemical Processing, Air Separation End User: Manufacturing, Oil & Gas, Pharmaceuticals, Aerospace Installation Type: Fixed, Portable, Modular, Integrated |
| Companies Covered | SMC Corporation, Festo AG & Co. KG, Gardner Denver, Schmalz GmbH, Piab AB, Parker Hannifin Corporation, Ingersoll Rand, Atlas Copco AB, Graham Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Jet Ejectors Market Evolving Landscape
Additive manufacturing of venturi throats is collapsing lead times for custom pressure-ratio geometries while enabling topology-optimized flow patterns previously unmachinable.
Computational fluid dynamics-optimized nozzle profiles are rewriting the efficiency frontier for multi-stage steam ejectors in deep-vacuum chemical processing. Hydrocarbon operators in the US Gulf Coast are specifying these geometries for sulfur recovery unit retrofits. The technology is compressing steam consumption benchmarks that have remained static since the 1980s.
EPA New Source Performance Standards for refinery flare systems are mandating vapor recovery unit upgrades with tighter vacuum system integrity requirements. Process engineers must now specify double-block-and-bleed isolation and continuous emissions monitoring interfaces on ejector installations. The regulation is reshaping procurement specifications for US downstream operators while creating specification divergence from European F-Gas compliance pathways.
Buyer consolidation among integrated chemical majors is compressing vendor qualification cycles and unbundling aftermarket service from initial equipment supply. Procurement teams at German and Indian petrochemical complexes are demanding ten-year total cost of ownership guarantees with predictive maintenance telemetry integration. This behavioral shift is visible most acutely in sulfuric acid and caprolactam process lines where unplanned vacuum loss carries catastrophic corrosion risk.
Air Jet Ejectors Market Segmentation
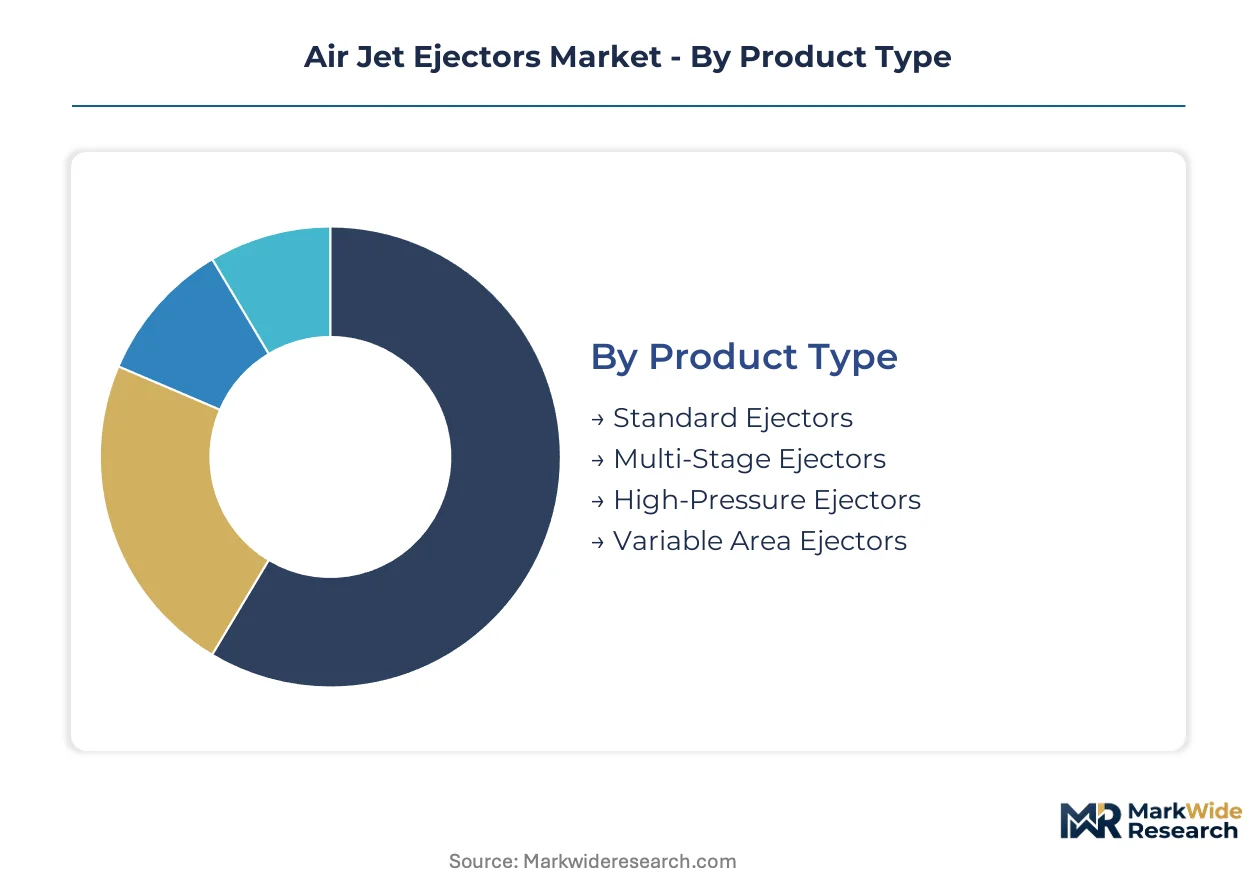
Air jet ejector procurement decisions split sharply between commodity replacement cycles and engineered system specifications. Material selection, stage configuration, and integration architecture each create distinct competitive arenas with divergent margin profiles and vendor qualification barriers.
Product Type:
Volume sales concentrate in standardized single-stage units, while premium capture flows to configurable multi-stage and high-pressure architectures for corrosive-service applications.
- Multi-Stage Ejectors:Stacked venturi configurations achieve absolute pressures below 10 mbar through kinetic energy cascading across three to six stages. Semiconductor fabrication facilities in South Korea and Taiwan specify these for wafer handling vacuum integrity where single-point failure risks contamination losses.
- High-Pressure Ejectors:Forged stainless steel construction withstands motive pressures exceeding 10 bar in flare gas recovery and sulfur recovery units. German and Dutch petrochemical operators retrofit these to meet EU F-Gas Regulation leak-tight mandates.
- Standard Ejectors:Single-stage cast iron or carbon steel units dominate general industrial vacuum duties below 100 mbar.
- Variable Area Ejectors:Adjustable throat geometries modulate suction capacity against fluctuating process loads.
Today's leader: Multi-Stage Ejectors. Tomorrow's challenger: High-Pressure Ejectors.
Application:
Process intensity and regulatory exposure determine specification tier, with chemical processing commanding corrosion-resistant alloys while fluid transport accepts standard materials.
- Chemical Processing:Sulfuric acid, caprolactam, and phosgene production lines require Hastelloy or duplex stainless venturi throats. Indian chemical corridors in Gujarat specify these for stricter emissions baselines than legacy European installations.
- Vacuum Systems:Centralized vacuum networks in automotive assembly plants and electronics cleanrooms demand hygienic-design ejectors with FDA-validated cleanability protocols.
- Fluid Transport:Pumping abrasive slurries and pneumatic conveying of bulk solids utilizes standard alloy construction.
- Air Separation:Cryogenic gas production facilities integrate ejectors into pre-cooling and purification subsystems.
Demand concentrates in chemical processing for margin, vacuum systems for volume.
End User:
Oil and gas operators drive specification complexity through safety-critical applications, while manufacturing procurement emphasizes total cost of ownership guarantees.
- Oil & Gas:Offshore platform flare gas recovery and vapor recovery unit retrofits specify API-compliant materials with double-block-and-bleed isolation. US Gulf Coast refineries face EPA New Source Performance Standards mandating continuous emissions monitoring interfaces.
- Pharmaceuticals:Lyophilization freeze-drying processes demand ejectors with surface finishes below 0.8 micrometers Ra and crevice-free designs for CIP/SIP validation.
- Manufacturing:Automotive and electronics production hubs in East Asia deploy multi-stage configurations for automated material handling.
- Aerospace:Altitude simulation chambers and fuel system testing rigs require precision vacuum control.
Oil and gas sets the specification ceiling; pharmaceuticals define the hygiene frontier.
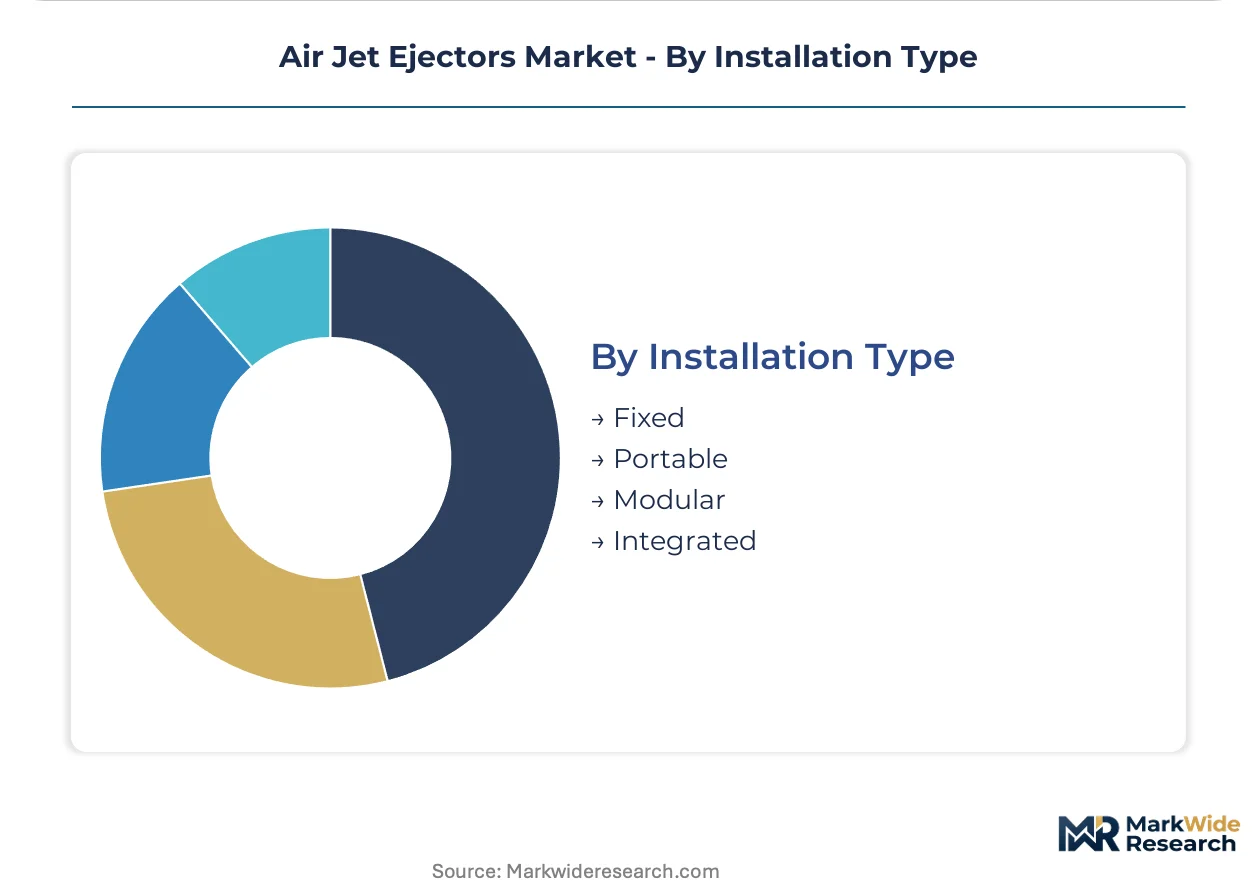
Installation Type:
Capital expenditure constraints favor fixed installations, while operational flexibility drives modular and portable alternatives in project-based industries.
- Modular:Pre-engineered skid packages collapse field installation timelines for sulfur recovery unit retrofits. German petrochemical procurement teams demand ten-year total cost of ownership guarantees with predictive maintenance telemetry integration.
- Integrated:Embedded nozzle-venturi designs with differential pressure sensing enable condition-based maintenance contracts. These configurations are gaining traction in ISO 5167 flow measurement convergence applications.
- Fixed:Permanent installations dominate continuous process industries with stable vacuum demand profiles.
- Portable:Mobile units serve temporary dewatering, emergency spill response, and construction site duties.
Fixed installations anchor current revenue; modular architectures capture retrofit momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters dominate air jet ejector procurement, with vacuum system installations tracking semiconductor fabrication expansion and automotive electrification investments across multiple national industrial zones.
Germany
Chemical processing corridors along the Rhine and Ruhr retrofit sulfur recovery units with stainless steel ejector configurations. EU F-Gas Regulation leak-tight mandates accelerate replacement cycles in Ludwigshafen and Leverkusen petrochemical complexes. Modular skid packages with predictive maintenance telemetry gain procurement preference among integrated chemical majors.
United States
EPA New Source Performance Standards force vapor recovery unit upgrades across Gulf Coast refineries. Double-block-and-bleed isolation specifications and continuous emissions monitoring interfaces reshape procurement protocols. Houston and Corpus Christi industrial zones drive specification complexity for flare gas recovery applications.
China
Semiconductor fabrication expansion in Shanghai and Hefei multi-stage ejector demand for wafer handling vacuum integrity. MIIT industrial upgrading guidelines emphasize energy efficiency benchmarks in process equipment selection. Yangtze River Delta electronics clusters concentrate procurement volume for hygienic-design configurations.
India
Gujarat and Maharashtra state industrial zones greenfield chemical capacity with stricter emissions baselines than legacy European installations. BIS certification requirements and state-level pollution control mandates elevate material specification tiers. Dahej and Mundra petrochemical corridors specify Hastelloy venturi throats for sulfuric acid process lines.
South Korea
Memory and logic chip fabrication in Pyeongtaek and Yongin drives multi-stage ejector demand for contamination-sensitive vacuum environments. MFDS pharmaceutical manufacturing standards extend to process equipment surface finish requirements. Busan-Ulsan industrial belt integrates ejectors into centralized vacuum networks for automotive component handling.
Air Jet Ejectors Market Competitive Landscape
Global majors compete with regional champions across pneumatic component distribution and engineered vacuum system integration. Market structure fragments between scale-driven diversified industrials and specialized fabricators focused on corrosive-service applications. Three archetypes dominate: Asian factory automation component suppliers, North American motion-and-control bundlers, and European precision vacuum specialists. Competitive moves concentrate on portfolio diversification through pneumatic system integration and geographic expansion via distribution partnerships.
Within the diversified industrial tier, SMC Corporation and Parker Hannifin Corporation exemplify contrasting regional anchoring strategies. SMC leverages extensive pneumatic component portfolios across Asian factory automation channels. Parker Hannifin anchors North American distribution through integrated motion and control system bundling. Graham Corporation occupies a specialist position in engineered vacuum solutions for chemical and petrochemical process intensity.
| Leading Market Players |
|---|
| SMC Corporation |
| Festo AG & Co. KG |
| Gardner Denver |
| Schmalz GmbH |
| Piab AB |
| Parker Hannifin Corporation |
| Ingersoll Rand |
| Atlas Copco AB |
| Graham Corporation |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation leak-tight mandates gate qualified supply for stainless steel ejector configurations, restricting premium-tier pricing access to fabricators with certified foundry partnerships and predictive maintenance telemetry capabilities. German chemical majors and Indian petrochemical operators now demand ten-year total cost of ownership guarantees, compressing margin predictability for commodity-grade suppliers while rewarding integrated service bundling.
Pricing Analysis
Input-cost pass-through from nickel and molybdenum volatility in stainless steel feedstocks dominates ejector pricing dynamics. Three-tier pricing structure across premium corrosion-resistant alloys, standard stainless configurations, and cast iron economy units separates chemical processing procurement from general industrial vacuum duties. Cost compression in standard alloy tiers is intensifying because mechanical vacuum pump substitution captures mid-range applications below 50 mbar. Fluid transport and pneumatic conveying segments exhibit highest price sensitivity; sulfur recovery and pharmaceutical lyophilization buyers prioritize certified cleanability over unit cost.
Supply Chain Analysis
Workforce availability for precision casting of venturi throats concentrates in German and Japanese supplier networks, creating single-source vulnerability for multi-stage ejector geometries. Manufacturing draws from stainless steel feedstock mills in Germany, Japan, and South Korea, with Hastelloy and duplex alloy dependencies anchored in specialty metal foundries. Nickel and molybdenum commodity price volatility presents persistent supply chain risk. Distribution runs through integrated chemical major procurement teams and OEM pneumatic system bundlers rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air jet ejectors market functions as a regulatory compounder where EPA New Source Performance Standards and EU F-Gas Regulation retrofits create sustained demand visibility for corrosion-resistant vacuum architectures.
For Market Incumbents: Cement foundry partnerships for precision-cast venturi throats in German and Japanese supplier networks to defend against additive manufacturing disruption. Deepen backward integration into stainless steel alloy sourcing to buffer nickel and molybdenum price volatility. Lock ten-year predictive maintenance telemetry contracts with Indian chemical corridor greenfield projects before specification standards crystallize.
For New Entrants and Emerging Players: Enter via modular skid packaging for sulfur recovery unit retrofits where project engineering talent scarcity extends vendor qualification cycles. Target Gujarat and Maharashtra state industrial zones in India where stricter emissions baselines than legacy European installations create specification upgrade windows. Lead with computational fluid dynamics-optimized nozzle geometries as a technical wedge against established steam consumption benchmarks.
For Investors and Strategic Acquirers: Roll-up economics work for European precision vacuum specialists because buyer consolidation among integrated chemical majors compresses vendor lists and rewards scale in aftermarket service bundling. Five-to-ten year viability hinges on regulatory enforcement continuity for leak-tight mandates. Watch EPA enforcement intensity on refinery flare system vapor recovery upgrades as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Foundries | Captive supply of Hastelloy venturi throats buffers nickel price volatility for German chemical corridor contracts. |
| Predictive Maintenance Telemetry Integration | Embedded differential pressure sensing enables ISO 5167-compliant condition-based service contracts with Indian petrochemical operators. |
| Additive Manufacturing of Venturi Geometries | Topology-optimized flow patterns collapse lead times for custom pressure-ratio configurations in sulfur recovery retrofits. |
| Joint Venture with East Asian Pneumatic Distributors | Channel access to semiconductor fabrication clusters in South Korea and Taiwan accelerates multi-stage ejector placement. |
| Green Manufacturing Transition for CIP/SIP Validation | Surface finishes below 0.8 micrometers Ra unlock pharmaceutical lyophilization demand with FDA-validated cleanability protocols. |
Research Methodology
Bottom-up chemical processing and oil and gas operator modeling reconciled against top-down pneumatic component supply tracking forms the analytical core. Primary interviews with plant engineers, procurement leads at integrated chemical majors, aftermarket service heads, and CFD simulation specialists combined with secondary validation from SEC filings, customs and trade data, ACC and Cefic industry reports, and EPA regulatory dockets. Triangulation across these sources calibrated installation base estimates and replacement cycle assumptions.
Input-output matrix framing connects motive steam consumption benchmarks, stage configuration economics, and alloy specification tiers to end-use demand across the projection horizon. Segmentation dimensions modeled include product type, application intensity, end-user industry, and installation architecture, with regional regulatory cluster effects layered across geographic production hubs. CAGRs derived from regression against historical retrofit cycles and policy enforcement trajectories. Forecast inputs incorporate semiconductor fabrication capacity announcements and refinery flare system compliance deadlines.
Inputs from plant engineer interviews and customs trade databases were available through the study window; gaps in real-time nickel and molybdenum spot price correlation with contract pricing introduce uncertainty bands around alloy cost pass-through assumptions. Forecasts reflect documented regulatory enforcement intensity and capital expenditure commitment patterns. Material deviation in EPA enforcement actions or EU F-Gas Regulation amendment timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Float Traps Market
Valves
Curb Valves Market
Valves
Flow Computer Market
Valves
Liner Regulators Market
Valves
India Industrial Valves Market
Valves
Steam Trap Valve Market
Valves
Safety Valve Test Benches Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Steam Safety Valve Market
Valves
North America Valves Market
Valves
Global Valves Market
Valves
Pressure Reducing Valve Market
Valves
Naval Actuators and Valves Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Rising Stem Ball Valve Market
Valves
Sliding Sleeves Market