
 Europe Tire Market | 2026-2036
Europe Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tire Market Intelligence
Fleet operator consolidation across Central Europe is expanding the bargaining power of large commercial buyers in the replacement tire channel. Michelin leverages its premium positioning and European manufacturing footprint to sustain margins in the high-performance segment. Continental AG anchors its competitive stance through deep integration with German OEM supply chains and advanced material science capabilities.
A tire is a toroidal flexible membrane of reinforced rubber composites, typically comprising natural and synthetic rubber, carbon black, steel cord, and textile ply, engineered to transmit vehicle loads, absorb road shocks, and maintain traction across varied surface conditions. Radial construction dominates value generation due to superior fuel efficiency and durability demands from fleet operators, while tubeless technology captures expanding share as safety regulations tighten and wheel assembly designs evolve. The aftermarket retailer channel retains structural importance as vehicle age profiles lengthen across Southern and Eastern Europe, though online distribution is gaining ground in replacement purchases for passenger car applications.
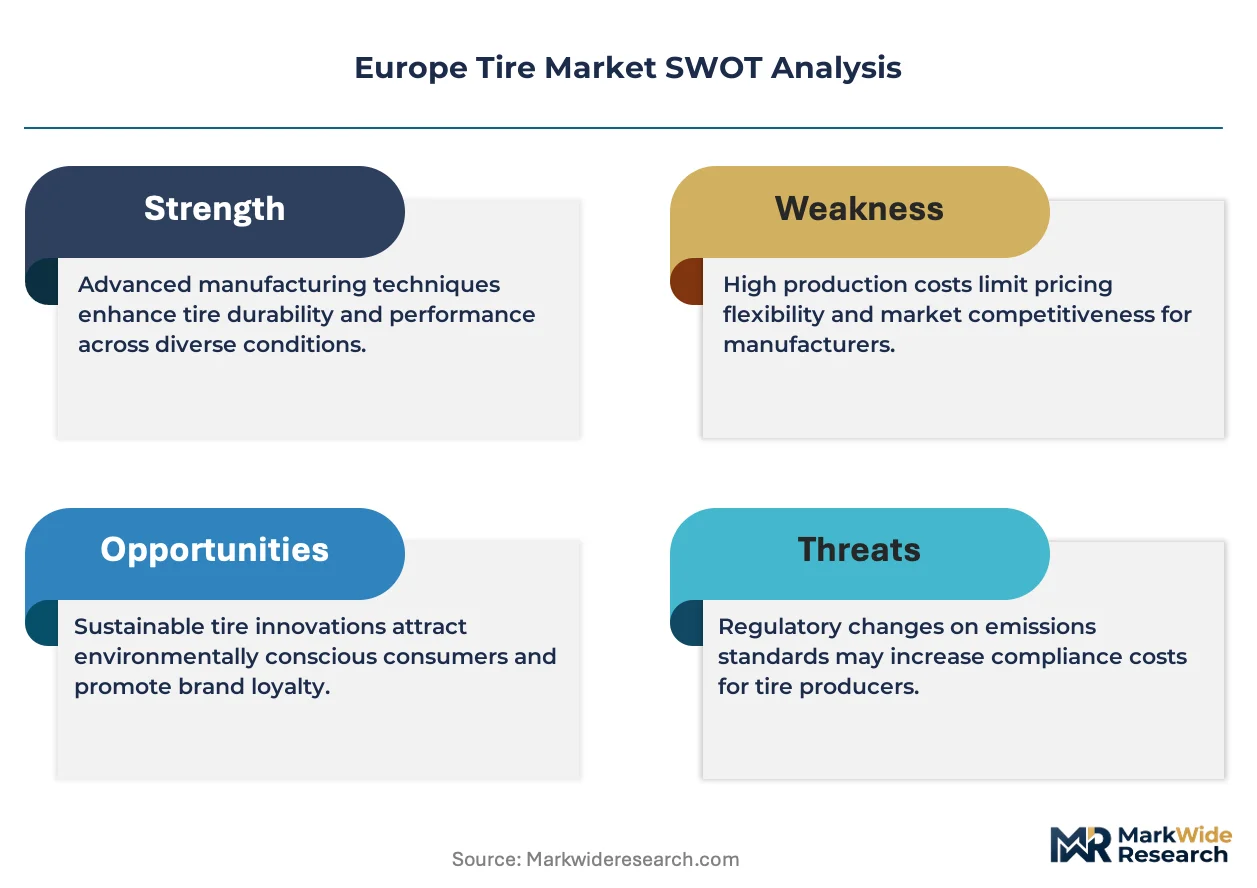
REACH compliance through ECHA mandates chemical disclosure and restriction protocols that elevate formulation costs for tire manufacturers serving European markets. The EU Green Deal and associated carbon-border mechanisms are pressuring producers to demonstrate lifecycle emissions reductions in raw material sourcing and manufacturing processes. Stakeholders must monitor regulatory calibration around end-of-life tire recycling quotas and embedded carbon thresholds, as these standards will determine facility investment viability and import competitiveness across the continent.
Market Dynamics
EU F-Gas Regulation and REACH compliance mandates are forcing reformulation of rubber compounds across European tire manufacturing, elevating input costs while creating competitive separation between integrated compounders and import-dependent assemblers.
Growth Catalysts
- Fleet utilization expansion:Logistics operators across Germany and France are extending vehicle duty cycles, accelerating replacement tire procurement in the commercial vehicle channel.
- REACH chemical disclosure protocols:ECHA mandates are consolidating supplier relationships toward compounders with certified sustainable sourcing capabilities.
- Tubeless safety adoption:Wheel assembly redesigns in premium passenger vehicles are displacing tubed configurations across OEM fitments.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions transmit directly into European manufacturing cost structures without hedging alternatives.
- Carbon black import concentration:Russian-origin feedstock displacement has tightened specialized filler supply for high-performance tread compounds.
- End-of-life recycling quota complexity:Divergent national implementation of EU tire recovery targets fragments compliance obligations across member states.
Strategic Opportunities
- Eastern European aftermarket penetration:Poland and Romania exhibit extended vehicle age profiles with underdeveloped replacement tire distribution infrastructure.
- Retreading technology convergence:Cold-cure bonding systems combined with laser tread inspection are enabling premium segment re-entry for commercial casings.
- EU Green Deal carbon-border alignment:Embedded emissions certification for imported tires creates first-mover advantage for low-carbon manufacturing investments.
Industry Challenges
- Compound formulation talent scarcity:Polymer science expertise for sustainable rubber alternatives is concentrating among legacy German and Italian research centers.
- Multi-standard certification timelines:Simultaneous EU tire labeling, UN ECE R117, and national winter tire mandates extend product approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tire Market |
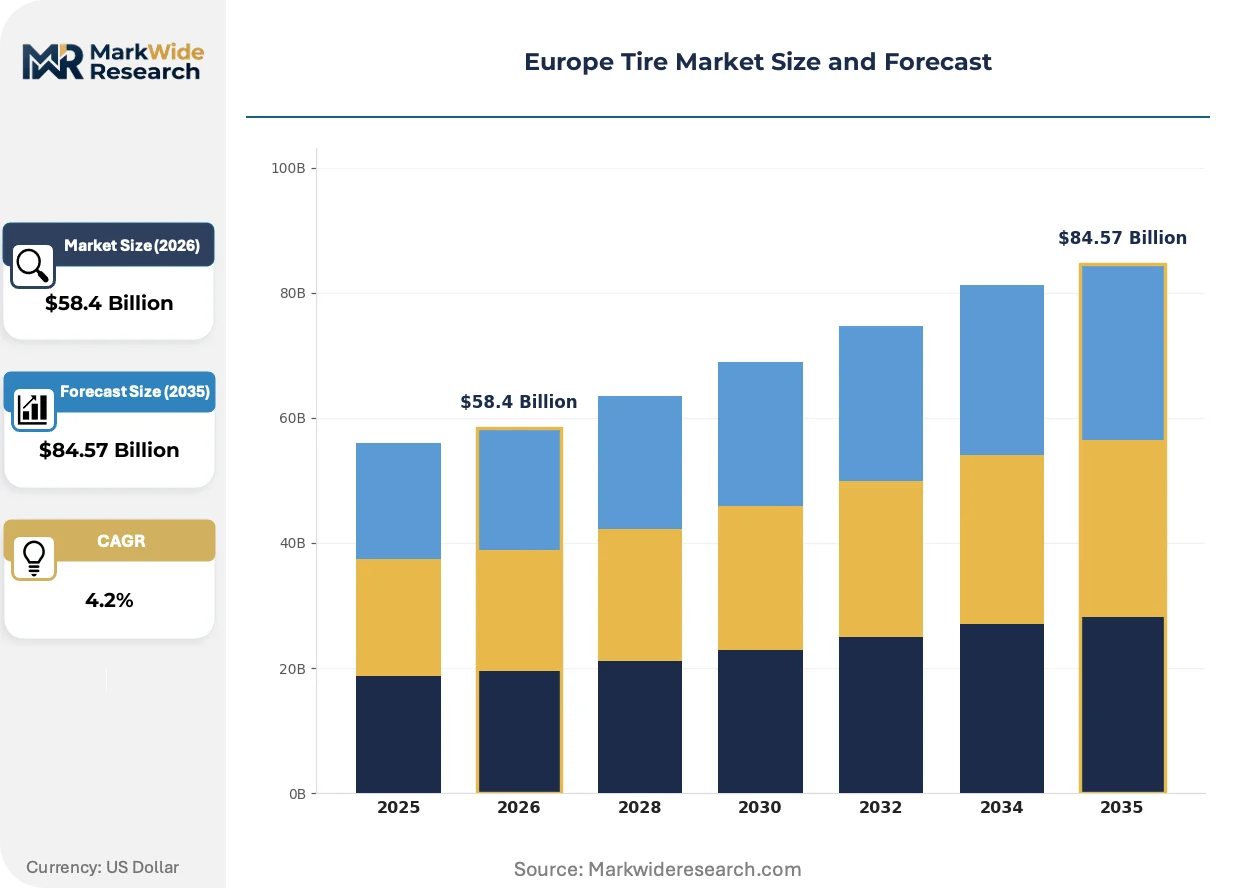
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $84.57 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Car, Light Truck, Heavy Truck, Bus Technology: Radial, Bias, Tubeless, Run-flat End User: OEMs, Aftermarket Retailers, Fleet Management, Service Centers Distribution Channel: Online, Dealerships, Retail Outlets, Wholesalers |
| Companies Covered | Goodyear Tire & Rubber Company, Yokohama Rubber Company Limited, Michelin, Hankook Tire & Technology Co., Ltd., Toyo Tires, Continental AG, Pirelli & C. S.p.A., Nitto Tires, Bridgestone Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tire Market Strategic Shifts & Innovations
Digital manufacturing integration and sustainable material substitution are compressing development cycles while redefining performance benchmarking across European tire value chains.
Intelligent tire sensor systems embedded within tread cavities are automating pressure and temperature monitoring for fleet operators. Commercial vehicle buyers in Germany and the Netherlands are specifying these systems in procurement tenders. The technology is automating predictive maintenance scheduling and reducing roadside failure incidents for long-haul operators.
EU F-Gas Regulation phase-down schedules are accelerating synthetic rubber process modifications. Manufacturers serving European markets must demonstrate alternative blowing agent adoption in foam component production. Premium passenger tire segments face compressed timelines for compound requalification ahead of 2027 restriction milestones.
Fleet procurement consolidation is concentrating buying power among Central European logistics groups. Traditional distributor networks are losing volume to direct manufacturer agreements with terms spanning multi-year replacement cycles. This concentration is most visible across Germany's Rhine-Ruhr industrial corridor where operator scale permits customized compound specifications.
Europe Tire Market Segmentation
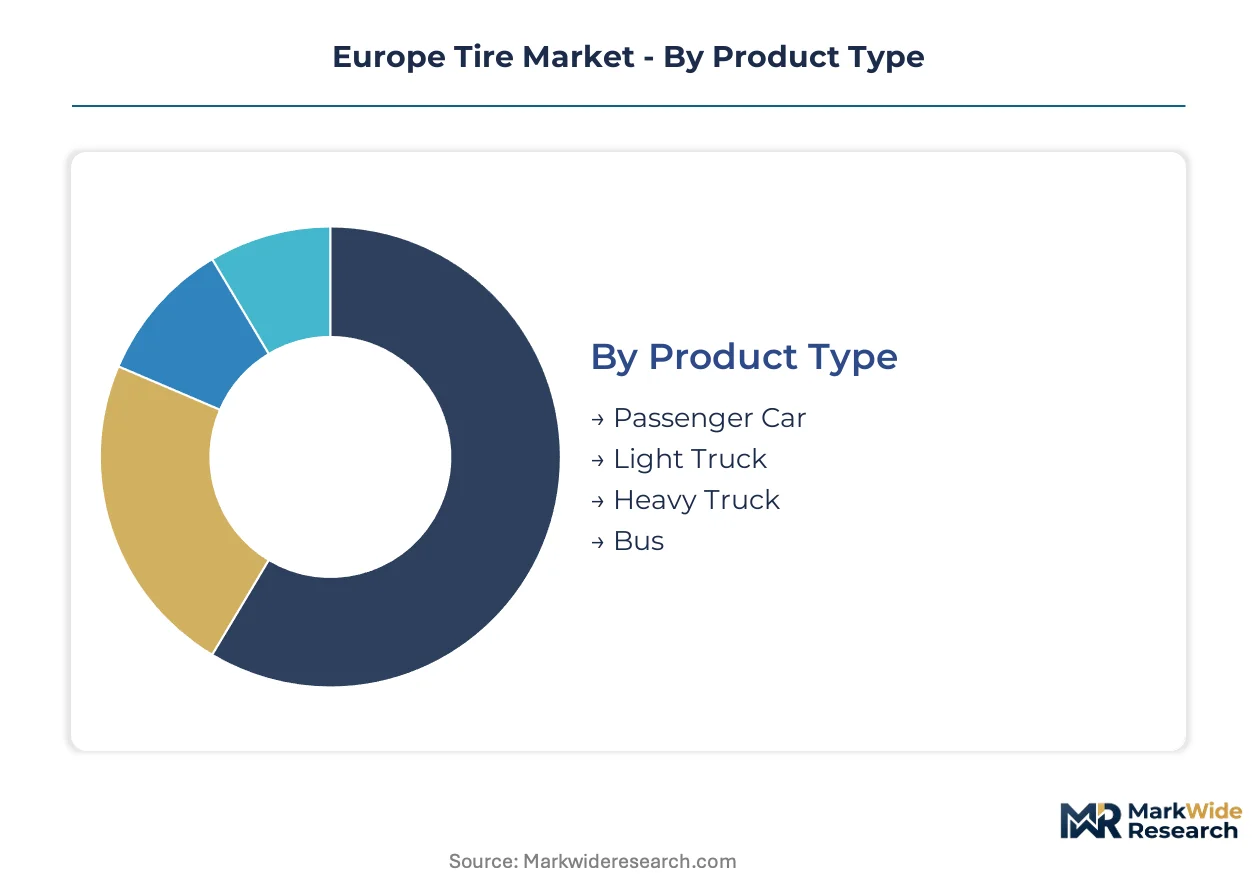
Tire segmentation across Europe reflects divergent technical specifications between vehicle classes and the regulatory pressures reshaping compound chemistry. Fleet procurement consolidation and REACH compliance mandates are compressing the supplier base within each category toward integrated manufacturers with certified sustainable sourcing capabilities.
Product Type:
Construction specifications and load-bearing requirements differentiate tire architectures across vehicle weight classes, with radial reinforcement dominating commercial applications.
- Passenger Car:Low-profile sidewall designs with silica-enhanced tread compounds optimize rolling resistance for fuel efficiency mandates. Demand concentrates in Germany's premium vehicle manufacturing corridor where OEM fitment specifications drive replacement patterns.
- Heavy Truck:Multi-ply steel belt construction supports axle loads exceeding 11.5 tonnes with retreadable casings extending service life. Fleet operators across France and Poland specify these for long-haul routes with predictive maintenance integration.
- Light Truck:Reinforced sidewall ratings accommodate mixed commercial-personal duty cycles common in Southern European markets.
- Bus:Urban stop-start tread patterns with enhanced heat dissipation serve municipal transit authorities under extended warranty terms.
Mature deployment sits with Passenger Car. Newer deployment is concentrated in Heavy Truck as fleet telematics enable usage-based replacement scheduling.
Technology:
Manufacturing process differentiation separates molded radial architectures from legacy bias-ply construction, with safety regulations accelerating tubeless adoption.
- Radial:Steel belt angles of 90 degrees to the direction of travel reduce heat buildup and extend tread life. German logistics corridors sustain above-average penetration as fleet fuel economy targets harden.
- Tubeless:Elimination of inner tubes through airtight bead-seat interfaces reduces weight and failure modes. Regulatory pressure from UN ECE R117 is displacing tubed configurations in premium passenger fitments.
- Bias:Cross-ply nylon cord construction retains niche presence in specialized agricultural and off-highway equipment serving Eastern European farming cooperatives.
- Run-flat:Reinforced sidewall inserts permit limited-distance operation at zero inflation pressure. Urban premium vehicle segments in Benelux markets specify these for safety-critical applications.
Radial technology commands the established installed base. Run-flat configurations are climbing the fastest among safety-specified urban fleet renewals.
End User:
Procurement scale and technical specification authority separate direct OEM relationships from fragmented aftermarket channels.
- OEMs:Original equipment fitments require compound qualification against vehicle-specific NVH and handling targets. German automotive manufacturers anchor regional demand through just-in-sequence supply agreements.
- Fleet Management:Centralized procurement of replacement tires across pooled vehicle assets leverages volume for customized service terms. Rhine-Ruhr logistics operators are consolidating supplier relationships toward multi-year framework contracts.
- Aftermarket Retailers:Independent distribution networks serve aged vehicle parc in Southern and Eastern Europe with price-tiered inventory.
- Service Centers:Installation-focused operations capture replacement demand through convenience positioning and alignment service bundling.
Fleet Management is gaining procurement concentration. Aftermarket Retailers retain structural importance in extending vehicle life markets.
Distribution Channel:
Channel economics reflect inventory carrying costs against customer acquisition efficiency across digital and physical touchpoints.
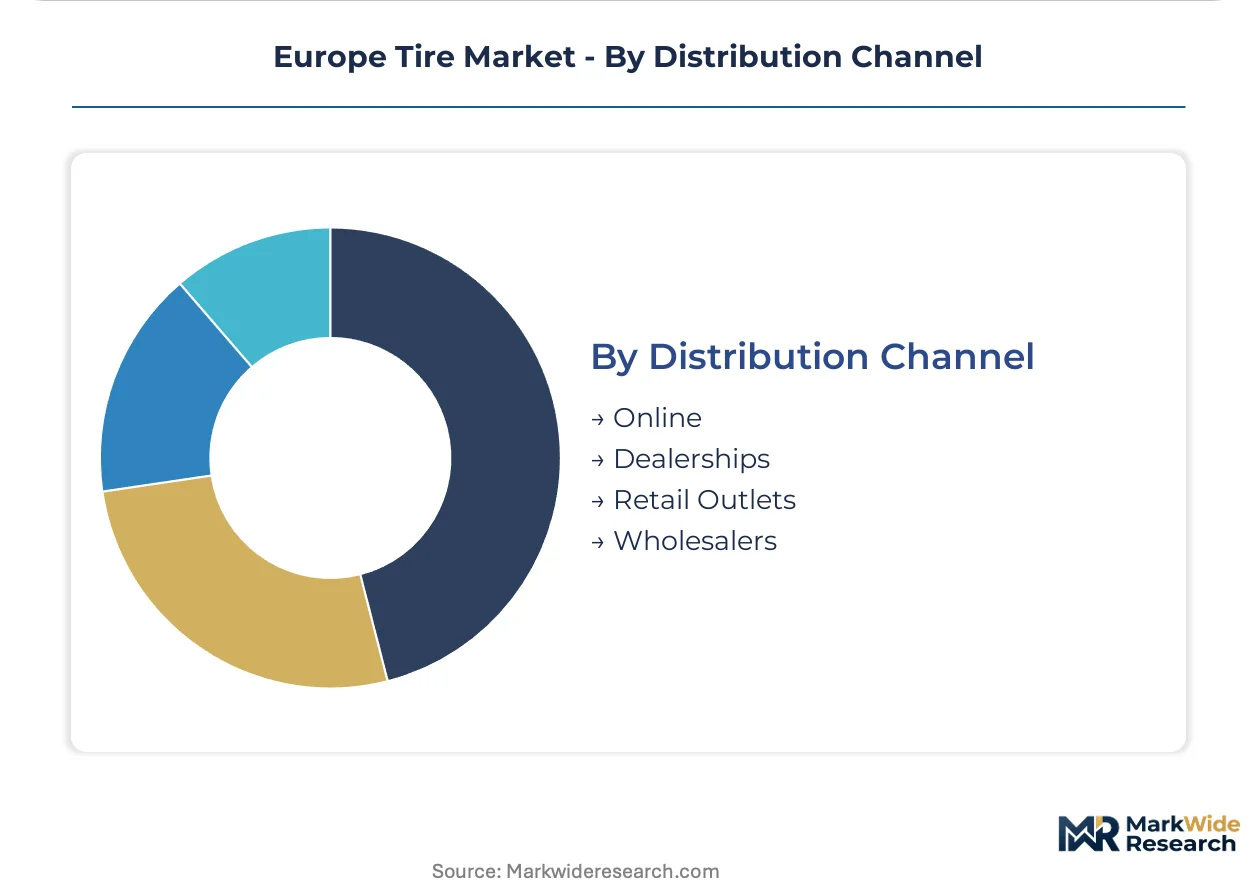
- Wholesalers:Regional distribution hubs aggregate volume from multiple manufacturers for downstream retailer fulfillment. Poland's developing replacement infrastructure depends on these intermediaries for inventory depth.
- Online:Direct-to-consumer platforms with fitment verification tools are displacing traditional search costs in passenger car replacement. Netherlands and UK markets show highest digital penetration among EU member states.
- Dealerships:Captive distribution tied to vehicle sales channels captures premium segment replacement at point of service.
- Retail Outlets:Physical presence with installation capability serves immediate replacement needs and seasonal changeover demand.
Wholesalers anchor commercial vehicle supply chains. Online channels are expanding most quickly in price-transparent passenger segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for replacement tires concentrates along Germany's industrial corridor and France's logistics networks, where fleet utilization rates drive above-average procurement volumes. Regulatory pressure from the EU Green Deal and F-Gas Regulation is reshaping manufacturing investments across the continent.
Germany
Rhine-Ruhr logistics operators and Bavarian premium vehicle manufacturers anchor regional tire consumption through fleet renewal programs and OEM fitment specifications. KBA enforcement of UN ECE R117 safety standards accelerates tubeless adoption in commercial vehicle registrations. Continental AG's Hanover research complex anchors advanced compound development for low-rolling-resistance tread formulations.
France
Paris Basin freight corridors and Lyon-anchored distribution networks sustain heavy-truck replacement demand amid extended vehicle duty cycles. REACH compliance through ECHA mandates chemical disclosure protocols that elevate formulation costs for domestic compounders. Auvergne-Rhône-Alpes hosts Michelin's Clermont-Ferrand innovation campus, where sustainable rubber alternatives undergo accelerated testing.
Italy
Emilia-Romagna's automotive supplier cluster and Lombardy-based commercial fleets generate above-average premium tire demand for performance vehicles. EU tire labeling requirements enforce rolling resistance and wet grip disclosure, compressing product approval timelines for Turin-area manufacturers. Pirelli's Milan headquarters coordinates compound qualification for European motorsport applications.
Poland
Extended vehicle age profiles and underdeveloped replacement infrastructure create aftermarket expansion opportunities across Silesian industrial zones and Warsaw logistics corridors. Divergent national implementation of EU tire recovery targets fragments compliance obligations for Polish distributors. Krakow-based wholesalers aggregate inventory for Eastern European retailer fulfillment.
Netherlands
Rotterdam port logistics and Amsterdam metropolitan fleet operators specify intelligent tire monitoring systems in procurement tenders. Digital distribution platforms with fitment verification tools achieve highest penetration rates among EU member states here. Eindhoven's automotive technology cluster supports sensor integration for predictive maintenance applications.
Europe Tire Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue retreading technology and sustainable material niches. The European tire market exhibits consolidated structure among integrated compounders with certified REACH compliance, while import-dependent assemblers face margin compression from reformulation costs. Three archetypes dominate: legacy manufacturers with deep OEM supply chain integration, specialists in commercial vehicle retreading systems, and Asian exporters leveraging cost-positioned radial production. Competitive moves center on multi-year fleet framework contracts and carbon-border alignment through embedded emissions certification.
Among premium-tier European manufacturers, Continental AG and Michelin exemplify integrated compounders with advanced material science capabilities and sustainable sourcing certifications. Yokohama Rubber Company Limited represents the Asian export archetype, occupying a position in performance-oriented replacement segments. Bridgestone Corporation anchors a hybrid posture across OEM fitment and aftermarket retail channels. These three entities collectively illustrate the competitive tension between regional manufacturing depth and global scale economies.
| Leading Market Players |
|---|
| Goodyear Tire & Rubber Company |
| Yokohama Rubber Company Limited |
| Michelin |
| Hankook Tire & Technology Co., Ltd. |
| Toyo Tires |
| Continental AG |
| Pirelli & C. S.p.A. |
| Nitto Tires |
| Bridgestone Corporation |
| Others |
Cost & Logistics Intelligence
Natural rubber futures traded on the Singapore Exchange cascade through European compounder cost structures into three distinct pricing tiers segmented by sustainability certification and OEM qualification status. REACH compliance investments and carbon-border adjustment exposure widen spreads between integrated manufacturers and import-dependent assemblers sourcing from Southeast Asian traders.
Pricing Analysis
Volume-margins split sharply between fleet framework contracts capturing multi-year replacement cycles at compressed terms and premium OEM fitments sustaining compounder margins through technical specification barriers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by ECHA certification tier, embedded carbon documentation, and predictive maintenance bundling. Price erosion runs through the economy import tier as Russian-origin carbon black displacement tightens specialized filler supply. Fleet procurement officers exhibit highest price sensitivity, while German premium vehicle manufacturers prioritize rolling resistance performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Gdansk anchor hub-and-spoke fulfillment patterns for replacement tire inventory across Northern and Eastern European markets. Manufacturing concentration centers on Germany, France, and Italy for integrated compounders with in-house mixing capabilities, while Poland and Romania host assembly-dependent operations drawing from Asian masterbatch suppliers. Raw material dependencies rest on Southeast Asian natural rubber plantations, Russian-origin carbon black feedstock alternatives, and steel cord from German and Belgian metallurgical plants. Single-source vulnerability in specialized silica grades for low-rolling-resistance compounds poses structural risk. Distribution runs through wholesaler networks for commercial vehicle channels and direct-to-fleet agreements bypassing traditional retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH reformulation mandates and carbon-border compliance costs are forcing consolidation among compounders lacking certified sustainable sourcing capabilities, eliminating margin-constrained import assemblers from contested fleet procurement tenders.
For Market Incumbents: Anchor defensive positioning through backward integration into certified natural rubber sourcing and captive carbon black production to offset feedstock volatility. Deepen OEM supply chain integration via just-in-sequence compound qualification for premium vehicle platforms. Prioritize multi-year framework contracts with Rhine-Ruhr logistics operators to lock replacement volume against retreading technology entrants. For New Entrants and Emerging Players: Cold-cure retreading systems with laser tread inspection offer technology-first wedge into the commercial vehicle aftermarket, targeting Poland and Romania where extended vehicle age profiles and underdeveloped distribution infrastructure create white-space opportunity. Pursue direct fleet relationships bypassing wholesaler networks. Emphasize embedded carbon certification to exploit EU Green Deal alignment preferences in German procurement tenders. For Investors and Strategic Acquirers: The window for entry favors integrated compounders with REACH-certified sourcing and established OEM qualification pipelines over import-dependent assembly operations. Long-term viability hinges on manufacturing footprint flexibility across Eastern European expansion markets and low-carbon process investments. Monitor ECHA calibration of end-of-life tire recycling quotas as inflection indicator for facility investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Rubber Sourcing | Captive supply of FSC-certified natural rubber insulates Continental AG and Michelin from Singapore Exchange price volatility. |
| Carbon Border Alignment Certification | Embedded emissions documentation for imported tires creates competitive separation under EU Green Deal implementation. |
| Intelligent Tire Sensor Integration | Predictive maintenance platforms specified by Rotterdam port operators automate fleet procurement renewal cycles. |
| Cold-Cure Retreading Technology Deployment | Laser inspection systems enable premium segment re-entry for commercial casings in Poland's developing aftermarket. |
| Multi-Year Fleet Framework Contracts | Rhine-Ruhr logistics operators consolidate supplier relationships toward customized compound specifications. |
Research Approach
Multi-period observation of Singapore Exchange natural rubber futures, EU carbon border adjustment mechanism implementation timelines, and fleet utilization rates across Germany and France anchored the trend analysis, supplemented by interviews with tire compounder procurement directors, ECHA regulatory affairs specialists, fleet maintenance managers at Rhine-Ruhr logistics operators, and aftermarket wholesaler executives in Poland. Secondary validation drew from KBA vehicle registration databases, ECHA REACH substance dossiers, EU tire labeling compliance records, and customs trade data for carbon black and natural rubber imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches modeled vehicle class, propulsion architecture, tire construction technology, and distribution channel dynamics throughout the forecast period. CAGRs derived from regression analysis of historical replacement rates against fleet age profiles and OEM production schedules. Industry-specific inputs incorporated EU F-Gas Regulation phase-down timelines for synthetic rubber process modifications and ECHA chemical restriction protocols affecting compound formulation costs.
Several conditions sit outside the modeled scope, including geopolitical disruption of Southeast Asian natural rubber supply, abrupt tariff reconfiguration affecting carbon black feedstock trade flows, and unilateral national deviations from EU tire recovery target implementation. Forecasts reflect documented assumptions around regulatory calibration and commodity price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Wheel Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
Steel Tire Cord Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Saudi Arabia Tire Market