
 Steel Tire Cord Market | 2026-2036
Steel Tire Cord Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Tire Cord Market Analytics
China is reconfiguring steel tire cord supply dynamics through massive domestic capacity additions across Jiangsu and Shandong provinces. N.V. Bekaert S.A. anchors European technology standards with proprietary brass-coating expertise. Henan Hengxing Science & Technology Co., Ltd. dominates domestic Chinese supply through integrated wire rod-to-cord operations. Hyosung Corporation positions its Southeast Asian plants to serve Japanese and Korean tire makers seeking geographic diversification.
Steel tire cord consists of high-tensile steel filaments, typically 0.15–0.38 mm in diameter, brass-plated for rubber adhesion and twisted into multi-wire structures that reinforce tire carcasses and belts under cyclic loading. Cord wire commands the largest volume share as radial tire architectures require layered belt packages for structural integrity. High carbon steel leads material demand due to its optimal strength-to-cost ratio for standard passenger and commercial tires, while coated steel variants gain traction in specialty applications requiring enhanced corrosion resistance.
REACH and RoHS frameworks in Europe restrict hazardous substance use in steel processing chemicals, pushing mills toward cleaner surface-treatment chemistries. China's GB standards and MIIT industrial policies enforce minimum tensile grades and energy-efficiency benchmarks at domestic steel cord plants. Tire manufacturers must monitor evolving EPA vehicle-emission rules in the United States, as lighter tire constructions directly influence fleet compliance calculations and steel cord specification requirements.
Market Dynamics
Radial tire architectures now dominate passenger and commercial vehicle specifications, compressing demand for bias-ply alternatives and concentrating steel cord procurement around high-tensile, brass-coated constructions that withstand cyclic belt loading. This structural shift is reconfiguring supplier qualification requirements and mill investment priorities across the value chain.
Growth Catalysts
- EU Green Deal vehicle-emission targets:Lighter tire constructions reduce rolling resistance and fleet CO2 footprints, pushing OEMs toward advanced steel cord specifications that cut mass without sacrificing durability.
- Electric vehicle platform proliferation:Battery-electric architectures impose higher static loads on tires, accelerating specification upgrades to ultra-high-tensile steel cord grades in premium segments.
- Jiangsu and Shandong capacity clusters:Integrated wire rod-to-cord operations in these provinces are compressing regional supply costs and capturing domestic tire maker procurement.
Market Restraints
- Scrap steel and ferroalloy volatility:Input cost swings for high-carbon wire rod feedstock compress margin predictability at cord drawing operations, particularly for non-integrated producers.
- REACH surface-treatment compliance:ECHA restrictions on traditional brass-coating chemistries force capital-intensive conversion to cleaner adhesion systems, raising fixed cost thresholds for European mills.
- Aramid and hybrid reinforcement substitution:Advanced polymer composites penetrate aircraft and select premium automotive segments where weight reduction outweighs steel's cost advantage.
Strategic Opportunities
- India PLI scheme for auto components:Domestic tire manufacturing incentives are attracting steel cord investment toward Gujarat and Tamil Nadu industrial corridors to serve localized OEM supply chains.
- Smart tire sensor integration:Steel cord architectures that accommodate embedded pressure and temperature monitoring electronics open aftermarket service revenue streams for tire makers.
- Recyclable mono-material belt packages:Single-steel-composition tire constructions simplify end-of-life processing and align with emerging extended producer responsibility frameworks in Europe.
Industry Challenges
- Metallurgical talent scarcity:Specialized wire drawing and heat treatment expertise is concentrating at legacy European and East Asian facilities, constraining new plant ramp speeds elsewhere.
- Multi-jurisdiction certification timelines:Simultaneous homologation against GB standards, ECE regulations, and DOT requirements extends product launch cycles for global tire platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Tire Cord Market |
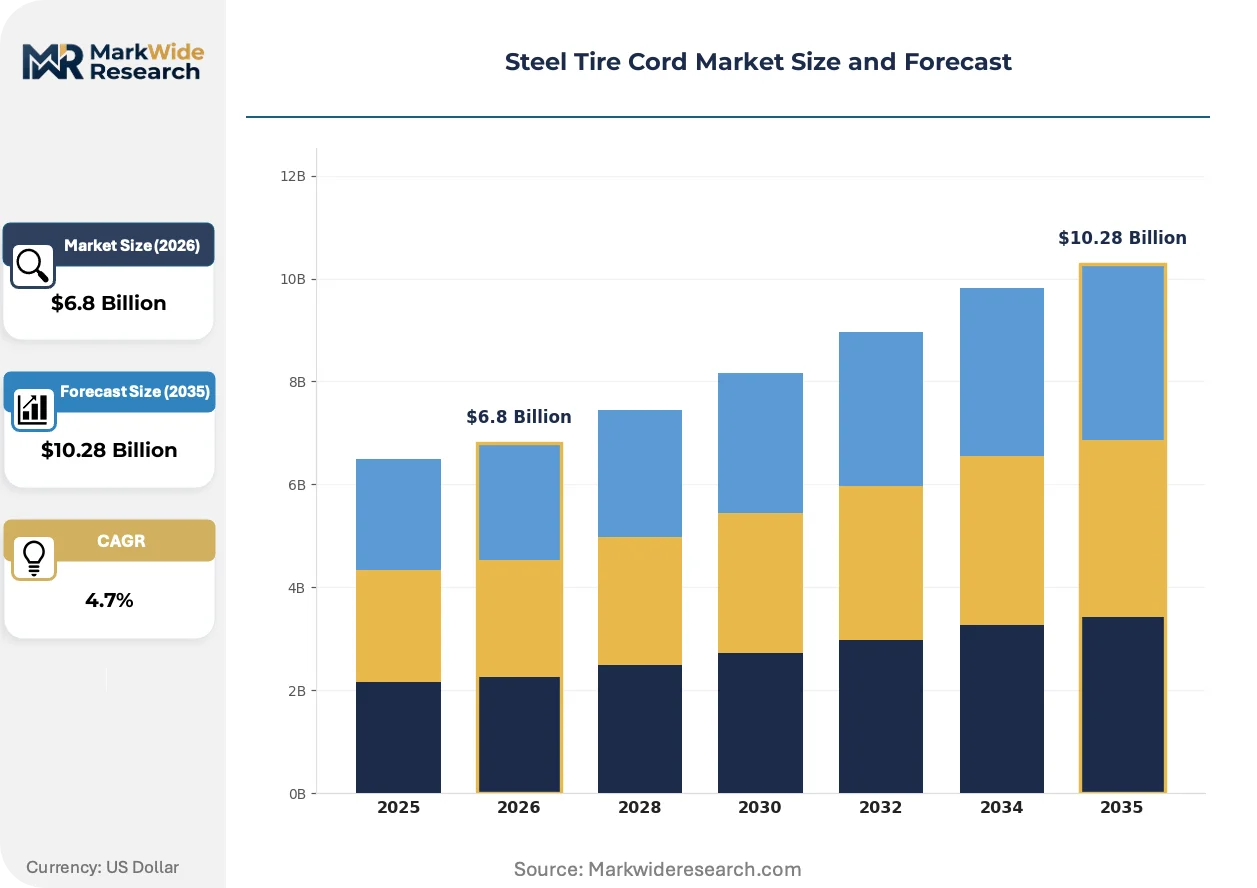
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bead Wire, Cord Wire, Braided Wire, Stranded Wire Application: Passenger Tires, Truck Tires, Bus Tires, Specialty Tires Material: High Carbon Steel, Stainless Steel, Alloy Steel, Coated Steel End User: Tire Manufacturers, Automotive Industry, Aerospace Industry, Others |
| Companies Covered | Tokusen Kogyo Co., Ltd., Henan Hengxing Science & Technology Co., Ltd., N.V. Bekaert S.A., Tokyo Rope Mfg. Co., Ltd., Shougang Century Holdings Limited, Hyosung Corporation, ArcelorMittal S.A., Jiangsu Xingda Steel Tyre Cord Co., Ltd., Sumitomo Electric Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Tire Cord Market Evolving Landscape
Digital process control and advanced materials engineering are converging to transform steel cord manufacturing from commodity production toward precision-specification supply. These developments are compressing defect rates, accelerating qualification cycles, and enabling mass customization at automotive OEM scale.
AI-driven defect detection is digitizing quality assurance across continuous wire drawing and stranding operations. Tire makers in Germany and Japan are mandating real-time surface anomaly monitoring as a supplier qualification condition. This capability is compressing lot rejection rates and reducing warranty exposure for belt package failures in high-speed applications.
REACH Annex XVII amendments are restricting hexavalent chromium in brass-coating baths, forcing mills toward trivalent alternatives and novel alloy formulations. European cord producers face 18-24 month conversion timelines for existing continuous plating lines. The regulatory pressure is accelerating R&D collaboration between steel mills and specialty chemical suppliers on cobalt-free adhesion systems.
Fleet operators are consolidating tire procurement through direct manufacturer contracts, bypassing traditional wholesale distribution. Large logistics companies in the United States and Germany now specify steel cord construction grades in their RFP documentation rather than delegating to distributor recommendations. This channel compression is forcing cord suppliers to develop direct technical service capabilities and transparent cost modeling for volume buyers.
Steel Tire Cord Market Segmentation
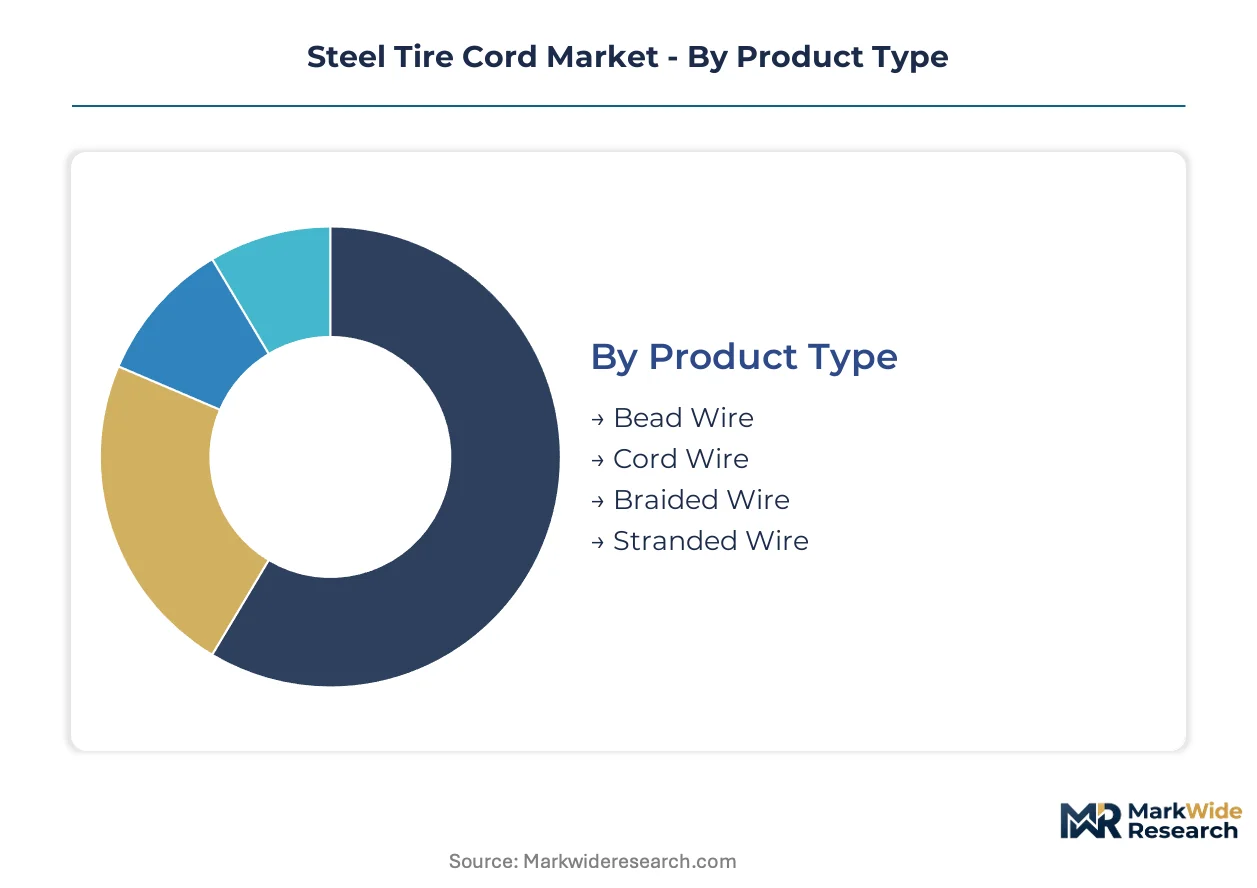
Steel tire cord procurement patterns diverge sharply across product specifications and end-use applications, with each segment demanding distinct metallurgical expertise and technical service intensity. Tire makers qualify suppliers separately for passenger, commercial, and specialty platforms, creating compartmentalized supply relationships that resist cross-selling.
Product Type:
After-sales technical support requirements vary dramatically across cord constructions, with complex multi-wire architectures demanding dedicated field engineering while simpler forms rely on standard quality documentation.
- Cord Wire:Multi-filament brass-coated constructions twisted into layered belt packages for radial tire architectures. Demand concentrates at radial tire plants in China and Southeast Asia where high-volume OEM contracts require continuous metallurgical support and rapid defect response protocols.
- Bead Wire:Heavy-gauge monofilament or simple-strand configurations anchoring tire beads to wheel rims. Truck and bus tire manufacturers in India and Brazil drive procurement, prioritizing tensile consistency over complex technical service given the product's structural simplicity.
- Braided Wire:Interlaced filament structures for specialty tire reinforcement. Motorsport and aircraft tire makers specify these for localized stress distribution.
- Stranded Wire:Concentric layer constructions offering intermediate properties between cord and braided forms. Mining and agricultural tire segments represent the primary demand pool.
By volume, Cord Wire leads. By growth pace, Bead Wire is ahead.
Application:
Cost tier differentiation separates commodity passenger tire supply from premium commercial and specialty segments, with specification stringency and qualification timelines expanding across the price spectrum.
- Passenger Tires:High-volume radial platforms for light vehicles. OEM supply chains in Germany, Japan, and South Korea dominate procurement, with ECE and DOT homologation requirements forcing extended supplier validation cycles and traceability systems.
- Truck Tires:Heavy-duty radial and select bias-ply constructions for freight vehicles. Demand clusters at fleet-direct procurement channels in the United States where rolling resistance specifications tie to EPA emission compliance calculations.
- Bus Tires:Urban transit and intercity coach applications with high duty cycles. Municipal procurement in Europe and state transport corporations in India shape regional demand patterns.
- Specialty Tires:Off-road, aircraft, and motorsport applications with extreme performance requirements. Aramid-steel hybrid constructions penetrate this tier where weight reduction justifies material cost premiums.
Passenger Tires commands the largest volume position. Specialty Tires expands most quickly as aircraft tire retrofits and electric vehicle performance variants accelerate specification upgrades.
Material:
Supply concentration for raw feedstock shapes procurement strategies, with integrated steel mills capturing high-carbon demand while specialty alloy and coated variants depend on external metallurgical partnerships.
- High Carbon Steel:0.72-0.82% carbon wire rod delivering optimal strength-to-cost ratios for standard reinforcement. Chinese integrated producers in Jiangsu and Shandong provinces dominate supply through captive wire rod-to-cord operations.
- Coated Steel:Brass, zinc, and novel alloy surface treatments for enhanced rubber adhesion and corrosion resistance. REACH Annex XVII compliance in Europe is accelerating trivalent chromium and cobalt-free formulation development.
- Stainless Steel:Corrosion-resistant austenitic and martensitic grades for extreme environment tires. Chemical processing and coastal mining vehicle applications drive niche demand.
- Alloy Steel:Chromium, manganese, or vanadium microalloying for ultra-high tensile grades. Premium electric vehicle tire platforms specify these for load-bearing capacity.
High Carbon Steel dominates volume throughput. Coated Steel gains share fastest as regulatory pressure and electric vehicle load requirements converge.
End User:
Customer type determines contract structure, with tire manufacturers demanding deep technical partnerships while downstream automotive and aerospace buyers delegate specification authority.
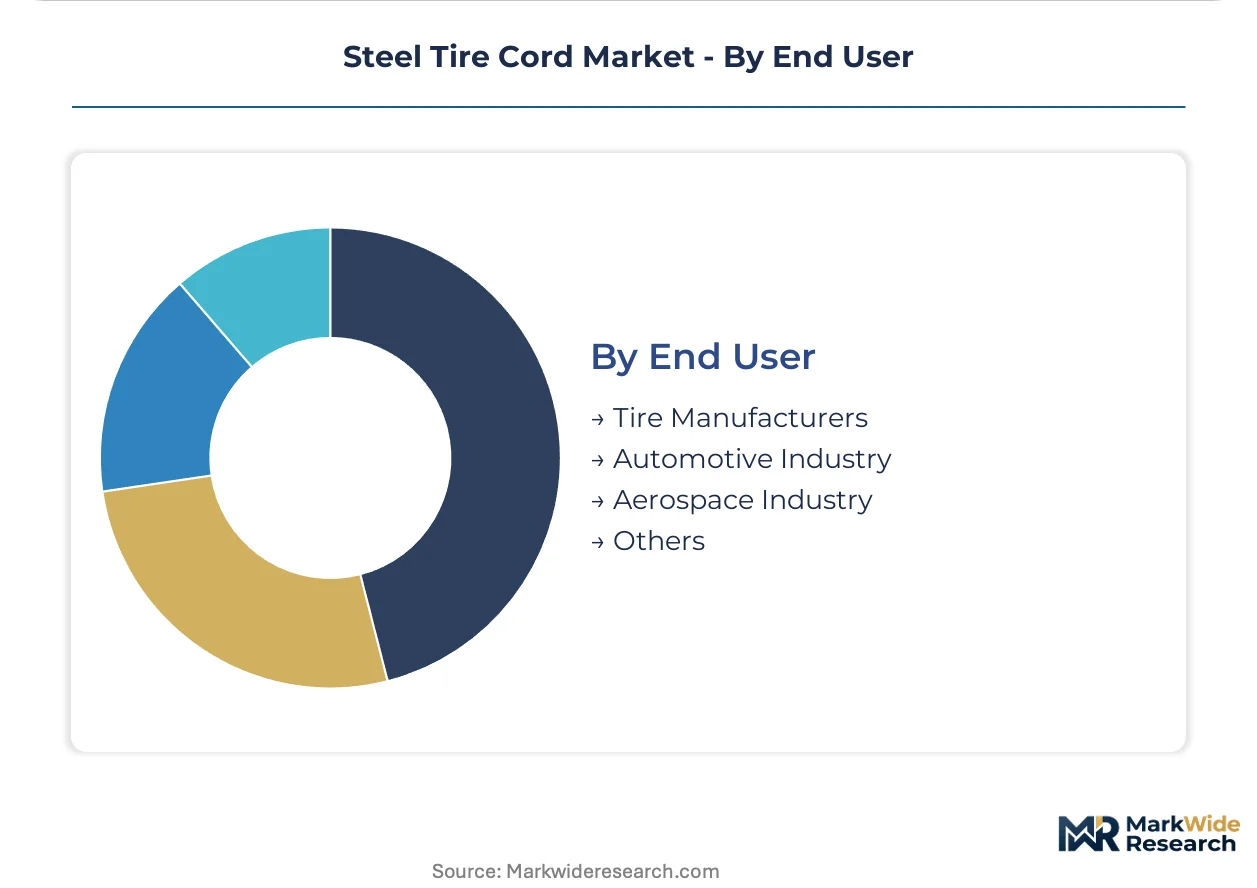
- Tire Manufacturers:Direct procurement of cord and bead wire for in-house tire construction. Michelin, Bridgestone, and Continental qualify suppliers through multi-year platform contracts with embedded volume commitments and joint R&D clauses.
- Automotive Industry:Vehicle OEMs specifying cord grades in tire supplier agreements. Ford and Volkswagen now mandate ultra-high-tensile constructions in electric vehicle platform documentation.
- Aerospace Industry:Aircraft tire OEMs and MRO channels sourcing specialty braided and alloy constructions. FAA and EASA certification requirements extend qualification timelines to 24-36 months.
- Others:Industrial conveyor belt, hose reinforcement, and cable applications repurposing tire-grade cord specifications. Mining equipment manufacturers represent the largest secondary demand pool.
Tire Manufacturers absorb the dominant volume share. Aerospace Industry shows the steepest expansion trajectory as post-pandemic fleet renewal accelerates and wide-body tire specifications upgrade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated wire rod-to-cord operations in Jiangsu and Shandong provinces concentrate the industry's supply base, while tire manufacturing clusters in Germany, Japan, and the United States drive specification standards. Regulatory divergence across REACH, GB standards, and EPA frameworks fragments qualification requirements. Regional demand patterns split between high-volume OEM procurement in Asia and premium performance segments in Europe and North America.
China
Domestic tire manufacturing capacity in Jiangsu and Shandong provinces absorbs the majority of regional steel cord output. MIIT industrial policies enforce minimum tensile grades and energy-efficiency benchmarks at steel cord plants, accelerating consolidation among non-integrated producers. Zhenjiang and Weihai industrial corridors host captive wire rod-to-cord facilities that compress supply costs for domestic tire makers.
Germany
OEM supply chains for premium passenger and electric vehicle platforms demand ultra-high-tensile steel cord grades with embedded traceability systems. EU Green Deal vehicle-emission targets push tire makers toward lighter belt constructions, directly influencing steel cord specification requirements. The Ruhr industrial region maintains specialized heat-treatment expertise, though REACH Annex XVII compliance costs pressure local plating operations.
United States
Fleet-direct procurement channels for truck tires now specify steel cord construction grades in RFP documentation, bypassing traditional distributor networks. EPA vehicle-emission rules tie lighter tire constructions to fleet compliance calculations, elevating technical dialogue between cord suppliers and volume buyers. Southeast industrial corridors attract wire drawing investment to serve localized OEM tire plants.
Japan
Premium tire platforms for domestic and export markets require real-time surface anomaly monitoring as a supplier qualification condition. METI standards coordinate with ECE regulations to extend homologation timelines for global tire platforms. Nagoya and Osaka industrial basins concentrate metallurgical expertise for ultra-high-tensile grades serving electric vehicle load requirements.
India
The PLI scheme for auto components attracts steel cord investment toward Gujarat and Tamil Nadu industrial corridors to serve localized OEM supply chains. BIS standards enforce tensile consistency requirements for truck and bus tire applications. Domestic tire manufacturing incentives compress import dependence for bead wire and standard cord constructions.
Steel Tire Cord Market Competitive Landscape
European technology specialists and Asian integrated producers split the market between premium specification supply and high-volume cost leadership. Three strategic archetypes occupy distinct competitive terrain: brass-coating technology leaders, captive wire rod-to-cord integrators, and regional scale specialists. Consolidation pressure concentrates among non-integrated drawing operations facing scrap steel volatility. Competitive moves center on backward integration into wire rod supply and geographic expansion toward tire manufacturing clusters.
Among European technology anchors, N.V. Bekaert S.A. exemplifies the brass-coating expertise archetype, while Henan Hengxing Science & Technology Co., Ltd. represents integrated wire rod-to-cord operations. Hyosung Corporation occupies a position within the regional scale specialist tier, positioning Southeast Asian capacity to serve Japanese and Korean tire maker procurement. These three company structures illustrate the competitive divergence between proprietary surface-treatment technology, captive upstream supply control, and geographic diversification strategies.
| Leading Market Players |
|---|
| Tokusen Kogyo Co., Ltd. |
| Henan Hengxing Science & Technology Co., Ltd. |
| N.V. Bekaert S.A. |
| Tokyo Rope Mfg. Co., Ltd. |
| Shougang Century Holdings Limited |
| Hyosung Corporation |
| ArcelorMittal S.A. |
| Jiangsu Xingda Steel Tyre Cord Co., Ltd. |
| Sumitomo Electric Industries, Ltd. |
| Others |
Value Network & Pricing Analysis
Overcapacity signals across Jiangsu and Shandong provinces are compressing regional pricing power while elevating fixed-cost absorption pressures for non-integrated European mills. This utilization imbalance concentrates procurement leverage with domestic Chinese tire manufacturers and accelerates margin divergence between captive wire rod-to-cord operators and standalone drawing facilities.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European steel cord supply, separating trivalent chromium-compliant premium grades from legacy hexavalent constructions facing conversion cost penalties. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales technical service bundling. Pricing pressure stems from scrap steel volatility compressing margin predictability at non-integrated producers. Fleet-direct procurement channels in the United States show least price sensitivity due to embedded EPA compliance value, while commodity bead wire buyers in India exhibit highest elasticity.
Supply Chain Analysis
Export-control restrictions on advanced heat-treatment furnace technology limit capacity expansion outside established European and East Asian supplier bases. Supply concentrates in China, Belgium, and Japan, with Jiangsu province hosting the largest integrated wire rod-to-cord footprint. Raw material flows draw from high-carbon wire rod, brass-coating chemicals, and specialized ferroalloys. Single-source vulnerability concentrates at legacy metallurgical expertise hubs in Germany and Japan. Distribution runs through direct technical service relationships between cord mills and tire manufacturer platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and embedded sensor integration layers are expanding faster than base cord hardware, transforming supplier economics toward recurring-revenue models. This service-attach dynamic favors operators with field engineering density and smart tire platform partnerships.
For Market Incumbents: Insulate brass-coating technology positions through accelerated trivalent chromium conversion and captive wire rod supply expansion in Southeast Asia. Aramid substitution in aircraft segments and cobalt-free adhesion system R&D gaps represent immediate threats. Backward integration into specialty alloy feedstock secures ultra-high-tensile grade qualification pipelines. For New Entrants and Emerging Players: Build out India PLI corridor capacity to capture localized OEM procurement migrating from Chinese import dependence. Gujarat and Tamil Nadu industrial zones offer the most penetrable white space. Technical partnership with domestic tire makers on BIS certification acceleration provides the critical go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across REACH-compliant European plating operations due to 18-24 month conversion timelines. Long-term viability centers on integrated wire rod-to-cord operations with captive metallurgical expertise. The signal to watch is MIIT consolidation mandates forcing distressed asset availability in Shandong province.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Rod Supply | Captive high-carbon feedstock secures margin stability against scrap volatility for Jiangsu operators. |
| Trivalent Chromium Plating Conversion | REACH Annex XVII compliance preserves European mill access to German and Belgian OEM supply chains. |
| Smart Tire Sensor Architecture Development | Steel cord constructions accommodating embedded electronics unlock aftermarket service revenue streams. |
| India PLI Corridor Capacity Buildout | Domestic tire manufacturing incentives attract investment toward Gujarat and Tamil Nadu industrial zones. |
| Cobalt-Free Adhesion System R&D | Novel alloy formulations address ECHA restrictions while maintaining rubber-to-steel bond integrity. |
Research Methodology
Operator-level perspectives from tire platform engineers, steel cord plant managers, brass-coating chemical specialists, and fleet procurement directors anchored the qualitative base. Primary fieldwork combined with secondary validation against MIIT industrial policy filings, ECHA REACH registration databases, customs wire rod trade statistics, and SEC filings from listed tire manufacturers. Bottom-up volume modeling and top-down market sizing triangulated across wire rod consumption data and tire production registrations.
Scenario-bracketing framed the analytical approach across the projection horizon, testing sensitivity to scrap steel price bands and electric vehicle penetration trajectories. Segmentation dimensions modeled included product construction type, material grade tier, end-use application, and regional regulatory cluster. CAGRs derived from historical volume elasticities against vehicle production forecasts and tire replacement cycle patterns. Ultra-high-tensile grade adoption curves and REACH conversion timelines served as industry-specific forecast inputs.
Stress conditions across ferroalloy price volatility, EU Green Deal acceleration, and Chinese capacity utilization floors were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on tire architecture migration and regulatory implementation schedules. Material shifts in cobalt-free adhesion system technical validation or India PLI scheme expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Automotive Wheel Coating Market