
 E-Bike Tire Market | 2026-2036
E-Bike Tire Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Tire Market Foresight
Premium puncture-resistant compounds are collapsing the gap between aftermarket replacement and factory-fit specifications. Continental AG leverages captive rubber compounding to sustain margin pools in the tubeless segment. Schwalbe - Ralf Bohle GmbH anchors its position through proprietary Addix compound chemistry. Michelin Group competes on tread longevity ratings across European cargo bike fleets.
E-bike tires are reinforced pneumatic or solid wheel coverings engineered to withstand higher sustained loads and torques than conventional bicycle tires, typically rated for speeds exceeding standard bicycle limits and constructed with enhanced bead seating for motor-assisted torque transfer. Clincher tires dominate current volume due to universal rim compatibility, while tubeless variants capture fastest growth as sealant technology eliminates pinch-flat failures in cargo and mountain applications. Tread design segmentation shows knobby patterns retaining share in German and Swiss mountain biking regions, whereas slick configurations expand in Dutch and Danish urban commuting corridors where wet-grip silica compounds command price premiums.
REACH compliance in the European Union governs chemical composition in tread polymers, while ECHA substance restrictions phase out polycyclic aromatic hydrocarbons in carbon black feedstocks. The EU Green Deal's embodied carbon requirements are reshaping supplier qualification criteria for OEM tire procurement. Stakeholders must monitor how Germany's KBA extends type-approval frameworks from e-bike motors to safety-critical components including tires.
Market Dynamics
EU F-Gas Regulation is forcing solvent-free compound reformulation across European manufacturing bases, compressing supplier qualification timelines while cargo fleet operators accelerate replacement cycles in Dutch and German urban corridors.
Growth Catalysts
- REACH chemical compliance:Tread polymer restrictions are eliminating non-compliant suppliers from OEM procurement lists, consolidating qualified vendor pools for compound specialists.
- Cargo bike fleet expansion:Berlin and Amsterdam municipal logistics contracts specify tubeless-ready specifications, pulling premium puncture-resistant configurations into standard procurement tiers.
- Wet-grip silica chemistry:Dutch commuting corridors command price premiums for hydrophilic tread formulations, rewarding compound innovation with margin expansion.
Market Restraints
- Carbon black feedstock volatility:ECHA polycyclic aromatic hydrocarbon restrictions constrain traditional reinforcing filler supply, elevating raw material qualification costs for compounders.
- German supplier concentration:Industrial corridor clustering around OEM assembly plants creates single-source vulnerability for tier-two distributors serving peripheral markets.
- Clincher rim lock-in:Universal compatibility requirements delay tubeless adoption in price-sensitive replacement segments, fragmenting inventory requirements.
Strategic Opportunities
- Swiss mountain biking regions:Knobby pattern demand persists in alpine terrain where e-MTB torque ratings exceed standard bicycle specifications, creating specialty compound niches.
- EU Green Deal embodied carbon:Supplier qualification criteria now weight lifecycle emissions, advantaging regional compounders with renewable energy sourcing.
- Direct fleet contracting:Urban logistics operators bypass traditional distribution tiers for volume tire procurement, compressing channel margins while securing volume commitments.
Industry Challenges
- KBA type-approval extension:Germany's motor vehicle authority is expanding safety-critical component frameworks to e-bike tires, lengthening certification timelines for new tread patterns.
- Sealant compatibility testing:Tubeless variants require validation across proprietary sealant chemistries, multiplying R&D overhead for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Tire Market |
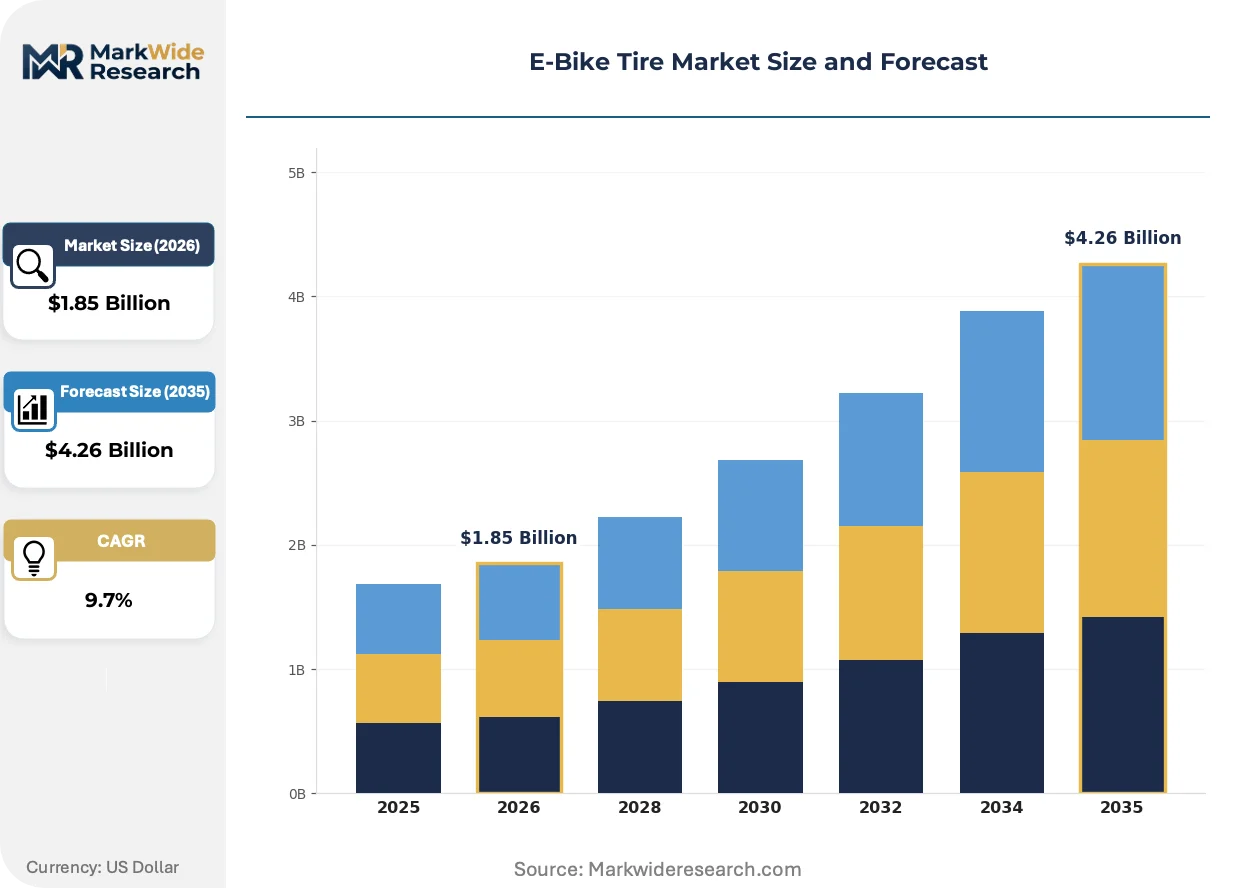
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clincher Tires, Tubeless Tires, Tubular Tires, Solid Tires, Foam-Filled Tires Tread Design: Slick, Knobby, Semi-Slick, Ribbed, Mixed Terrain Application: Urban Commuting, Mountain Biking, Touring, Cargo Transport, Recreation End User: Bike Manufacturers, Rental Fleets, Delivery Services, Individual Riders, Repair Shops |
| Companies Covered | Michelin Group, Continental AG, Schwalbe - Ralf Bohle GmbH, Pirelli & C. SpA, Vittoria SpA, Maxxis International, Kenda Tires, CST (Cheng Shin Rubber), Dunlop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Tire Market Shifts & Advancements
Compound chemistry and regulatory carbon accounting are compressing traditional manufacturing timelines while reshaping how specifications propagate from OEM assembly plants to aftermarket channels.
Thermoplastic polyurethane inserts are miniaturizing puncture protection layers without weight penalties. German cargo fleet operators specify these configurations for urban delivery routes where debris exposure is constant. The technology is miniaturizing the performance gap between aftermarket replacements and factory-fit premium tiers, collapsing historical specification stratification.
EU Green Deal embodied carbon requirements are reshaping supplier qualification protocols for OEM procurement. Compounders must now document energy sourcing and feedstock provenance to maintain approved vendor status. German industrial corridor manufacturers face compressed compliance timelines as Dutch and Danish fleet operators embed carbon thresholds in tender specifications.
Subscription-based tire replacement programs are displacing transactional aftermarket purchasing in municipal logistics contracts. Amsterdam and Berlin fleet managers bundle tread wear monitoring with scheduled swap-out services, unbundling traditional retail distribution. Danish urban corridors show fastest uptake where public procurement mandates operational expenditure models over capital equipment ownership.
E-Bike Tire Market Segmentation
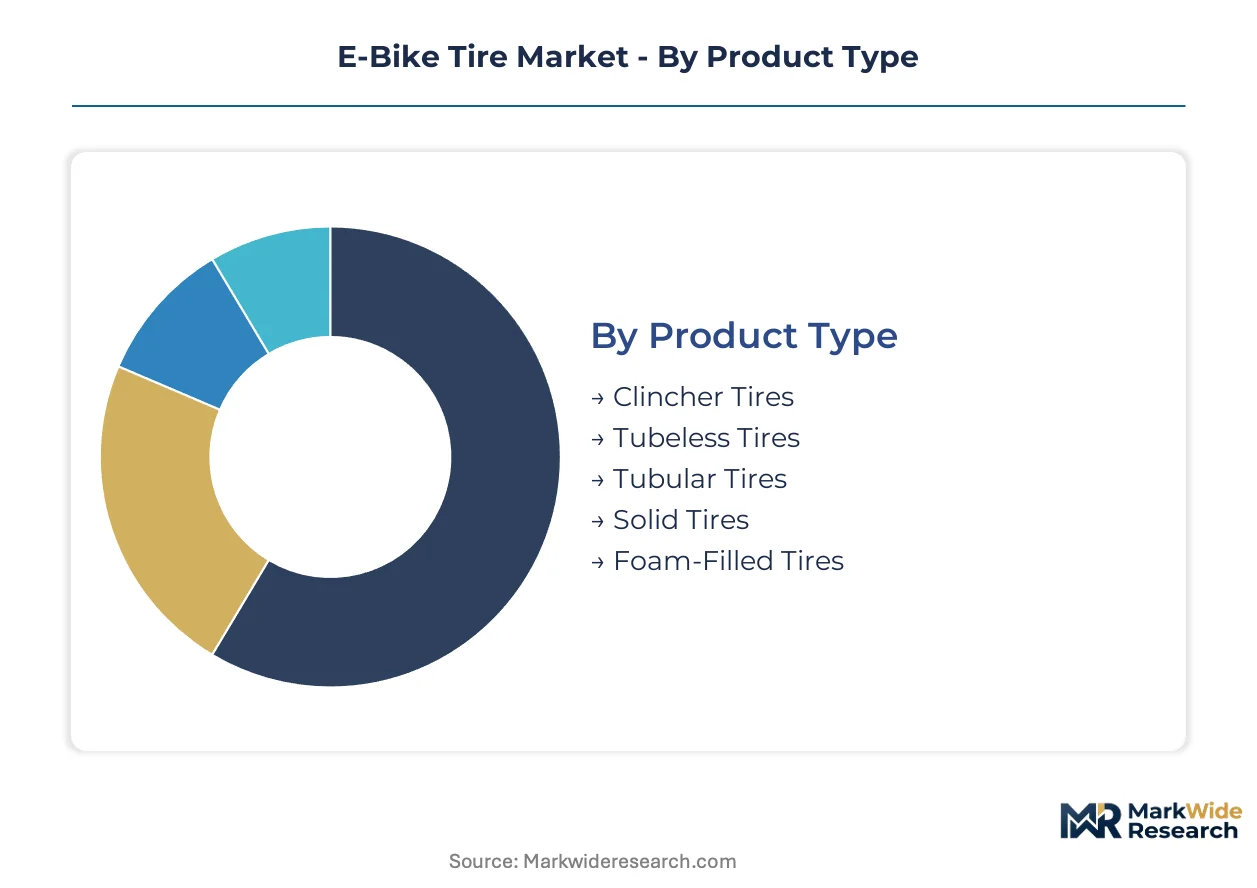
E-bike tire segmentation reflects divergent technical requirements across motor-assisted applications. Specification tiers separate factory-fit OEM procurement from aftermarket replacement channels.
Product Type:
REACH chemical compliance and EU F-Gas Regulation differentiate manufacturing pathways across pneumatic and solid constructions.
- Clincher Tires:Beaded wire or Kevlar-reinforced edges seat into hooked rims for universal compatibility. Dutch and German urban commuting fleets specify these for rapid roadside replacement capability.
- Tubeless Tires:Liquid sealant fills cavity between tire and rim, eliminating pinch-flat failures. Berlin and Amsterdam cargo operators mandate tubeless-ready specifications for debris-heavy delivery routes; wet-grip silica compounds command procurement premiums here.
- Tubular Tires:Sewn-closure casing glues directly to rim bed. Road racing applications in Swiss alpine regions sustain niche demand despite mounting complexity.
- Solid Tires:Monolithic rubber or polyurethane construction eliminates inflation maintenance. Danish municipal bike-share programs deploy these for vandalism resistance.
- Foam-Filled Tires:Closed-cell polymer replaces pressurized air. German industrial corridor logistics operators specify these for puncture-proofing in construction-zone access routes.
Clincher configurations handle the majority of throughput; tubeless variants are gaining share fastest as fleet procurement tightens specifications.
Tread Design:
Cost tier stratification separates premium compound formulations from commodity rubber specifications.
- Slick:Continuous contact patch maximizes rolling efficiency on paved surfaces. Dutch urban corridors specify hydrophilic silica formulations for wet-grip performance.
- Knobby:Aggressive lug patterns bite into loose terrain. Swiss and German alpine e-MTB regions demand reinforced sidewalls for torque-rated motor assistance.
- Semi-Slick:Centerline smoothness transitions to shoulder knobs. Touring applications across Danish rural routes balance speed and contingency grip.
- Ribbed:Circumferential grooves channel water. Berlin delivery fleets specify these for predictable braking in urban drainage conditions.
- Mixed Terrain:Variable lug geometry adapts to surface transitions. German cargo operators traversing cobblestone-to-asphalt routes favor this compromise specification.
Slick patterns dominate volume in lowland fleet contracts; knobby configurations climb fastest as e-MTB torque ratings expand addressable terrain.
Application:
Volume concentration follows municipal procurement cycles and seasonal replacement patterns.
- Urban Commuting:Puncture-resistant compounds withstand debris exposure on daily routes. Amsterdam and Berlin fleet operators accelerate replacement cycles through subscription service models.
- Mountain Biking:Reinforced bead seating transfers motor torque without slip. Swiss alpine terrain sustains premium pricing for e-MTB-rated sidewall constructions.
- Touring:Long-distance durability prioritizes tread longevity over grip aggression. Danish long-haul routes specify all-weather compounds.
- Cargo Transport:Load-bearing carcass plies accommodate motor-assisted hauling weights. German industrial corridor OEMs integrate these into factory-fit specifications.
- Recreation:Price-sensitive replacement demand dominates this segment. Repair shops in peripheral markets stock clincher inventory for compatibility breadth.
Urban commuting handles the majority of replacement volume; cargo transport expands most quickly as logistics electrification accelerates.
End User:
Customer type determines margin structure and channel configuration.
- Bike Manufacturers:OEM procurement demands documented carbon provenance under EU Green Deal supplier qualification. German assembly plants cluster near compounders for just-in-sequence delivery.
- Rental Fleets:High-rotation usage patterns prioritize total cost of ownership over unit price. Danish municipal operators bundle tread monitoring with scheduled swap-out services.
- Delivery Services:Debris exposure and mileage accumulation compress replacement intervals. Berlin and Amsterdam last-mile logistics specify premium puncture protection.
- Individual Riders:Aftermarket replacement follows wear-indicator triggers. Price sensitivity delays tubeless adoption in this segment.
- Repair Shops:Inventory breadth requirements favor universal-fit clincher stocking. Margin compression from direct fleet contracting pressures traditional distribution tiers.
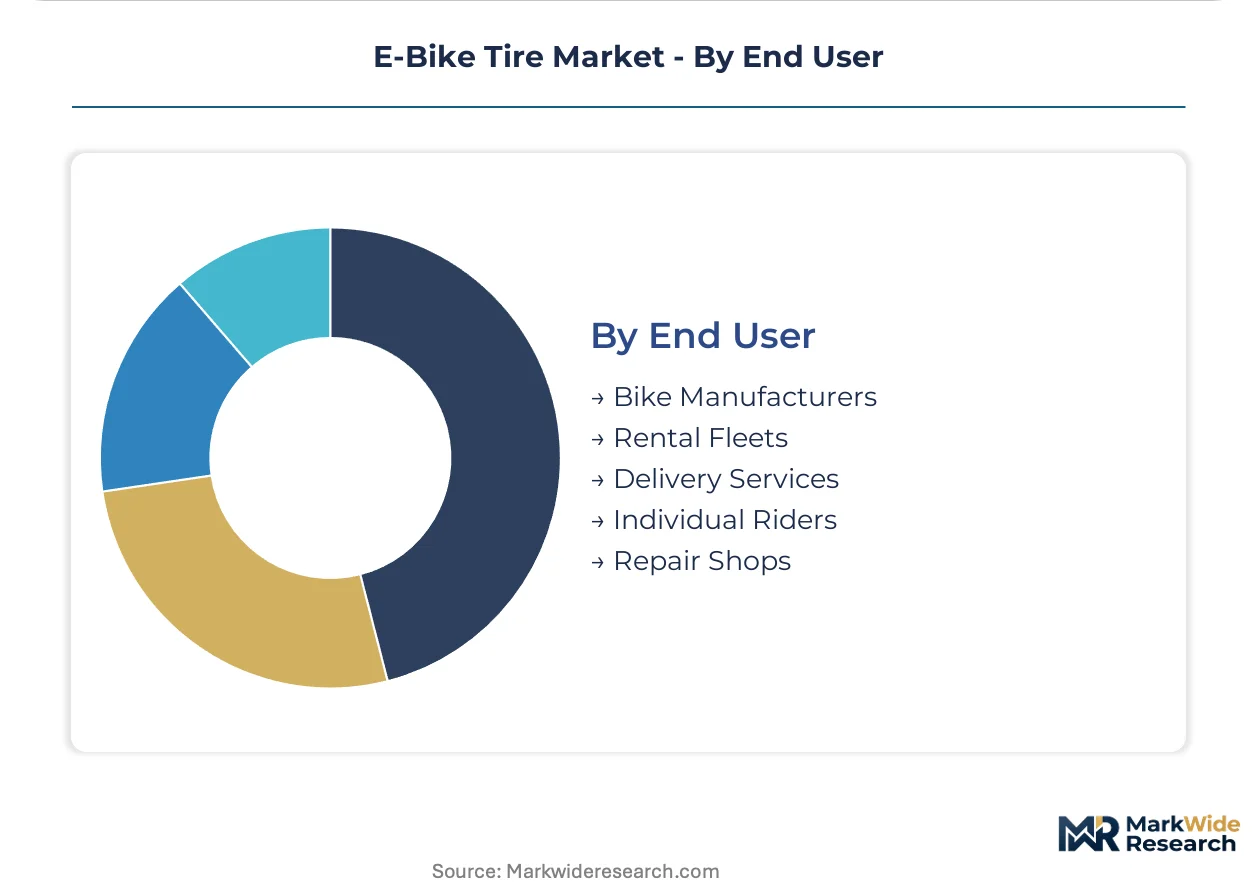
Bike manufacturers anchor premium specification throughput; delivery services represent the steepest expansion trajectory as urban logistics electrifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export tubeless-ready specifications to Dutch fleet operators through the Rhine-Ruhr industrial corridor, while Swiss alpine demand pulls knobby-pattern reinforcements across the AlpTransit logistics network.
Germany
Cargo fleet electrification in Berlin and Hamburg accelerates replacement cycles for load-rated carcass plies. KBA type-approval frameworks now extend safety-critical component testing to e-bike tires, lengthening certification timelines for new tread patterns. The North Rhine-Westphalia industrial corridor clusters Continental AG and Schwalbe production facilities near OEM assembly plants for just-in-sequence delivery.
Netherlands
Amsterdam municipal logistics contracts specify wet-grip silica compounds for debris-heavy urban routes. EU Green Deal embodied carbon requirements are reshaping supplier qualification protocols for fleet procurement tenders. The Randstad metropolitan region concentrates subscription-based tire replacement programs that displace traditional retail distribution channels.
Switzerland
Alpine e-MTB torque ratings exceed standard bicycle specifications, sustaining demand for reinforced sidewall constructions in Zurich and Geneva catchment areas. REACH chemical compliance governs tread polymer composition for cross-border sales into EU member states. Swissmedic coordinates with ECHA on substance restriction alignment for carbon black feedstocks.
Denmark
Copenhagen fleet operators embed operational expenditure models in public procurement mandates, accelerating subscription service uptake. F-Gas Regulation compliance pressures compounders toward solvent-free reformulation across Nordic manufacturing bases. Danish urban corridors show fastest adoption of tread wear monitoring bundled with scheduled swap-out services.
Belgium
Brussels-based logistics electrification programs specify puncture-resistant configurations for last-mile delivery density. ECHA substance restrictions phase out polycyclic aromatic hydrocarbons in reinforcing fillers, elevating raw material qualification costs. The Flanders industrial zone positions compounders for EU-wide distribution through Antwerp port connectivity.
E-Bike Tire Market Competitive Landscape
Listed leaders compete with private specialists across compound chemistry and fleet contracting channels. The vendor base stratifies into three tiers: integrated rubber compounders with captive polymer facilities, specialty tire houses focused on performance segments, and volume fabricators serving price-sensitive replacement demand. Strategic archetypes include EU-based compound specialists leveraging REACH compliance as a qualification barrier, Asian manufacturers capturing scale in clincher volume, and regional distributors building direct fleet relationships. Dominant competitive moves center on backward integration into rubber compounding and geographic expansion through municipal logistics procurement.
Within the integrated compounder tier, Continental AG and Michelin Group exemplify archetypes combining captive polymer production with OEM just-in-sequence delivery. Schwalbe - Ralf Bohle GmbH occupies a position representing private specialist focus on proprietary Addix chemistry for premium puncture-resistant configurations. These three anchors illustrate how supplier qualification consolidation under EU chemical regulations is compressing viable competitive positioning toward compound innovation and documented carbon provenance.
| Leading Market Players |
|---|
| Michelin Group |
| Continental AG |
| Schwalbe - Ralf Bohle GmbH |
| Pirelli & C. SpA |
| Vittoria SpA |
| Maxxis International |
| Kenda Tires |
| CST (Cheng Shin Rubber) |
| Dunlop |
| Others |
Supply & Pricing Matrix
Sixty-day compound qualification timelines under REACH chemical compliance compress procurement windows while amplifying pricing power for German rubber compounders serving Dutch fleet operators. This lead-time compression reinforces margin stratification between solvent-free certified suppliers and commodity tire fabricators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with just-in-sequence delivery premiums. Three-tier pricing structure across premium, standard, and economy levels separates factory-fit tubeless specifications from aftermarket clincher replacements. Cost compression in the replacement tier intensifies as direct fleet contracting bypasses traditional distribution markups. Individual riders exhibit highest price sensitivity, while municipal logistics operators absorb premiums for documented carbon provenance under EU Green Deal supplier qualification.
Supply Chain Analysis
Inventory concentration in Germany's North Rhine-Westphalia industrial corridor feeds just-in-sequence assembly at OEM plants. Raw material sourcing draws from Malaysian natural rubber plantations, German synthetic polymer facilities, and Belgian carbon black feedstock processors. Single-source vulnerability persists around solvent-free compounders qualified under F-Gas Regulation. Distribution runs through tier-one distributors serving fleet operators, with direct contracting displacing retail channels in Amsterdam and Berlin municipal corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-bike tire demand acceleration represents a high-growth disruption propelled by EU Green Deal embodied carbon requirements reshaping supplier qualification protocols across European procurement.
For Market Incumbents: Fortify backward integration into captive rubber compounding to defend margin pools against Asian volume fabricators. Secure KBA type-approval certification for new tread patterns before regulatory frameworks lengthen. Anchor capacity within the Rhine-Ruhr corridor to maintain just-in-sequence delivery relationships with German OEM assembly plants. For New Entrants and Emerging Players: Subscription-based fleet servicing gaps in Danish and Dutch urban corridors offer white-space penetration where incumbents under-serve operational expenditure procurement models. Target Copenhagen and Amsterdam municipal logistics tenders with bundled tread monitoring and scheduled swap-out services. Pursue direct contracting channels that bypass traditional tier-one distribution markups. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized tire divisions lacking EU chemical compliance infrastructure. Long-term viability hinges on compound innovation capabilities and documented renewable energy sourcing. Monitor KBA regulatory expansion signals as inflection indicators for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive polymer production secures margin pools against feedstock volatility under ECHA restrictions. |
| Solvent-Free Manufacturing Transition | F-Gas Regulation compliance qualifies suppliers for Dutch and German fleet procurement tenders. |
| Direct Fleet Contracting Expansion | Subscription service models displace retail distribution in Amsterdam and Berlin municipal corridors. |
| KBA Type-Approval Investment | Safety-critical component certification lengthens competitive moats for new tread pattern introductions. |
| Carbon Provenance Documentation | EU Green Deal supplier qualification embeds lifecycle emissions thresholds in OEM procurement. |
Research Methodology
The analysis maps clincher, tubeless, and solid tire constructions, each validated through compound R&D directors, OEM procurement managers, fleet operations heads, and aftermarket distribution partners. Primary fieldwork across German industrial corridor facilities, Dutch municipal logistics operators, and Swiss alpine e-MTB retailers combined with customs trade data, ECHA substance restriction filings, and KBA regulatory announcements. Secondary validation drew from EU Green Deal policy documents, REACH compliance databases, and tire industry association reports. Bottom-up volume modeling triangulated against top-down market sizing across product type, tread design, application, and end-user segments.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions modeled include tire construction type, compound chemistry tier, motor torque rating, and regional regulatory cluster. CAGRs derived from replacement cycle acceleration in fleet segments and penetration trajectory for tubeless configurations. Industry-specific inputs incorporated KBA certification timeline assumptions and F-Gas Regulation compliance cost curves for solvent-free reformulation.
Underlying assumptions cover sustained electrification in urban logistics, regulatory stability for REACH chemical restrictions, and carbon accounting enforcement in OEM procurement, with deviation risk concentrated in feedstock price volatility for PAH-compliant carbon black. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Solid Tire Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Self-Sealing Tire Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
High Performance Wheels Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Global Automotive Tire Socks Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Tire Carousel Market