
 Racing Tires Market | 2026-2036
Racing Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Racing Tires Market Analysis
Aftermarket tire service revenue is rewriting how suppliers capture lifetime value from racing teams. Bridgestone Corporation leverages its Formula One heritage to sustain technical consulting contracts beyond unit sales. Michelin anchors its margin pool in endurance racing where multi-stint tire strategies command premium pricing.
Racing tires are high-performance elastomer composites engineered with specialized tread compounds, aramid or steel belt reinforcements, and carcass designs that withstand sustained cornering forces above 200 km/h; their primary purpose is to maximize mechanical grip and thermal stability during competitive motorsport events. Soft compound tires dominate qualifying sessions where single-lap pace determines grid position, while wet tires represent the fastest-growing product type as climate-adaptive race calendars expand rain-affected events. Radial tire technology leads in sports car and touring car categories, yet bias-ply construction persists in drag and vintage racing niches where sidewall compliance matters.
The EPA regulates particulate emissions from tire manufacturing facilities in the United States, while REACH governs chemical substance registration across European production sites, and the FIA technical regulations directly specify tire dimension and construction standards for Formula championships. These frameworks collectively elevate compliance costs but also create barriers that favor established suppliers with dedicated homologation teams. Stakeholders must monitor how bio-based material mandates and thermal efficiency rules reshape compound development priorities across motorsport categories.
Market Dynamics
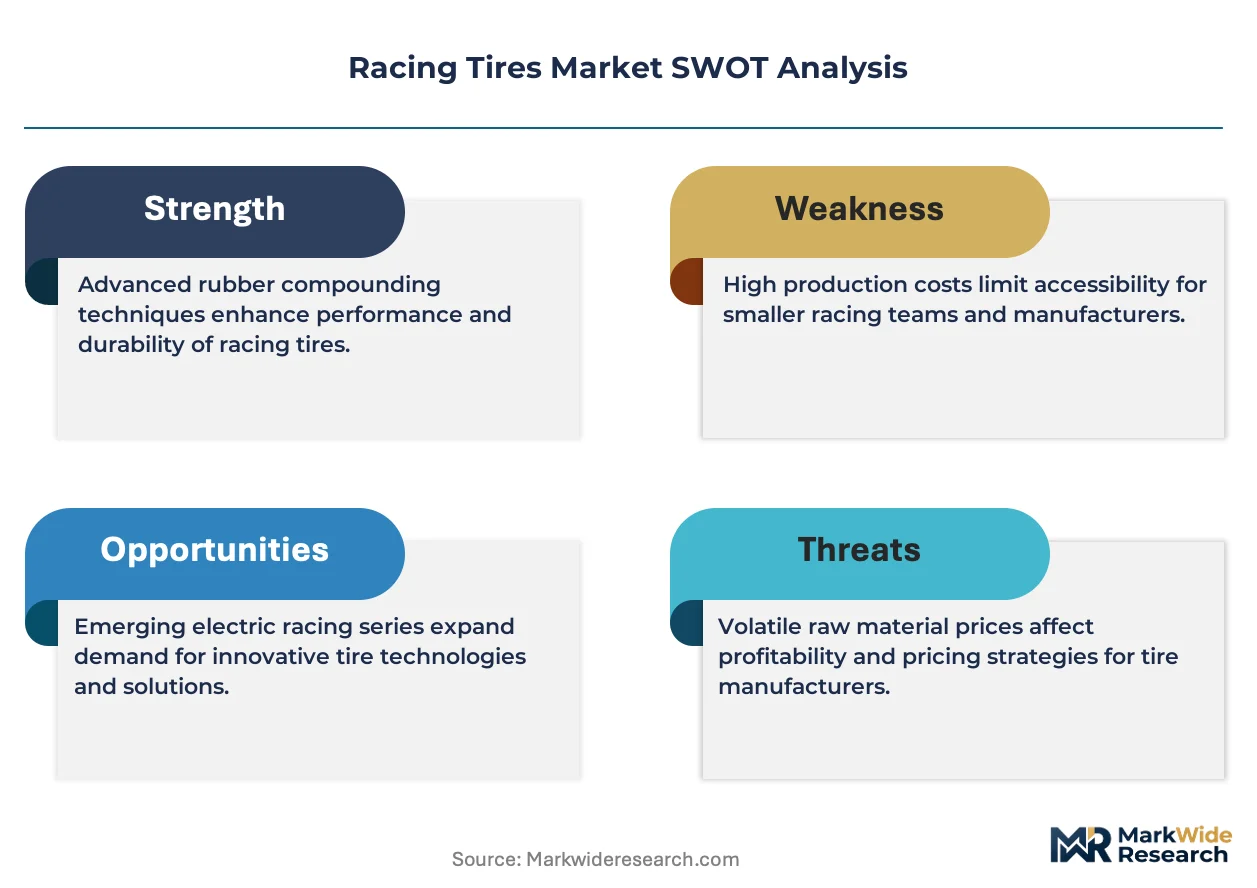
The EU F-Gas Regulation and REACH compliance are forcing compound reformulation across European production facilities, while Formula One and GT endurance fleets expand tire consumption per season through extended race calendars and multi-stint strategies.
Growth Catalysts
- EU F-Gas Regulation:Mandates on fluorinated greenhouse gases push manufacturers toward bio-based synthetic rubber formulations, opening premium positioning for compliant suppliers.
- GT endurance racing expansion:Multi-stint tire strategies in 24-hour and endurance events generate recurring high-volume orders from factory-backed teams.
- Aramid belt reinforcement:Advanced fiber technology enables sustained cornering forces above 200 km/h, qualifying tires for top-tier homologation categories.
Market Restraints
- Petroleum-derived synthetic rubber volatility:Feedstock price swings compress margin pools for compound-dependent manufacturers.
- German and Italian supply concentration:Motorsport manufacturing clusters in these countries create geographic dependency risk for OEM contract fulfillment.
- Bias-ply technical ceiling:Sidewall compliance advantages in drag and vintage niches cannot scale to modern thermal efficiency requirements.
Strategic Opportunities
- Japan's permanent circuit infrastructure:Suzuka and Fuji Speedway anchor OEM supply contracts with predictable annual volume commitments.
- Wet tire category expansion:Climate-adaptive race calendars are expanding rain-affected events, creating demand for specialized tread compounds.
- Aftermarket technical consulting:Service revenue models beyond unit sales capture lifetime value from racing teams through compound optimization support.
Industry Challenges
- Homologation team scarcity:Dedicated FIA technical regulation expertise concentrates among established suppliers, blocking mid-tier market entry.
- Thermal efficiency rule integration:New compound development priorities must satisfy simultaneous grip and heat management targets.
- REACH substance registration timelines:Chemical approval delays extend product certification cycles beyond traditional motorsport development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Racing Tires Market |
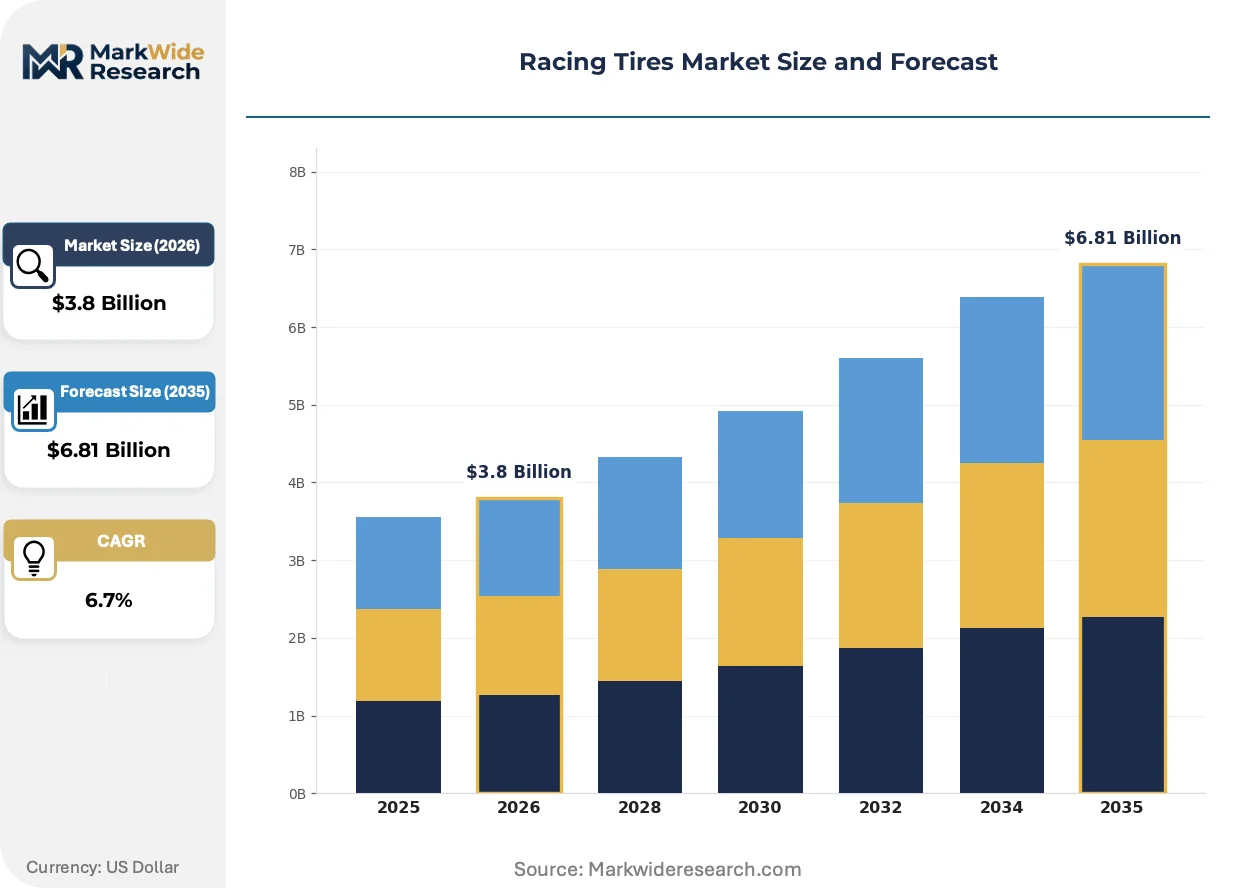
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
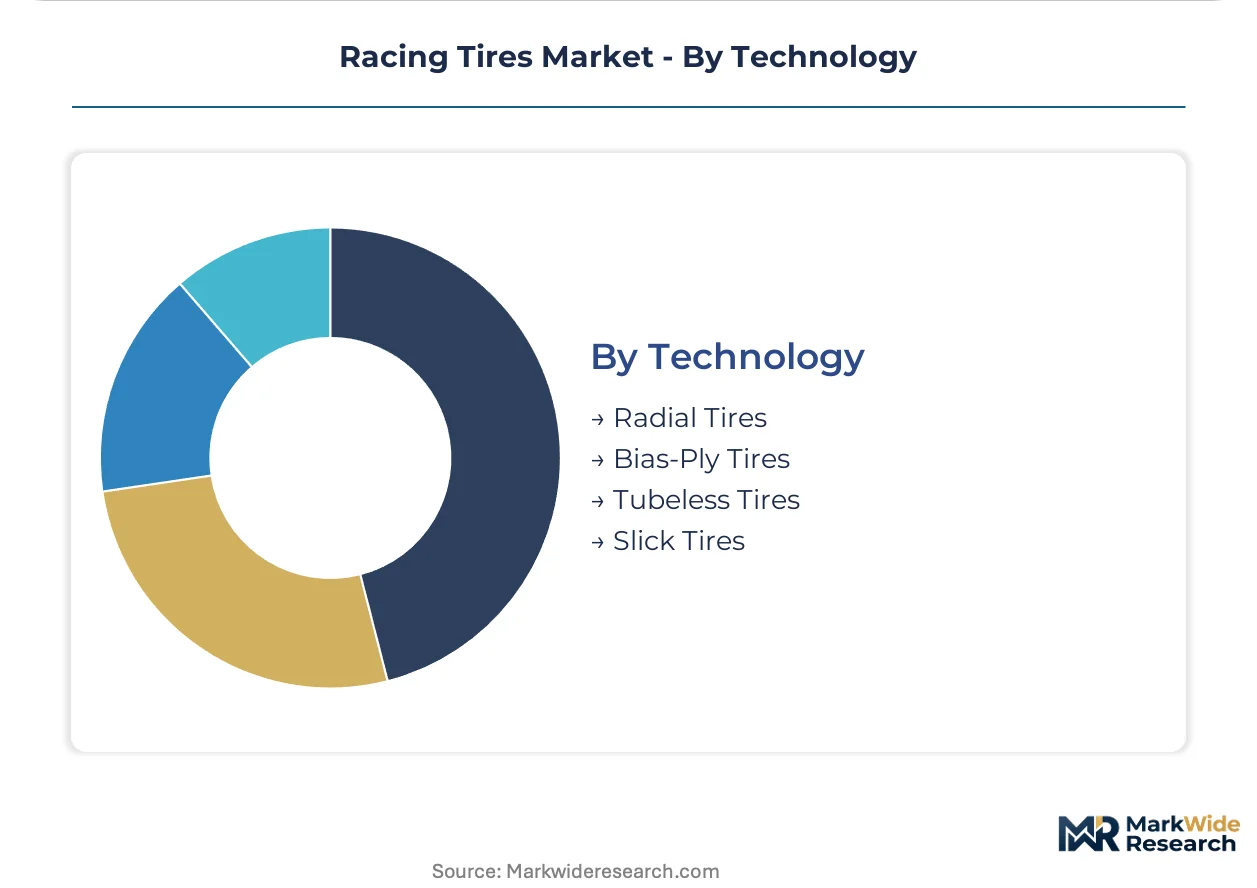
| Segmentation | Product Type: Soft Compound, Hard Compound, Wet Tires, Intermediate Tires Vehicle Type: Formula Cars, Sports Cars, Touring Cars, Drift Cars Usage Scenario: Track Racing, Street Racing, Endurance Racing, Rally Racing Technology: Radial Tires, Bias-Ply Tires, Tubeless Tires, Slick Tires |
| Companies Covered | Bridgestone Corporation, Michelin, Continental AG, Pirelli & C. S.p.A., The Goodyear Tire & Rubber Company, The Yokohama Rubber Co., Ltd., Hankook Tire & Technology Co., Ltd., Maxxis International, Hoosier Racing Tire Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Racing Tires Market Emerging Trajectories
Compound chemistry and construction methods are undergoing forced evolution as regulatory pressure intersects with performance demands from expanding endurance calendars.
Guayule-derived natural rubber is migrating from experimental batches to qualifying compound formulations. Pirelli and Michelin test teams are adopting bio-based elastomers at pace for 2025 homologation cycles. This material transition is compressing petroleum-dependent supply chains while opening new agricultural sourcing partnerships in arid-climate regions.
REACH substance registration now governs chemical inputs across European tire production sites. ECHA documentation requirements extend development timelines but create defensible moats for suppliers with dedicated compliance infrastructure. Wet tire compounds face the steepest reformulation burden as hydrophobic additive portfolios come under enhanced scrutiny.
Racing teams are unbundling tire supply from technical service contracts. Factory squads now separately procure compound optimization consulting, thermal mapping, and stint strategy modeling. This disaggregation is most visible in Formula One and WEC paddocks where data-driven performance guarantees replace traditional volume-based supply agreements.
Racing Tires Market Segmentation

Racing tire segmentation maps directly to competitive format requirements and regulatory constraints across motorsport categories. Compound chemistry, vehicle specifications, and usage intensity create distinct procurement patterns that suppliers must address through targeted product architectures.
Product Type:
The use-case spectrum spans single-lap qualifying pace to sustained multi-hour thermal management, with each compound class engineered for specific track conditions and stint strategies.
- Soft Compound:Maximum mechanical grip compounds formulated for qualifying sessions where single-lap pace determines grid position. Demand concentrates in Formula One and sprint race formats across Germany and Italy, where factory-backed teams prioritize track position over tire longevity.
- Wet Tires:Specialized tread patterns with hydrophobic additive packages engineered for rain-affected events. Climate-adaptive race calendars are expanding rain-affected events across Japan's permanent circuits, creating demand for rapid compound optimization support from technical consulting teams.
- Hard Compound:Thermal-resistant formulations designed for extended stint lengths and reduced degradation rates.
- Intermediate Tires:Cross-condition compounds bridging dry and wet performance envelopes for variable weather transitions.
The dominant share belongs to soft compound formulations, while wet tires are closing the gap fastest as climate volatility reshapes race calendar planning.
Vehicle Type:
Cost tier differentiation separates prototype budgets from production-based racing categories, with each vehicle class imposing distinct homologation and supply contract structures.
- Formula Cars:Single-seat open-wheel designs with FIA-mandated tire dimensions and construction standards. REACH compliance and EU F-Gas Regulation compound reformulation requirements elevate barriers for suppliers serving European-based championships.
- Sports Cars:GT and prototype endurance vehicles utilizing multi-stint tire strategies. Factory-backed teams in 24-hour events generate recurring high-volume orders with premium pricing for thermal mapping and stint optimization services.
- Touring Cars:Production-based silhouettes with controlled tire specifications and volume procurement.
- Drift Cars:Sidewall compliance-dependent vehicles where bias-ply construction persists despite thermal efficiency limitations.
Sports cars command the largest procurement volumes, while formula cars maintain the steepest technology premium.
Usage Scenario:
Application intensity varies from controlled circuit environments to variable surface conditions, driving divergent durability and adaptability requirements.
- Endurance Racing:24-hour and multi-stint formats requiring thermal stability across compound batches. Suzuka and Fuji Speedway anchor predictable annual volume commitments from Japanese OEM supply contracts.
- Track Racing:Controlled circuit environments with standardized surface conditions and temperature ranges.
- Street Racing:Temporary circuit formats with variable grip levels and surface irregularities.
- Rally Racing:Variable terrain surfaces requiring compound adaptability beyond circuit-optimized formulations.
Endurance racing generates the highest per-event consumption, with track racing providing the most stable baseline demand.
Technology:
Construction maturity separates scalable radial architectures from niche applications where legacy designs retain functional advantages.
- Radial Tires:Steel and aramid belt reinforcements enabling sustained cornering forces above 200 km/h. Sports car and touring car categories have standardized on radial construction, with homologation team expertise concentrating among established European suppliers.
- Slick Tires:Treadless contact surfaces maximizing dry-weather mechanical grip for qualifying and sprint formats.
- Bias-Ply Tires:Diagonal cord construction providing sidewall compliance for drag and vintage racing niches.
- Tubeless Tires:Eliminated inner tube designs reducing unsprung mass and thermal retention.
Radial construction holds the installed base majority, though slick tires are gaining share fastest in sprint-format expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's motorsport engineering clusters consume racing tires through endurance and touring car formats, while Japan's permanent circuit infrastructure supports different consumption patterns centered on factory-backed endurance programs and domestic single-seater series.
United States
Drag racing and NASCAR oval formats drive specialized bias-ply demand alongside sports car endurance growth at Sebring and Daytona. EPA particulate emission standards from tire manufacturing facilities elevate compliance costs for domestic compound production. Indiana-based racing tire specialists concentrate drag and dirt track supply contracts with independent series organizers.
Germany
Nürburgring 24-hour and DTM touring car grids anchor high-volume procurement from factory-backed manufacturer teams. KBA vehicle certification requirements intersect with EU F-Gas Regulation mandates on fluorinated greenhouse gases in rubber processing. Baden-Württemberg and Bavaria host motorsport engineering clusters where OEM supply contracts concentrate around Porsche and Mercedes-AMG racing programs.
Italy
Monza and Imola circuits anchor Formula One and GT endurance tire consumption through Ferrari-affiliated racing programs. REACH chemical substance registration governs compound inputs at European production sites serving Italian motorsport demand. Emilia-Romagna's motorsport manufacturing corridor concentrates Pirelli technical operations and Ferrari Corse Clienti logistics.
Japan
Suzuka and Fuji Speedway generate predictable annual volume commitments through Super GT and Super Formula tire supply agreements. METI industrial standards support domestic aramid fiber and synthetic rubber supply chain integration for racing compound production. Tochigi and Shizuoka prefectures host tire R&D facilities co-located with Honda and Toyota motorsport engineering centers.
United Kingdom
Silverstone and Brands Hatch circuits support historic racing and British GT demand alongside Formula One technical consulting services. ECHA documentation requirements for REACH compliance extend development timelines for wet tire compound reformulation. Motorsport Valley clusters in Oxfordshire and Northamptonshire concentrate engineering services that unbundle tire supply from technical optimization contracts.
Racing Tires Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The racing tire market structures around a tight oligopoly of full-line manufacturers with dedicated homologation teams, while mid-tier specialists occupy niche categories where FIA technical regulation expertise is less critical. Three archetypes dominate: integrated rubber conglomerates with motorsport heritage divisions, tire specialists with exclusive championship supply contracts, and regional manufacturers serving national racing series. Consolidation pressure operates through backward integration into bio-based raw material sourcing and captive aramid fiber supply arrangements.
Within the integrated conglomerate tier, Bridgestone Corporation and Michelin exemplify players that leverage Formula One and endurance racing heritage to sustain technical consulting revenue beyond unit sales. Continental AG occupies a position bridging premium road car and motorsport compound development. Yokohama-based The Yokohama Rubber Co., Ltd. represents the Asia-Pacific anchor for factory-backed Super GT supply relationships.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin |
| Continental AG |
| Pirelli & C. S.p.A. |
| The Goodyear Tire & Rubber Company |
| The Yokohama Rubber Co., Ltd. |
| Hankook Tire & Technology Co., Ltd. |
| Maxxis International |
| Hoosier Racing Tire Corp. |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp petrochemical corridor's freight cost dynamics compress margin pools for compound-dependent manufacturers while amplifying price differentiation between REACH-compliant European suppliers and import-dependent buyers. Petroleum-derived synthetic rubber volatility feeds back into contract structures, with factory-backed teams in Germany and Italy capturing volume discounts through multi-year offtake agreements that smaller endurance racing programs cannot match.
Pricing Analysis
Long-term offtake agreements dominate procurement between established suppliers and factory-backed manufacturer teams, while spot purchasing persists for independent racing programs and vintage series operators. Price differentiation hinges on FIA homologation tier and after-sales technical consulting bundling, with premium positioning reserved for suppliers offering compound optimization support. Cost compression in the mid-tier is intensifying because REACH substance registration timelines extend product certification cycles. Independent endurance racing teams exhibit the highest price sensitivity due to unpredictable sponsorship renewal cycles, whereas Formula One factory squads prioritize performance guarantees over unit cost.
Supply Chain Analysis
Petroleum-derived butadiene and styrene feedstock draws from German, Dutch, and Belgian petrochemical clusters, with aramid fiber reinforcement sourcing concentrated in the United States and Japan. Guayule-derived natural rubber represents an emerging agricultural input from arid-climate regions, though commercial volumes remain constrained. Single-source vulnerability characterizes FIA homologation team expertise, which concentrates among established European suppliers. Distribution runs through direct OEM supply contracts for factory-backed programs, with aftermarket channels serving independent racing teams and historic vehicle operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Racing tire supply constitutes a defensive-moat market where regulatory entrenchment creates durable barriers. REACH compliance infrastructure and FIA technical regulation expertise concentrate among incumbents, locking out mid-tier competitors.
For Market Incumbents: Entrench position by deepening backward integration into bio-based synthetic rubber feedstocks, particularly guayule cultivation partnerships in arid-climate sourcing regions. Expand captive aramid fiber supply arrangements to insulate against petroleum price volatility. Prioritize homologation team capacity additions in Baden-Württemberg and Emilia-Romagna to defend against emerging Asia-Pacific challengers seeking European championship entry.
For New Entrants and Emerging Players: Build out wet tire compound specialization targeting climate-adaptive race calendar expansion across Japan's permanent circuits. Focus initial penetration on drift and vintage racing niches where bias-ply technical requirements reduce FIA homologation barriers. Pursue technical consulting service contracts that unbundle from tire supply, capturing lifetime value through thermal mapping and stint strategy modeling rather than competing on compound volume.
For Investors and Strategic Acquirers: Regional manufacturers with exclusive national series supply contracts represent the most defensible acquisition archetype. Motorsport heritage divisions within integrated rubber conglomerates command premium valuations due to irreplaceable FIA relationship equity. Watch for inflection in EU F-Gas Regulation enforcement stringency, which would accelerate bio-based compound transition timelines and reward early backward integration into sustainable feedstock supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Guayule-derived natural rubber sourcing insulates compound formulations from petroleum price volatility and REACH scrutiny. |
| Homologation Team Capacity Expansion | FIA technical regulation expertise concentration in Germany and Italy creates defensible moats against Asia-Pacific entrants. |
| Technical Consulting Service Unbundling | Compound optimization and thermal mapping contracts capture lifetime value beyond unit sales in Formula One and WEC paddocks. |
| Wet Tire Compound Specialization | Climate-adaptive race calendar expansion across Suzuka and Fuji Speedway creates demand for hydrophobic additive expertise. |
| Captive Aramid Fiber Supply Arrangements | Aramid belt reinforcement sourcing from Japanese and American fiber producers secures sustained cornering force capability above 200 km/h. |
Methodological Framework
Operator-level perspectives from tire compound R&D directors, FIA technical delegates, factory team procurement managers, and endurance racing strategists anchored the qualitative base. These primary insights were cross-referenced against customs and trade data, FIA homologation filings, SEC 10-K disclosures from listed rubber conglomerates, and motorsport engineering cluster reports from Baden-Württemberg and Emilia-Romagna. Bottom-up volume estimates from individual championship tire allocations were reconciled with top-down market sizing derived from OEM supply contract values.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, optimistic, and conservative tracks reflecting alternative assumptions on EU F-Gas Regulation enforcement timing and bio-based compound adoption velocity. Segmentation dimensions modeled encompassed compound chemistry class, vehicle architecture category, endurance versus sprint format intensity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to disclosed championship expansion plans and permanent circuit infrastructure investment pipelines.
Stress conditions across petroleum feedstock price volatility, REACH substance registration delays, and championship calendar disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on homologation cycle timing and factory team budget commitment stability. Cross-checking against FIA tire supply tender disclosures and disclosed OEM motorsport expenditure is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Agricultural Tires Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Continuous Track Wheels Market