
 Global Pneumatic Tires Market | 2026-2036
Global Pneumatic Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pneumatic Tires Market Analysis
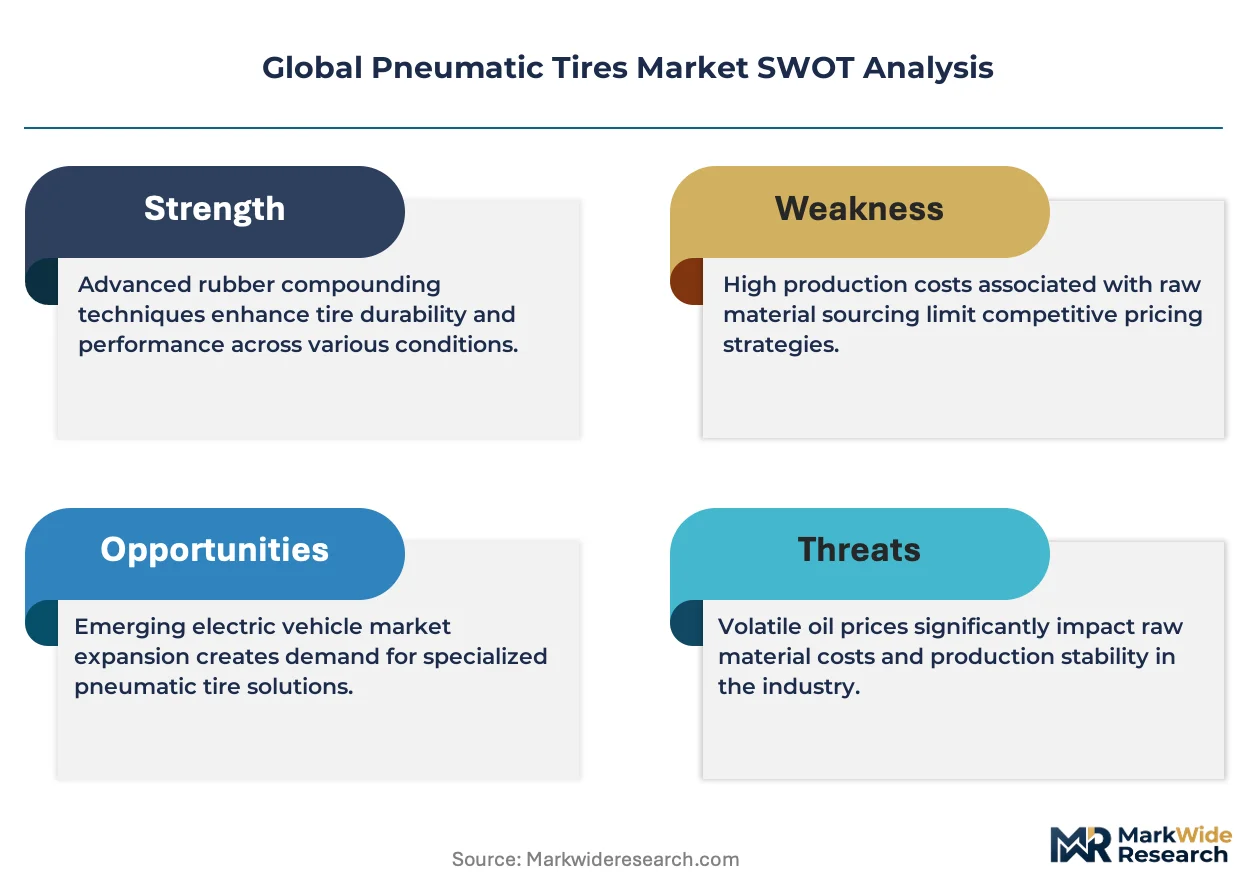
Fleet operator consolidation among logistics and ride-hailing platforms is hardening procurement leverage over tire suppliers. Michelin sustains premium positioning through advanced silica compound research and motorsport-derived technology transfer. Bridgestone Corporation anchors its volume base through deep partnerships with Japanese and North American automakers. Continental AG differentiates via integrated tire sensor systems and digital fleet management services.
Pneumatic tires are flexible, air-filled structures comprising rubber compounds, textile reinforcement layers, and steel bead wires manufactured through calendering, extrusion, and vulcanization processes; they cushion vehicles against road irregularities while transmitting traction, braking, and steering forces. Radial tires dominate the product type landscape due to superior fuel efficiency and tread life, while tubeless configurations are displacing tubed variants in passenger and commercial segments. Specialty tires command concentrated margin pools in mining and agricultural applications where extreme duty cycles justify premium pricing.
The US NHTSA enforces uniform tire quality grading and fuel efficiency standards that shape manufacturer R&D priorities, while the EU REACH regulation restricts hazardous substances in tire formulations and the EU Green Deal accelerates demand for low rolling-resistance designs. China's GB standards and MIIT directives mandate tire labeling and energy efficiency classifications for domestic sales. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance costs and product specification fragmentation.
Market Dynamics
Fleet operator consolidation and original equipment procurement centralization are compressing supplier margins while forcing tire manufacturers to embed predictive maintenance capabilities and lifecycle cost guarantees into contract structures.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is accelerating demand for low-global-warming-potential tire inflation systems and sustainable refrigerant alternatives in commercial vehicle applications.
- Silica compound advances:Precipitated silica technology improves wet grip and rolling resistance simultaneously, enabling premium tier positioning in passenger and light truck segments.
- China's new energy vehicle production:Domestic automaker scaling is concentrating original equipment tire demand in Shanghai, Guangzhou, and Hefei manufacturing clusters.
Market Restraints
- Natural rubber price volatility:Supply concentration in Thailand, Indonesia, and Vietnam exposes manufacturers to weather-driven harvest disruptions and speculative commodity swings.
- EU REACH compliance costs:Restrictions on polycyclic aromatic hydrocarbons and heavy metals in tire formulations force reformulation investments across European production facilities.
- Retreading substitution:Commercial fleet operators extend casing life through cold and hot retreading processes, compressing replacement tire volume in long-haul trucking.
Strategic Opportunities
- India's commercial vehicle expansion:Infrastructure investment and logistics modernization are underpenetrated relative to vehicle stock, creating whitespace for radial tire penetration in medium and heavy-duty segments.
- Tire-as-a-service models:Subscription-based pricing for fleet customers bundles mounting, rotation, pressure monitoring, and replacement scheduling into per-kilometer contracts.
- EU Green Deal tailwinds:Carbon border adjustment mechanisms and embodied carbon disclosure requirements favor low-rolling-resistance designs manufactured with renewable energy inputs.
Industry Challenges
- Compound formulation talent scarcity:Deep expertise in silica-silane coupling chemistry and bio-based elastomer development concentrates among a narrow cohort of materials scientists.
- Smart tire certification timelines:RF sensor integration and tread depth monitoring algorithms require validation against UN ECE R141 and regional cybersecurity standards before OEM fitment approval.
- Legacy ERP integration friction:Digital fleet management platforms must synchronize with incumbent transportation management systems used by established logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pneumatic Tires Market |
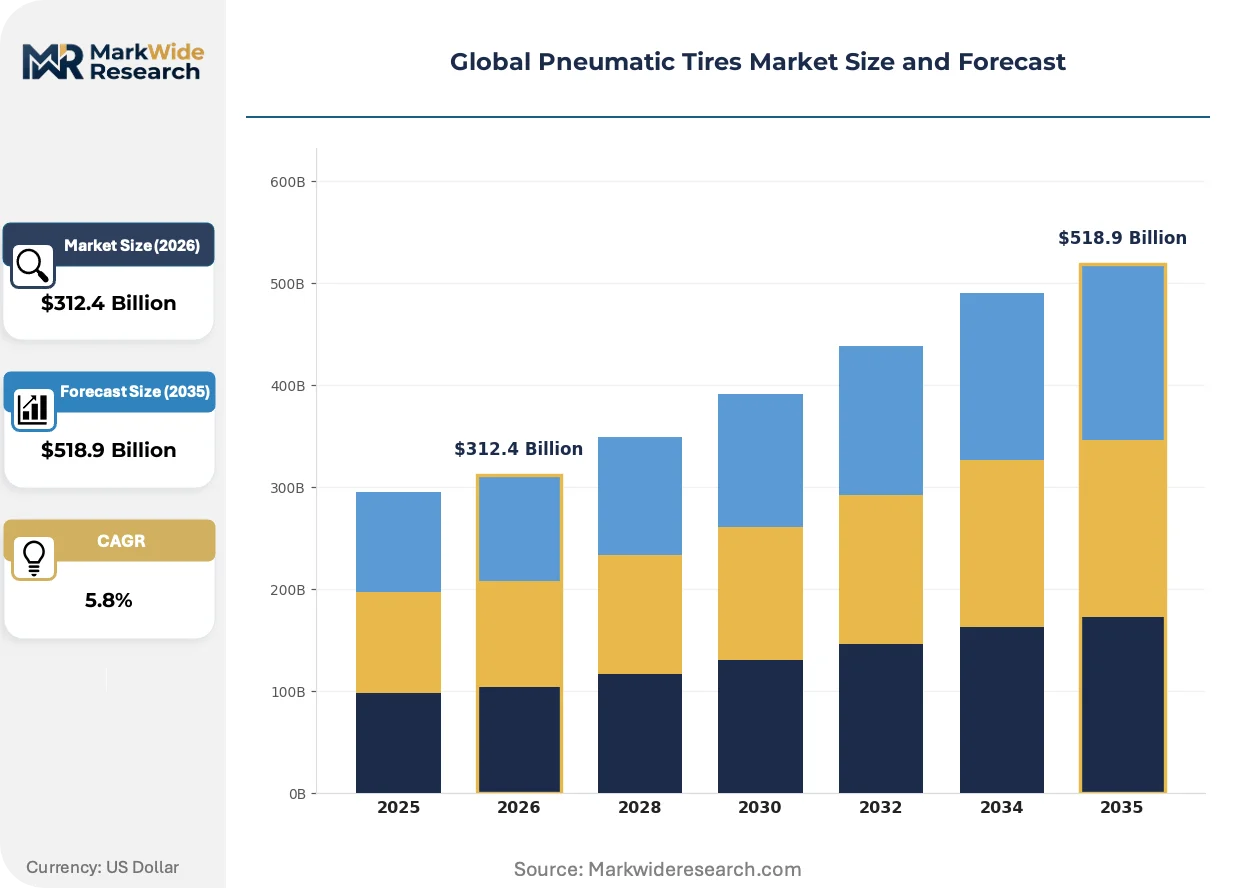
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $518.9 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Tubeless Tires, Specialty Tires End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Equipment Application: On-Road, Off-Road, Racing, Agricultural Distribution Channel: Online Retail, Brick-and-Mortar, Wholesalers, Distributors |
| Companies Covered | Michelin, Continental AG, Bridgestone Corporation, Goodyear Tire & Rubber Company, Hankook Tire & Technology, Yokohama Rubber Co., Ltd., Kumho Tire Co., Inc., Pirelli, Cooper Tire & Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pneumatic Tires Market Emerging Trajectories
Active sensor integration and sustainable material substitution are redefining product architecture while regulatory pressure on lifecycle emissions forces concurrent innovation across compound chemistry and manufacturing energy sourcing.
Intelligent tire systems are integrating pressure, temperature, and accelerometer sensors directly into tire carcasses to transmit real-time load and wear data to vehicle telematics platforms. Commercial fleet operators in Germany and the Netherlands are adopting these systems fastest due to insurance premium incentives and road toll optimization. This capability is integrating predictive maintenance scheduling into logistics software, compressing unplanned downtime and shifting supplier value propositions from product sales to uptime guarantees.
The EU F-Gas Regulation and REACH chemical restrictions are tightening material specifications simultaneously, forcing simultaneous compliance with fluorinated gas phase-downs and hazardous substance elimination. Tire manufacturers serving European markets must certify formulations against both frameworks or face market exclusion. Passenger and light truck segments bear the highest compliance burden as they serve price-sensitive consumers unwilling to absorb full cost pass-through.
Direct procurement relationships between large fleet operators and tire manufacturers are displacing traditional wholesale distribution in commercial segments. Logistics platforms with centralized vehicle pools in the United States and Western Europe negotiate frame contracts specifying performance metrics rather than unit prices. This restructuring concentrates purchasing power among fewer buyers and forces manufacturers to maintain regional service networks that distributors previously operated.
Global Pneumatic Tires Market Segmentation
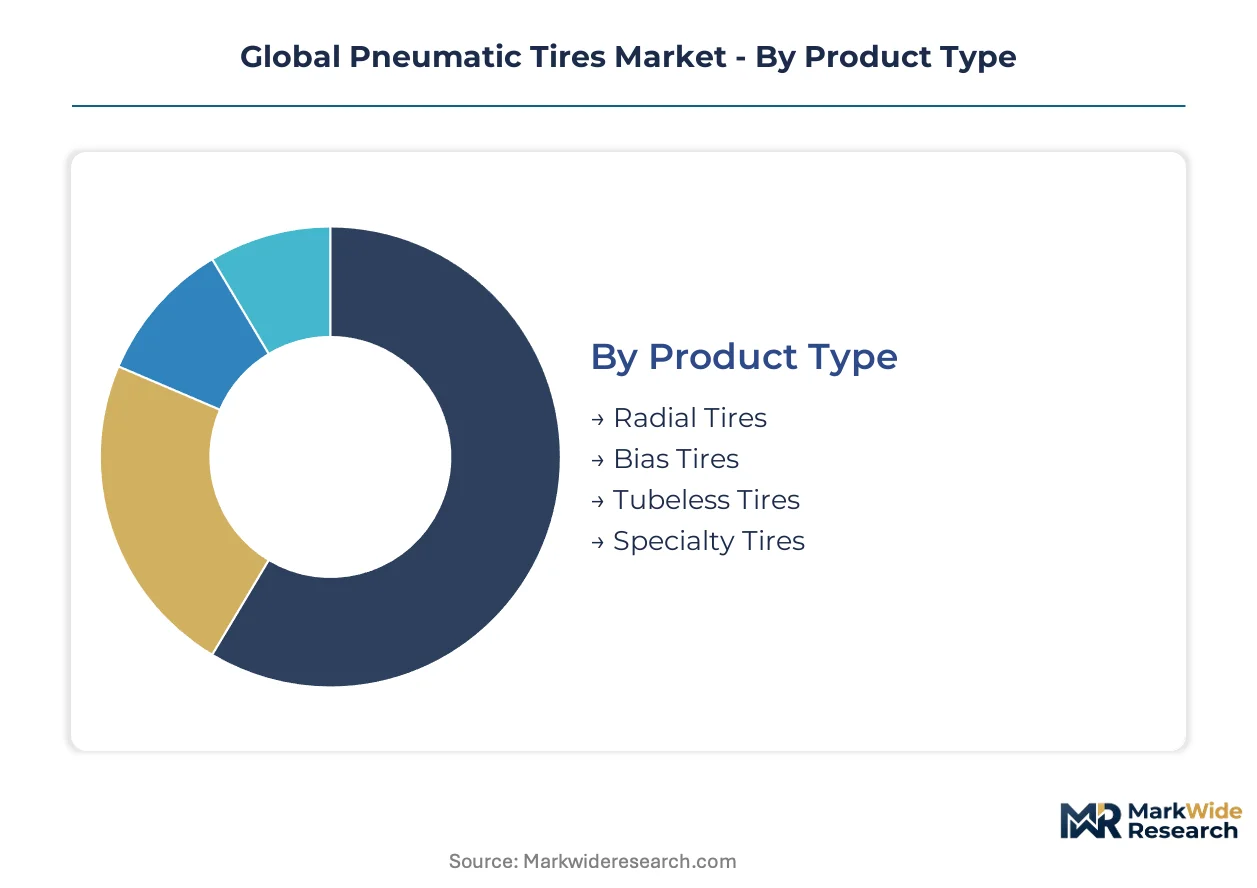
Pneumatic tire segmentation reveals how manufacturing scale, compound chemistry specialization, and fleet procurement centralization concentrate margin pools across distinct product architectures. Understanding these divides exposes where capacity investments align with demand trajectories.
Product Type:
Supply concentration in radial tire manufacturing dominates global capacity, with Southeast Asian natural rubber processing clusters and European silica compound R&D centers anchoring distinct competitive positions.
- Radial Tires:Steel-belted construction with perpendicular cord plies delivers superior fuel efficiency and tread longevity. Passenger and light truck fleets in Germany and Japan specify radial designs for original equipment fitment due to rolling resistance mandates under EU Green Deal and METI efficiency directives.
- Tubeless Tires:Elimination of inner tubes through airtight bead-to-rim sealing reduces weight and puncture failure modes. China's new energy vehicle manufacturers in Hefei and Guangzhou procurement clusters specify tubeless configurations for battery electric platforms seeking maximum range efficiency.
- Bias Tires:Diagonal ply construction suits low-speed, high-load applications where cost minimization outweighs rolling resistance penalties. Construction equipment and agricultural implement manufacturers specify bias designs for emerging market price sensitivity.
- Specialty Tires:Extreme-duty compounds for mining haul trucks and port container handlers command concentrated margin pools. Retreading viability in these segments extends casing life across severe duty cycles.
Radial tires absorb the bulk of installed capacity; tubeless configurations are expanding most quickly.
End User:
Cost tier differentiation separates premium original equipment specifications from replacement market price competition, with fleet scale determining procurement leverage intensity.
- Passenger Vehicles:Original equipment manufacturers specify low-rolling-resistance compounds and noise-optimized tread patterns. REACH-compliant silica-silane formulations dominate European fitment while China's MIIT labeling mandates shape domestic procurement.
- Commercial Vehicles:Long-haul trucking fleets negotiate lifecycle cost contracts bundling tires, mounting, and predictive maintenance. Retreading program participation compresses new tire volume in US and European fleet segments with centralized procurement platforms.
- Two-Wheelers:High-volume, low-margin production concentrates in India and Southeast Asia for domestic consumption and export. Bias construction dominates due to cost constraints and lower speed operational envelopes.
- Heavy-Duty Equipment:Mining and construction applications demand cut-resistant compounds and reinforced sidewalls. Extreme load ratings justify premium pricing independent of passenger vehicle commodity cycles.
Passenger vehicles command the largest revenue base; commercial vehicle tire-as-a-service contracts are climbing the fastest.
Application:
Volume concentration in on-road segments contrasts with margin concentration in specialized environments where performance failure carries catastrophic cost consequences.
- On-Road:Highway and urban pavement applications dominate unit volume with standardized load and speed ratings. NHTSA uniform quality grading and EU tire labeling directives shape consumer visible performance differentiation.
- Off-Road:Construction, mining, and logging environments demand reinforced carcasses and deep-lug tread patterns. Casing durability for multiple retread cycles determines total cost of ownership calculations.
- Agricultural:Soil compaction minimization and traction in variable field conditions drive flotation tire designs. Seasonal demand patterns in North American and European planting cycles create inventory management complexity.
- Racing:Motorsport-derived compound technology transfers to ultra-high-performance street tires. Extreme temperature tolerance and grip consistency justify development cost recovery through premium pricing tiers.
On-road applications absorb the bulk of installed capacity; agricultural specifications are gaining share fastest amid precision farming mechanization.
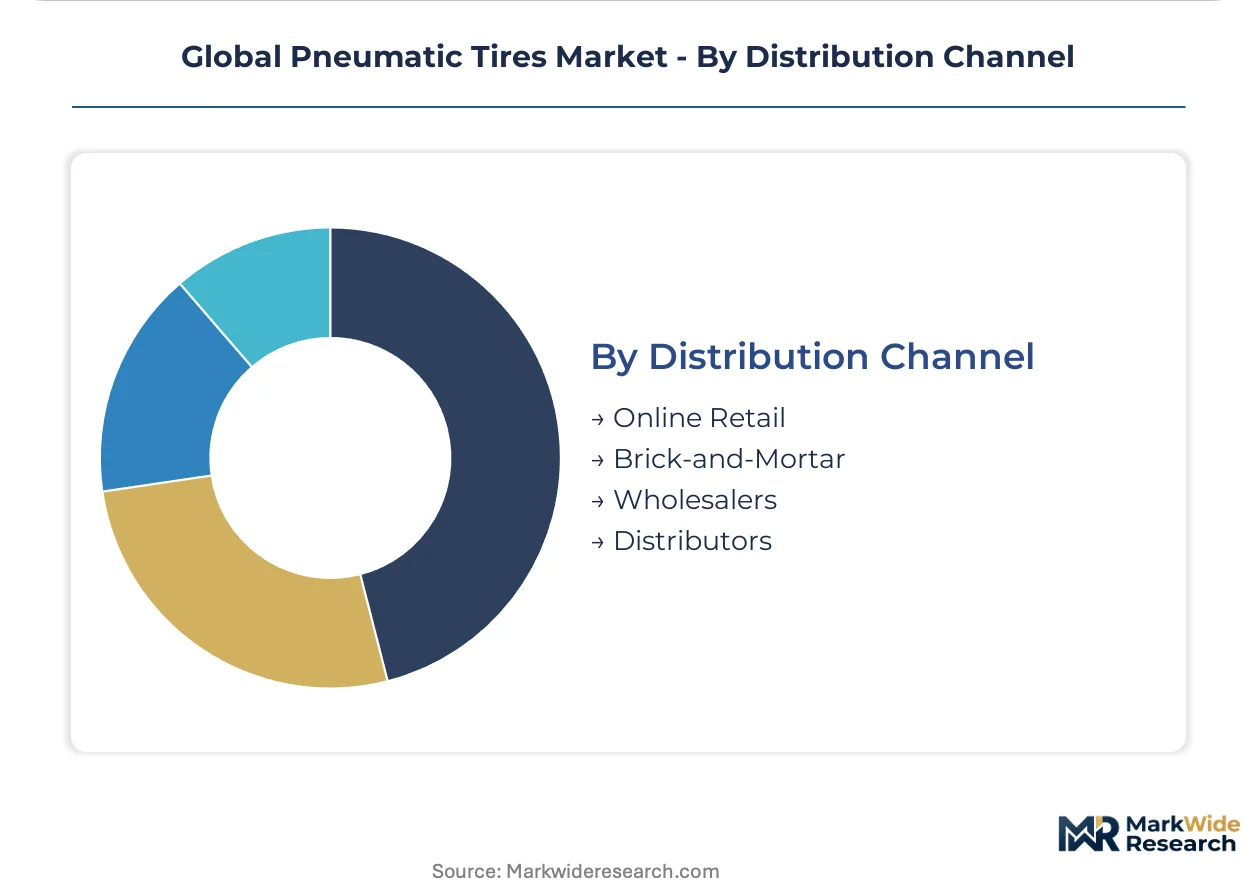
Distribution Channel:
Customer type fragmentation between individual consumers, independent repair shops, and centralized fleet operators forces parallel channel strategies with distinct service intensity requirements.
- Brick-and-Mortar:Tire retail chains and independent dealers provide mounting, balancing, and alignment services. Immediate availability and installation expertise defend this channel against pure-play online competition.
- Wholesalers:Regional inventory aggregation serves independent repair shops and smaller fleet operators lacking direct manufacturer relationships. Credit terms and assortment breadth sustain intermediary relevance.
- Online Retail:Direct-to-consumer shipment with third-party installation partnerships expands price-transparent comparison shopping. Fitment data accuracy and return logistics complexity constrain growth in specialized sizes.
- Distributors:Authorized distribution networks maintain manufacturer brand integrity and warranty administration. Technical training and field engineering support differentiate from commodity wholesale.
Brick-and-mortar channels absorb the bulk of transaction volume; online retail is expanding most quickly among replacement consumers seeking price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural rubber plantations in Thailand, Indonesia, and Vietnam anchor Southeast Asian feedstock supply for tire manufacturers worldwide. This raw material concentration shapes regional production economics and exposes compounders to climate-driven harvest volatility. Demand fragmentation across major automotive manufacturing clusters forces parallel compliance with divergent regulatory frameworks.
China
Domestic new energy vehicle production concentrates procurement demand in Shanghai, Guangzhou, and Hefei manufacturing clusters. MIIT tire labeling mandates and GB standards enforce energy efficiency classifications for domestic sales. BYD and CATL supply chain integration is pulling original equipment tire specifications toward low-rolling-resistance designs optimized for battery electric range.
Germany
EU REACH chemical restrictions and the F-Gas Regulation impose dual compliance burdens on compound formulations sold into European markets. KBA vehicle certification requirements cascade into tire homologation standards for original equipment fitment. Continental AG and BMW procurement partnerships in Bavaria and Lower Saxony exemplify integrated supply chain relationships between tire makers and premium automakers.
United States
Long-haul trucking fleet consolidation in the Midwest and Southeast is centralizing commercial tire procurement through frame contracts. NHTSA uniform tire quality grading shapes consumer-visible performance differentiation in replacement markets. Goodyear Tire & Rubber Company maintains manufacturing presence in Ohio and Oklahoma to serve domestic original equipment and replacement demand.
India
Commercial vehicle expansion and logistics infrastructure investment are creating whitespace for radial tire penetration in medium and heavy-duty segments. BIS certification requirements and PLI scheme incentives for automotive component manufacturing are tightening quality standards. Apollo Tyres and MRF production facilities in Tamil Nadu and Gujarat serve domestic demand and export markets across South Asia and Africa.
Japan
METI efficiency directives and JIS standards enforce rolling resistance and noise performance thresholds for domestic market sales. Bridgestone Corporation and Yokohama Rubber Co., Ltd. anchor production in Kanto and Kansai industrial corridors. Motorsport-derived technology transfer programs support premium tier positioning in global original equipment procurement.
Global Pneumatic Tires Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue smart tire integration and sustainable material substitution as differentiation vectors. The vendor base clusters around three maturity tiers: integrated multinational compounders with captive R&D facilities, regional specialists serving price-sensitive replacement markets, and technology-focused entrants developing sensor-embedded architectures. Strategic archetypes include scale-driven volume players, premium-tier performance specialists, and service-integrated fleet solution providers. Competitive intensity manifests through manufacturing capacity expansion in Southeast Asian natural rubber processing zones and strategic partnerships with electric vehicle original equipment manufacturers.
Within the integrated multinational tier, Michelin, Continental AG, and Bridgestone Corporation exemplify distinct competitive positioning strategies. The French tire maker anchors premium tier positioning through motorsport technology transfer and advanced silica compound research programs. Continental AG occupies a position defined by integrated tire sensor systems and digital fleet management service bundling. Bridgestone Corporation represents the volume-anchored archetype through deep partnerships with Japanese and North American automakers. These three entities collectively illustrate how geographic origin, corporate structure, and strategic emphasis combine to create defensible market positions without direct product or technology claims.
| Leading Market Players |
|---|
| Michelin |
| Continental AG |
| Bridgestone Corporation |
| Goodyear Tire & Rubber Company |
| Hankook Tire & Technology |
| Yokohama Rubber Co., Ltd. |
| Kumho Tire Co., Inc. |
| Pirelli |
| Cooper Tire & Rubber Company |
| Others |
Supply Flow & Price Mechanics
Backward integration into Thai and Indonesian natural rubber processing anchors both supply security and margin control for compounders serving European and North American automakers. This upstream control over feedstock costs insulates premium-tier manufacturers from commodity volatility while forcing mid-tier competitors into spot-market exposure that compresses their pricing flexibility.
Pricing Analysis
Warranty and service bundling separate contract structures across the market, with fleet-as-a-service agreements incorporating mounting, rotation, and predictive maintenance against unbundled replacement transactions. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by rolling-resistance certification grade and silica-silane compound sophistication. Cost compression in the economy tier is intensifying because Chinese domestic automakers are consolidating procurement volume around state-owned tire suppliers. Replacement consumers in Southeast Asian two-wheeler segments exhibit the highest price sensitivity, while German premium OEMs accept substantial premiums for REACH-compliant homologated fitments.
Supply Chain Analysis
Natural rubber supply rests on Thai, Indonesian, and Vietnamese plantation output that feeds calendering and extrusion operations across East Asian manufacturing hubs. Precipitated silica from European specialty chemical producers and steel bead wire from Chinese metallurgical plants constitute critical secondary inputs. Single-source vulnerability concentrates in Southeast Asian latex harvesting, where El Niño-driven drought patterns disrupt tapping schedules and inflate compounder raw material costs. Distribution runs through authorized networks for OEM fitment and wholesale intermediaries for fragmented replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural rubber plantation capacity expansion lags tire manufacturing scale-up, propping pricing power among integrated compounders with captive upstream assets. This supply-constrained structure favors stakeholders with backward integration or long-term offtake agreements.
For Market Incumbents: Cement premium positioning by accelerating silica-silane R&D investment and securing exclusive motorsport technology transfer pipelines. Defend against Chinese state-owned entrants by deepening direct procurement relationships with European and Japanese automakers. Prioritize certification investment for EU REACH and F-Gas Regulation compliance to maintain market access. For New Entrants and Emerging Players: Enter via India's underpenetrated radial tire segment for medium and heavy-duty commercial vehicles, where infrastructure investment outpaces domestic manufacturing capacity. Target agricultural flotation tire specifications in North American precision farming corridors as a second white-space vector. Pursue tire-as-a-service partnerships with logistics platforms seeking per-kilometer pricing models. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated multinationals seeking sensor-embedded tire capabilities or Southeast Asian manufacturing footprints. Five-to-ten-year viability hinges on compound formulation talent retention and smart tire certification completion against UN ECE R141 standards. Monitor EU carbon border adjustment mechanism implementation timing as the critical inflection signal for low-rolling-resistance design premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Rubber Processing | Captive Thai and Indonesian plantation supply insulates margin from weather-driven commodity swings. |
| Smart Tire Sensor Certification | UN ECE R141 validation unlocks OEM fitment for pressure and tread depth monitoring systems. |
| Silica-Silane Compound R&D Expansion | Advanced wet grip formulations satisfy EU Green Deal rolling-resistance mandates for premium positioning. |
| Tire-as-a-Service Platform Launch | Per-kilometer contracts with German and Dutch fleet operators compress competitor replacement volume. |
| REACH-Compliant Formulation Investment | Polycyclic aromatic hydrocarbon elimination secures European market access against regulatory exclusion risk. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with tire R&D directors, OEM procurement leads, fleet operations managers, and aftermarket distribution heads. ECHA substance restriction databases, NHTSA uniform quality grading reports, and MIIT tire labeling directives provided regulatory validation. Bottom-up volume modeling across product types and end-use segments triangulated against top-down automotive production forecasts.
Segment-level granularity modeled radial, tubeless, bias, and specialty tire architectures separately across passenger, commercial, two-wheeler, and heavy-duty equipment end uses. Geographic disaggregation captured country-specific regulatory clusters and manufacturing footprint distributions. CAGRs derived from compound annual trajectory analysis of unit demand and average selling price evolution. Electric vehicle original equipment procurement concentration and retreading substitution rates served as industry-specific forecast modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural rubber harvest disruption scenarios or accelerated EU carbon border adjustment implementation. Projections reflect assumptions regarding fleet electrification pacing, REACH enforcement intensity, and Southeast Asian plantation yield stability. A small set of named triggers—F-Gas Regulation phase-down acceleration, Chinese NEV subsidy policy shifts, and German KBA homologation timeline changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Green Tires Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Global Advanced Tires Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Tire Inflating Machine Market