
 Online Car-Hailing Service Market | 2026-2036
Online Car-Hailing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Online Car-Hailing Service Market Insights
Platform licensing revenue is reshaping competitive economics as operators monetize driver data and algorithmic dispatch tools beyond per-ride commissions. Uber Technologies Inc. leverages its global network density to sustain pricing power in high-frequency urban corridors. Didi Global Inc. anchors its position through in-house mapping and autonomous-vehicle R&D pipelines. Grab Holdings Inc. differentiates by embedding financial services and delivery logistics within its super-app architecture.
Online car-hailing services are digital platforms that algorithmically match passengers with available drivers using GPS triangulation, dynamic pricing engines, and real-time demand-forecasting models, primarily serving urban mobility and commercial transportation needs. Ride-hailing commands the dominant share of transaction volume due to its immediacy and reliability for time-sensitive trips, while electric vehicle fleets represent the fastest-expanding vehicle category as municipalities mandate zero-emission zones. Luxury services concentrate margin pools through premium pricing and contracted driver standards, whereas carpooling remains structurally constrained by route-optimization complexity and passenger coordination friction.
The US Department of Transportation enforces safety standards for commercial ride-hail operations through NHTSA guidelines, while the EU AI Act imposes algorithmic transparency requirements on automated dispatch and pricing systems. India's Motor Vehicle Aggregator Guidelines issued by the Ministry of Road Transport mandate GPS integration and driver background verification protocols. Stakeholders must monitor how fragmented national licensing regimes and emerging data-localization mandates affect cross-border platform scalability and capital allocation priorities.
Market Dynamics
Fleet electrification mandates and algorithmic dispatch optimization are compressing operator margins while simultaneously raising barriers to entry for capital-constrained regional platforms.
Growth Catalysts
- EU Green Deal vehicle-emission standards:Zero-emission zone mandates in Paris, Berlin, and Amsterdam are accelerating EV fleet turnover and creating dedicated charging infrastructure partnerships.
- Corporate travel program expansion:Business travelers across Fortune 500 procurement departments are consolidating preferred vendor agreements with integrated expense management platforms.
- GPS triangulation and dynamic pricing engines:Real-time demand-forecasting models are reducing passenger wait times below three minutes in dense urban corridors.
Market Restraints
- EV battery supply concentration:Lithium-ion cell production clusters in China and South Korea expose fleet operators to raw material price volatility and geopolitical supply disruptions.
- Driver background verification protocols:India's Motor Vehicle Aggregator Guidelines impose multi-week onboarding delays that constrain peak-demand capacity scaling.
- Algorithmic transparency requirements:The EU AI Act mandates explainable dispatch logic, increasing compliance costs for machine-learning pricing systems.
Strategic Opportunities
- Autonomous-vehicle R&D pipelines:Convergence of LiDAR perception systems and edge-computing hardware is enabling pilot deployments in geofenced districts.
- Super-app financial services embedding:Digital wallet and micro-lending integration within ride platforms captures transaction data for credit-scoring adjacent revenue streams.
- India's metropolitan corridor densification:Bangalore and Mumbai's expanding IT parks and special economic zones concentrate commuter demand along predictable arterial routes.
Industry Challenges
- Cross-border data-localization mandates:Fragmented national licensing regimes in Southeast Asia and the Middle East force redundant server infrastructure investments.
- Driver retention and gig-worker classification:Labor court rulings in California, the United Kingdom, and Brazil are redefining contractor status and benefit obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Car-Hailing Service Market |
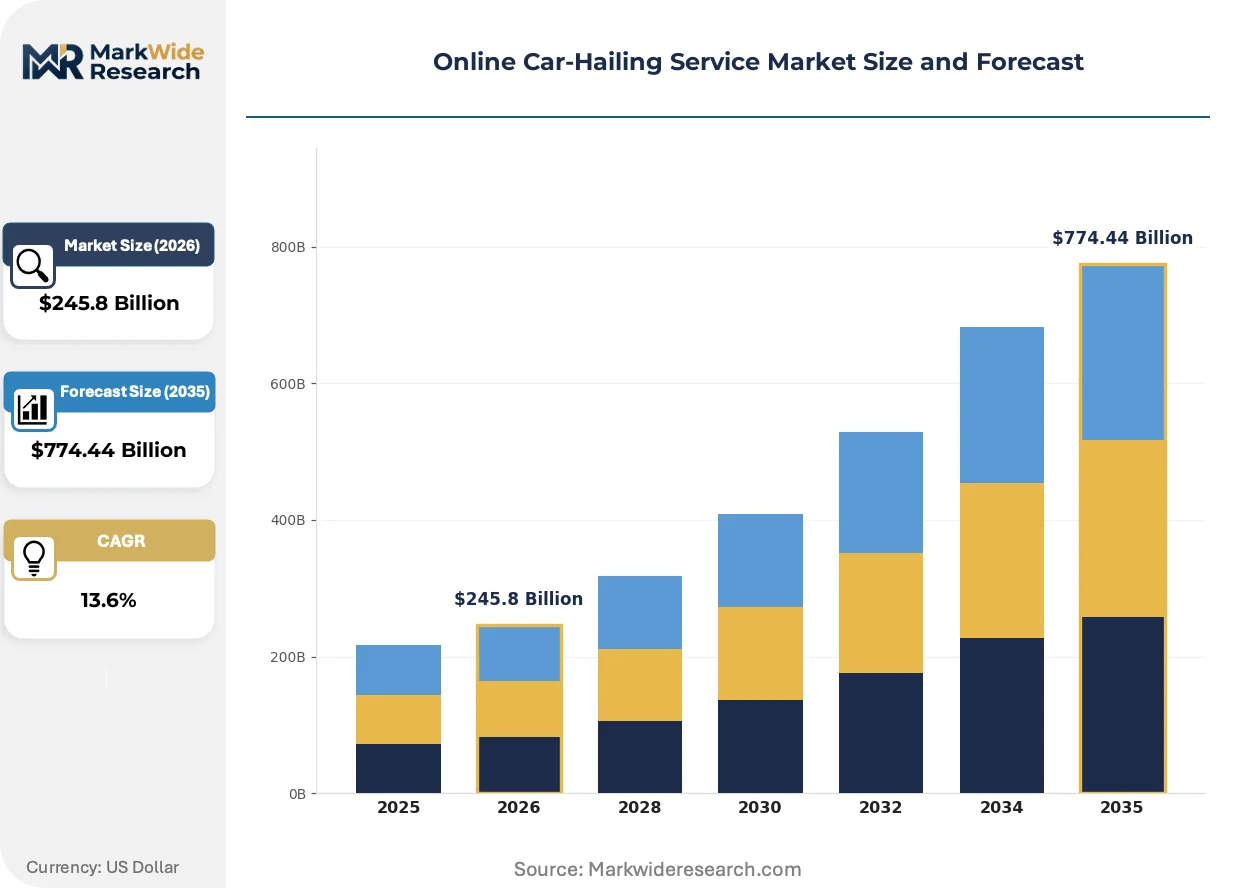
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $774.44 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Sharing, Ride-Hailing, Carpooling, Luxury Services Customer Type: Business Travelers, Daily Commuters, Tourists, Students Vehicle Type: Sedans, SUVs, Vans, Electric Vehicles Application: Urban Mobility, Intercity Travel, On-Demand Delivery, Rental Services |
| Companies Covered | Uber Technologies Inc., Lyft Inc., Grab Holdings Inc., Bolt Technology OÜ, Didi Global Inc., Ola Cabs, inDrive, Gett, BlaBlaCar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Car-Hailing Service Market Trends and Innovations
Autonomous dispatch algorithms and embedded financial ecosystems are dissolving the traditional boundaries between mobility, payments, and logistics platforms.
Machine-learning route-optimization engines trained on historical traffic patterns and event-calendar data are rendering obsolete static zone-based driver positioning. Fleet operators in Singapore and Dubai are deploying these systems to reduce empty-mile ratios below twelve percent. The compression in driver downtime is shifting unit economics toward utilization-rate metrics rather than per-ride commission structures.
The EU AI Act's algorithmic transparency requirements are forcing platforms to maintain auditable logs of pricing surge triggers and driver-ranking criteria. This regulatory friction is diverting engineering resources from feature development toward compliance documentation. Premium service tiers in Germany and France are responding by marketing human-override customer support as a differentiated value proposition.
Corporate procurement departments are consolidating travel spend through centralized booking platforms that negotiate volume-based rate caps with preferred mobility providers. This buyer concentration is displacing direct-to-consumer app downloads for weekday business trips in London, New York, and Tokyo. After-hours and weekend demand remains fragmented across multiple consumer-facing platforms.
Online Car-Hailing Service Market Segmentation
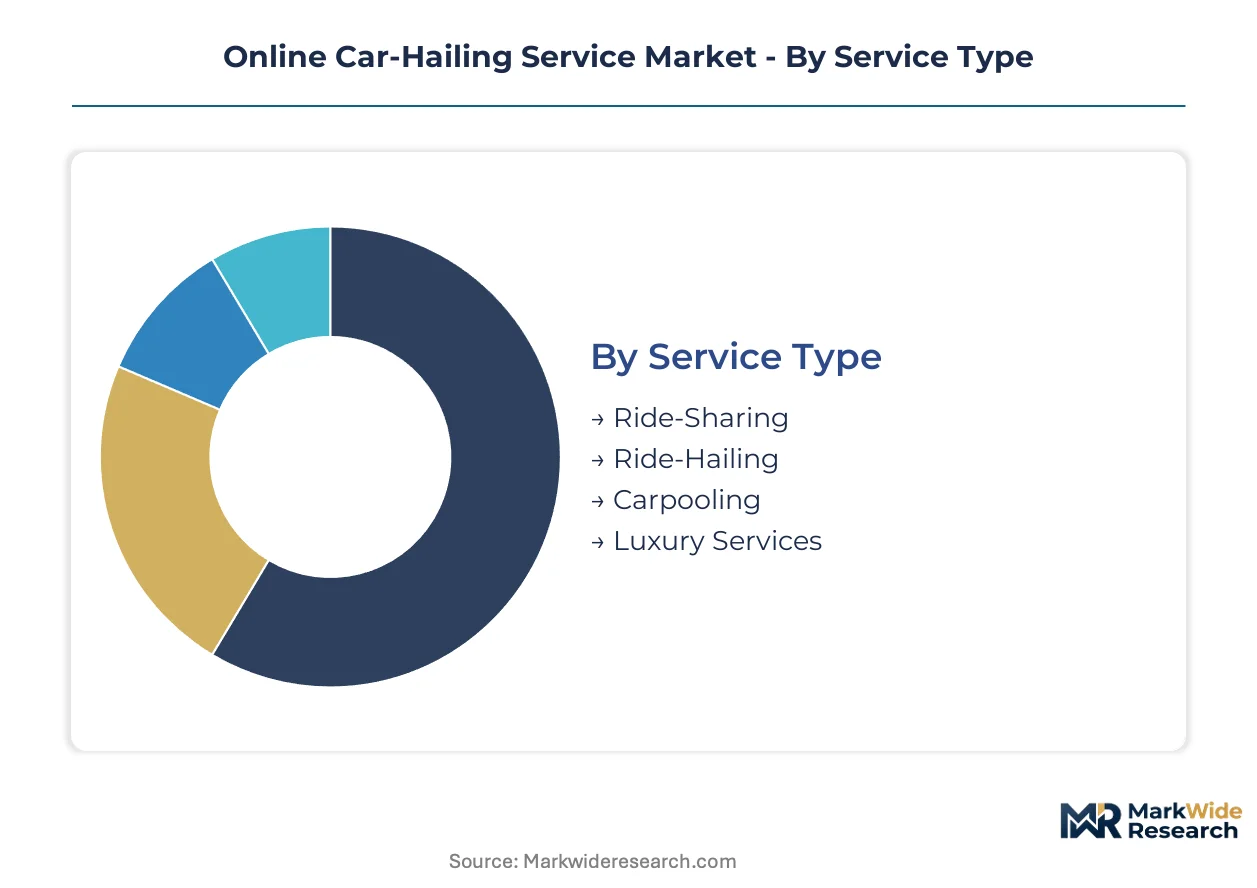
Segmentation in the online car-hailing service market reveals divergent operational models and margin structures. Each dimension exposes distinct capital intensity requirements and regulatory exposure profiles that shape platform strategy.
Service Type:
After-sales service intensity varies sharply across service models, with luxury tiers demanding dedicated account management while carpooling operates on minimal intervention.
- Ride-Hailing:On-demand matching algorithms connect passengers with nearest available drivers through GPS triangulation and dynamic surge pricing. Corporate travel programs in London and New York consolidate procurement spend here, compressing margins through volume-based rate caps.
- Ride-Sharing:Multi-passenger pooling algorithms optimize route efficiency by matching travelers with similar origin-destination pairs. Bangalore's IT corridor densification drives adoption among cost-conscious commuters facing congested arterial roads.
- Carpooling:Pre-scheduled coordination platforms reduce per-mile costs through fixed-route matching. Structural friction from passenger synchronization constraints limits scalability in dispersed suburban markets.
- Luxury Services:Contracted driver standards and premium vehicle specifications command elevated pricing tiers. Paris and Dubai operators leverage this segment to offset EV fleet transition costs through higher per-trip yields.
By volume, ride-hailing leads. By growth pace, luxury services is ahead.
Customer Type:
Cost tier stratification separates enterprise procurement departments from discretionary individual spenders.
- Business Travelers:Fortune 500 procurement departments negotiate preferred vendor agreements with integrated expense management platforms. EU Green Deal compliance requirements increasingly filter supplier selection criteria.
- Daily Commuters:Recurring route predictability enables subscription pricing models and loyalty program retention mechanics. Mumbai's special economic zones concentrate demand along fixed morning and evening corridors.
- Tourists:Intermittent usage patterns with high price elasticity and destination discovery requirements. Airport transfer partnerships and multilingual driver matching address friction points.
- Students:Price-sensitive segment with concentrated demand around campus clusters and nightlife districts. Micro-lending integration within super-app architectures expands payment flexibility.
Business travelers generate highest per-user revenue. Students are expanding most quickly through campus-centric platform partnerships.
Vehicle Type:
Application context determines fleet composition, with urban density favoring compact configurations and intercity routes demanding larger capacity.
- Electric Vehicles:Zero-emission powertrains mandated by Amsterdam, Berlin, and Paris congestion zone regulations. Battery supply concentration in East Asia exposes operators to lithium price volatility and geopolitical disruption risk.
- Sedans:Standard four-door configurations optimized for single-passenger or small-group urban trips. Maintenance network density and parts availability support high utilization rates in mature markets.
- SUVs:Elevated seating capacity and luggage space serve airport transfers and group travel requirements. Higher capital costs and fuel consumption compress unit economics outside premium pricing tiers.
- Vans:Multi-passenger configurations for corporate shuttle contracts and event logistics. NHTSA commercial vehicle safety standards impose additional inspection and driver certification burdens in the United States.
Sedans dominate deployed fleet share. Electric vehicles are gaining share fastest through regulatory mandate acceleration.
Application:
Geography concentration patterns separate dense urban corridors from dispersed intercity corridors with divergent driver supply dynamics.
- Urban Mobility:High-frequency trips within metropolitan boundaries with sub-three-minute wait time expectations. Real-time demand forecasting models trained on historical traffic patterns enable predictive driver positioning.
- Intercity Travel:Scheduled longer-distance routes requiring driver return-trip optimization or passenger backfill coordination. India's Motor Vehicle Aggregator Guidelines mandate enhanced insurance coverage for cross-state operations.
- On-Demand Delivery:Parcel and food logistics integration within super-app architectures. Grab Holdings and similar platforms leverage existing driver networks to capture adjacent revenue streams.
- Rental Services:Hourly or daily vehicle access without driver provision. Digital key handoff and automated inspection workflows reduce operational overhead compared to traditional fleet management.
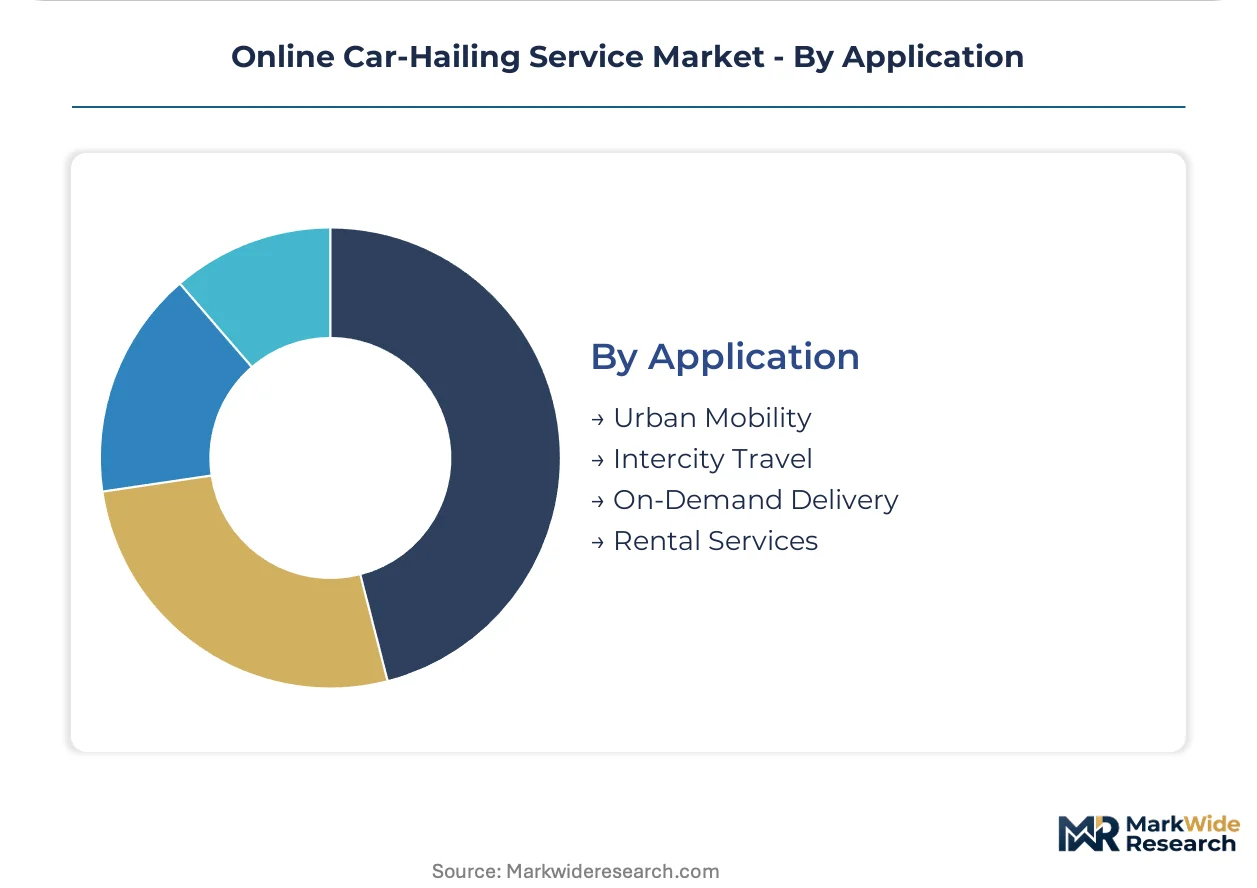
Urban mobility commands transaction volume leadership. On-demand delivery shows steepest expansion trajectory through logistics convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Corporate travel procurement dominates revenue concentration in mature Western markets. Emerging economies exhibit higher price elasticity with super-app convergence driving platform stickiness.
United States
Fortune 500 corporate travel programs consolidate preferred vendor agreements with integrated expense management platforms. NHTSA commercial vehicle safety standards govern driver certification and insurance minimums. New York and San Francisco corridors concentrate transaction density through high-frequency urban mobility demand.
Germany
EU Green Deal zero-emission zone mandates in Berlin accelerate EV fleet turnover timelines. KBA vehicle type approval requirements impose additional certification burdens on autonomous-vehicle pilot programs. Munich and Frankfurt business districts generate premium-tier demand through contracted driver service standards.
India
Bangalore IT corridor densification and Mumbai special economic zones concentrate commuter demand along predictable arterial routes. Motor Vehicle Aggregator Guidelines mandate GPS integration and multi-week driver background verification protocols. Delhi-NCR and Hyderabad expanding metro networks create first-mile last-mile integration opportunities.
China
Dual carbon goals and municipal zero-emission zone designations compress fleet electrification timelines in Beijing and Shanghai. MIIT data-localization requirements force redundant server infrastructure investments for cross-border platform operations. Shenzhen and Guangzhou autonomous-vehicle R&D clusters enable geofenced pilot deployments.
Brazil
São Paulo and Rio de Janeiro metropolitan congestion drives adoption of pooled ride-sharing among cost-conscious commuters. Labor court rulings redefine gig-worker contractor classification and benefit obligations. ANVISA-equivalent transport regulations govern commercial ride-hail operations at state level.
Online Car-Hailing Service Market Competitive Landscape
Capability concentration sits with technology-intensive specialists; scale advantage sits with network-density leaders. The market structures around three tiers: global platform operators with super-app architectures, regional specialists with localized regulatory expertise, and niche players focused on premium or pooled service segments. Dominant competitive moves include strategic partnerships for charging infrastructure access and portfolio diversification into adjacent logistics and financial services.
Within the global platform tier, Uber Technologies Inc. and Didi Global Inc. exemplify divergent geographic anchoring strategies. Uber leverages network density across North American and European urban corridors. Didi occupies a position centered on mapping technology and autonomous-vehicle development pipelines. Grab Holdings Inc. represents the super-app convergence archetype, embedding delivery logistics and digital wallet services within mobility platforms.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| Lyft Inc. |
| Grab Holdings Inc. |
| Bolt Technology OÜ |
| Didi Global Inc. |
| Ola Cabs |
| inDrive |
| Gett |
| BlaBlaCar |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's concentrated battery cell manufacturing capacity feeds directly into fleet operator procurement leverage, with lithium-ion supply tightness translating into elevated vehicle acquisition costs that compress per-trip margins across European and Indian markets.
Pricing Analysis
Long-term offtake agreements between major platforms and vehicle lessors dominate fleet procurement, while spot-market spot-hire arrangements cover surge capacity. Three-tier pricing structure across premium, standard, and economy levels separates corporate travel accounts from discretionary commuters and students. Cost compression in the economy tier is intensifying because algorithmic matching has commoditized base service differentiation. Corporate procurement departments exhibit lowest price sensitivity due to integrated expense management requirements, while students demonstrate highest elasticity with micro-lending dependency.
Supply Chain Analysis
Extended payment terms from Chinese battery manufacturers to vehicle assemblers have become standard, with supply-chain finance facilities bridging working capital gaps for fleet operators. Manufacturing concentrates in China, South Korea, and Germany for electric powertrains, while vehicle assembly localizes in Mexico, India, and Poland. Raw material dependencies span lithium carbonate, nickel sulfate, and rare-earth permanent magnets. Single-source vulnerability around cathode active material exposes operators to geopolitical disruption risk. Distribution runs through regional fleet management companies that handle maintenance and driver onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platforms face substitution pressure from autonomous-vehicle shuttle services and micromobility integration, requiring defensive repositioning around data moats and regulatory capture.
For Market Incumbents: Build switching-cost moats through embedded financial services and loyalty program lock-in. Prioritize backward integration into charging infrastructure partnerships to secure fleet electrification timelines. Defend against super-app convergence by controlling driver supply through exclusive employment contracts in key metropolitan corridors.
For New Entrants and Emerging Players: Build out white-label platform licensing for regional taxi cooperatives seeking digital transformation. Target India's tier-two cities where Motor Vehicle Aggregator Guidelines enforcement remains fragmented. Pursue campus-centric deployment models with university procurement departments as anchor accounts.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mapping and perception-software specialists over capital-intensive fleet operators. Long-term viability hinges on autonomous-vehicle R&D monetization pathways rather than per-ride commission sustainability. Monitor regulatory clarity on gig-worker classification as inflection signal for labor cost structure normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Secures fleet electrification timelines under EU Green Deal zero-emission mandates in Paris and Berlin. |
| Super-App Financial Services Integration | Captures transaction data for credit-scoring adjacent revenue streams across Southeast Asian markets. |
| Autonomous-Vehicle Pilot Deployment | Enables geofenced robotaxi operations leveraging Shenzhen LiDAR perception clusters. |
| Corporate Travel Procurement Consolidation | Locks volume-based rate caps with Fortune 500 integrated expense management platforms. |
| Regional Platform Licensing Agreement | Monetizes algorithmic dispatch tools to capital-constrained taxi cooperatives in tier-two Indian cities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory databases, and vehicle registration records. Interviews with fleet operations directors, platform product managers, driver supply coordinators, and municipal transport regulators informed demand-side and supply-side assessments. Bottom-up driver supply modeling triangulates against top-down transaction volume estimates from corporate expense management platforms.
Forecast inputs include vehicle electrification mandate timelines, battery cost trajectory assumptions, and algorithmic matching efficiency improvements. Segmentation dimensions span service type, customer archetype, vehicle propulsion architecture, and metropolitan corridor density. CAGRs derive from logistic curve fitting to historical adoption patterns and regulatory inflection points. Autonomous-vehicle deployment readiness and gig-worker classification rulings serve as scenario-branching variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-platform conglomerates would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Engineering Services Market
Automotive Services
Mobile Car Wash Service Market
Automotive Services
Driverless Sweeper Market
Automotive Services
Global Car Wash Market
Automotive Services
Automatic Vehicle Washing System Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Motorsports Market
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Auto Leasing Services Market
Automotive Services
Automotive Register Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market
Automotive Services
Cab Services Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Vehicle Conversion Market