
 Autonomous Intelligent Vehicle Market | 2026-2036
Autonomous Intelligent Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Intelligent Vehicle Market Outlook
Level 4 autonomy certification is collapsing from a premium niche into a baseline competitive requirement. Waymo LLC leverages its extensive real-world mileage accumulation to sustain operational credibility across urban testbeds. NVIDIA Corporation anchors the semiconductor layer with specialized compute platforms, while Mobileye Global Inc. differentiates through camera-first perception stacks that reduce hardware cost burdens for mass-market integration.
An autonomous intelligent vehicle integrates perception sensors, decision algorithms, and actuation systems to navigate without human intervention, typically requiring sub-10-millisecond latency in sensor-to-steering response loops for safety-critical maneuvers. Passenger vehicles command current deployment volumes, though freight logistics applications are expanding fastest as long-haul routes offer structured operational design domains with predictable edge cases. Machine learning represents the dominant technology investment area, while V2X communication infrastructure remains nascent outside government-funded corridor projects.
NHTSA in the United States, the EU AI Act alongside ECE R79/R157 frameworks in Europe, and MIIT connectivity standards in China collectively determine type-approval pathways and data governance obligations for cross-border fleet operations. These regulatory architectures directly constrain which sensor configurations and over-the-air update protocols gain market access. Stakeholders must track divergence between performance-based safety benchmarks and prescriptive technology mandates as the decisive variable for platform scalability.
Market Dynamics
Level 4 autonomy certification is collapsing from a premium niche into a baseline competitive requirement, compressing development timelines and forcing sensor stack standardization across OEM portfolios.
Growth Catalysts
- EU AI Act compliance mandates:Fleet operators in Germany and France accelerate perception system upgrades to meet algorithmic transparency requirements, pulling forward replacement cycles for non-compliant hardware.
- Freight logistics corridor densification:Structured operational design domains along the I-10 and I-75 corridors in the United States reduce edge-case exposure, lowering insurance premia for autonomous trucking deployments.
- Lidar cost curves:Solid-state manufacturing scale in Chinese component ecosystems compresses unit economics below the threshold for mass-market passenger vehicle integration.
Market Restraints
- Compute substrate concentration:Advanced driver-assistance system-on-chip supply concentrates among three foundry operators, exposing procurement schedules to geopolitical export control volatility.
- ECE R79/R157 homologation friction:European type-approval timelines for automated lane-keeping systems extend 18-24 months, delaying revenue recognition for platform launches.
- High-definition map maintenance burden:Centimeter-accurate localization requires quarterly refresh cycles, constraining operational expansion to corridors with guaranteed data vendor commitment.
Strategic Opportunities
- Middle Eastern regulatory sandboxes:UAE and Saudi Arabia permit driverless commercial operations without safety-driver mandates, creating first-mover data accumulation advantages for perception algorithm training.
- V2X infrastructure convergence:5G-V2X roadside unit deployment along Japan's Shin-Tomei Expressway enables cooperative perception, reducing onboard sensor count requirements for participating vehicles.
- Mine-site automation retrofit:Australian iron ore operations in the Pilbara region commission autonomous haulage conversions, bypassing public-road regulatory complexity entirely.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification expertise concentrates among Tier-1 suppliers, constraining OEM in-house development velocity and inflating program management overhead.
- Over-the-air update governance:China's MIIT cybersecurity review requirements for firmware modifications extend deployment windows, complicating rapid-response patches for perception edge cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Intelligent Vehicle Market |
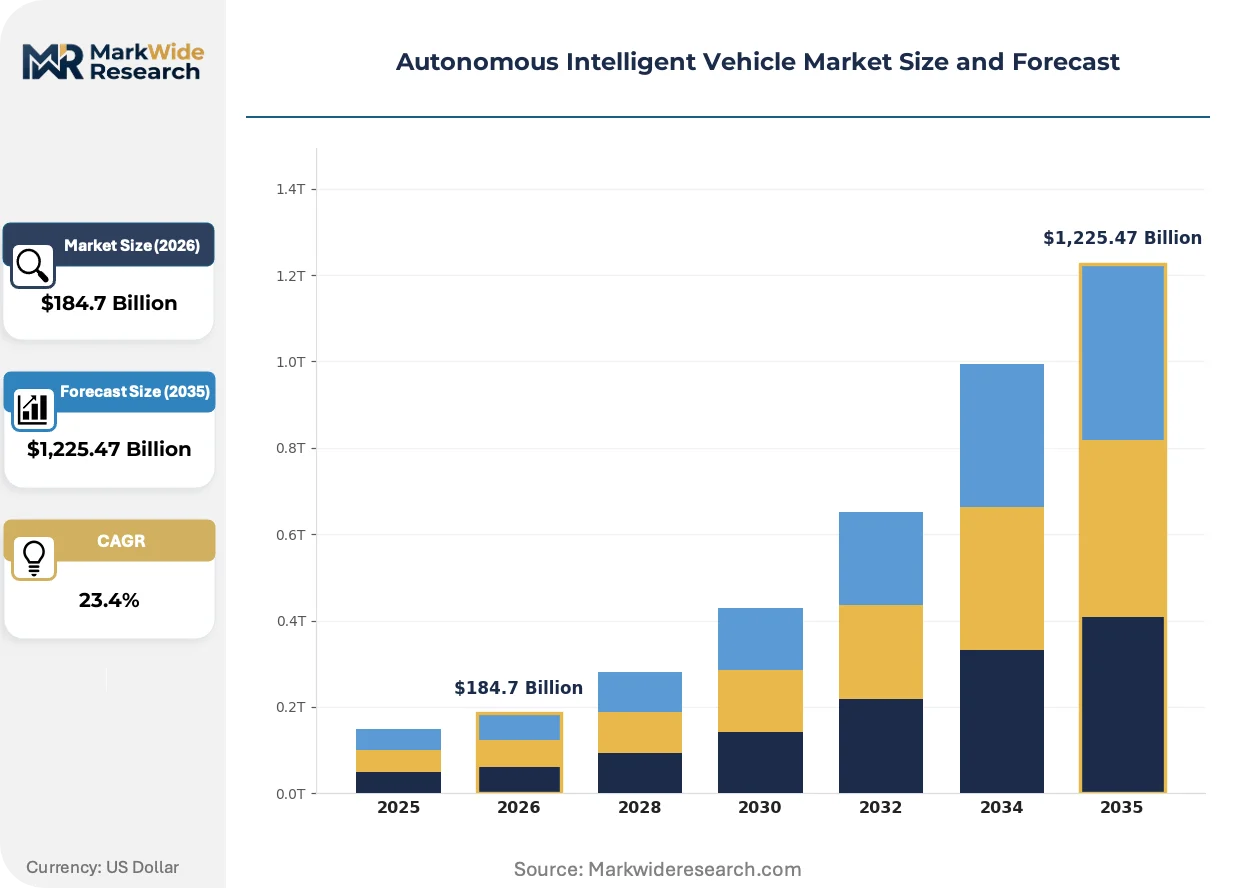
| Market Size in 2026 | $184.7 Billion |
| Market Size in 2035 | $1,225.47 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vehicles, Delivery Drones, Industrial Trucks, Agricultural Equipment Technology: LiDAR, Sensor Fusion, V2X Communication, Machine Learning End User: Ride-Hailing Services, Logistics Companies, Public Transportation, Private Owners Application: Urban Mobility, Freight Logistics, Emergency Services, Road Maintenance |
| Companies Covered | Waymo LLC, Tesla, Inc., Cruise LLC, Mobileye Global Inc., NVIDIA Corporation, Aurora Innovation, Inc., Zoox Inc., Baidu Inc., Aptiv PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Intelligent Vehicle Market Strategic Shifts
Sensor fusion architectures are fragmenting as camera-first and lidar-primary camps diverge on cost-performance tradeoffs, while regulatory pressure on algorithmic explainability forces new validation methodologies.
Lidar hardware is decomposing into modular sub-assemblies—transmitters, receivers, and scanning mechanisms—enabling tiered supplier participation. Chinese automotive OEMs integrate these disaggregated components directly, bypassing integrated module vendors. This vertical disintegration compresses bill-of-material costs and accelerates iteration cycles for custom range-resolution specifications.
The EU AI Act's risk-classification framework for autonomous systems imposes conformity assessment obligations on training data provenance and model documentation. European fleet operators now require algorithmic audit trails as a procurement precondition. German commercial vehicle manufacturers have responded by establishing dedicated AI governance offices with direct board reporting lines.
Fleet procurement criteria now weight total cost of ownership over upfront capital expenditure, privileging platform architectures with hardware upgrade paths. Ride-hailing operators in the United States negotiate sensor refresh guarantees extending across seven-year depreciation schedules. This contractual evolution favors suppliers with modular, backward-compatible product roadmaps over sealed-unit designs.
Autonomous Intelligent Vehicle Market Segmentation
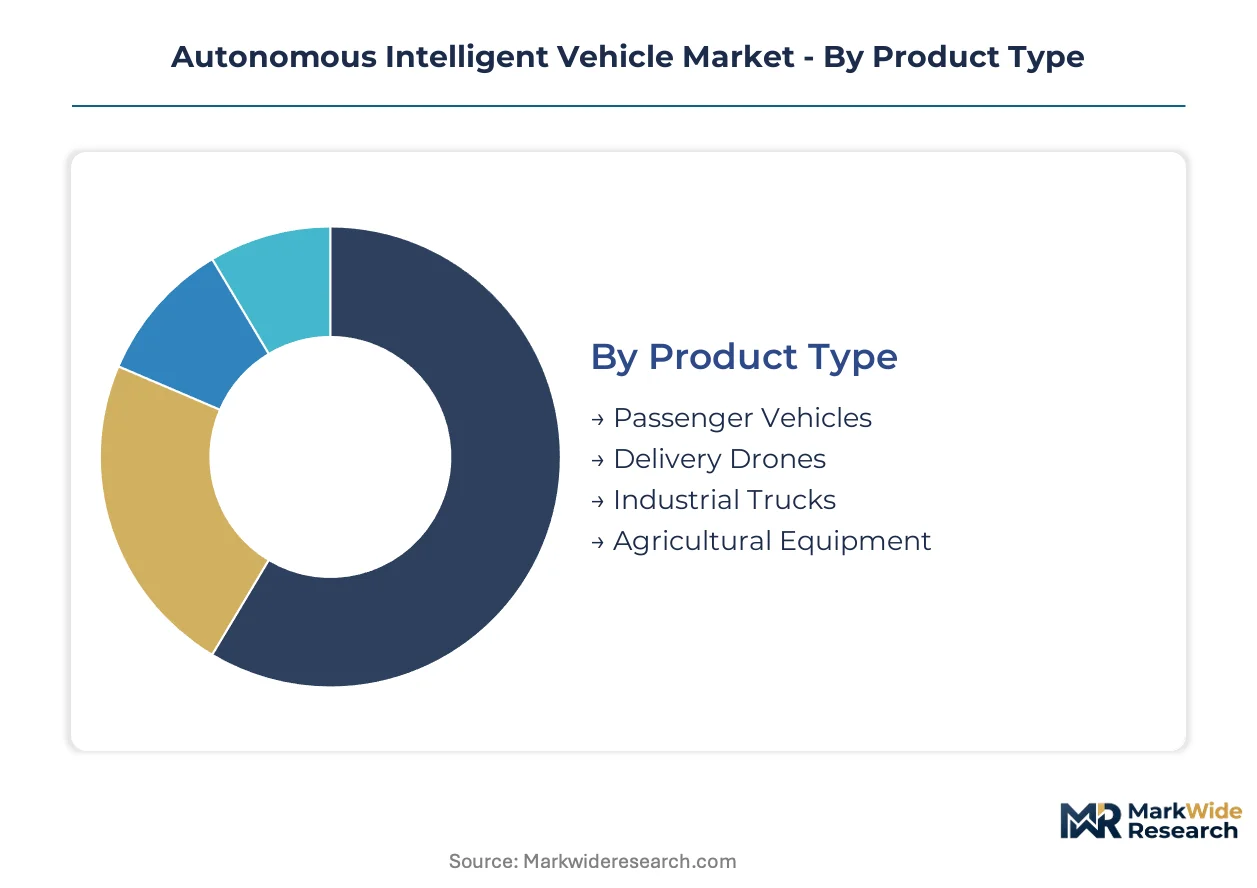
Regulatory frameworks fragment the autonomous intelligent vehicle market along technology readiness thresholds, with type-approval pathways determining which product configurations achieve commercial scale. Segment boundaries shift as compliance costs reshape procurement criteria across fleet operators and private buyers.
Product Type:
EU AI Act risk classification and NHTSA testing protocols create divergent certification burdens that segment product viability by operational domain complexity.
- Passenger Vehicles:Urban robotaxi deployments dominate current certification activity, with Waymo accumulating real-world mileage in San Francisco and Phoenix to satisfy NHTSA safety-driver exemption petitions. German OEMs accelerate Level 4 integration to meet ECE R79 lane-keeping mandates ahead of EU AI Act algorithmic transparency deadlines.
- Delivery Drones:Last-mile aerial autonomy operates under FAA Part 135 waivers in the United States and EASA specific-category approvals in Europe, constraining payload-range configurations to sub-25kg platforms. UAE regulatory sandboxes in Dubai permit beyond-visual-line-of-sight operations without equivalent pilot requirements, attracting fleet testing investment.
- Industrial Trucks:Mining haulage in Australia's Pilbara region bypasses public-road homologation entirely through site-specific exemptions.
- Agricultural Equipment:GPS-guided tractors with ISO 12100 functional safety compliance operate in controlled field environments with minimal edge-case exposure.
Passenger vehicles handle the majority of throughput; delivery drones are gaining share fastest through regulatory sandbox expansion.
Technology:
Hardware cost curves and computational substrate availability determine which sensing modalities achieve mass-market integration versus fleet-only deployment.
- LiDAR:Solid-state manufacturing scale in Chinese component ecosystems compresses unit economics below thresholds for passenger vehicle integration. Mechanical scanning variants retain dominance in long-haul trucking for 300-meter range requirements along I-10 corridor deployments.
- Sensor Fusion:Camera-radar-lidar integration dominates Level 4 urban deployments, with NVIDIA DRIVE platforms processing 2+ terabytes per hour of multimodal data. European fleet operators now require algorithmic audit trails for fused perception outputs under EU AI Act conformity assessment.
- V2X Communication:5G-V2X roadside unit deployment remains concentrated in Japan's Shin-Tomei Expressway and Chinese government-funded smart highway corridors.
- Machine Learning:Training data provenance documentation consumes 30-40% of development overhead for EU market entry.
Sensor fusion commands current deployment volumes; LiDAR shows the steepest cost-reduction trajectory enabling mass-market penetration.
End User:
Procurement scale and depreciation horizon differentiate fleet operator requirements from consumer purchase patterns.
- Ride-Hailing Services:Fleet operators negotiate seven-year sensor refresh guarantees, privileging modular hardware architectures with backward-compatible upgrade paths. Operational cost reduction targets in the United States drive consolidation around NVIDIA and Mobileye compute platforms.
- Logistics Companies:Structured operational design domains along interstate corridors reduce insurance premia for autonomous trucking, with freight operators prioritizing total cost of ownership over upfront capital expenditure.
- Public Transportation:Municipal procurement cycles extend 18-36 months, delaying revenue recognition for platform launches.
- Private Owners:Advanced driver-assistance systems dominate current penetration, with Level 4 private deployment constrained by liability frameworks.
Ride-hailing services concentrate the majority of current procurement volume; logistics companies are expanding most quickly through corridor densification.
Application:
Operational design domain predictability determines which use cases achieve regulatory clearance ahead of technical maturity.
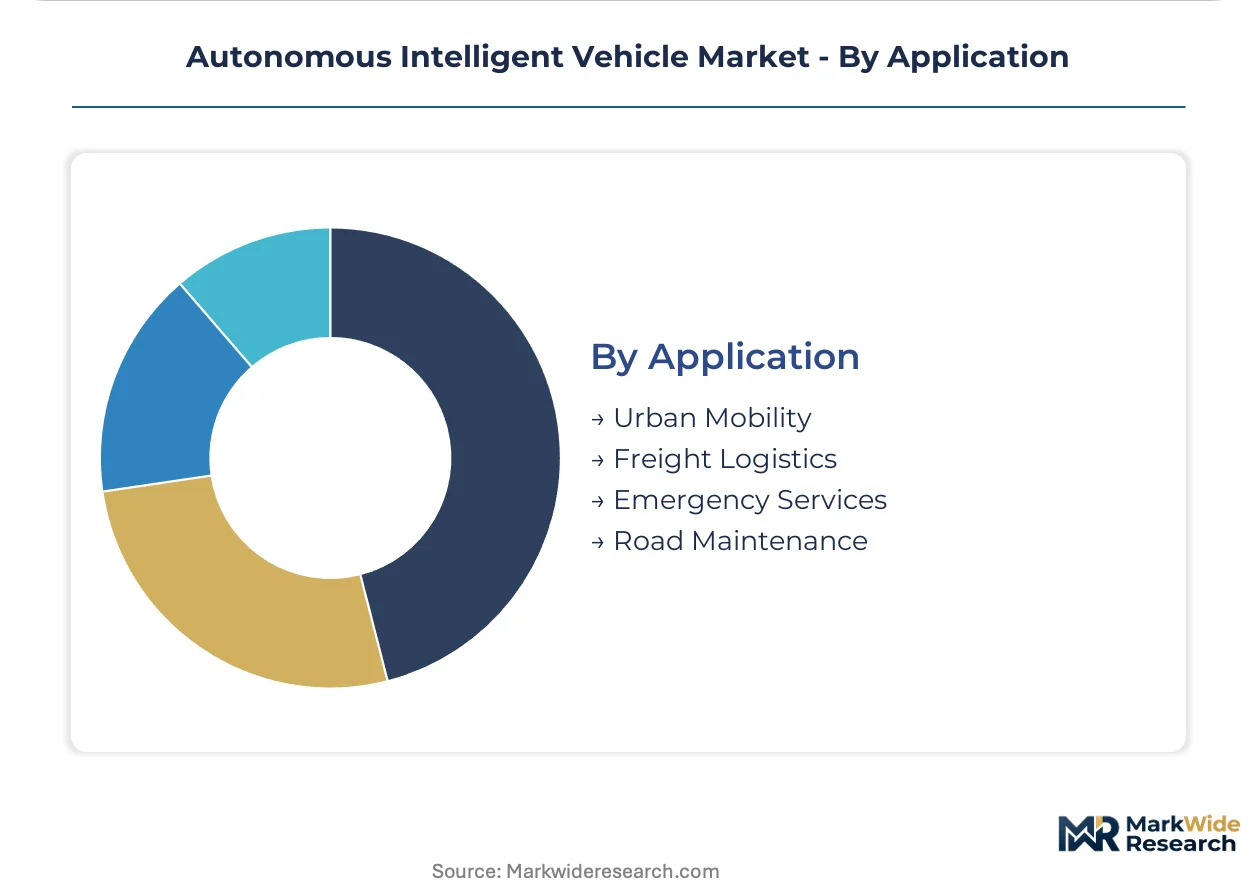
- Urban Mobility:Dense edge-case exposure requires sub-10-millisecond sensor-to-steering latency, constraining deployment to geofenced zones with high-definition map coverage. San Francisco, Phoenix, and Shenzhen dominate pilot activity.
- Freight Logistics:Long-haul routes offer predictable traffic patterns and limited pedestrian interaction, enabling driver-out operations on dedicated corridors before urban generalization.
- Emergency Services:Situational awareness requirements for unpredictable incident response delay autonomous deployment.
- Road Maintenance:Low-speed, closed-course operations permit earlier automation with reduced functional safety burdens.
Urban mobility absorbs the dominant share of development investment; freight logistics climbs the fastest on deployment timelines through operational design domain advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Germany and France absorb premium pricing for EU AI Act-compliant hardware, while Chinese buyers exploit domestic solid-state lidar cost curves to compress procurement budgets by half.
United States
NHTSA safety-driver exemption petitions concentrate deployment investment around San Francisco and Phoenix urban testbeds. The Federal Motor Carrier Safety Administration pilots autonomous trucking exemptions along I-10 and I-75 freight corridors. Waymo accumulates real-world mileage in these clusters to satisfy federal credibility thresholds for driverless commercial permits.
China
MIIT connectivity standards and GB homologation frameworks accelerate domestic OEM integration of disaggregated lidar sub-assemblies. Shenzhen and Beijing host the majority of robotaxi pilot deployments with municipal data governance sandbox permissions. Baidu anchors perception algorithm training through government-funded smart highway corridor projects.
Germany
ECE R79 lane-keeping mandates and impending EU AI Act algorithmic transparency deadlines compress Level 4 development timelines for premium passenger vehicle portfolios. KBA type-approval friction extends 18-24 months for automated systems, delaying revenue recognition. Stuttgart and Munich industrial clusters concentrate Tier-1 supplier functional safety engineering capacity.
Japan
METI-funded 5G-V2X roadside unit deployment along the Shin-Tomei Expressway enables cooperative perception trials that reduce onboard sensor requirements. Nagoya and Tokyo metropolitan areas host OEM validation programs for machine learning training data provenance documentation. Domestic procurement criteria weight total cost of ownership over upfront capital expenditure.
United Arab Emirates
MOHAP and Dubai Road and Transport Authority permit driverless commercial operations without safety-driver mandates, creating first-mover data accumulation advantages. Abu Dhabi and Dubai regulatory sandboxes attract fleet testing investment from perception algorithm developers. Seven-year sensor refresh guarantees emerge as standard contractual terms in regional ride-hailing procurement.
Autonomous Intelligent Vehicle Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive positioning across the semiconductor layer and the perception stack integration tier. Semiconductor specialists concentrate compute substrate supply among three foundry operators, exposing procurement schedules to geopolitical volatility. Camera-first perception integrators compete against lidar-primary hardware vendors on mass-market unit economics. Dominant competitive moves include strategic partnerships for training data access and geographic expansion into Middle Eastern regulatory sandboxes.
Within the technology-architecture tier, NVIDIA Corporation anchors specialized compute platform supply for multimodal sensor fusion processing, while Mobileye Global Inc. exemplifies camera-first perception stack differentiation that reduces hardware cost burdens for OEM integration programs. Waymo LLC occupies a position in the real-world mileage accumulation archetype, leveraging urban testbed deployment scale to sustain operational credibility for regulatory exemption petitions.
| Leading Market Players |
|---|
| Waymo LLC |
| Tesla, Inc. |
| Cruise LLC |
| Mobileye Global Inc. |
| NVIDIA Corporation |
| Aurora Innovation, Inc. |
| Zoox Inc. |
| Baidu Inc. |
| Aptiv PLC |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month KBA type-approval timelines in Germany concentrate inventory risk among Tier-1 suppliers, compressing their pricing power against OEMs while accelerating cost pass-through demands for EU AI Act-compliant perception hardware.
Pricing Analysis
After-sales sensor refresh guarantees extending across seven-year depreciation schedules now drive lifetime value for ride-hailing fleet operators, shifting revenue models from upfront hardware sales to long-term service contracts. Pricing stratifies across Level 4-certified, Level 2+-capable, and ADAS-basic tiers, with certification-grade differentiation widening spreads between urban robotaxi-grade and highway-assist configurations. Cost compression in solid-state lidar sub-assemblies is intensifying because Chinese OEMs integrate disaggregated components directly, bypassing integrated module vendors. Logistics companies exhibit the highest price sensitivity due to total cost of ownership procurement criteria, while premium passenger vehicle portfolios remain least sensitive to hardware premiums.
Supply Chain Analysis
Port congestion along transpacific trade lanes elevates inbound logistics costs for semiconductor substrates, exposing procurement schedules to container availability volatility. Advanced driver-assistance system-on-chip supply concentrates among foundry operators in Taiwan, South Korea, and the United States, drawing from silicon wafer and advanced packaging inputs. Single-source vulnerability in photonics components for lidar transmitters creates chokepoint exposure. Distribution runs through Tier-1 system integrators with direct OEM platform engineering relationships, constraining bypass opportunities for component specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation around NVIDIA and Mobileye compute platforms has shifted buyer power toward standardized architectures, fragmenting pricing leverage for sealed-unit perception vendors.
For Market Incumbents: Fortify backward integration into solid-state lidar sub-assembly production to capture cost compression from Chinese manufacturing scale. Deepen certification investment in ECE R79/R157 homologation expertise to accelerate KBA approval timelines against emerging camera-first competitors. Control channel relationships with ride-hailing operators through modular hardware roadmaps that guarantee seven-year refresh compatibility. For New Entrants and Emerging Players: Differentiate on algorithmic explainability documentation to satisfy EU AI Act procurement preconditions among German and French fleet operators. Target Middle Eastern regulatory sandboxes in UAE and Saudi Arabia for first-mover data accumulation without safety-driver mandates. Pursue mine-site automation retrofit opportunities in Australia's Pilbara region to bypass public-road homologation complexity entirely. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergence between performance-based safety benchmarks and prescriptive technology mandates determines platform scalability across jurisdictions. Acquisition targets should display ISO 26262 functional safety certification capacity and established AI governance offices with board reporting structures. The signal to watch is NHTSA safety-driver exemption petition approval velocity as an operational credibility inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Stack Standardization | OEM platform engineering teams consolidate around NVIDIA DRIVE and Mobileye EyeQ architectures to compress development timelines. |
| Regulatory Sandbox Expansion | UAE and Saudi Arabia permits enable driverless commercial operations without safety-driver mandates, accelerating data accumulation. |
| Vertical Disintegration | Chinese OEMs integrate disaggregated lidar sub-assemblies directly, bypassing integrated module vendors to compress bill-of-material costs. |
| AI Governance Office Establishment | German commercial vehicle manufacturers create dedicated compliance units with direct board reporting to satisfy EU AI Act audit trail requirements. |
| Freight Corridor Densification | Structured operational design domains along I-10 and I-75 reduce insurance premia for autonomous trucking deployments. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, ride-hailing fleet operations directors, and regulatory affairs specialists at KBA and NHTSA, and refined through secondary validation against SEC 10-K filings, vehicle production databases, IHS Markit registration data, and EMA-type approval records. Bottom-up segmentation modeling triangulated against top-down market sizing across passenger vehicle, delivery drone, industrial truck, and agricultural equipment configurations.
Variance decomposition across technology readiness thresholds, operational design domain complexity, and regional regulatory clusters shaped the analytical framework over the projection horizon. Modeled dimensions spanned autonomy level, sensing modality, end-user procurement scale, and application environment predictability. CAGRs derived from segment-level volume trajectories weighted by type-approval pathway maturity, with inputs including lidar cost curve assumptions and fleet operator depreciation schedule standardization.
Material uncertainties — NHTSA exemption petition velocity, EU AI Act enforcement calibration, and foundry capacity allocation shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory sandbox expansion and solid-state manufacturing scale. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
Driverless Cab Service Market
Autonomous Vehicles
Autonomous Taxi Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market