
 Saudi Arabia Tire Market | 2026-2036
Saudi Arabia Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Tire Market Intelligence
Fleet procurement in Saudi Arabia's commercial transport sector is shifting toward consolidated long-term supply contracts with tier-one tire suppliers. Bridgestone Middle East leverages its established dealer network across the Kingdom to secure fleet maintenance agreements. Michelin Arabia sustains premium positioning through original equipment partnerships with European vehicle assemblers serving the Saudi market. Hankook Tire and Technology competes on replacement cycle value, targeting price-sensitive operators in the growing light-truck segment.
A tire is a toroidal rubber-composite structure reinforced with steel belts, textile plies, and bead wires, manufactured through calendering, extrusion, and vulcanization processes to provide load-bearing capacity, traction, and shock absorption for wheeled vehicles. Radial construction dominates the Saudi aftermarket due to superior heat dissipation and fuel efficiency on the Kingdom's high-speed arterial highways. Passenger car tires occupy the largest volume share, while heavy-duty vehicle tires command the strongest margin pools due to specialized compound requirements and shorter replacement intervals under extreme operating temperatures. Off-road application tires are gaining traction in mining and construction zones near the Eastern Province's industrial cities.
SASO mandates compliance with Gulf Standardization Organization tire labeling and rolling-resistance protocols, while the Saudi Customs Authority enforces anti-dumping duties on select Asian-origin imports to protect domestic distribution channels. The Ministry of Transport's freight corridor expansions and the Riyadh Metro commissioning will reshape vehicle utilization patterns and tire wear profiles. Stakeholders must monitor SASO's planned alignment with United Nations Economic Commission for Europe regulations and the pace of domestic retreading facility investments to assess import substitution risks.
Market Dynamics
Fleet consolidation across Saudi Arabia's logistics corridor is compressing replacement cycles and forcing distributors to abandon spot-market procurement in favor of volume-commitment frameworks with certified radial suppliers.
Growth Catalysts
- Freight corridor expansion:The Ministry of Transport's arterial highway upgrades between Riyadh, Jeddah, and Dammam are accelerating commercial vehicle utilization rates and shortening tire replacement intervals across long-haul fleets.
- SASO labeling mandates:The Saudi Standards, Metrology and Quality Organization's rolling-resistance and wet-grip disclosure requirements are filtering out uncertified imports and redirecting procurement toward compliant radial products.
- E-commerce logistics density:Last-mile delivery fleet operators in Riyadh and Jeddah are scaling light-truck and van deployments, creating sustained aftermarket demand for speed-rated passenger-car tires.
Market Restraints
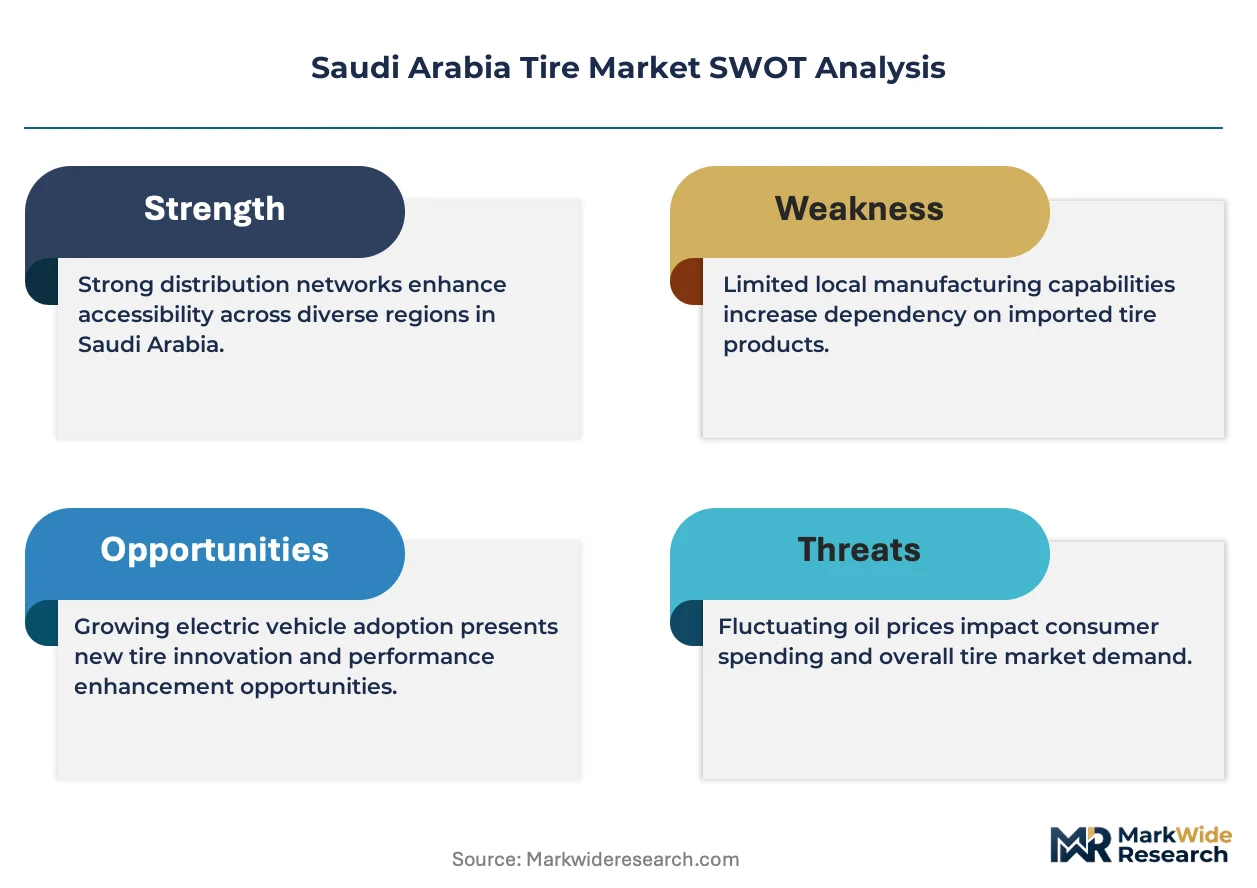
- Natural rubber price volatility:Thai and Indonesian latex supply disruptions transmit directly into Saudi distributor margins, compressing working capital flexibility for mid-tier dealers.
- Import concentration risk:Overreliance on containerized shipments through Jeddah Islamic Port creates single-point vulnerability during Red Sea transit disruptions or customs clearance bottlenecks.
- Retreading infrastructure gap:Limited domestic vulcanization and tread-winding capacity forces heavy-duty operators to import replacement casings or absorb premium new-tire costs.
Strategic Opportunities
- Eastern Province mining zones:Off-highway tire demand from phosphate and bauxite extraction sites near Jubail Industrial City remains underserved by specialized compound suppliers.
- Smart tire telemetry:Pressure-monitoring and tread-wear sensors are converging with fleet management platforms, enabling predictive replacement scheduling for logistics operators.
- NEOM construction logistics:The giga-project's heavy-equipment mobilization is creating temporary demand spikes for earthmover and articulated-dump-truck tires that outstrip standard inventory cycles.
Industry Challenges
- Certification timeline compression:SASO's planned alignment with United Nations Economic Commission for Europe regulations is forcing distributors to revalidate entire product portfolios simultaneously.
- Skilled mounting technician scarcity:Commercial tire service bays in secondary cities lack trained personnel for run-flat and low-profile fitments on premium European vehicle imports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Tire Market |
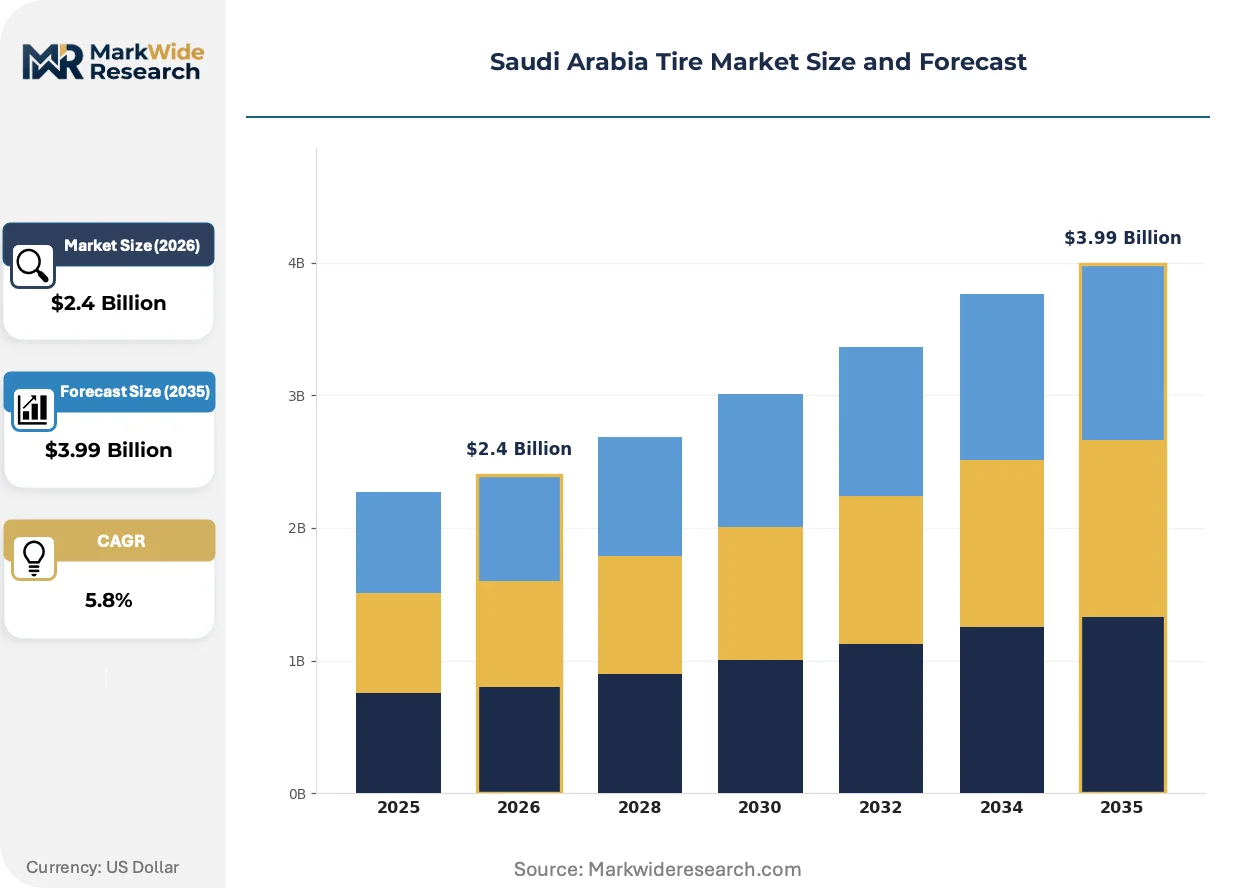
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Radial, Bias, Tubeless, Tube Vehicle Type: Passenger Cars, Light Trucks, Heavy-Duty Vehicles, Buses Distribution Channel: Online, Retail Stores, Wholesalers, Service Centers Application: On-Road, Off-Road, Racing, Industrial |
| Companies Covered | Continental AG, Yokohama Rubber Company, Bridgestone Middle East, Kumho Tire, Hankook Tire and Technology, Michelin Arabia, Pirelli & C. S.p.A, Toyo Tire Corporation, Goodyear Tire and Rubber Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Tire Market Strategic Shifts & Innovations
Material science advances and regulatory disclosure mandates are rewriting procurement criteria across Saudi Arabia's tire value chain, with heat-resistant compounds and connected monitoring systems displacing conventional selection frameworks.
Silica-reinforced tread compounds are displacing carbon-black formulations in high-performance summer tires destined for the Kingdom's asphalt highways exceeding 50°C surface temperatures. Premium passenger-car importers in Jeddah are specifying these formulations for OEM fitment to reduce rolling resistance and extend fuel economy. This material transition is converging with SASO's energy-labeling requirements to compress the viable product portfolio for distributors serving the luxury vehicle segment.
SASO's adoption of Gulf Standardization Organization tire labeling protocols is mandating wet-grip and noise-level disclosures on all retail packaging. Distributors must now maintain dual inventory streams—labeled stock for consumer replacement and bulk unlabeled shipments for fleet direct procurement. The regulation is compressing margin structures for smaller dealers lacking the warehouse management systems to track batch-specific certification documentation.
Fleet operators are consolidating maintenance spend under single-source contracts that bundle tires, mounting, balancing, and roadside assistance. Logistics companies serving the Riyadh-Dammam corridor are abandoning transactional garage relationships in favor of annual volume agreements with national distributor networks. This procurement compression is visible most acutely among cold-chain transporters where downtime costs exceed tire price differentials by an order of magnitude.
Saudi Arabia Tire Market Segmentation
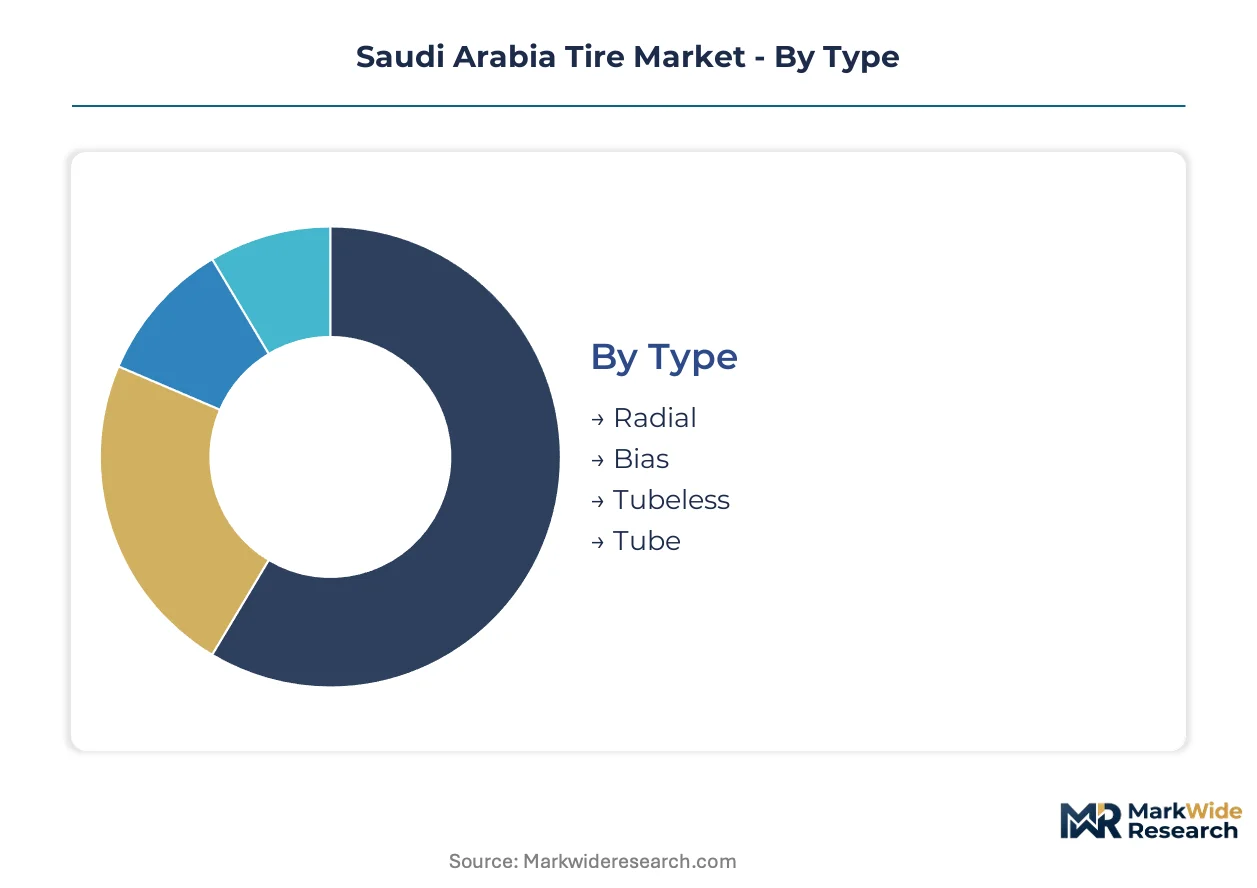
Saudi Arabia's tire procurement patterns fragment sharply across construction technology, vehicle duty cycles, and channel economics. SASO certification requirements and fleet consolidation are compressing viable segment combinations while opening specialized niches in mining and logistics corridors.
Type:
Construction method determines heat tolerance, fuel economy trade-offs, and SASO compliance eligibility for Kingdom operators.
- Radial:Steel-belted carcass construction with perpendicular cord plies delivers superior heat dissipation on Riyadh-Jeddah arterial highways exceeding 50°C surface temperatures. Long-haul fleets under Ministry of Transport freight corridor expansions are mandating radial fitments to minimize rolling resistance and extend replacement intervals.
- Bias:Diagonal ply construction with crossed textile cords offers puncture resistance for short-haul urban delivery and secondary road conditions. Price-sensitive operators in Jeddah's light-truck segment continue specifying bias construction for low-speed, high-load municipal applications despite fuel economy penalties.
- Tubeless:Integral air-retention liner eliminates separate inner tube, reducing unsprung weight and simplifying roadside repair for passenger car and light-truck fleets.
- Tube:Separate inflatable tube within casing construction persists in heavy-duty mining equipment and select commercial vehicle retread applications.
Volume sits with Radial; growth tilts toward Tubeless as fleet telematics penetration accelerates pressure monitoring integration.
Vehicle Type:
Duty cycle intensity and operating temperature exposure create divergent margin structures across the Kingdom's commercial and consumer vehicle parc.
- Passenger Cars:Speed-rated radial tires with silica-reinforced compounds dominate Riyadh and Jeddah consumer replacement demand. E-commerce logistics density is expanding van-derived passenger-car tire specifications for last-mile delivery fleets.
- Heavy-Duty Vehicles:Multi-axle truck tires with specialized heat-resistant tread formulations command premium positioning due to shorter replacement intervals under extreme operating temperatures. Eastern Province phosphate extraction routes are accelerating demand for reinforced carcass designs.
- Light Trucks:Commercial van and pickup fitments bridge passenger-car comfort with load-bearing capacity for urban logistics operators.
- Buses:Urban transit and intercity coach tires emphasize retreadability and sidewall durability for high-cyclical loading patterns.
Passenger Cars generate the highest unit volumes; Heavy-Duty Vehicles capture the steepest margin expansion as specialized compound requirements intensify.
Distribution Channel:
Procurement scale and technical service requirements are restructuring channel economics as fleet operators abandon transactional relationships.
- Service Centers:Integrated mounting, balancing, and alignment capabilities with trained technicians for run-flat and low-profile fitments. Cold-chain transporters serving the Riyadh-Dammam corridor are consolidating annual volume agreements with national service center networks.
- Wholesalers:Bulk procurement intermediaries supplying independent garages and secondary city dealers face margin compression from SASO batch-tracking documentation requirements.
- Retail Stores:Consumer-facing outlets with immediate fitment capacity concentrate in Riyadh and Jeddah purchasing power clusters.
- Online:Direct-to-consumer platforms with warehouse fulfillment are gaining traction among price-comparison shoppers for standardized passenger-car specifications.
Service Centers consolidate fleet procurement; Online channels are climbing fastest among younger vehicle owners in metropolitan provinces.
Application:
Surface conditions and equipment mobility requirements determine tread pattern geometry, compound hardness, and casing reinforcement specifications.
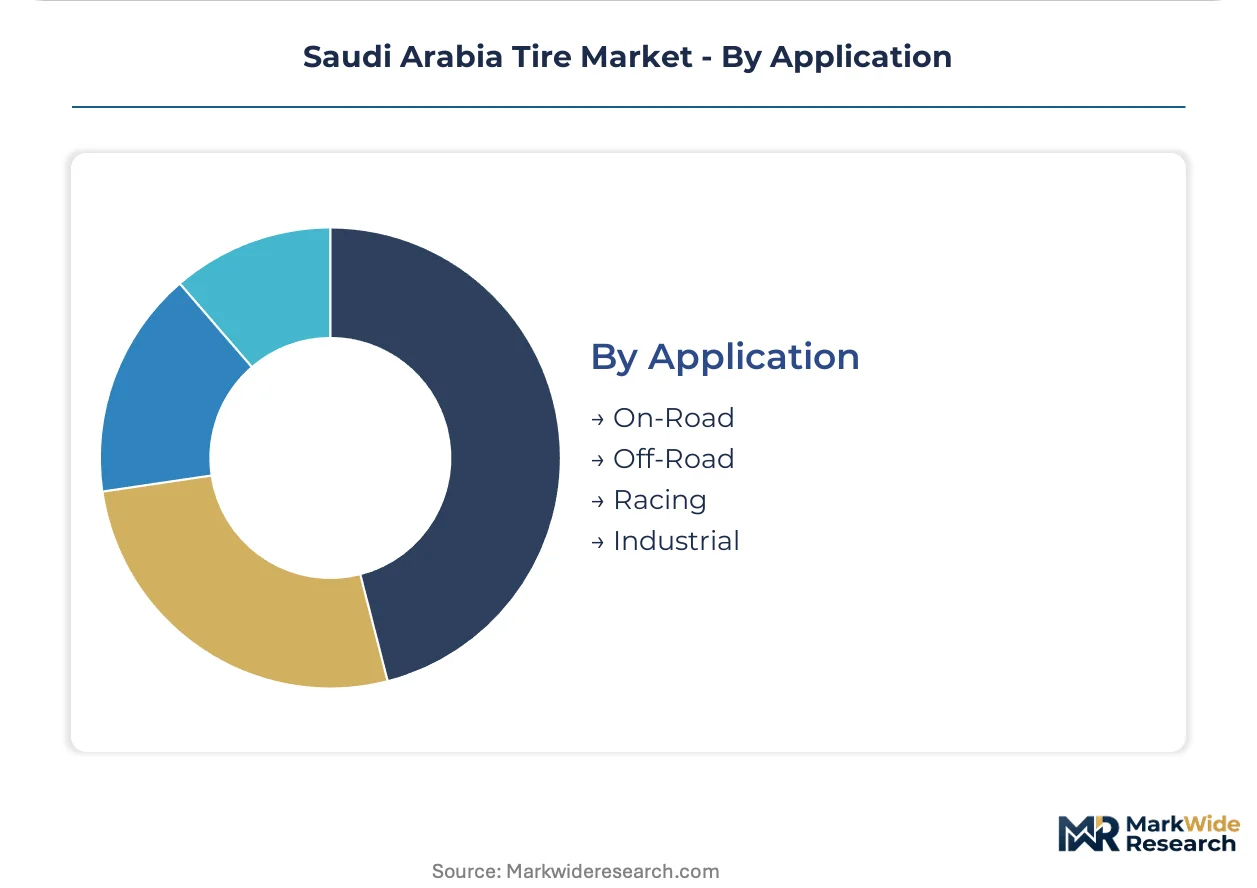
- On-Road:Highway-optimized tread designs with continuous center ribs and siping for wet-grip performance on Saudi Arabia's expanding asphalt network. SASO rolling-resistance labeling is filtering non-compliant imports from this category.
- Off-Road:Deep-lug tread patterns with cut-resistant compounds for phosphate and bauxite extraction sites near Jubail Industrial City. Specialized earthmover tires for NEOM construction logistics are creating temporary demand spikes.
- Industrial:Forklift and material-handling equipment tires with non-marking compounds for warehouse and port operations.
- Racing:Ultra-high-performance track and desert rally specifications with minimal tread depth and maximum dry-grip formulations.
On-Road commands installed base; Off-Road is expanding most quickly as Eastern Province mining capacity scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand in the Saudi Arabia tire market concentrates in Riyadh and Jeddah, where commercial vehicle density and consumer purchasing power outpace other provinces. Eastern Province mining zones and NEOM construction corridors are reshaping regional procurement patterns.
Riyadh
Riyadh anchors the Kingdom's tire demand through dense logistics corridors and the Riyadh Metro commissioning. SASO labeling mandates filter non-compliant imports from retail channels in the capital. Fleet operators along the Riyadh-Dammam freight artery negotiate consolidated supply contracts with national distributor networks.
Eastern Province
Phosphate and bauxite extraction near Jubail Industrial City accelerates off-highway tire procurement for earthmoving equipment. The Ministry of Transport's arterial highway upgrades shorten replacement cycles for long-haul fleets serving industrial zones. Specialized compound suppliers remain underserved in this mining-heavy sub-region.
Western Region
Jeddah's consumer replacement market demands speed-rated radial tires with silica-reinforced formulations for extreme summer temperatures. The Jeddah Islamic Port concentrates import volume, creating single-point vulnerability during Red Sea transit disruptions. Premium passenger-car importers specify OEM fitments to meet SASO energy-labeling requirements.
NEOM Northwest
The giga-project's heavy-equipment mobilization generates temporary demand spikes for earthmover and articulated-dump-truck tires. Construction logistics outstrip standard inventory cycles, forcing distributors to pre-position specialized stock. Fleet telematics penetration accelerates predictive replacement scheduling among NEOM contractors.
Saudi Arabia Tire Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue fleet telematics integration and predictive service models. The vendor base stratifies across premium European brands, mid-tier Asian manufacturers, and regional distribution specialists. Three archetypes dominate: original equipment partners serving vehicle assemblers, volume-driven replacement suppliers, and fleet-contract integrators bundling tires with maintenance services. Competitive moves concentrate on long-term supply agreements with logistics operators and certification alignment with SASO's evolving standards.
Within the premium-tier vector, Continental AG and Michelin Arabia exemplify original equipment positioning through European vehicle partnerships. Bridgestone Middle East anchors the fleet-contract archetype, leveraging established dealer networks for maintenance bundling. Hankook Tire and Technology occupies the replacement-cycle value position, targeting price-sensitive light-truck operators. These three represent distinct competitive vectors rather than direct substitution rivals.
| Leading Market Players |
|---|
| Continental AG |
| Yokohama Rubber Company |
| Bridgestone Middle East |
| Kumho Tire |
| Hankook Tire and Technology |
| Michelin Arabia |
| Pirelli & C. S.p.A |
| Toyo Tire Corporation |
| Goodyear Tire and Rubber Company |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap distributors dominate Saudi Arabia's tire wholesale tier, concentrating procurement leverage in Jeddah-based trading houses that negotiate annual volume commitments with Thai and Indonesian manufacturers. This ownership pattern compresses margin structures for smaller dealers lacking the working capital to absorb natural rubber price volatility or pre-position SASO-certified inventory ahead of labeling mandate deadlines.
Pricing Analysis
Volume sits with standard-grade radial tires for light-truck fleets, while premium passenger-car fitments with silica-reinforced compounds capture the widest margins. Price differentiation hinges on SASO certification tier and after-sales service bundling, with compliant products commanding positioning premiums over gray-market imports. Pricing pressure stems from Thai latex supply disruptions transmitting directly into distributor landed costs. Cold-chain logistics operators show the least price sensitivity, absorbing premium tire costs to minimize downtime exposure.
Supply Chain Analysis
Natural rubber supply rests on Thai and Indonesian latex plantations, with synthetic rubber feedstocks anchored in South Korean and Japanese petrochemical complexes. Steel cord and textile ply inputs draw from Chinese and Indian metallurgical processors. Supply chain risk concentrates in single-point vulnerability at Jeddah Islamic Port, where Red Sea transit disruptions or customs clearance bottlenecks strand containerized shipments. Distribution runs through consolidated national service center networks for fleet procurement, while independent garages and secondary city dealers rely on wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO's rolling-resistance and wet-grip labeling mandates erect a compliance moat that favors established distributors with batch-tracking documentation systems and warehouse management infrastructure. This regulatory barrier filters out uncertified imports and consolidates procurement share among certified radial suppliers.
For Market Incumbents: Deepen backward integration into retreading capabilities to capture heavy-duty vehicle replacement demand currently forced toward premium new-tire imports. Secure long-term supply agreements with Eastern Province mining operators before specialized earthmover tire demand spikes at NEOM construction corridors. Vertical control over vulcanization capacity defends margin position against natural rubber price volatility.
For New Entrants and Emerging Players: Independent cold-chain transporters in secondary cities represent the most penetrable buyer archetype, lacking integrated service relationships with national distributor networks. Target predictive tire telemetry bundling for logistics operators along the Riyadh-Dammam freight artery. A fleet-telematics-first go-to-market angle bypasses entrenched dealer relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier distributors with SASO certification infrastructure in the Western Region, where Jeddah's consumer replacement market demands speed-rated formulations. Long-term viability hinges on alignment with Ministry of Transport freight corridor expansions and domestic retreading facility investments. Watch SASO's planned United Nations Economic Commission for Europe regulatory alignment as the inflection trigger for portfolio revalidation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Investment | Batch-tracking documentation systems filter gray-market competitors from retail channels. |
| Retreading Capacity Buildout | Domestic vulcanization facilities reduce heavy-duty operator dependence on imported casings. |
| Fleet Telematics Integration | Pressure-monitoring sensors enable predictive replacement scheduling for logistics operators. |
| Eastern Province Mining Focus | Specialized compound supply for phosphate extraction near Jubail Industrial City remains underserved. |
| NEOM Pre-Positioning | Earthmover tire inventory buffers construction logistics demand spikes in Northwest Saudi Arabia. |
Research Approach
Independent corroboration across fleet procurement directors, national distributor network managers, and SASO compliance officers underwrites the qualitative findings in this study. Primary interviews with logistics operators, tire service center technicians, and wholesale trading house executives combined with secondary validation from customs/trade data, Ministry of Transport freight corridor disclosures, and SASO regulatory filings. Bottom-up tire shipment tracking and top-down vehicle parc analysis triangulate volume estimates.
Comparable historical replacement cycles across radial and bias construction categories anchored the forecast window to observed duty-cycle intensities. The analytical framework models construction technology, vehicle type, distribution channel, and application segments throughout the forecast period. CAGRs derive from vehicle utilization rate projections under Vision 2030 infrastructure investments and SASO regulatory adoption curves.
Revisions become necessary when Red Sea transit disruptions extend container dwell times, natural rubber price volatility exceeds historical bands, or SASO accelerates United Nations Economic Commission for Europe alignment timelines. A small set of triggers—freight corridor completion rates, domestic retreading facility commissioning, and fleet telematics penetration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
High Performance Wheels Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Airless Tires Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Bicycle Rim Market
Tires and Wheels
North America OTR Tire Market