
 Singapore Last Mile Delivery Market | 2026-2036
Singapore Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Last Mile Delivery Market Insights
Asset-light leasing and pay-per-use vehicle financing is tilting competitive dynamics toward operators with flexible fleet economics. Ninja Van leverages its proprietary routing engine to sustain density in residential zones. GrabExpress anchors its position through integration with the super-app's ride-hail driver pool. Lalamove competes on SME-focused same-day capacity with modular van subscriptions.
Last mile delivery denotes the final leg of logistics where parcels move from distribution hubs to end recipients, typically spanning under 50 kilometers with time windows compressed to same-day or next-day service. The segment encompasses route-optimized dispatch, real-time tracking infrastructure, and multi-drop sequencing algorithms engineered for urban density. Express delivery leads service type revenue pools due to premium pricing on speed-guaranteed slots, while drone delivery represents the fastest-growing delivery model as regulatory sandbox approvals expand beyond one-north and Punggol test zones. On-demand delivery occupies the highest margin tier by monetizing impulse purchase velocity from quick-commerce platforms.
Singapore's Land Transport Authority vehicle quota system and the National Environment Agency's commercial vehicle emission schemes jointly constrain diesel fleet expansion while accelerating electric van adoption timelines. The Personal Data Protection Commission governs delivery recipient data handling, adding compliance architecture costs to tracking system deployments. Stakeholders must weigh battery-electric total cost of ownership against charging infrastructure gaps in industrial estates before committing to fleet transformation timelines.
Market Dynamics
The Land Transport Authority's vehicle quota system is compressing diesel fleet renewal timelines while accelerating electric van deployment across commercial logistics networks. Fleet operators now face binding constraints on vehicle expansion permits that reshape capacity planning economics.
Growth Catalysts
- E-commerce parcel density:Quick-commerce platforms generate sustained volume growth in residential zones, creating route economies that justify dedicated fleet investments.
- NEA commercial vehicle emission schemes:Carbon-based surcharges on diesel vans tilt total cost of ownership toward battery-electric alternatives, accelerating fleet turnover decisions.
- Tuas mega-port integration:Consolidated container handling at the western logistics corridor shortens drayage distances to last-mile distribution hubs.
Market Restraints
- Certificate of Entitlement scarcity:The LTA's quarterly auction system caps commercial vehicle growth, forcing operators to prioritize asset utilization over fleet expansion.
- Charging infrastructure gaps:Industrial estates in Jurong and Pioneer lack high-capacity DC charging for heavy electric vans, constraining operational range.
- Labor cost compression:Driver wages face upward pressure from ride-hail platform competition, squeezing per-delivery margins without pricing power.
Strategic Opportunities
- Drone delivery sandbox expansion:Beyond Punggol and one-north test zones, Civil Aviation Authority of Singapore approvals could unlock aerial last-mile for medical and high-value parcels.
- Carbon credit monetization:Fleet electrification generates tradeable emissions reductions under Singapore's carbon pricing framework.
- Micro-fulfillment node placement:Vacant retail space in HDB heartlands offers low-cost inventory positioning for sub-two-hour delivery promises.
Industry Challenges
- Route optimization talent scarcity:Data science capabilities for dynamic dispatch algorithms remain concentrated among a handful of technology-forward operators.
- PDPC compliance architecture:Recipient data handling requirements add fixed costs to tracking system deployments that smaller fleet operators struggle to absorb.
- Intermodal handoff friction:Container-to-van transfers at port terminals create dwell time variability that compresses delivery window reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Last Mile Delivery Market |
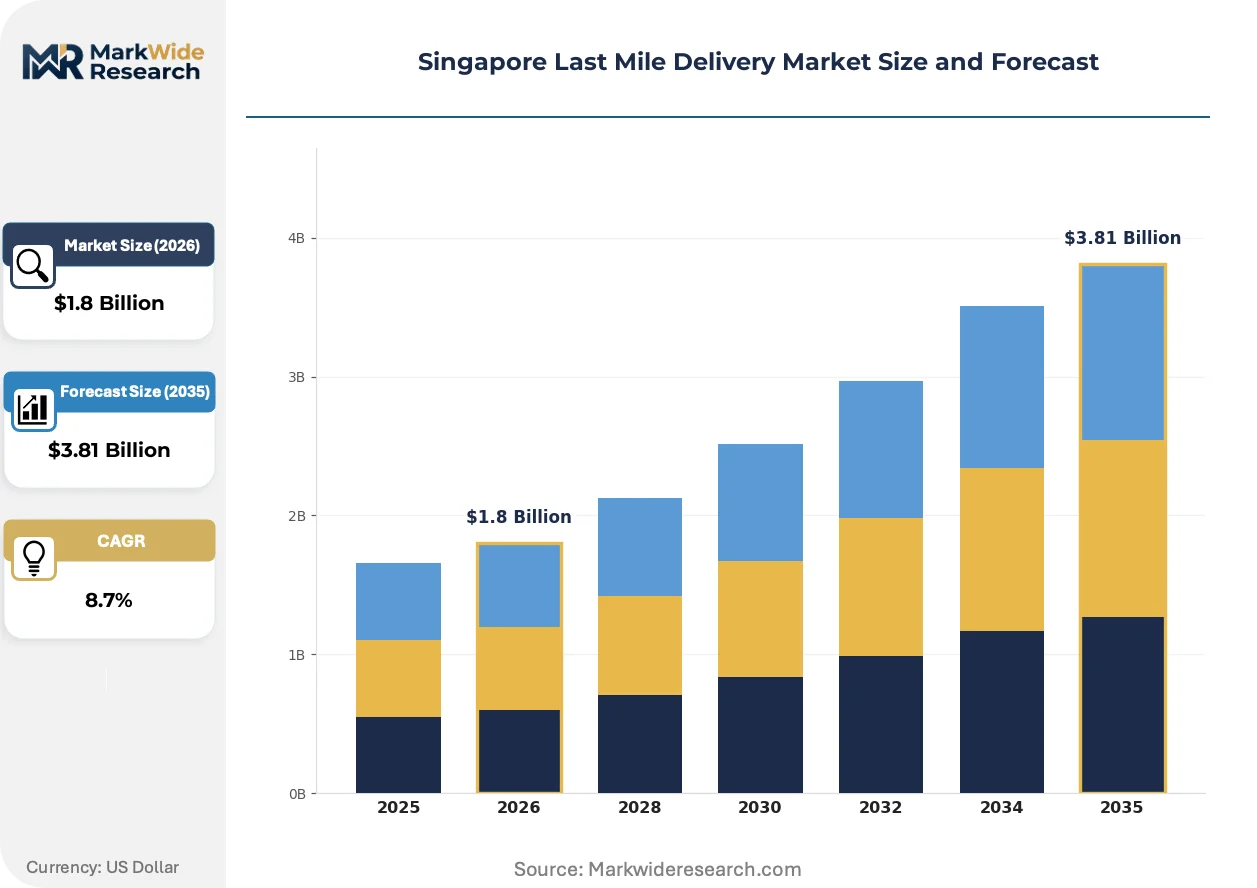
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Express Delivery, On-Demand Delivery, Scheduled Delivery Delivery Model: Bicycle Courier, Motorcycle Courier, Van Delivery, Drone Delivery Customer Type: Retailers, E-Commerce Companies, Third-Party Logistics, SMEs Technology: Route Optimization, Tracking Systems, Automated Dispatch, Mobile Apps |
| Companies Covered | Ninja Van, Singapore Post, J&T Express, GrabExpress, DHL Express, Lalamove, SPX Express, Pickupp, EVFY, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Last Mile Delivery Market Trends and Innovations
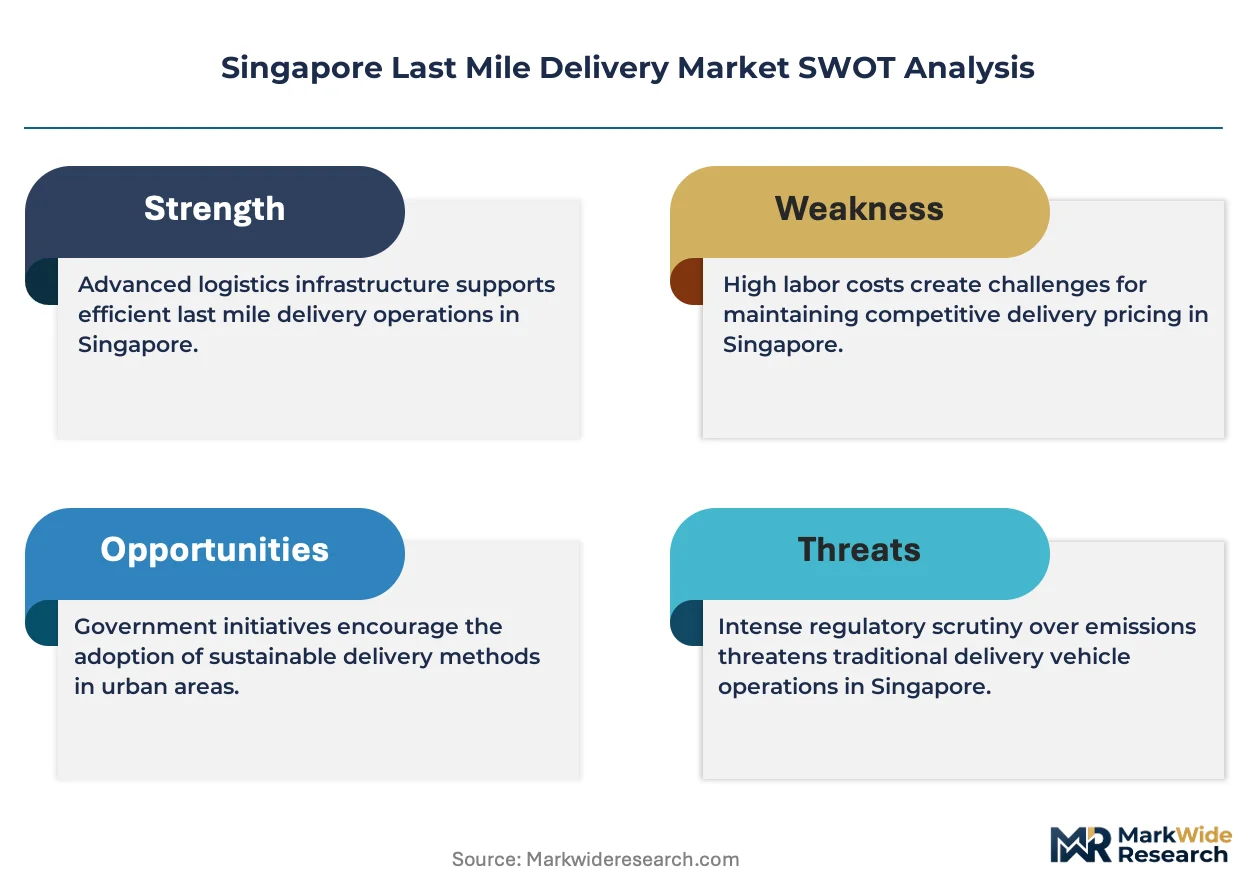
Operational technology is collapsing traditional distance-cost relationships while regulatory pressure rewrites fleet composition rules. These shifts are compressing competitive differentiation into algorithmic execution and asset flexibility.
Dynamic routing engines leveraging real-time traffic ingestion and machine learning are collapsing the cost gap between scheduled and on-demand delivery economics. Third-party logistics providers deploy these systems to match GrabExpress's driver-pool density without captive labor. The structural consequence is collapsing premium pricing power for express slots as algorithmic efficiency democratizes speed guarantees.
Singapore's Land Transport Authority has tightened commercial vehicle quota allocations while the National Environment Agency phased in stricter particulate emission standards for diesel vans. These overlapping constraints force fleet operators to accelerate electric transition timelines or pay escalating carbon surcharges. Heavy van segments face the steepest compliance cost escalation, driving consolidation toward operators with capital reserves for battery-electric procurement.
Quick-commerce platforms now demand sub-30-minute delivery windows that traditional hub-and-spoke distribution cannot fulfill. Dark store networks and micro-fulfillment nodes in residential zones are displacing centralized warehouse models for impulse-driven categories. This pattern concentrates in the Central Region corridor where population density supports inventory placement within two kilometers of recipient clusters.
Singapore Last Mile Delivery Market Segmentation
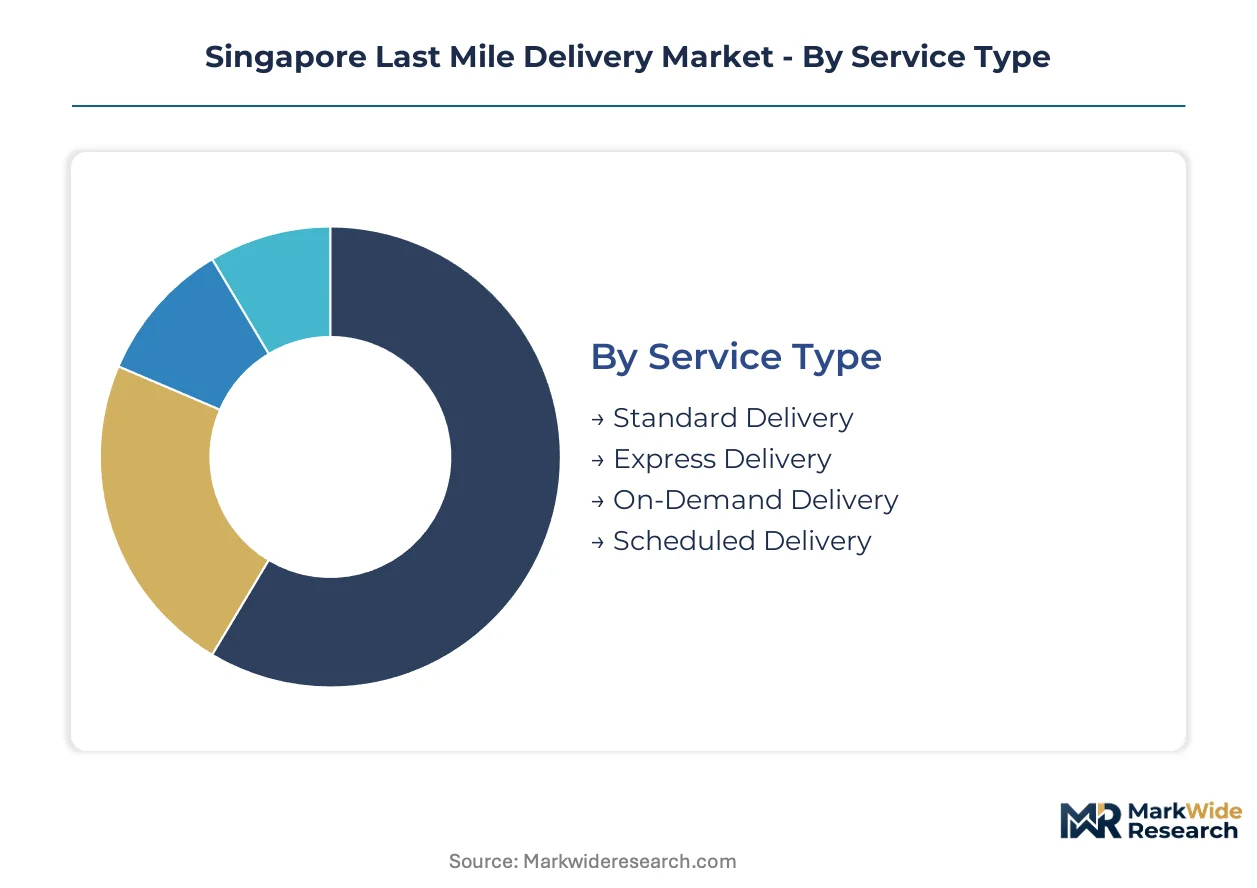
Segmentation in Singapore's last mile delivery market reveals how service velocity, vehicle constraints, and data infrastructure determine operator economics. Each dimension exposes different pressure points from the Land Transport Authority's vehicle quota system and the Personal Data Protection Commission's compliance requirements.
Service Type:
Cost tier differentiation separates commodity logistics from premium velocity guarantees, with pricing power concentrated at the speed-determined extremes.
- Standard Delivery:Next-day or two-day fulfillment windows dominate B2B replenishment and non-urgent e-commerce. Parcel density in Jurong and Tuas industrial zones sustains route economics for consolidated drop sequences.
- Express Delivery:Same-day guaranteed slots command premium pricing through time-definite handoff commitments. Central Region corridor demand from financial services and medical suppliers anchors revenue concentration here.
- On-Demand Delivery:Sub-60-minute windows monetize impulse velocity from quick-commerce platforms.
- Scheduled Delivery:Pre-booked slots optimize asset utilization during off-peak hours.
Express Delivery commands the established base. The steepest expansion runs through On-Demand Delivery.
Delivery Model:
Vehicle selection reflects payload requirements against Certificate of Entitlement scarcity and National Environment Agency emission surcharge exposure.
- Bicycle Courier:Human-powered final-leg coverage suits dense HDB estates and CBD document exchanges. Limited to parcels under 10 kilograms, this model evades vehicle quota constraints entirely while facing labor competition from ride-hail platforms.
- Van Delivery:Heavy electric vans handle bulk furniture and appliance segments where payload exceeds 100 kilograms. Charging infrastructure gaps in Pioneer and Penjuru industrial zones constrain operational range for this segment.
- Motorcycle Courier:Two-wheelers navigate congestion for mid-weight parcels in the 10-30 kilogram band.
- Drone Delivery:Aerial platforms bypass ground congestion for medical and high-value parcels under 5 kilograms.
Van Delivery commands the established base. The steepest expansion runs through Drone Delivery.
Customer Type:
Account scale determines contract structure, with enterprise volumes enabling dedicated fleet allocation against spot-market SME flexibility.
- E-Commerce Companies:Platform-integrated logistics demand API-connected dispatch systems handling thousands of daily parcels. Central Region warehousing proximity to recipient clusters in Tampines and Woodlands shapes hub placement decisions.
- SMEs:Fragmented merchant bases rely on third-party capacity with no minimum volume commitments. Modular subscription pricing from logistics aggregators addresses cash-flow constraints here.
- Retailers:Brick-and-click operations require omnichannel fulfillment integrating store inventory with home delivery.
- Third-Party Logistics:Asset-light operators broker capacity across multiple fleet networks.
E-Commerce Companies command the established base. The steepest expansion runs through SMEs.
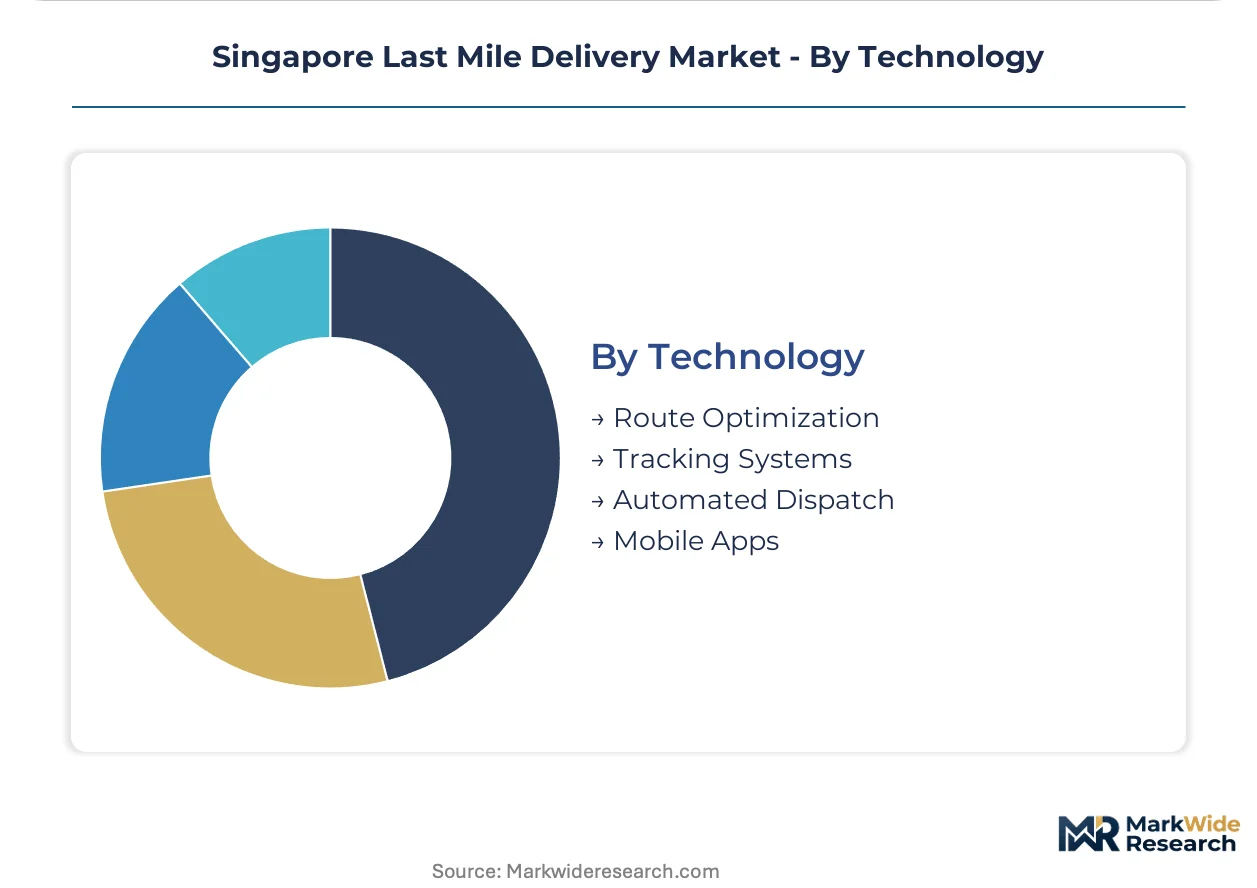
Technology:
Software layer investments separate algorithmic execution leaders from dispatch-dependent followers, with compliance architecture adding fixed cost burdens.
- Route Optimization:Machine learning dispatch engines ingest real-time traffic and weather to compress delivery windows. Dynamic rerouting capability distinguishes technology-forward operators from static route planners.
- Tracking Systems:GPS and RFID infrastructure enables recipient visibility and proof-of-delivery capture. Personal Data Protection Commission consent management requirements add deployment complexity here.
- Automated Dispatch:Rules-based order-to-vehicle matching reduces human dispatcher headcount.
- Mobile Apps:Driver-facing interfaces handle navigation, customer communication, and payment capture.
Route Optimization commands the established base. Tracking Systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central Region logistics corridors command premium pricing power against Jurong industrial zones where bulk consolidation compresses per-parcel margins. This geographic asymmetry shapes fleet deployment economics across Singapore's constrained landmass.
Central Region
Financial services and medical suppliers generate express delivery demand from Raffles Place and Tanjong Pagar clusters. The Land Transport Authority's vehicle quota system limits fleet expansion permits for operators serving this corridor. Marina Bay and Orchard Road concentration supports sub-60-minute on-demand delivery promises through micro-fulfillment node placement.
Tuas Logistics Corridor
Mega-port container volumes create drayage-to-last-mile handoff demand for bulk furniture and appliance segments. National Environment Agency commercial vehicle emission schemes accelerate electric van adoption timelines for heavy payload operators. Tuas West industrial estates see fleet operators consolidating distribution hubs to minimize distance to recipient clusters.
Jurong Industrial Zone
B2B replenishment cycles sustain standard delivery route economics for consolidated drop sequences. Certificate of Entitlement scarcity forces operators to prioritize asset utilization over fleet expansion in this zone. Jurong East and Penjuru industrial estates face charging infrastructure gaps that constrain heavy electric van operational range.
Tampines-Woodlands Axis
HDB heartland population density supports quick-commerce platform volume growth for impulse-driven categories. Personal Data Protection Commission compliance requirements add fixed costs to tracking system deployments serving residential zones. Tampines regional centre and Woodlands industrial parks anchor inventory positioning for sub-two-hour delivery promises.
Punggol-Sengkang Corridor
Drone delivery sandbox approvals from the Civil Aviation Authority of Singapore unlock aerial last-mile testing for medical and high-value parcels. One-north adjacent zones extend regulatory experimentation beyond initial test boundaries. Punggol digital district concentration enables real-time traffic ingestion for dynamic routing engine calibration.
Singapore Last Mile Delivery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in routing engine and tracking infrastructure layers. The Singapore market structures around three strategic archetypes: super-app logistics divisions leveraging ride-hail driver pools, pure-play last-mile specialists with proprietary dispatch algorithms, and traditional postal operators modernizing legacy networks. Competitive moves concentrate on fleet electrification partnerships and micro-fulfillment node real estate acquisition.
Among Singapore-based operators, Ninja Van and Singapore Post exemplify contrasting archetype positioning. Ninja Van occupies the technology-forward specialist tier with density-focused residential zone routing. Singapore Post anchors the incumbent modernization vector, bridging postal infrastructure with express delivery velocity. GrabExpress represents the super-app integration model, monetizing driver-pool fungibility across mobility and logistics demand peaks.
| Leading Market Players |
|---|
| Ninja Van |
| Singapore Post |
| J&T Express |
| GrabExpress |
| DHL Express |
| Lalamove |
| SPX Express |
| Pickupp |
| EVFY |
| Others |
Pricing and Supply Chain Analysis
The Tuas-Jurong logistics corridor anchors Singapore's last mile delivery cost structure, concentrating fleet procurement and charging infrastructure investments in ways that stratify pricing power across express, standard, and on-demand service tiers.
Pricing Analysis
E-commerce platform buyers anchor Singapore's pricing structure around volume-scaled contract tiers, with express delivery premiums widening against standard service as Certificate of Entitlement scarcity constrains fleet expansion. Price differentiation hinges on delivery velocity guarantees and recipient data handling compliance tiers under PDPC requirements. Pricing pressure stems from ride-hail platform competition for driver labor, compressing per-delivery margins without corresponding rate increases. SME merchants exhibit highest price sensitivity due to cash-flow constraints, while enterprise e-commerce platforms absorb premium rates for API-integrated dispatch reliability.
Supply Chain Analysis
Tariff exposure between China and Singapore dominates electric van procurement risk as fleet operators accelerate battery-electric transitions under NEA emission surcharge pressure. Supply concentration centers on Chinese battery manufacturers, South Korean electric drivetrain suppliers, and Japanese charging component specialists. Raw material dependencies span lithium carbonate, rare earth magnets, and high-grade aluminum for lightweight van bodies. Single-source vulnerability persists in proprietary routing engine software licensing. Distribution runs through Land Transport Authority-approved vehicle dealers and third-party logistics aggregators brokering spot capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's last mile delivery market fragments across service velocity tiers, with quick-commerce platform demand creating specialist niches in sub-30-minute fulfillment that reward algorithmic execution over asset-heavy fleet ownership.
For Market Incumbents: Insulate core route density in Central Region corridors through exclusive micro-fulfillment node real estate leases, while accelerating electric van deployment ahead of NEA emission surcharge escalations. Counter GrabExpress's driver-pool fungibility by embedding proprietary routing engines deeper into e-commerce platform API integrations. For New Entrants and Emerging Players: Jurong industrial zone underpenetration in B2B scheduled delivery offers white-space entry with lower Certificate of Entitlement competition than consumer corridors. Target SME merchant aggregators with modular van subscription pricing that converts fixed fleet costs to variable delivery economics. Pursue Civil Aviation Authority of Singapore drone delivery sandbox approvals for medical parcel specialization as regulatory moat. For Investors and Strategic Acquirers: Asset-light logistics aggregators with algorithmic dispatch capabilities represent the priority acquisition archetype for exposure to Singapore's electrification transition without fleet ownership risk. Long-term viability rests on carbon credit monetization infrastructure and PDPC-compliant data architecture. Watch for Civil Aviation Authority of Singapore drone delivery zone expansions beyond Punggol as inflection signal for aerial last-mile platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | NEA emission surcharge exposure accelerates battery-electric procurement timelines for heavy van segments. |
| Micro-Fulfillment Node Acquisition | HDB heartland retail vacancy enables sub-two-hour delivery promises without centralized warehouse dependency. |
| Drone Delivery Sandbox Expansion | Civil Aviation Authority of Singapore approvals beyond one-north unlock aerial medical parcel premiums. |
| Routing Engine Licensing Agreement | Algorithmic dispatch capability separates technology-forward operators from static route planners. |
| Carbon Credit Monetization Program | Singapore carbon pricing framework generates tradeable emissions reductions from fleet electrification. |
Research Methodology
The analysis maps express delivery, on-demand fulfillment, drone delivery, and scheduled B2B service tiers, each validated through fleet operations directors, e-commerce logistics procurement managers, last mile technology vendors, and Land Transport Authority policy specialists. Primary interview insights triangulate against Land Transport Authority vehicle registration databases, National Environment Agency emission scheme filings, Civil Aviation Authority of Singapore regulatory notices, and e-commerce platform logistics partnership disclosures. Bottom-up parcel volume modeling and top-down market sizing converge across service type, delivery model, customer segment, and technology layer dimensions.
Forecast assumptions hold Land Transport Authority vehicle quota allocations and NEA emission surcharge trajectories within announced policy parameters across the analysis window. Segmentation modeling incorporates service velocity tiers, vehicle payload classes, customer account scales, and routing technology sophistication levels. CAGR derivation rests on parcel volume elasticity to e-commerce platform GMV growth, electric van total cost of ownership crossover timelines, and quick-commerce platform geographic expansion patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by super-app logistics divisions or drone delivery specialists would shift outcomes beyond modeled ranges. Continuous validation against Land Transport Authority permit auction results and NEA compliance cost reporting is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
LAMEA Last Mile Delivery Market
Logistics and Shipping
ASEAN Chemical Logistics Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
North America Same Day Delivery Market
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
Digital Freight Matching Market