
 Trailer Wheel Market | 2026-2036
Trailer Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Trailer Wheel Market Analytics
Modular wheel-and-tire bundling is consolidating buyer choice across the trailer wheel supply chain. Accuride Corporation leverages its forged aluminum capacity to serve high-load fleet contracts. Maxion Wheels sustains foundry scale across multiple rim diameters for utility and cargo trailer OEMs. Dexstar Wheel specializes in steel wheel variants for price-sensitive agricultural and construction trailer segments.
A trailer wheel is a load-bearing rim assembly, typically constructed from stamped steel, cast aluminum, or forged alloy, designed to mount tires on towed vehicles ranging from utility trailers to heavy livestock haulers. The component must withstand dynamic radial and cornering loads while maintaining dimensional tolerance for hub-centric mounting and brake drum clearance. Steel wheels retain volume leadership in utility and cargo trailer applications due to cost efficiency and impact resistance, while aluminum wheels command margin pools in boat and horse trailer segments where corrosion resistance and reduced unsprung weight justify premium positioning. Composite wheel development occupies a niche but growing lane as manufacturers explore fiber-reinforced polymers for specialty lightweight configurations.
The EPA regulates commercial trailer emissions indirectly through heavy-duty vehicle standards that influence fleet equipment refresh cycles, while the NHTSA governs brake and wheel-end performance under Federal Motor Vehicle Safety Standards. ISO 3894 and SAE J267 provide international and North American test protocols for wheel fatigue and impact resistance that shape product certification requirements. Stakeholders must monitor evolving EPA phase-down schedules and state-level weight limit variances that determine aluminum versus steel specification splits across regional fleet procurement.
Market Dynamics
Fleet operators face mounting pressure to reduce unsprung weight as EPA emissions standards tighten for commercial towing equipment, forcing specification shifts from steel to aluminum wheel architectures across long-haul logistics networks.
Growth Catalysts
- EPA Phase-Down Schedules:The Environmental Protection Agency's progressive emissions standards for heavy-duty vehicles accelerate fleet equipment refresh cycles, driving aluminum wheel procurement to achieve weight-based compliance improvements.
- Boat Trailer Corrosion Resistance:Coastal recreational boating operators specify marine-grade aluminum wheels to combat saltwater degradation, sustaining premium replacement demand in corrosion-prone environments.
- Forged Alloy Manufacturing Scale:North American foundry capacity expansion for high-strength aluminum alloys reduces per-unit production costs, narrowing the price gap against stamped steel alternatives.
Market Restraints
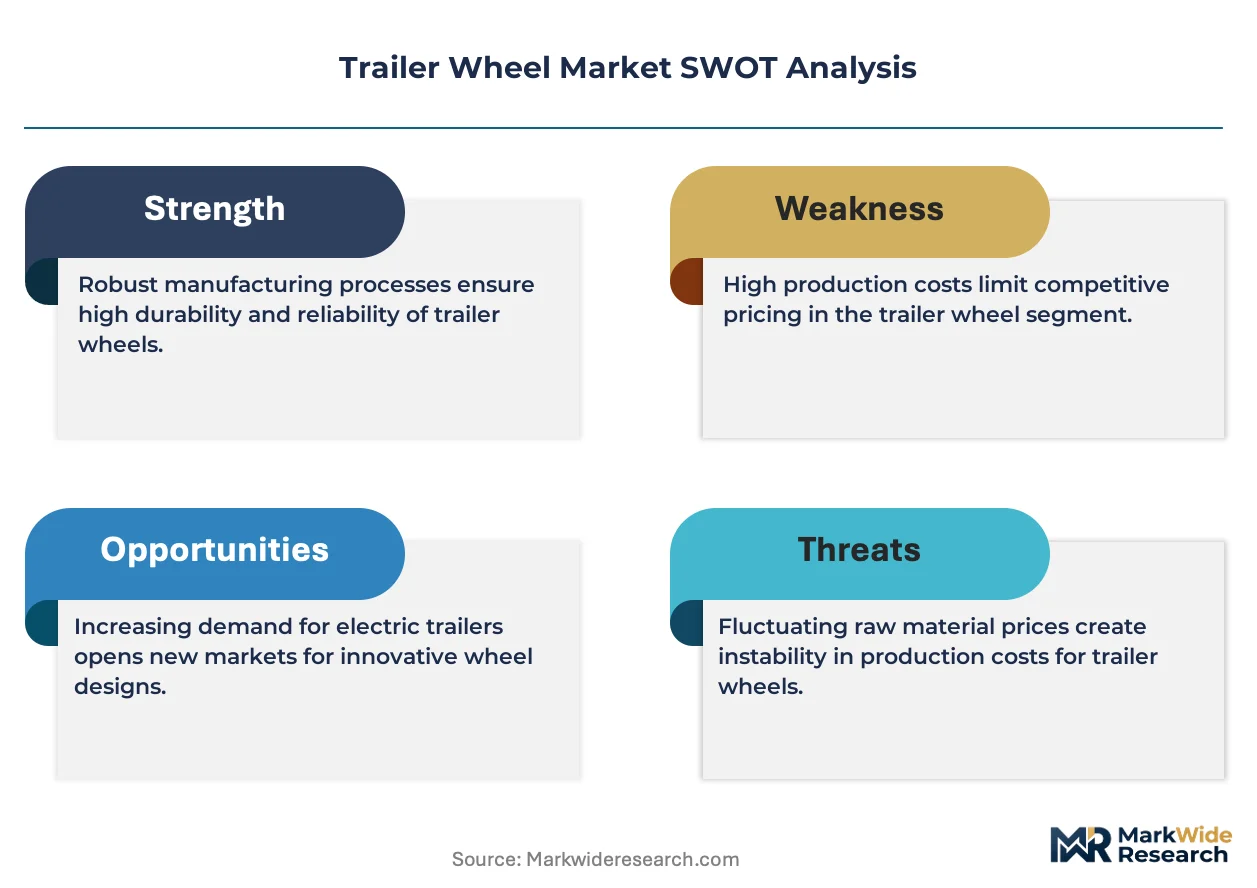
- Aluminum Price Volatility:London Metal Exchange aluminum contract fluctuations compress margin predictability for wheel manufacturers, forcing hedging costs onto smaller fabricators.
- Steel Wheel Supply Concentration:Domestic steel wheel production clusters in the industrial Midwest, creating geographic vulnerability to regional labor disruptions or energy cost spikes.
- Composite Material Technical Limitations:Fiber-reinforced polymer wheels face unresolved fatigue-testing failures under sustained radial loads, blocking adoption in livestock and heavy cargo segments.
Strategic Opportunities
- Electric Trailer Integration:Battery-electric trailer prototypes require lightweight wheel assemblies to offset powertrain mass, opening specification windows for advanced aluminum and hybrid material designs.
- State-Level Weight Limit Variances:Jurisdictions with elevated gross vehicle weight thresholds permit heavier payload configurations, incentivizing aluminum wheel investments to maximize legal cargo capacity.
- Direct Fleet Procurement Platforms:Digital sourcing channels connecting wheel manufacturers with national fleet operators bypass traditional distributor markups, capturing margin recovery in high-volume contracts.
Industry Challenges
- SAE J267 Certification Timelines:Extended validation protocols for new wheel designs delay product launches by 12-18 months, compressing competitive response windows.
- Legacy Hub-Centric Integration:Mixed fleets operating steel and aluminum wheels face maintenance complexity from incompatible mounting specifications, raising total cost of ownership calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailer Wheel Market |
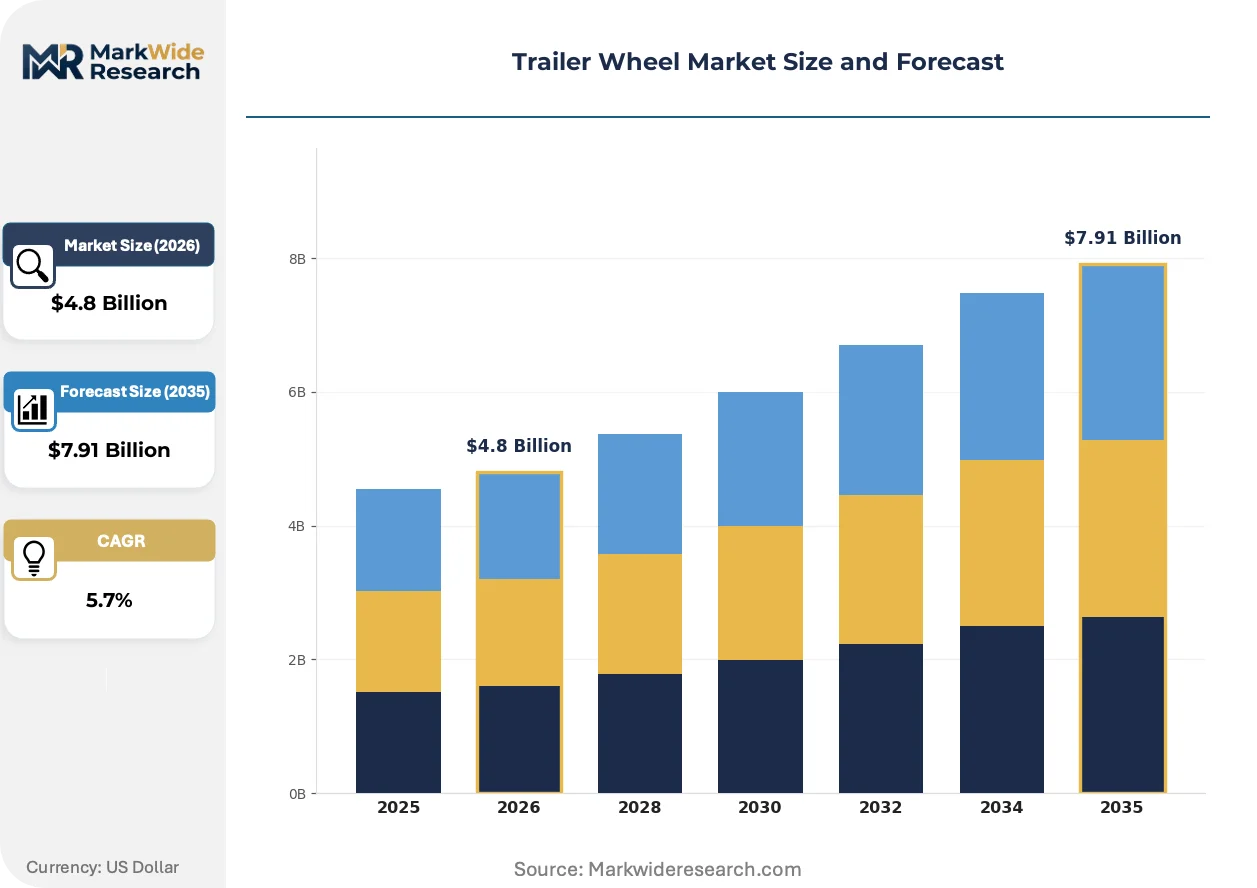
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Wheels, Aluminum Wheels, Composite Wheels, Spoked Wheels Application: Utility Trailers, Boat Trailers, Cargo Trailers, Horse Trailers End User: Commercial Users, Individual Consumers, Fleet Operators, Rental Services Size: 13 Inch, 14 Inch, 15 Inch, 16 Inch |
| Companies Covered | TSW Alloy Wheels, MHT Luxury Wheels, Maxion Wheels, Dexstar Wheel, Hitachi Metals Ltd., Accuride Corporation, Voxx Products, Global Wheel, Carlstar Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailer Wheel Market Evolving Landscape
Material science advances and regulatory compliance pressures are restructuring how trailer wheels are specified, manufactured, and procured across commercial and recreational segments.
Forged aluminum wheel technology is expanding into high-load fleet applications previously dominated by steel. The process delivers superior strength-to-weight ratios through directional grain alignment. Long-haul logistics operators now specify forged variants for 19.5-inch and 22.5-inch rim diameters. This technology is expanding into price-sensitive utility trailer segments as production scale reduces unit economics.
The EPA's indirect regulation of commercial trailer emissions through heavy-duty vehicle standards is reshaping fleet procurement calendars. Phase-down schedules force accelerated equipment replacement to maintain operational compliance. Aluminum wheel specifications concentrate in California and Northeast corridor fleets where state-level enforcement tightens fastest.
Modular wheel-and-tire bundling is altering traditional distribution economics. National fleet operators now negotiate consolidated supply agreements covering mounting, balancing, and roadside replacement services. This procurement consolidation pressures independent distributors and small regional fabricators. The shift is most visible in United States long-haul logistics where total cost of ownership calculations dominate specification decisions.
Trailer Wheel Market Segmentation
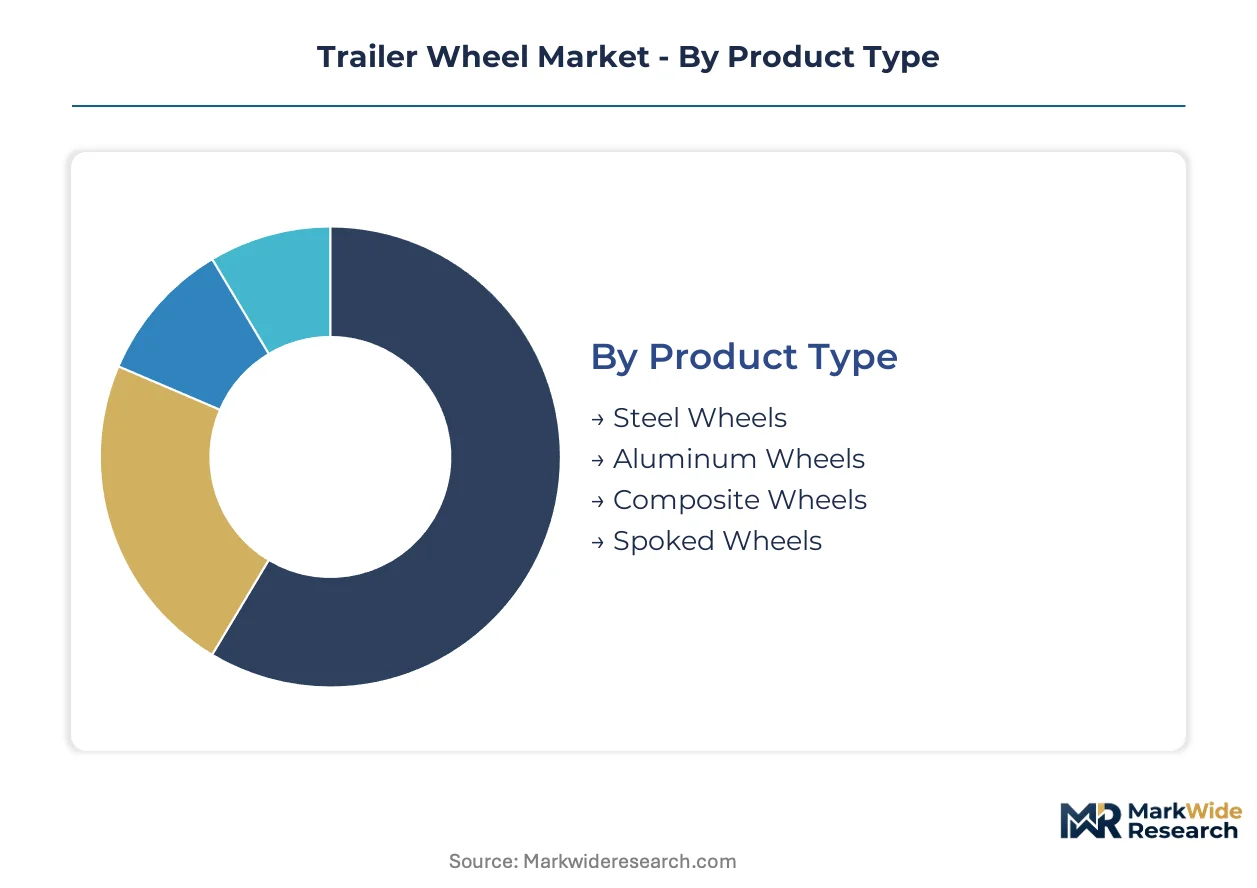
Trailer wheel procurement splits sharply across material architectures and duty cycles, with capital requirements varying dramatically between stamped steel tooling and forged aluminum foundries. Specification decisions cascade through fleet economics, corrosion exposure, and payload optimization, creating distinct margin pools that reward manufacturing scale in some segments and customization agility in others.
Product Type:
Capital intensity peaks with forged aluminum foundries requiring directional grain alignment equipment, while stamped steel operations demand lower upfront tooling investments but higher per-unit material throughput.
- Steel Wheels:Stamped carbon steel rims dominate utility and cargo trailer specifications through cost efficiency and impact resistance. Fleet procurement in the United States concentrates here for dry freight and construction equipment where unsprung weight reduction delivers minimal fuel economy returns. EPA emissions phase-down schedules are slowly eroding this dominance as operators calculate total cost of ownership across aluminum alternatives.
- Aluminum Wheels:Cast and forged aluminum variants command premium positioning in boat and horse trailer segments where saltwater corrosion resistance and reduced maintenance justify price multiples. California and Northeast corridor fleets specify these for refrigerated and specialty cargo trailers facing stringent state-level enforcement timelines.
- Composite Wheels:Fiber-reinforced polymer constructions occupy experimental niches in lightweight specialty applications, constrained by unresolved SAE J267 fatigue certification failures under sustained radial loads.
- Spoked Wheels:Traditional wire-spoke designs persist in vintage and custom trailer restoration markets, requiring manual lacing craftsmanship that resists automated manufacturing scale.
Steel wheels absorb the bulk of installed capacity; aluminum wheels are expanding most quickly as foundry scale narrows unit economics against stamped alternatives.
Application:
Duty cycle severity and environmental exposure create divergent specification requirements across trailer categories, with corrosion risk and payload sensitivity driving material selection.
- Utility Trailers:General-purpose flatbed and enclosed configurations for residential and light commercial hauling represent the highest-volume specification category. Price-sensitive procurement favors steel wheels in the Midwest and Southeast where salt exposure remains minimal and replacement cycles extend to failure rather than preventive refresh.
- Boat Trailers:Marine-grade aluminum specifications dominate coastal markets from Florida through the Gulf Coast and Pacific Northwest. Saltwater immersion and splash exposure mandate corrosion-resistant alloys, with premium forged variants gaining share in high-value yacht transport segments.
- Cargo Trailers:Dry van and refrigerated box trailers for long-haul logistics face accelerating aluminum specification shifts as fleet operators model fuel savings against acquisition premiums. Weight limit variances across state jurisdictions incentivize lightweight wheel investments to maximize legal payload.
- Horse Trailers:Livestock transport configurations prioritize ride quality and reduced unsprung mass to minimize animal stress during transit. Aluminum wheels command sustained premium positioning here, with forged variants specified for commercial breeding operations and cast alternatives serving recreational equestrian markets.
Cargo trailers generate the highest absolute unit demand; boat trailers maintain the steepest premium pricing differential across material tiers.
End User:
Procurement sophistication and total cost of ownership modeling capability separate institutional buyers from price-driven transactional purchasers.
- Commercial Users:Small business operators in construction, landscaping, and local delivery segments prioritize acquisition cost over lifecycle economics, sustaining steel wheel volume in 15-inch and 16-inch rim diameters.
- Individual Consumers:Recreational boaters and horse owners demonstrate willingness to pay corrosion resistance and aesthetic premiums, driving aluminum specification in direct-to-consumer retail channels.
- Fleet Operators:National logistics companies employ centralized procurement platforms that negotiate consolidated wheel-and-tire bundling agreements. These buyers model fuel economy, maintenance intervals, and resale value across aluminum specifications, bypassing traditional distributor markups.
- Rental Services:Equipment rental fleets prioritize damage tolerance and rapid replacement availability, favoring steel wheels for construction and utility trailer categories where customer abuse rates remain elevated.
Fleet operators command the most favorable pricing terms; individual consumers pay the highest per-unit premiums for specialty finishes and marine-grade alloys.
Size:
Rim diameter selection correlates directly with gross vehicle weight rating and tire load range requirements, with manufacturing tooling dedicated to high-volume diameter clusters.
- 13 Inch:Compact utility and personal watercraft trailers specify this diameter for light-duty applications where tire availability and replacement cost dominate procurement decisions.
- 14 Inch:Mid-size utility and small cargo trailers represent a transitional specification tier with mixed steel and aluminum penetration depending on regional price sensitivity.
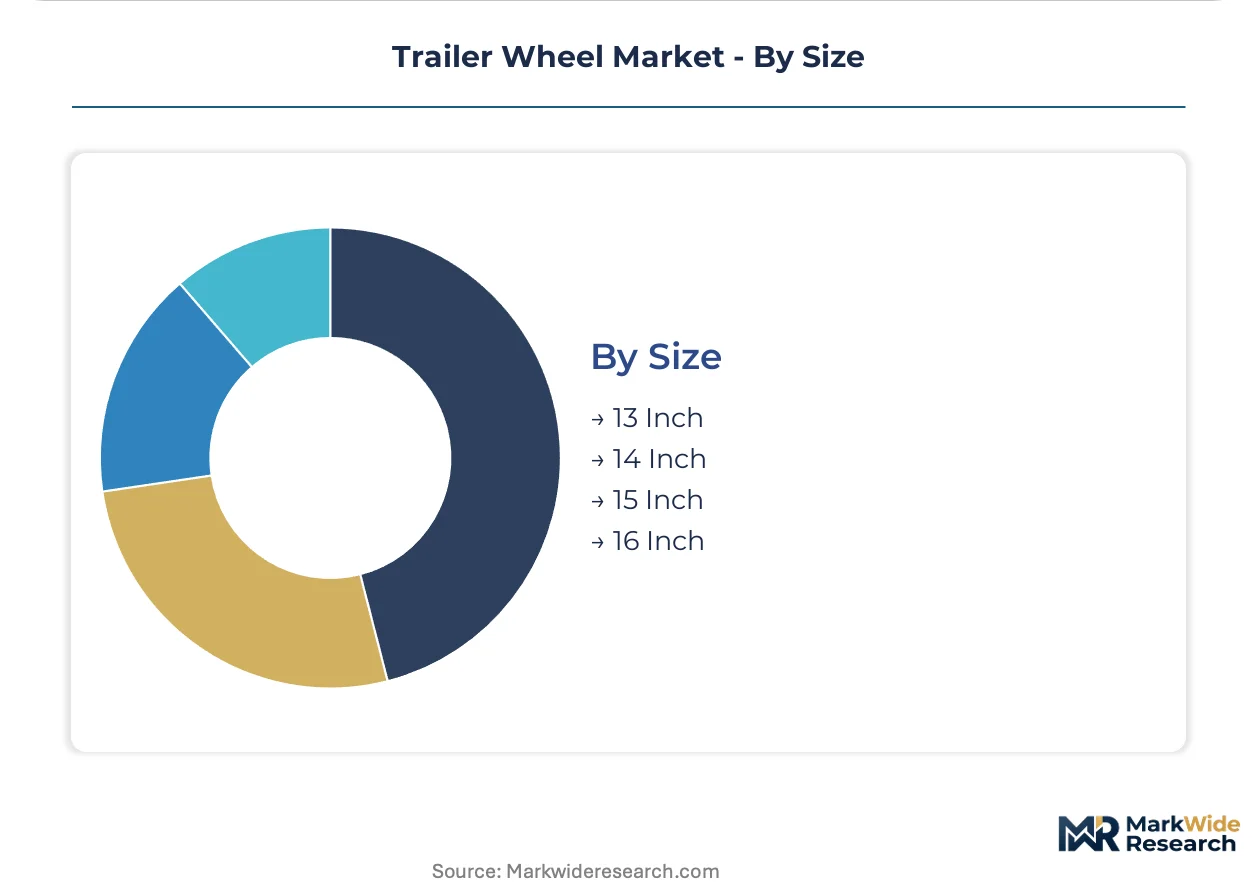
- 15 Inch:The highest-volume diameter category serves broad utility, boat, and light cargo segments with extensive tire manufacturer support and distributor inventory concentration.
- 16 Inch:Heavy-duty utility, livestock, and commercial cargo applications specify this diameter for elevated load range tires, with aluminum forged variants gaining specification in premium fleet contracts.
15-inch rims anchor production volume; 16-inch specifications are climbing fastest as fleet operators upgrade axle ratings for payload optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trailer wheel production clusters in North American foundries and steel stamping centers, while consumption concentrates in logistics corridors and coastal recreational markets. The United States dominates absolute demand through long-haul fleet procurement and boat trailer replacement cycles. Mexico and Canada supply integrated manufacturing capacity serving cross-border OEM contracts.
United States
Long-haul logistics operators in California and the Northeast corridor drive aluminum wheel specification shifts under EPA heavy-duty vehicle standards. The NHTSA enforces brake and wheel-end performance under Federal Motor Vehicle Safety Standards. Manufacturing concentrates in the industrial Midwest, with Ohio and Michigan foundries serving national fleet procurement platforms.
Canada
Recreational boating operators along the Pacific and Atlantic coasts sustain marine-grade aluminum demand for saltwater-exposed trailer configurations. Transport Canada aligns commercial vehicle regulations with US NHTSA standards to facilitate cross-border fleet interoperability. Ontario-based fabricators supply steel wheel variants for construction and agricultural trailer segments serving Prairie Provinces resource extraction.
Mexico
Maquiladora operations in Nuevo León and the Bajío Region produce stamped steel wheels for US utility trailer OEMs leveraging nearshoring cost structures. The country's automotive manufacturing regulator enforces alignment with US EPA emissions frameworks for integrated North American production. Querétaro industrial parks host aluminum foundry investments serving cross-border electric trailer prototype programs.
Germany
Precision forging specialists in Baden-Württemberg supply high-load aluminum wheel architectures for European livestock and cargo trailer manufacturers. The KBA enforces brake system and wheel-end compliance under EU Whole Vehicle Type Approval frameworks. Stuttgart-area engineering clusters drive fatigue-testing protocol development that shapes SAE J267 and ISO 3894 certification benchmarks.
China
Domestic trailer production in Shandong and Jiangsu provinces consumes stamped steel wheels for construction and agricultural equipment serving Belt and Road infrastructure projects. The MIIT governs commercial vehicle component standards through GB certification protocols. Yangtze River Delta foundries export cast aluminum variants to Southeast Asian boat trailer assemblers.
Trailer Wheel Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material tiers and rim diameter configurations. Market structure tilts toward consolidated scale in aluminum forging and fragmented competition in stamped steel variants. Three archetypes dominate: integrated foundry-to-finish aluminum producers, regional steel stamping specialists, and diversified automotive component suppliers leveraging shared manufacturing platforms. Competitive moves concentrate on foundry capacity expansion for forged alloy production and backward integration into aluminum billet supply.
Within the integrated aluminum tier, Accuride Corporation and Maxion Wheels exemplify scale-driven foundry operations serving high-load fleet contracts. Dexstar Wheel occupies a position among steel-focused fabricators supplying price-sensitive utility and agricultural segments. These three anchors illustrate the material-based stratification that defines procurement decisions across commercial and recreational trailer end uses.
| Leading Market Players |
|---|
| TSW Alloy Wheels |
| MHT Luxury Wheels |
| Maxion Wheels |
| Dexstar Wheel |
| Hitachi Metals Ltd. |
| Accuride Corporation |
| Voxx Products |
| Global Wheel |
| Carlstar Group |
| Others |
Value Network & Pricing Analysis
Forged aluminum foundry specialists concentrated in Ohio and Michigan command wage premiums that widen pricing spreads between premium forged and standard cast aluminum tiers, compressing margin recovery for stamped steel fabricators in cost-sensitive utility segments.
Pricing Analysis
Margin tightening in steel wheel tiers reflects London Metal Exchange aluminum contract volatility forcing hedging costs onto smaller fabricators. Three-tier pricing structure across premium forged, standard cast, and economy stamped levels separates fleet procurement platforms from independent distributor channels. Price differentiation rests on SAE J267 certification grade and volume scale in consolidated national contracts. Commercial fleet operators demonstrate lowest price sensitivity through total cost of ownership modeling, while small construction and landscaping businesses remain most reactive to acquisition cost differentials.
Supply Chain Analysis
Regional distribution centers in the industrial Midwest anchor hub-and-spoke patterns serving utility trailer OEMs and aftermarket channels. Manufacturing concentrates in the United States, Mexico, and Germany, with maquiladora operations in Nuevo León feeding cross-border OEM contracts. Raw material flows draw from primary aluminum smelters, carbon steel coil producers, and high-strength alloy billet suppliers. Single-source vulnerability concentrates in domestic steel wheel stamping clusters exposed to regional labor disruptions. Distribution runs through national fleet procurement platforms consolidating wheel-and-tire bundling agreements alongside traditional independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trailer wheel manufacturing is becoming a vertical-integration race as players pursue captive supply of high-strength aluminum billets to secure margin pools in forged alloy specifications.
For Market Incumbents: Lock in forged aluminum foundry capacity through equipment upgrades in Ohio and Michigan industrial corridors. Secure long-term billet supply agreements to insulate against London Metal Exchange volatility threatening margin predictability. Accelerate SAE J267 certification pipelines to compress competitive response windows for new wheel designs. For New Entrants and Emerging Players: Fiber-reinforced polymer fatigue-testing breakthroughs offer a technology-first wedge into lightweight specialty configurations unresolved under sustained radial loads. Target experimental electric trailer prototype programs in Querétaro industrial parks seeking hybrid material designs. Pursue direct digital procurement platform integration to bypass entrenched distributor markups in price-transparent fleet segments. For Investors and Strategic Acquirers: Re-rating potential sits with integrated foundry-to-finish aluminum producers given EPA phase-down schedule acceleration driving specification shifts from steel. Five-to-ten year viability favors manufacturers with backward integration into primary aluminum supply. Monitor state-level weight limit variance adoption rates as inflection indicators for aluminum penetration in heavy cargo configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Forged Foundry Capacity Expansion | Captures EPA-driven fleet specification shifts toward lightweight aluminum architectures in California and Northeast corridors. |
| Backward Integration into Billet Supply | Insulates margin pools from London Metal Exchange volatility compressing smaller fabricator competitiveness. |
| Digital Fleet Procurement Platform Launch | Bypasses traditional distributor markups through direct national logistics operator contracting with consolidated wheel-and-tire bundling. |
| Composite Material Fatigue Certification Investment | Resolves SAE J267 testing failures blocking fiber-reinforced polymer adoption in livestock and heavy cargo segments. |
| Cross-Border Maquiladora Manufacturing Scale-Up | Leverages Nuevo León cost structures to serve US utility trailer OEMs amid nearshoring supply chain restructuring. |
Research Methodology
Document review covered SEC 10-K filings, customs and trade data, EPA emissions enforcement records, and SAE technical standards, complemented by interviews with fleet procurement managers, foundry operations directors, aftermarket distribution channel heads, and OEM platform engineers. Primary fieldwork triangulated against secondary validation from aluminum industry association reports, NHTSA safety compliance databases, and state-level commercial vehicle regulatory filings. Bottom-up unit shipment modeling reconciled with top-down market value estimation across material tiers and rim diameter configurations.
Segmentation outputs reflect product type, application duty cycle, end-user procurement sophistication, and rim diameter specifications across the projection horizon. CAGRs derived from regression analysis of historical fleet equipment refresh patterns correlated with EPA phase-down schedule enforcement intensity. Forecast inputs incorporated foundry capacity utilization rates, London Metal Exchange aluminum price trend assumptions, and state-level weight limit variance adoption trajectories.
Several conditions sit outside the modeled scope, including unannounced tariff modifications on aluminum billet imports, breakthrough composite material certifications resolving SAE J267 fatigue failures, and disruptive electric trailer platform commercialization timelines. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and raw material price band stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Brazil Automotive Tire Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Wheel Spacers and Adapters Market