
 Automotive Racing Slicks Tire Market | 2026-2036
Automotive Racing Slicks Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Racing Slicks Tire Market Outlook
Silica-reinforced tread formulations is broadening the performance envelope for racing slicks in wet-heat conditions. Michelin leverages its Le Mans prototyping pipeline to sustain compound innovation across endurance grids. Pirelli anchors Formula supply contracts through captive trackside engineering services. Bridgestone competes in Super GT and IndyCar channels with controlled thermal-degradation profiles.
Automotive racing slicks tires are purpose-built, grooveless pneumatic tires constructed from specialized elastomer compounds with zero tread pattern, engineered to maximize contact-patch adhesion and heat-cycling consistency on dry paved circuits. Manufacturing integrates precision calendering, autoclave curing under nitrogen pressure, and laser-guided uniformity inspection to achieve sub-millimeter radial runout tolerances. Soft compound variants dominate qualifying sessions where single-lap grip determines grid position, while medium compound configurations represent the fastest-growing segment as sprint-format series proliferate. Endurance racing applications command premium positioning due to multi-stint durability requirements and team-level technical partnerships.
FIA technical regulations govern tire dimensions, compound allocations, and trackside temperature windows for Formula and World Endurance series. EPA emissions frameworks indirectly shape domestic motorsport venue operating permits, influencing regional event density and tire consumption patterns. ISO 9001 and ISO 14001 certifications function as baseline qualifiers for supplier qualification by factory-backed racing programs. Stakeholders must monitor evolving bio-sourced polymer mandates and thermal-efficiency benchmarks that will redefine compound formulation roadmaps.
Market Dynamics
FIA thermal-performance thresholds are compressing compound development cycles, forcing manufacturers to accelerate multi-compound prototyping while maintaining single-lap consistency across variable track temperatures.
Growth Catalysts
- Sprint-format proliferation:Short-duration race formats across regional touring car championships are elevating medium-compound procurement volumes. Teams prioritize rapid heat-cycle recovery over multi-stint durability.
- REACH polymer mandates:EU bio-sourced elastomer requirements are accelerating R&D investment in sustainable compound formulations. Manufacturers with captive polymer research facilities capture technical partnership contracts.
- Nürburgring endurance density:Germany's 24-hour and VLN calendar sustains year-round professional tire consumption. Amateur track-day programs extend addressable demand beyond factory-backed teams.
Market Restraints
- Natural rubber price volatility:Hevea brasiliensis supply concentration in Southeast Asia exposes compounders to input cost swings. Spot market fluctuations compress margin predictability for non-integrated manufacturers.
- Autoclave curing bottleneck:Nitrogen-pressure vessel capacity constraints limit batch throughput during peak racing seasons. Equipment lead times exceed twelve months for specialized curing infrastructure.
- Formula supply contract concentration:Exclusive technical partnerships with single-series organizers lock competitors out of premium positioning channels. New entrants face multi-year qualification barriers.
Strategic Opportunities
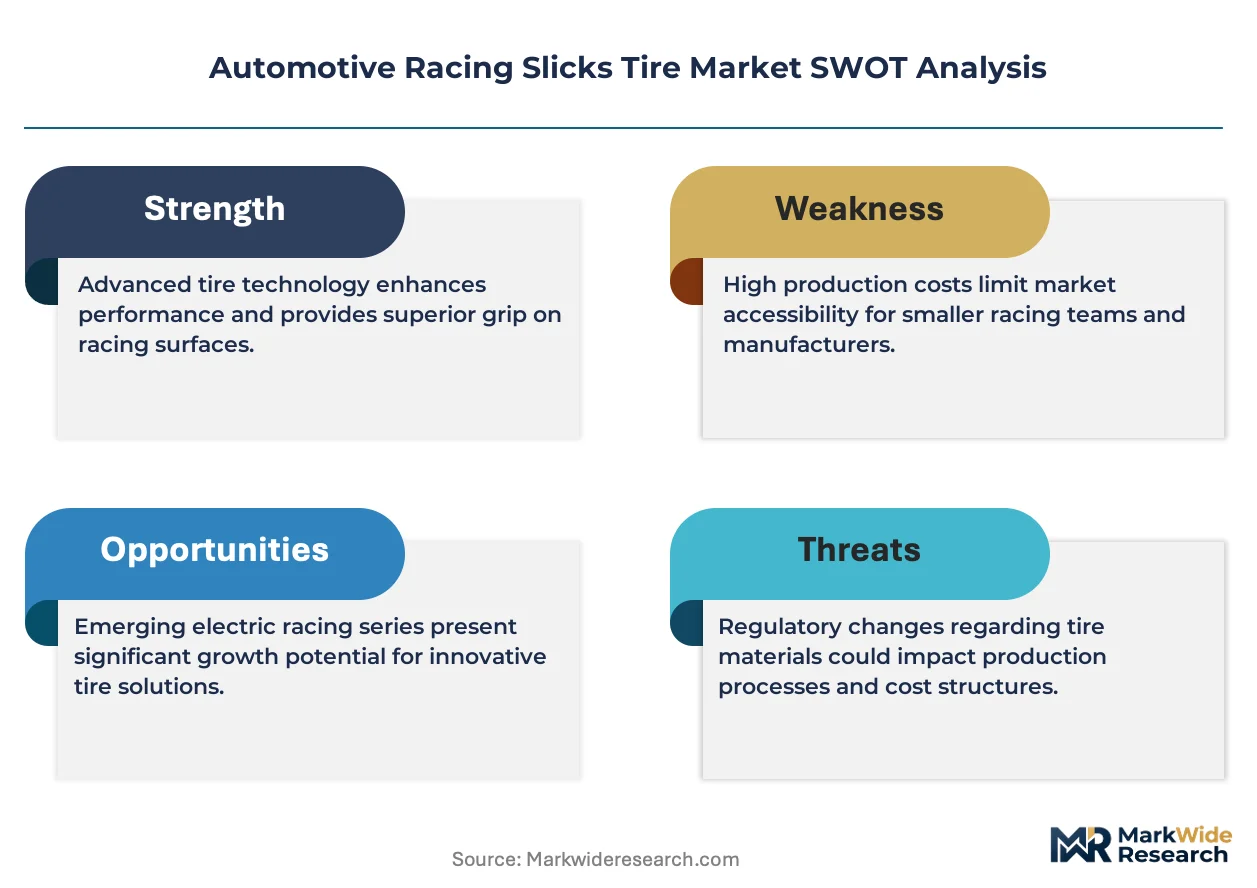
- Electric touring car expansion:FIA ETCR and regional EV championships are creating torque-optimized compound requirements. Instantaneous power delivery demands modified contact-patch pressure distribution.
- Trackside engineering unbundling:Independent data-analytics providers are fragmenting traditional manufacturer-captive service models. Third-party telemetry specialists enable smaller tire brands to compete on technical support.
- ISO 14001 certification premium:Factory-backed programs are mandating environmental management credentials as baseline procurement qualifiers. Early certifiers capture technical partnership renewals.
Industry Challenges
- Compounder talent scarcity:Specialized elastomer formulation expertise concentrates among retiring cohorts. Knowledge transfer mechanisms lag behind workforce transition timelines.
- Multi-stint simulation complexity:Predictive heat-degradation modeling requires integration of track-specific asphalt data, ambient condition variability, and vehicle-setup parameters. Validation cycles consume development bandwidth.
- Homologation timeline compression:FIA technical directive issuance windows are narrowing relative to season-start deadlines. Manufacturers face simultaneous compound validation across multiple championship calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Racing Slicks Tire Market |
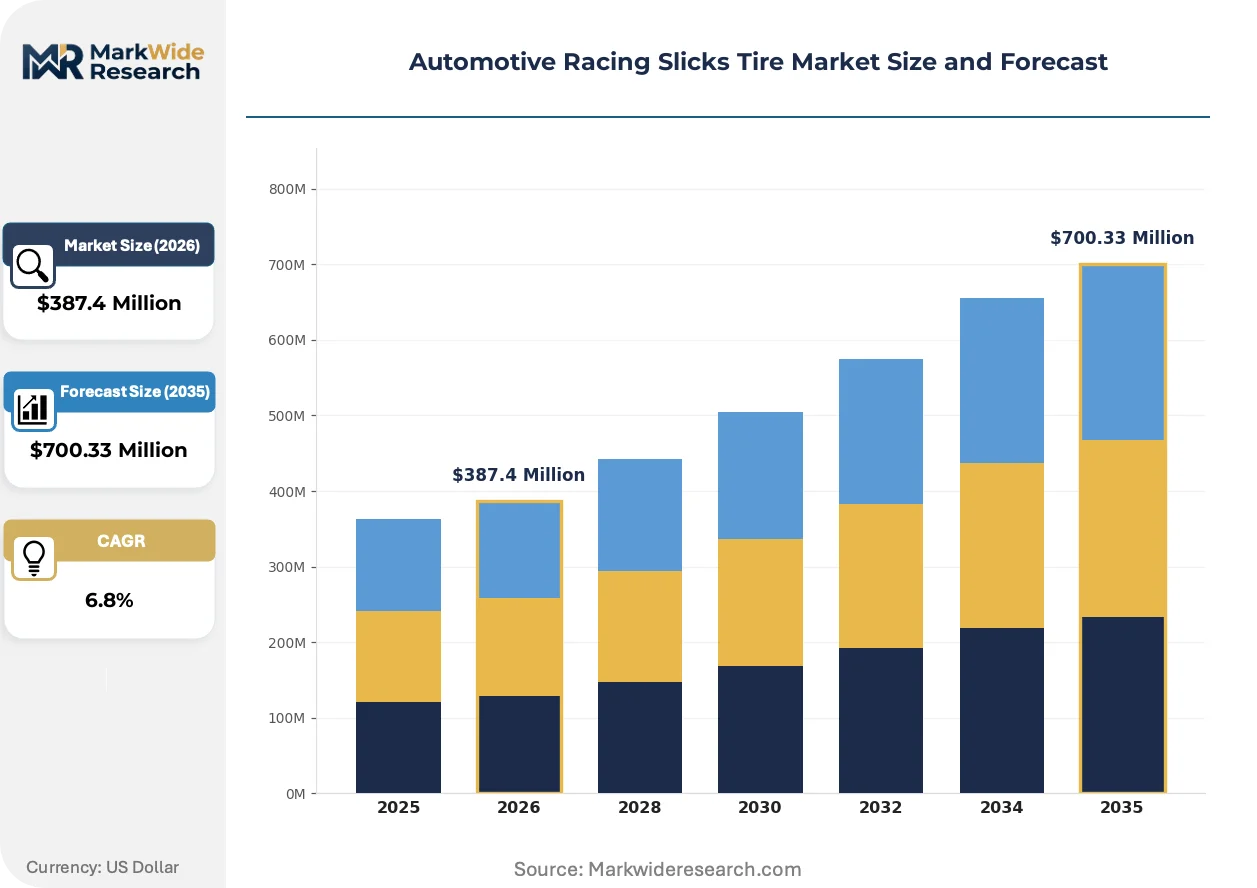
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Compound, Medium Compound, Hard Compound, Rain Tire Application: Formula Racing, Endurance Racing, Touring Car Racing, Drag Racing End User: Professional Teams, Amateur Racers, Racing Schools, Track Organizers Distribution Channel: Direct Sales, Online Retail, Specialty Stores, Distributors |
| Companies Covered | Goodyear, Yokohama, Michelin, Dunlop, Hankook, Pirelli, Continental, Toyo, Bridgestone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Racing Slicks Tire Market Strategic Shifts
Silica-reinforced tread chemistry is redefining wet-heat performance boundaries while regulatory pressure on polymer sourcing intensifies formulation roadmaps. Competitive positioning now hinges on trackside data integration capabilities.
Laser-guided uniformity inspection systems are expanding into production quality assurance at premium manufacturing facilities. Michelin deploys sub-millimeter radial runout detection across its Le Mans prototyping pipeline, compressing defect identification cycles from batch sampling to continuous monitoring. This precision layer is expanding into cost-optimized product tiers as calibration technology matures.
EU F-Gas Regulation constraints on industrial process emissions are reshaping autoclave curing infrastructure investment. Manufacturers must retrofit nitrogen recovery systems or absorb carbon-border adjustment costs on imported cured product. German KBA type-approval requirements for motorsport equipment are accelerating compliance expenditure among mid-tier compounders serving Nürburgring customer bases.
Direct technical partnership contracting is displacing distributor-mediated procurement among professional endurance teams. Squadra Corse and customer racing programs now negotiate compound allocation, trackside engineering, and data-analytics bundles directly with manufacturers. This channel compression is most visible in Germany, where Hockenheimring and Nürburgring proximity enables same-day logistics integration.
Automotive Racing Slicks Tire Market Segmentation
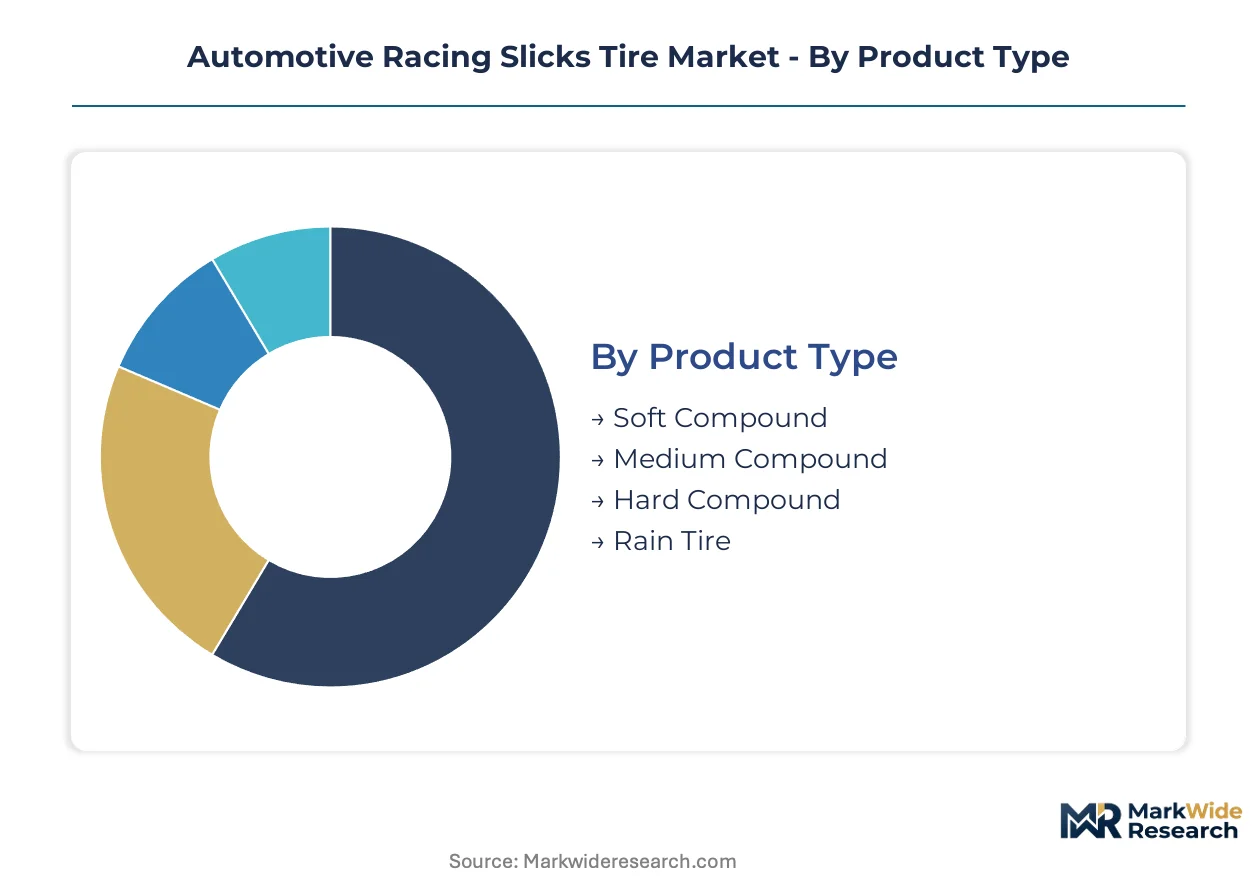
Racing slicks segmentation reflects the tension between qualifying-optimized grip and race-distance durability. Compound allocation strategies differ sharply across sprint formats versus endurance calendars. Distribution channel selection tracks team sophistication levels and procurement authorization structures.
Product Type:
Volume concentrates in medium compound procurement, while premium positioning anchors soft compound and rain tire development pipelines.
- Soft Compound:Ultra-low durometer elastomer formulations maximize mechanical keying with asphalt surfaces for single-lap qualifying performance. FIA Formula grids in Germany and Italy drive concentrated procurement, with teams accepting rapid thermal degradation as a tradeoff for grid position.
- Medium Compound:Balanced hysteresis characteristics deliver heat-cycle recovery across 15-25 lap stints without catastrophic grip cliff. Regional touring car championships and sprint endurance formats are elevating procurement volumes fastest as heat management protocols standardize.
- Hard Compound:High glass-transition polymer matrices resist abrasive wear on high-load circuits like Spa-Francorchamps and Monza. Long-distance endurance programs specify these for double-stint strategies.
- Rain Tire:Grooved tread patterns with silica-dominant compounds activate below track-specific moisture thresholds. Development investment clusters with Le Mans and WEC technical partnerships.
Mature deployment sits with soft compound qualifying sets. Newer deployment is concentrated in medium compound configurations as championship formats compress race distances.
Application:
Cost tier separation distinguishes factory-backed technical partnerships from customer racing procurement budgets.
- Formula Racing:FIA-mandated dimensional and compound allocation rules govern exclusive supply contracts. Thermal-performance threshold compliance consumes the majority of manufacturer R&D bandwidth.
- Endurance Racing:Multi-stint durability requirements command premium compound pricing and captive trackside engineering services. Michelin and Pirelli anchor technical partnerships through 24-hour race calendars.
- Touring Car Racing:Controlled tire regulations across BTCC, DTM, and Super GT limit compound variety to two or three specifications per event. Procurement volumes scale with grid size.
- Drag Racing:Specialized wrinkle-wall constructions and ultra-soft launch compounds optimize for straight-line acceleration. NHRA and FIA European Drag Racing Championship maintain distinct technical regulations.
Volume leadership belongs to touring car applications. Margin concentration flows through endurance racing technical partnerships.
End User:
Customer type determines service bundling depth and data-analytics integration intensity.
- Professional Teams:Factory-backed programs negotiate compound allocation, trackside engineering, and telemetry analysis as integrated contracts. ISO 14001 certification functions as a baseline procurement qualifier.
- Amateur Racers:Track-day participants and club competitors purchase through distributor networks with limited technical support. Price sensitivity drives preference for prior-season compound formulations.
- Racing Schools:Fleet procurement emphasizes durability and consistent heat-cycle behavior over ultimate grip. Long-term supply agreements with volume discounts predominate.
- Track Organizers:Nürburgring and Hockenheimring operations source control tires for amateur events and driving experiences. Logistics proximity to German manufacturing facilities shapes supplier selection.
Technical sophistication peaks with professional teams. Amateur racer volume is expanding fastest as track-day program accessibility broadens.
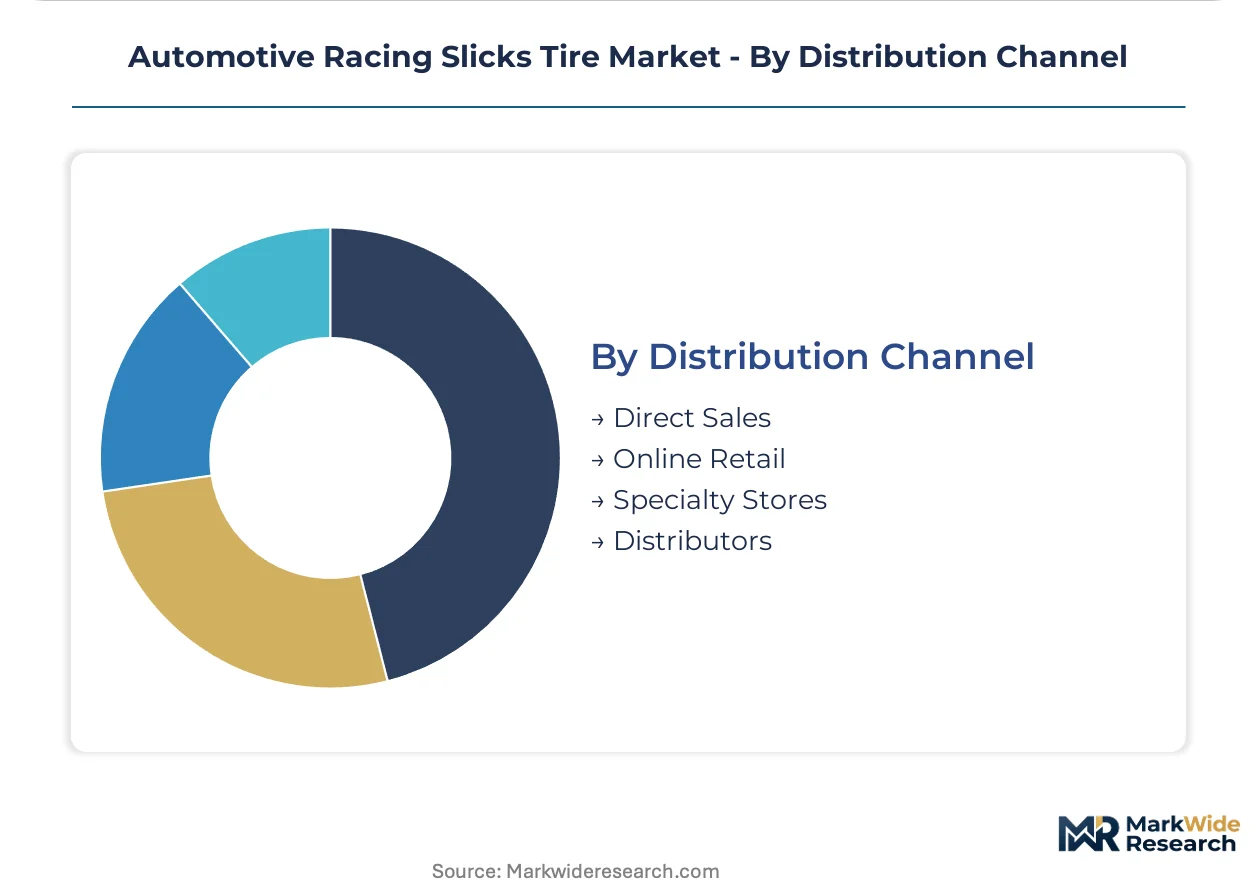
Distribution Channel:
Supply concentration favors direct manufacturer relationships for professional tiers, with fragmentation across retail channels for amateur segments.
- Direct Sales:Manufacturers negotiate technical partnership contracts directly with factory teams and endurance programs. This channel captures premium positioning and recurring revenue streams.
- Online Retail:E-commerce platforms serve amateur racers and club competitors with standardized compound offerings. Logistics integration with European distribution centers enables next-day delivery to German circuits.
- Specialty Stores:Motorsport-focused retailers provide compound consultation and mounting services. Physical presence near major racing circuits supports last-minute procurement.
- Distributors:Regional intermediaries aggregate demand from smaller teams and racing schools. Inventory carrying costs and compound shelf-life constraints limit distributor participation.
Channel compression is displacing distributor-mediated flows among professional tiers. Amateur procurement is fragmenting across online and specialty retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates the highest professional racing slicks procurement intensity, with Nürburgring and Hockenheimring calendars sustaining dense tire consumption across factory and amateur tiers.
Germany
The Nürburgring 24-hour and VLN endurance calendars sustain year-round professional tire demand. KBA type-approval requirements for motorsport equipment accelerate compliance expenditure among compounders serving German circuits. Stuttgart and Cologne manufacturing clusters anchor Michelin and Pirelli's captive trackside engineering operations.
United States
NHRA drag racing and IndyCar oval circuits generate specialized ultra-soft launch compound procurement. EPA emissions frameworks indirectly shape domestic motorsport venue operating permits, influencing regional event density. Indianapolis and Charlotte racing corridors concentrate tire distribution infrastructure for professional teams.
Japan
Super GT technical regulations and D1 Grand Prix drift series sustain medium-compound volume growth. METI industrial standards govern polymer research facility certifications for domestic compounders. Osaka-Nagoya manufacturing belt hosts Bridgestone's thermal-degradation profile development for controlled wear characteristics.
United Kingdom
BTCC controlled tire regulations limit compound variety to two or three specifications per event, scaling procurement with grid size. REACH polymer mandates accelerate R&D investment in sustainable formulations among UK-based technical partnerships. Silverstone and Brands Hatch circuits anchor Midlands distribution networks for professional endurance programs.
Italy
FIA Formula supply contracts concentrate premium positioning through exclusive technical partnerships. EU F-Gas Regulation constraints on industrial process emissions reshape autoclave curing infrastructure investment for Italian compounders. Monza and Imola circuits in Lombardy sustain high-load circuit abrasive wear testing for hard compound matrices.
Automotive Racing Slicks Tire Market Competitive Environment
Exclusive technical partnership contracting dominates the current landscape, displacing distributor-mediated flows among professional tiers. The vendor base concentrates around three to five integrated manufacturers with captive polymer research and trackside engineering capabilities. Two strategic archetypes prevail: full-stack compounders controlling upstream elastomer sourcing, and specialist motorsport divisions of diversified tire groups. Competitive intensity manifests through multi-year FIA supply contract bidding and autoclave curing capacity expansion.
Among the integrated compounder archetype, Michelin and Pirelli exemplify positions anchored by Le Mans prototyping pipelines and Formula supply relationships. Bridgestone occupies a distinct tier focused on Super GT and IndyCar thermal-degradation specialization. Yokohama represents the diversified group model with motorsport division scale advantages in regional touring car channels.
| Leading Market Players |
|---|
| Goodyear |
| Yokohama |
| Michelin |
| Dunlop |
| Hankook |
| Pirelli |
| Continental |
| Toyo |
| Bridgestone |
| Others |
Value Chain & Pricing Dynamics
Specialized elastomer formulation expertise concentrates among retiring cohorts in Southeast Asia, with labor-cost differentials between Thai and Malaysian compound development centers widening pricing-tier spreads for premium versus standard compound configurations.
Pricing Analysis
Volume concentrates in medium compound procurement while margin flows through soft compound qualifying sets and endurance racing technical partnerships. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 14001 certification status, captive trackside engineering bundling, and compound heat-cycle consistency grades. Price erosion runs through amateur racer segments as prior-season compound formulations flood distributor channels. Professional teams exhibit lowest price sensitivity due to integrated technical partnership contracting, while club competitors and racing schools drive hardest bargain on per-set procurement.
Supply Chain Analysis
Single-source vulnerability sits with Hevea brasiliensis natural rubber harvesting concentrated in Thailand, Indonesia, and Malaysia. Synthetic polymer feedstocks and silica reinforcement agents draw from German and Japanese petrochemical complexes. Tariff exposure on cured tire imports into EU markets compounds margin pressure for non-integrated manufacturers. Distribution runs through direct manufacturer relationships for factory-backed programs, with fragmentation across specialty retailers and online platforms for amateur tier procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive racing slicks tire market sits in a technology-transition phase as silica-reinforced tread chemistry displaces carbon-black dominant formulations and electric touring car torque demands reshape compound architecture.
For Market Incumbents: Deepen captive polymer research facility investments to secure REACH-compliant bio-sourced elastomer pipelines before EU mandates tighten. Expand autoclave curing capacity in Stuttgart and Cologne manufacturing clusters to relieve nitrogen-pressure vessel bottlenecks during peak racing seasons. Defend Formula supply contract positioning against emerging data-analytics unbundling threats by integrating telemetry services into technical partnership bundles.
For New Entrants and Emerging Players: The price-point gap between premium Michelin-Pirelli technical partnerships and economy-tier distributor-sourced amateur procurement creates white-space opportunity. Target amateur racer segments in Germany's Nürburgring track-day ecosystem with medium-compound offerings priced between prior-season clearance and current-season premium tiers. Penetrate through online retail channels with next-day logistics integration to Hockenheimring and Nürburgring circuits.
For Investors and Strategic Acquirers: The window for entry favors compounders with captive autoclave infrastructure and ISO 14001 certification credentials already secured. Long-term viability hinges on Le Mans prototyping pipeline access and FIA supply contract qualification timelines. Watch for FIA thermal-performance threshold tightening as inflection signal that will accelerate R&D spend requirements and consolidate vendor base around integrated manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Capacity Expansion | Relieves nitrogen-pressure curing bottlenecks during Nürburgring 24-hour and VLN peak demand windows. |
| Backward Integration into Bio-Sourced Polymers | Secures REACH-compliant elastomer supply chains ahead of EU bio-sourced mandate tightening. |
| Trackside Engineering Unbundling Partnership | Enables smaller tire brands to compete on technical support via third-party telemetry specialists. |
| Electric Touring Car Compound Development | Addresses FIA ETCR torque-optimized contact-patch pressure distribution requirements. |
| ISO 14001 Certification Acceleration | Captures factory-backed program renewals as environmental management credentials become baseline qualifiers. |
Study Parameters
Document review covered FIA technical regulations, EPA emissions frameworks, REACH polymer mandate documentation, and ISO certification standards, complemented by interviews with tire compound development directors, endurance racing team principals, motorsport distributor procurement leads, and KBA type-approval officers. Secondary validation drew from customs trade data, SEC filings of diversified tire groups, ECHA regulatory submissions, and endurance championship technical bulletins. Bottom-up procurement volume modeling triangulated against top-down manufacturer capacity assessments.
Cross-referencing historical compound allocation patterns against expert panel input on FIA regulatory trajectory shaped the analytical framework across the analysis window. Segmentation dimensions modeled include compound durometer grade, racing application format, end-user sophistication tier, and distribution channel structure. CAGRs derived from volume trajectory synthesis incorporating sprint-format proliferation rates, endurance calendar density, and electric championship expansion timelines. Forecast inputs captured natural rubber spot market volatility bands and autoclave curing capacity expansion pipelines.
Underlying measurement precision varies by segment; Formula Racing and Endurance Racing technical partnership data carry tighter precision than amateur racer distributor channel estimates. Forecasts reflect assumptions on FIA regulatory issuance timing, EU bio-sourced polymer mandate implementation pacing, and electric touring car championship grid scaling. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Wheel Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
Steel Tire Cord Market
Tires and Wheels
Bias Tire Market