
 Global Electric Vehicle Tire Market | 2026-2036
Global Electric Vehicle Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Vehicle Tire Market Analysis
The EU Green Deal is hardening emission benchmarks for automotive suppliers, forcing tire makers to reformulate compounds and retool production lines for low-rolling-resistance SKUs. Michelin leverages its silica-silane R&D pipeline to sustain premium positioning in European OEM channels. Bridgestone anchors North American supply through its Tennessee manufacturing complex, while Continental AG differentiates via integrated sensor-enabled tire systems for EV platforms.
An electric vehicle tire is a pneumatic or solid tire engineered with reinforced sidewalls, specialized tread compounds, and optimized contact patches to manage the instant torque, elevated curb weight, and extended range requirements of battery-electric propulsion systems; its primary purpose is to minimize energy loss while maintaining acoustic comfort and load-bearing capacity under continuous high-torque conditions. Radial construction dominates value capture due to structural durability under EV axle loads, while run-flat technology commands outsized margins from luxury OEMs seeking elimination of spare tire weight. Fleet operators represent the fastest-growing end-user channel as commercial electrification programs expand contracted tire-service agreements.
The EPA, ECHA, and China's MEE collectively enforce chemical disclosure, rolling resistance labeling, and end-of-life recovery mandates that dictate compound formulation and market access across the three largest demand centers. REACH restrictions on aromatic oils and the EU F-Gas Regulation on manufacturing emissions push suppliers toward bio-sourced synthetic rubber and water-based processing aids. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps.
Market Dynamics
Instant torque delivery from battery-electric powertrains is forcing tire engineers to redesign contact-patch geometry and heat-dissipation architecture, compressing development cycles while elevating performance thresholds beyond legacy ICE benchmarks.
Growth Catalysts
- California's Advanced Clean Trucks regulation:Fleet electrification mandates in the United States are accelerating procurement of EV-specific tire platforms for commercial vehicles, expanding addressable demand beyond passenger segments.
- Silica-silane compound innovation:Advanced tread formulations are reducing rolling resistance coefficients below legacy thresholds, directly extending vehicle range and satisfying OEM homologation requirements.
- German OEM channel concentration:Premium vehicle manufacturers headquartered in Germany are specifying integrated tire-sensor systems as standard equipment, pulling supplier R&D investment toward intelligent tire architectures.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply concentration exposes compounders to commodity swings that compress margin buffers on fixed-price OEM contracts.
- REACH aromatic oil restrictions:European chemical disclosure mandates are forcing reformulation of plasticizer packages, adding certification lag to new product introductions.
- Solid-state battery mass reduction:Lighter next-generation cell architectures threaten to obsolete current heavy-load tire designs before full amortization of specialized mold investments.
Strategic Opportunities
- India's PLI scheme for automotive components:Domestic manufacturing incentives are opening greenfield capacity for suppliers seeking to localize production for emerging EV assembly clusters.
- Tire-as-a-service models:Fleet operators are migrating from unit purchase to mileage-based subscription contracts, creating recurring revenue streams and captive data assets.
- China's dual carbon goals:National emissions targets are accelerating demand for low-rolling-resistance SKUs in the world's largest EV production base, favoring early-mover compounders with water-based processing capabilities.
Industry Challenges
- Acoustic engineering talent scarcity:Specialized noise-vibration-harshness expertise for EV-specific tread patterns commands premium compensation, constraining R&D bandwidth at mid-tier suppliers.
- Homologation timeline compression:Accelerated OEM platform launches are squeezing validation cycles for rolling resistance and wet-grip certification under UN ECE R117.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Vehicle Tire Market |
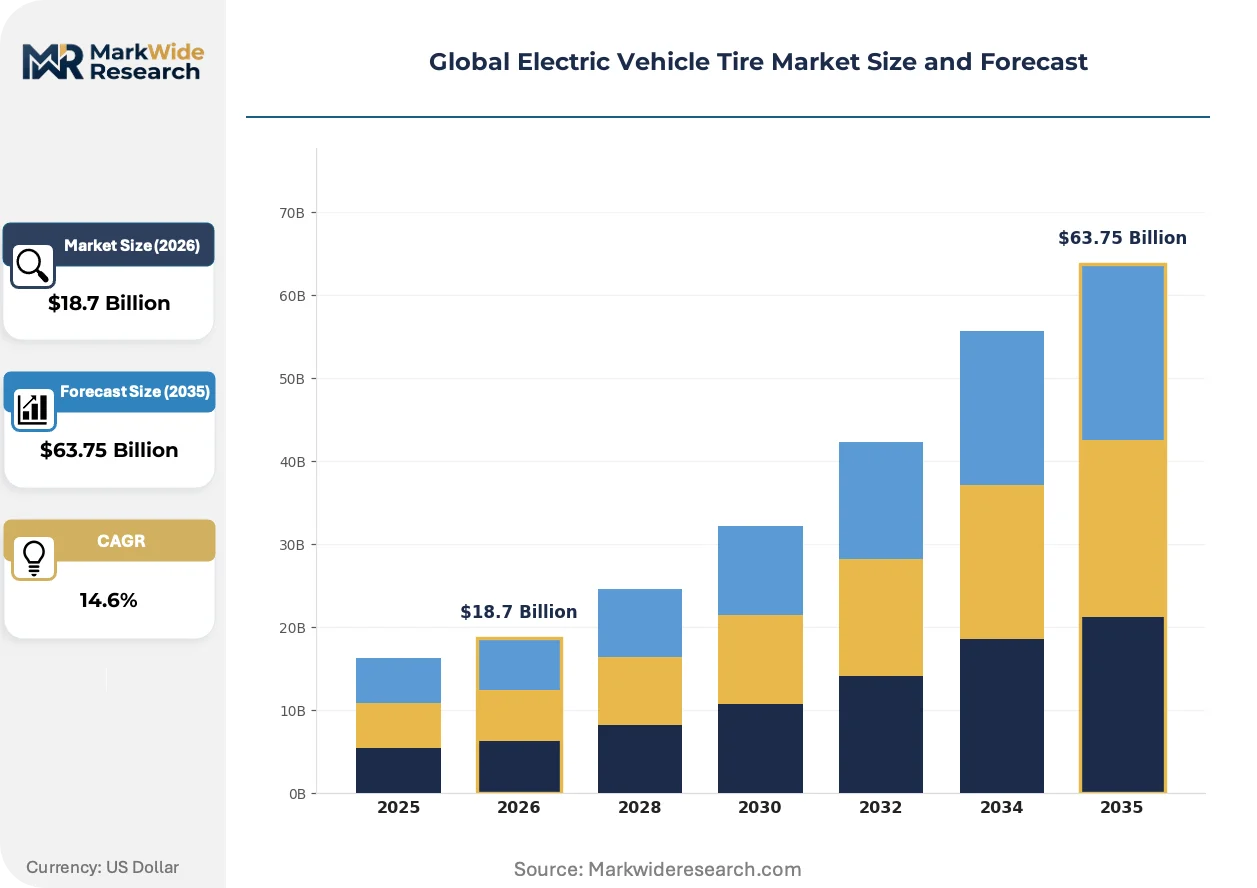
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Season, Summer, Winter, Performance Technology: Radial, Bias, Tubeless, Run-Flat End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks |
| Companies Covered | Michelin, Bridgestone Corporation, The Goodyear Tire & Rubber Company, Continental AG, Pirelli & C. SpA, Hankook Tire & Technology Co., Ltd., Sumitomo Rubber Industries, Ltd., Nokian Tyres plc, Yokohama Rubber Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Vehicle Tire Market Emerging Trajectories
Sensor-embedded tire architectures and AI-driven tread-wear prediction are converging to transform rubber products into data-generating vehicle components, redefining value capture beyond commodity manufacturing.
Enso is rewriting competitive positioning in the EV tire segment through thermoplastic elastomer formulations that eliminate petroleum-derived synthetic rubber entirely. Early adopters include Nordic fleet operators with explicit carbon-neutrality procurement criteria. The technology is compressing lifecycle emissions calculations for OEM sustainability reporting, forcing incumbent compounders to accelerate bio-sourced material roadmaps or risk exclusion from premium RFQs.
REACH restrictions on microplastic release from tire abrasion are mandating capture-device compatibility and tread-wear rate disclosures for all new homologations in the European Union. Tire makers must now integrate particulate measurement protocols into development workflows, adding testing overhead. Premium OEMs are responding by specifying minimum wear-performance thresholds that favor harder compound formulations, trading acoustic comfort for regulatory compliance.
Fleet procurement teams are consolidating supplier relationships around integrated service contracts that bundle tires, installation, rotation, and end-of-life recovery under single-vendor accountability. This displaces fragmented spot-purchase patterns dominant in ICE-era maintenance. The shift is most visible in Germany and the Netherlands, where logistics operators face binding CO2 reduction targets that require granular tire-performance data for regulatory verification.
Global Electric Vehicle Tire Market Segmentation
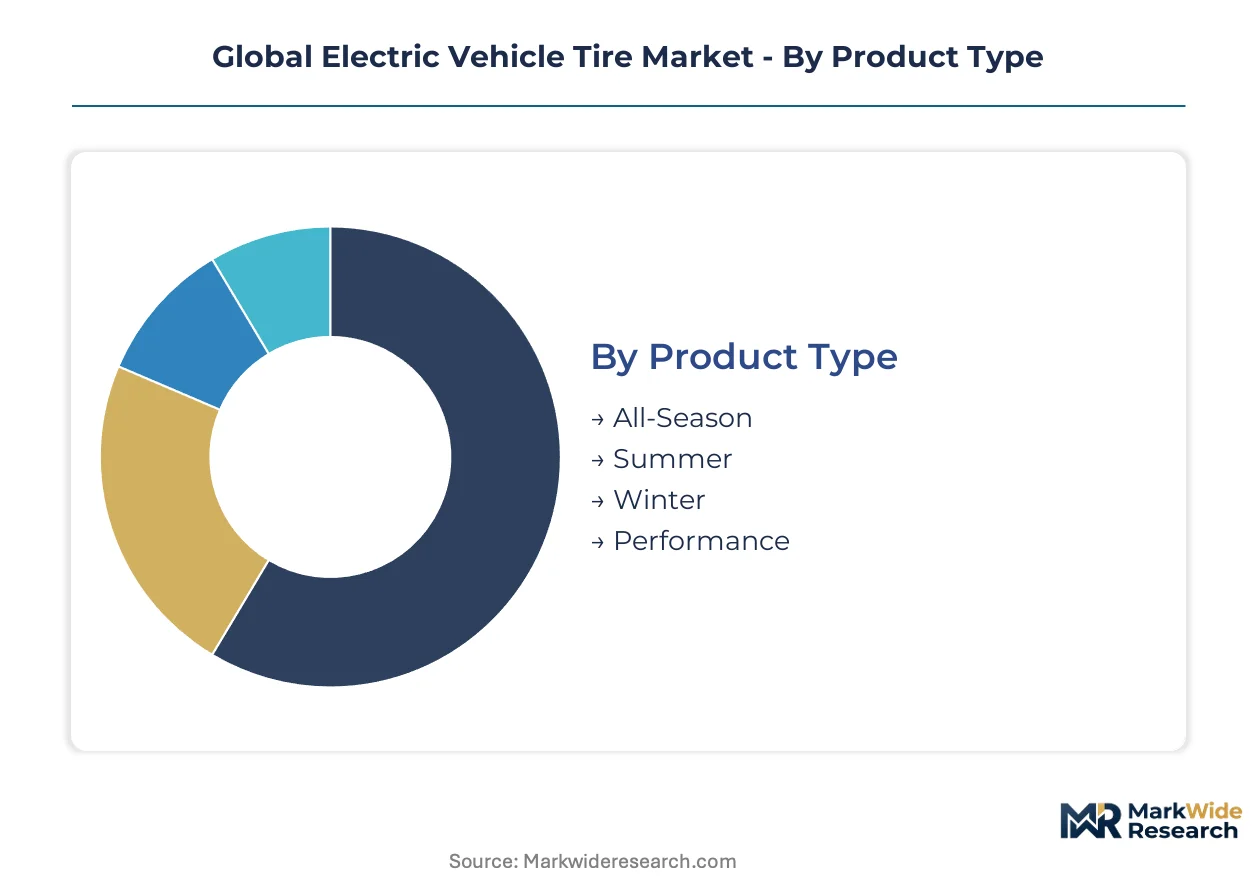
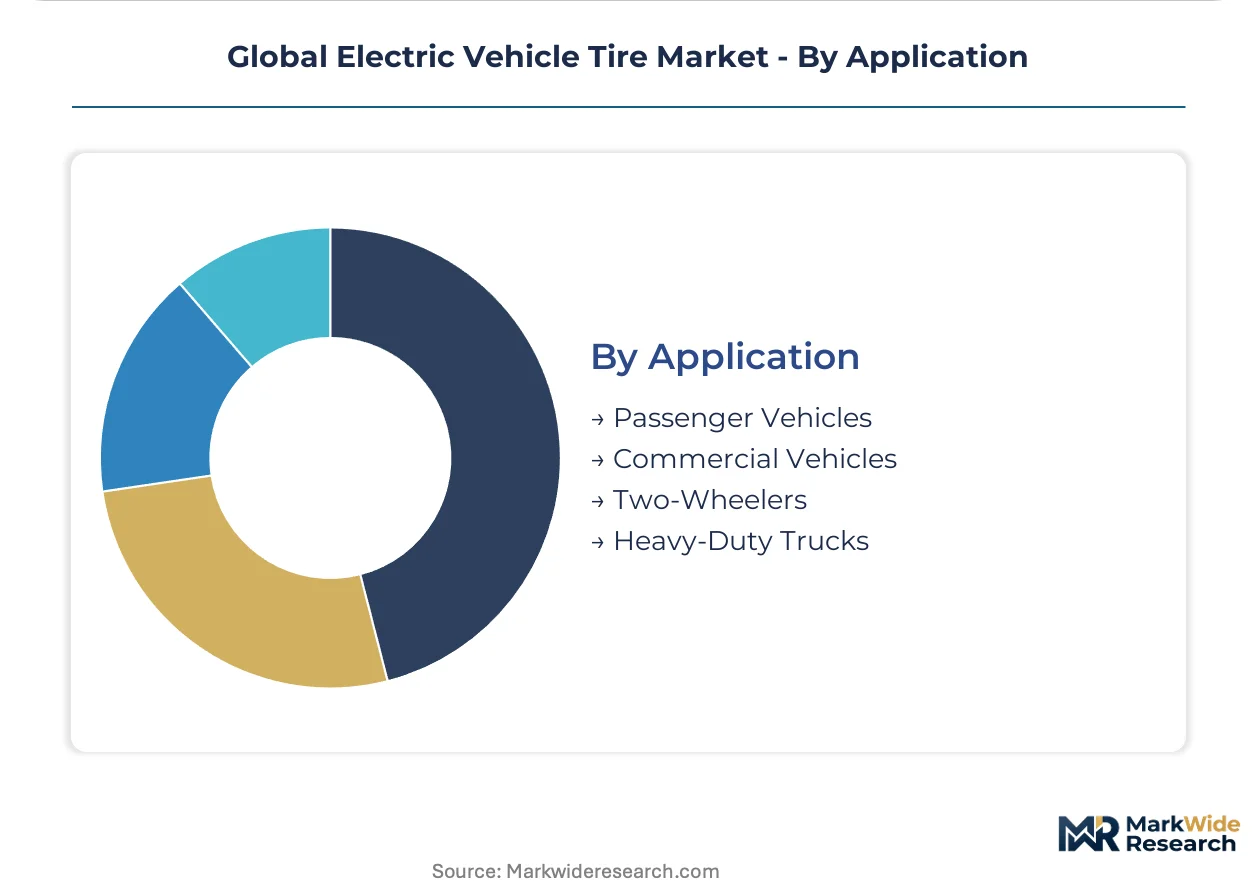
EV tire procurement splits sharply between OEM homologation requirements and aftermarket replacement cycles. Each segment category reflects distinct technical specifications, volume economics, and margin structures that suppliers must navigate simultaneously.
Product Type:
Buyers differentiate primarily by climate exposure and performance expectations rather than price sensitivity alone.
- All-Season:Multi-compound tread designs balance wet-grip silica content with cold-weather flexibility polymers. OEM channel concentration in Germany and the United States favors these SKUs for base-model homologation, though California fleet operators are specifying dedicated summer-winter rotations to maximize range.
- Performance:Aramid-reinforced sidewalls and asymmetric tread patterns manage instant torque delivery from dual-motor configurations. German premium manufacturers specify these as standard equipment, pulling compounders toward higher glass-transition temperature formulations that sacrifice some rolling resistance for dry-grip confidence.
- Summer:Specialized tread compounds optimize for high-temperature durability and hydroplaning resistance. Mediterranean markets and Middle Eastern fleets specify these exclusively.
- Winter:Soft-compound formulations with siped tread patterns maintain elasticity below freezing. Nordic countries mandate these through seasonal tire regulations.
Volume sits with All-Season; growth tilts toward Performance as dual-motor EV architectures proliferate.
Technology:
Construction method determines load-bearing capacity, repairability, and sensor integration potential.
- Radial:Steel-belted carcass construction distributes EV axle loads across broader contact patches. This architecture captures the majority of OEM specification in China, Germany, and the United States due to structural durability under continuous high-torque conditions.
- Run-Flat:Reinforced sidewall inserts enable extended mobility after pressure loss, eliminating spare tire weight. German luxury OEMs specify these as standard, commanding outsized margins despite higher rolling resistance coefficients.
- Bias:Cross-ply construction offers simpler manufacturing for emerging market price points. Limited to two-wheeler and select commercial applications.
- Tubeless:Sealed rim interfaces reduce unsprung mass and simplify roadside service. Aftermarket conversion demand concentrates in India and Southeast Asia.
Radial construction dominates unit economics; Run-Flat technology captures premium positioning fastest.
End User:
Procurement scale and service integration requirements separate institutional buyers from fragmented retail demand.
- Fleet Operators:Contracted tire-service agreements bundle installation, rotation, and end-of-life recovery under mileage-based subscription models. Logistics operators in Germany and the Netherlands are consolidating supplier relationships around these integrated contracts to meet binding CO2 reduction targets.
- OEMs:Homologation timelines and rolling resistance certification under UN ECE R117 constrain supplier selection. German, Chinese, and US vehicle manufacturers specify integrated tire-sensor systems as standard equipment.
- Aftermarket Providers:Independent service networks compete on installation speed and inventory breadth. Price pressure intensifies as Chinese manufacturing capacity expands.
- Individual Consumers:Replacement purchases follow wear-indicator triggers with limited brand loyalty. Online direct-to-consumer channels are fragmenting traditional retail capture.
Volume concentrates with OEMs; expansion is steepest among Fleet Operators as commercial electrification accelerates.
Application:
Axle load and duty cycle requirements dictate compound durability and heat-dissipation architecture.
- Passenger Vehicles:Low-rolling-resistance compounds prioritize range extension over load capacity. This segment absorbs the majority of silica-silane R&D investment as German and Chinese OEMs compete on efficiency ratings.
- Commercial Vehicles:Reinforced carcass designs manage elevated curb weights from battery-electric powertrains. California's Advanced Clean Trucks regulation is accelerating procurement of EV-specific platforms for last-mile delivery and regional haul.
- Two-Wheelers:Compact tire dimensions with high-pressure ratings suit urban mobility applications. Indian and Southeast Asian markets dominate specification.
- Heavy-Duty Trucks:Multi-axle load distribution and retread compatibility drive design priorities. Limited homologation activity concentrates in European pilot programs.
Passenger Vehicles anchor current volume; Commercial Vehicles are climbing the fastest as fleet electrification mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European OEM specification activity for EV-specific tire platforms, while Qingdao and Shanghai concentrate Chinese manufacturing capacity for silica-silane compound production. Detroit and Los Angeles drive North American fleet procurement programs under tightening state-level electrification mandates.
China
Qingdao's tire manufacturing corridor supplies the majority of domestic EV OEM demand through radial construction platforms optimized for battery-electric axle loads. The Ministry of Ecology and Environment enforces chemical disclosure mandates under dual carbon goals that accelerate water-based processing adoption. Shanghai's Pudong district hosts compound R&D facilities serving BYD and Tesla's Gigafactory Shanghai with low-rolling-resistance formulations.
Germany
Munich and Stuttgart-based premium manufacturers specify run-flat tire systems as standard equipment for dual-motor EV architectures. The KBA enforces UN ECE R117 rolling resistance certification timelines that compress supplier validation cycles. Continental's Hanover headquarters anchors integrated sensor-enabled tire development for German OEM channels seeking intelligent tire architectures.
United States
California's Advanced Clean Trucks regulation accelerates commercial EV tire procurement through Los Angeles and Long Beach port logistics operators. The EPA coordinates with NHTSA on fuel economy standards that indirectly pressure tire rolling resistance coefficients. Michelin's Greenville, South Carolina facility supplies southeastern OEM assembly plants with all-season compounds for base-model homologation.
India
Chennai's automotive corridor attracts greenfield tire capacity under the PLI scheme for automotive components targeting domestic EV assembly clusters. The Bureau of Indian Standards mandates labeling compliance for rolling resistance performance on imported SKUs. Gujarat's Sanand industrial zone hosts emerging tubeless tire conversion demand from two-wheeler electrification programs in Ahmedabad and Surat.
Japan
Nagoya's industrial belt concentrates heat-dissipation R&D for performance tire compounds managing instant torque from dual-motor configurations. METI coordinates national standards alignment with UN ECE regulations to preserve export market access. Yokohama's Kanagawa prefecture maintains compound formulation facilities serving Toyota and Nissan EV platforms with specialized tread patterns.
Global Electric Vehicle Tire Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration and OEM homologation depth. The market structure consolidates around compound innovation leaders and sensor-embedded system specialists, with mid-tier fabricators competing on aftermarket volume and price positioning. Three archetypes dominate: integrated intelligent tire architects, silica-silane compound specialists, and fleet-service contract consolidators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as suppliers secure OEM homologation slots and localized manufacturing positions.
Within the integrated intelligent tire tier, Continental AG and Michelin exemplify archetype positioning through European OEM channel concentration. Hankook Tire & Technology Co., Ltd. anchors Korean manufacturing scale for global supply diversification. Bridgestone Corporation occupies a position spanning premium OEM specification and North American aftermarket breadth.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone Corporation |
| The Goodyear Tire & Rubber Company |
| Continental AG |
| Pirelli & C. SpA |
| Hankook Tire & Technology Co., Ltd. |
| Sumitomo Rubber Industries, Ltd. |
| Nokian Tyres plc |
| Yokohama Rubber Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
German premium OEMs and California fleet operators command distinct pricing architectures that stratify across performance tiers, with value-based contracts for sensor-integrated tires displacing transactional spot purchases in high-volume channels.
Pricing Analysis
Range-extension performance anchors value-based pricing for silica-silane compounds, with OEMs paying premiums for UN ECE R117-certified rolling resistance grades that directly influence vehicle efficiency ratings. Price differentiation separates run-flat systems specified by Munich and Stuttgart manufacturers from standard radial constructions serving Chinese domestic brands. Cost compression in the aftermarket tier is intensifying because Chinese manufacturing capacity expansion floods spot-purchase channels with unbranded inventory. Fleet operators show lowest price sensitivity due to mileage-based subscription economics, while individual consumers in India and Southeast Asia drive aggressive commoditization.
Supply Chain Analysis
Specialized acoustic engineering talent shortages in Stuttgart, Nagoya, and Detroit constrain mold-design throughput and compress development timelines for noise-optimized tread patterns. Manufacturing gravity centers on Qingdao's tire corridor, Tennessee's production complex, and Hanover's R&D facilities. Compound formulation draws from Thai and Indonesian natural rubber, precipitated silica from China, and aramid fibers from domestic European sources. Single-source vulnerability concentrates in aromatic oil alternatives subject to REACH reformulation mandates. Distribution runs through OEM homologation channels, fleet-service integrators, and fragmented aftermarket retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV tire sector sits in a compound-innovation transition, with thermoplastic elastomer formulations from emerging suppliers displacing petroleum-derived synthetic rubber in Nordic fleet procurement.
For Market Incumbents: Anticipate thermoplastic elastomer substitution threatening premium positioning by accelerating bio-sourced material roadmaps and securing exclusive sensor-integration partnerships with German OEM platform teams. Backward integration into water-based processing capabilities defends margin structure against REACH compliance cost inflation. For New Entrants and Emerging Players: Capture India's PLI-subsidized manufacturing capacity before incumbent localization locks in supplier relationships with Chennai-based EV assembly clusters. Fleet-as-a-service subscription models in Germany and the Netherlands offer the most penetrable entry vector, with carbon-neutrality certification as the decisive go-to-market credential. For Investors and Strategic Acquirers: The window for entry favors compound-innovation specialists with demonstrated water-based processing scale and existing OEM homologation relationships. Long-term viability hinges on defensible positions in sensor-embedded architectures as intelligent tires become standard equipment. Monitor solid-state battery mass-reduction timelines as the critical inflection signal threatening heavy-load tire design amortization.| Strategic Initiative | Industry Significance |
|---|---|
| Silica-Silane Capacity Expansion | Qingdao and Tennessee facilities must scale to meet OEM range-extension specifications under California ACT mandates. |
| Sensor-Platform Integration | Continental's Hanover architecture demonstrates how tire data streams lock in German OEM channel exclusivity. |
| Bio-Sourced Compound Transition | Enso's thermoplastic formulations force incumbents to reformulate or forfeit Nordic fleet RFQs. |
| Fleet-Service Contract Consolidation | Mileage-based subscriptions in Rotterdam and Hamburg displace fragmented spot purchasing with recurring revenue capture. |
| Water-Based Processing Adoption | China's MEE enforcement under dual carbon goals favors early movers with compliant manufacturing infrastructure. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with tire R&D directors, OEM platform engineers, fleet procurement managers, and aftermarket distribution heads. ECHA REACH substance databases, EPA fuel economy certification records, UN ECE R117 homologation registries, and vehicle production databases provided validation benchmarks. Bottom-up volume modeling and top-down value reconciliation triangulated segment estimates across the analysis window.
Production-volume streams from IHS Markit registration data reconciled with compounder shipment disclosures and OEM tire-fitment specifications. Segmentation dimensions spanned propulsion architecture, vehicle class, construction technology, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated against fleet electrification mandate timelines and battery-electric production ramp rates. Silica-silane adoption curves and sensor-integration penetration rates informed technology-transition assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state battery commercialization, natural rubber commodity swings, and divergence between EU and US chemical disclosure regimes. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
Tire Building Machinery Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Rechargeable Tires Market