
 Global Tire Curing Press Machine Market | 2026-2036
Global Tire Curing Press Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tire Curing Press Machine Market Outlook
The capital-intensity divergence between Tier-1 system integrators and regional fabricators is bifurcating competitive tiers in tire curing press supply. Mitsubishi Heavy Industries Machinery Systems Ltd. leverages its integrated mechatronics platform to dominate high-throughput radial tire lines. Greatoo Intelligent Equipment Inc. anchors its position through captive servo-hydraulic control technology and proximity to Chinese tire OEM clusters. Himile Mechanical Science and Technology Co. Ltd. differentiates via precision mold-handling automation for complex tread geometries.
A tire curing press machine applies controlled heat and pressure to vulcanize green tire assemblies into finished products, typically operating at clamping forces exceeding 2,500 kN and temperatures near 180°C to cross-link rubber compounds. Electromechanical and automated product types are capturing margin pools as energy costs and cycle-time precision reshape buyer economics. Application demand concentrates in passenger vehicles where run-flat and low-rolling-resistance tire architectures require tighter bladder-pressure control. Heat transfer and automated systems technology segments are expanding fastest as tire manufacturers retrofit legacy hydraulic floors.
EU F-Gas Regulation and REACH compliance are pressuring European tire builders to specify closed-loop thermal systems with reduced refrigerant leakage risk. China's GB energy-efficiency standards and India's BIS machinery safety codes are tightening import eligibility for used or non-certified press equipment. The US EPA and OSHA jointly influence thermal emissions and worker-safety specifications for domestic tire plant retrofits. Stakeholders must monitor how regional carbon-border adjustments and machinery-safety harmonization reshape total cost of ownership for cross-border press procurement.
Market Dynamics
Electromechanical press architectures are compressing energy footprints and cycle times, forcing legacy hydraulic floor retrofits across Southeast Asian tire clusters while EU F-Gas Regulation accelerates thermal system replacement timelines.
Growth Catalysts
- EU Energy-Efficiency Directives:Electromechanical curing press specifications are displacing hydraulic systems in German and Italian tire plants seeking carbon-border compliance.
- Passenger Vehicle Radialization:Run-flat and low-rolling-resistance tire architectures in Vietnam and Indonesia require tighter bladder-pressure control, driving press automation upgrades.
- China's Dual Carbon Goals:GB energy-efficiency standards are mandating servo-hydraulic retrofits, expanding replacement demand from domestic tire OEM clusters.
Market Restraints
- Steel and Servo Motor Cost Volatility:Input price swings for high-grade alloys and precision motion components compress fabricator margins on fixed-price contracts.
- Regional Supply Concentration:Critical electromechanical subsystems concentrate among Japanese and German component specialists, creating single-source exposure for tier-2 press builders.
- REACH Compliance Friction:Complex chemical substance documentation requirements for thermal fluids and sealants delay EU certification timelines for non-European press exporters.
Strategic Opportunities
- India BIS Machinery Safety Codes:Tightening import eligibility for non-certified equipment creates white space for compliant electromechanical press suppliers in Maharashtra and Tamil Nadu tire corridors.
- Automotive OEM Direct Sourcing:Tire manufacturers are unbundling after-sales service contracts, opening channel entry for specialized bladder and mold-handling automation providers.
- Heat Transfer-Conveyance Convergence:Integration of automated mold shuttle systems with closed-loop thermal management is enabling single-floor layouts for greenfield Southeast Asian plants.
Industry Challenges
- Mechatronics Talent Scarcity:Shortage of servo-hydraulic control engineers and thermal systems specialists constrains deployment velocity for electromechanical retrofits.
- Legacy Floor Integration Complexity:Hydraulic press foundations and pit configurations in mature US and European plants resist electromechanical drop-in replacement without structural rework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tire Curing Press Machine Market |
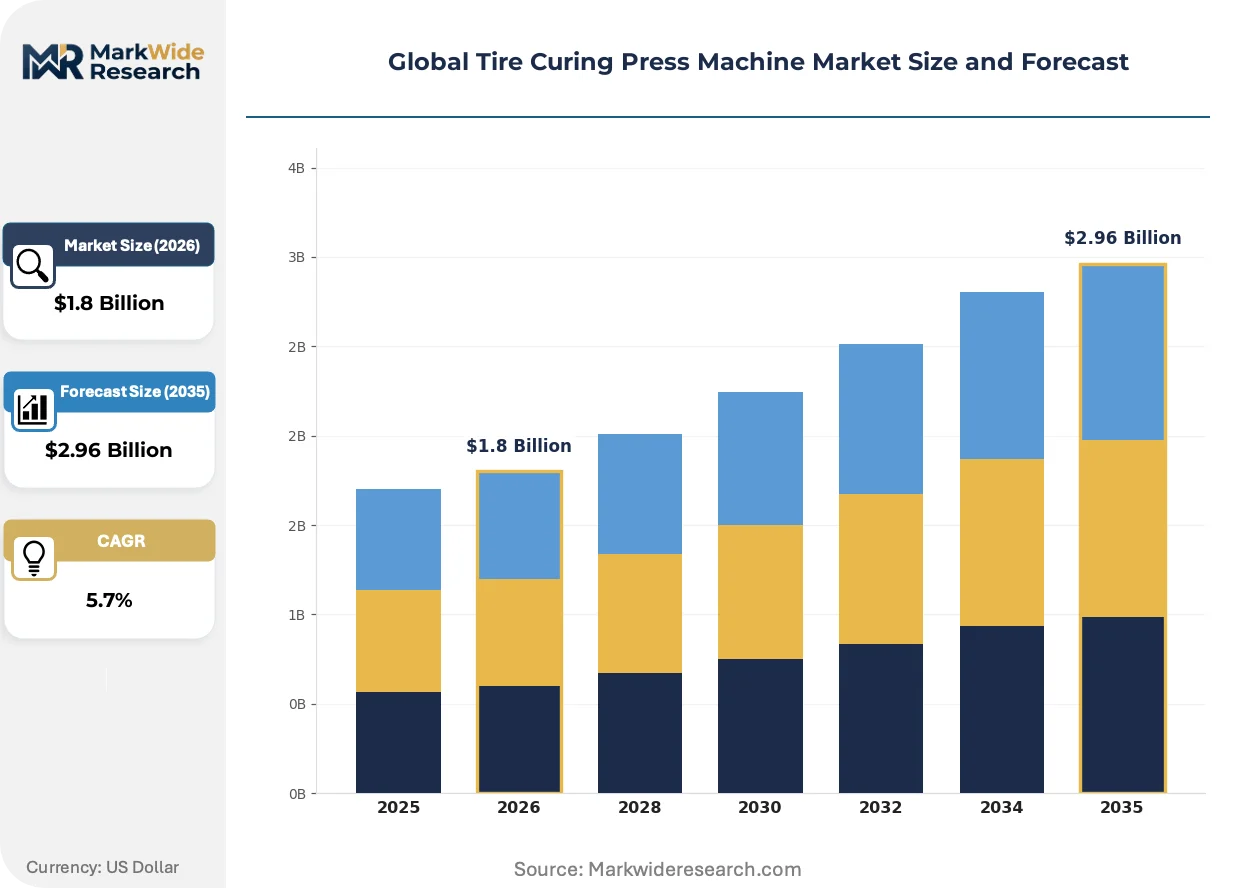
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Mechanical, Electromechanical, Automated End User: Tire Manufacturers, Rubber Processors, OEMs, Aftermarket Suppliers Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Specialty Tires Technology: Heat Transfer, Pressure Control, Automated Systems, Manual Control |
| Companies Covered | McNeil & NRM Inc., Cima Impianti S.p.A., Mitsubishi Heavy Industries Machinery Systems Ltd., Greatoo Intelligent Equipment Inc., HERBERT Maschinenbau GmbH & Co. KG, Himile Mechanical Science and Technology Co. Ltd., Harburg-Freudenberger Maschinenbau GmbH, Qingdao Mesnac Co. Ltd., Tianjin Saixiang Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tire Curing Press Machine Market Strategic Shifts
Digital twin architectures and predictive maintenance platforms are compressing unplanned downtime in high-throughput radial tire lines, while regulatory pressure on thermal emissions accelerates closed-loop system adoption.
Servo-electric bladder control systems are miniaturizing precision pressure modulation for complex tread geometries. Tier-1 tire manufacturers in Japan and South Korea are deploying these systems for run-flat production cycles. This miniaturization is enabling single-operator press banks and reducing per-unit energy draw by eliminating hydraulic powerpack infrastructure.
EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in tire plant thermal systems from 2030. European tire builders are specifying ammonia-based and CO2 transcritical heat pumps for curing press temperature loops. German and Italian OEMs are front-loading capital allocation to avoid stranded asset risk in legacy chiller infrastructure.
Buyer consolidation among multinational tire groups is compressing vendor negotiation cycles and unbundling long-term service agreements. Direct procurement of bladder replacement schedules and predictive analytics subscriptions is displacing bundled maintenance contracts. This pattern is most visible in Thailand and Vietnam where greenfield plant operators prioritize operational expenditure transparency over capital-heavy legacy service models.
Global Tire Curing Press Machine Market Segmentation
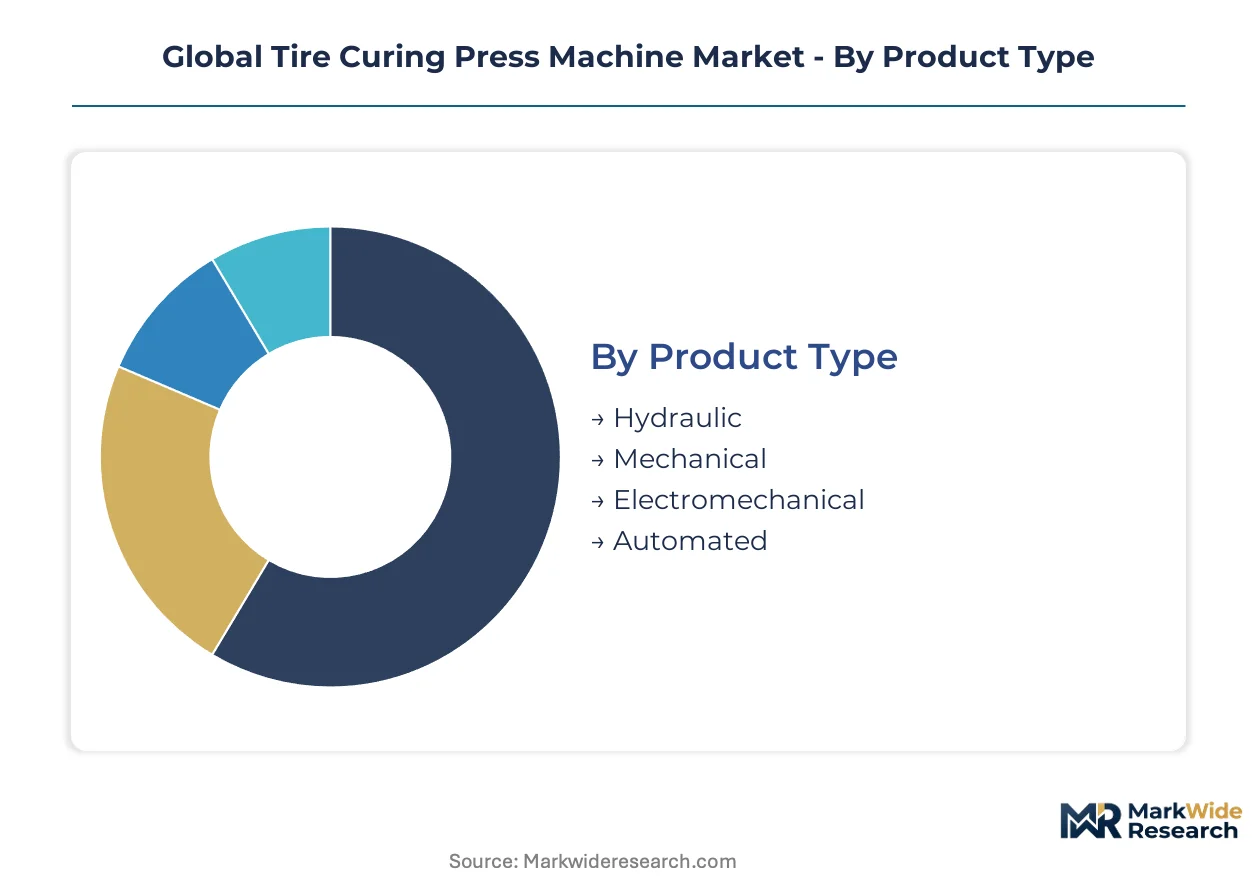
Tire curing press procurement patterns diverge sharply across technology platforms and buyer archetypes. Equipment specification varies by end-use volume requirements, regional energy regulations, and plant automation maturity.
Product Type:
Electromechanical architectures are displacing legacy hydraulic floors as EU F-Gas Regulation tightens thermal emissions compliance and electricity costs reshape Southeast Asian factory economics.
- Hydraulic:Clamping force generation through fluid-power cylinders dominates mature US and European installations. Foundation retrofit costs and mechatronics talent scarcity slow replacement timelines in these legacy footprints.
- Mechanical:Linkage-based force transmission persists in cost-sensitive batch operations. Vietnamese and Indonesian greenfield operators bypass this tier entirely for servo-controlled alternatives.
- Electromechanical:Servo-electric drive systems eliminate hydraulic infrastructure and compress cycle times. Japanese and South Korean tire OEMs specify these for run-flat production lines requiring bladder-pressure precision.
- Automated:Integrated mold-handling and thermal-loop robotics enable single-operator press banks. Thai and Vietnam greenfield plants prioritize this tier for labor-cost containment and throughput maximization.
Hydraulic retains volume leadership in installed base; automated holds the steepest expansion curve.
End User:
Buyer consolidation among multinational tire groups is compressing vendor negotiation power and fragmenting after-sales service procurement.
- Tire Manufacturers:Bridgestone, Michelin, and Continental unbundle long-term maintenance contracts and source bladder replacements and predictive analytics separately. Direct OEM procurement of automation subsystems is rising.
- Rubber Processors:Compound suppliers and intermediate processors require curing capacity for prototype and specialty batch production. Smaller press footprints and manual control systems dominate this tier.
- OEMs:Automotive manufacturers with captive tire operations specify electromechanical presses aligned with corporate carbon-neutrality targets. German and Japanese automotive OEMs drive specifications here.
- Aftermarket Suppliers:Retread and remanufacturing operators prioritize hydraulic mechanical simplicity and parts availability. Cost pressure limits automation penetration in this segment.
Tire manufacturers command the largest equipment procurement volumes; OEMs are climbing fastest on electrification mandates.
Application:
Passenger vehicle radialization is concentrating investment in bladder-pressure precision, while commercial vehicle demand favors durability over cycle-time compression.
- Passenger Vehicles:Run-flat and low-rolling-resistance architectures require tight thermal and pressure control. Electromechanical presses with servo-electric bladder systems dominate new capacity in Vietnam and Indonesia.
- Commercial Vehicles:Heavy-duty truck and bus tires prioritize clamping force endurance over speed. Hydraulic systems persist in this segment due to lower capital intensity and simpler maintenance protocols.
- Off-Road Vehicles:Mining and construction tire curing requires oversized press configurations with extended heat-soak cycles. Specialty fabricators serve this niche with customized thermal systems.
- Specialty Tires:Aircraft, agricultural, and two-wheeler applications demand mold-handling flexibility for low-volume, high-mix production. Automated mold shuttle systems enable economic batch sizes here.
Passenger vehicles anchor procurement volumes; specialty tires are expanding most quickly on aviation and electric two-wheeler demand.
Technology:
Heat transfer and automated systems are capturing capital allocation as energy costs and labor scarcity reshape buyer economics.
- Heat Transfer:Closed-loop thermal management with ammonia-based or CO2 transcritical heat pumps is displacing hydrofluorocarbon chillers ahead of EU F-Gas bans. German and Italian tire builders front-load this transition.
- Pressure Control:Servo-hydraulic and servo-electric bladder modulation enables complex tread geometries. Miniaturized precision systems from Japanese component specialists concentrate supply risk.
- Automated Systems:Mold shuttle robotics and predictive maintenance platforms compress unplanned downtime. Digital twin architectures from Mitsubishi Heavy Industries and Himile Mechanical anchor competitive differentiation.
- Manual Control:Operator-dependent systems persist in retread operations and emerging-market micro-factories. GB energy-efficiency standards and India's BIS codes are narrowing import eligibility for this tier.
Heat transfer commands replacement-driven demand; automated systems are gaining share fastest on greenfield plant specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in tire curing press machinery reveal a shifting trade balance as electromechanical technology transfers from German and Japanese engineering centers toward Southeast Asian manufacturing clusters. Capital equipment flows concentrate where radial tire capacity expands fastest.
China
Domestic tire OEM clusters in Shandong and Jiangsu provinces drive procurement of servo-hydraulic retrofits under GB energy-efficiency standards. MIIT machinery certification requirements tighten import eligibility for non-compliant used equipment. Qingdao and Guangzhou anchor greenfield press deployment for passenger vehicle radial lines.
Germany
EU F-Gas Regulation accelerates thermal system replacement in Continental and Michelin production facilities across North Rhine-Westphalia. ECHA REACH compliance documentation requirements extend certification timelines for foreign press exporters. The Stuttgart and Hanover industrial corridors concentrate ammonia-based heat pump adoption ahead of 2030 refrigerant bans.
United States
EPA thermal emissions guidelines and OSHA worker-safety specifications shape retrofit economics in legacy tire plants across Ohio and South Carolina. The Southeast manufacturing belt sees selective electromechanical upgrades where foundation rework costs permit. Detroit-area automotive OEMs with captive tire operations specify carbon-neutral press alignments.
Vietnam
Radial tire greenfield investments in Binh Duong and Dong Nai provinces prioritize automated mold-handling systems for labor-cost containment. BIS machinery safety codes from neighboring India create compliance reference points for import specifications. Ho Chi Minh City logistics hubs facilitate rapid bladder and thermal subsystem sourcing.
India
Maharashtra and Tamil Nadu tire corridors expand capacity under BIS machinery safety code tightening that excludes non-certified press imports. CEA electrical safety standards intersect with state-level industrial incentives in Gujarat. Pune and Chennai manufacturing zones concentrate electromechanical procurement for export-oriented radial production.
Global Tire Curing Press Machine Market Competitive Environment
Concentration sits with integrated mechatronics specialists and regional fabricators serving distinct buyer tiers. Japanese and German engineering houses anchor premium specifications for high-throughput radial lines, while Chinese equipment builders capture volume procurement through proximity to domestic tire OEM clusters. Strategic differentiation runs through captive control technology and mold-handling automation capabilities. Competitive moves emphasize backward integration into servo-hydraulic subsystems and geographic expansion through localized assembly partnerships.
Within the integrated systems tier, Mitsubishi Heavy Industries Machinery Systems Ltd. exemplifies mechatronics platform dominance, while Greatoo Intelligent Equipment Inc. and Himile Mechanical Science and Technology Co. Ltd. represent Chinese fabricators leveraging regional supply chain density. HERBERT Maschinenbau GmbH and Harburg-Freudenberger Maschinenbau GmbH occupy positions among German precision engineering specialists. McNeil & NRM Inc. sits within the North American service-anchored segment. These archetypes illustrate how technology origin and buyer geography stratify competitive positioning without requiring uniform global scale.
| Leading Market Players |
|---|
| McNeil & NRM Inc. |
| Cima Impianti S.p.A. |
| Mitsubishi Heavy Industries Machinery Systems Ltd. |
| Greatoo Intelligent Equipment Inc. |
| HERBERT Maschinenbau GmbH & Co. KG |
| Himile Mechanical Science and Technology Co. Ltd. |
| Harburg-Freudenberger Maschinenbau GmbH |
| Qingdao Mesnac Co. Ltd. |
| Tianjin Saixiang Technology Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between tire OEMs and electromechanical press suppliers lock in multi-year supply access while anchoring price visibility against steel and servo motor volatility. These arrangements concentrate procurement power among Bridgestone, Michelin, and Continental while compressing margin buffers for tier-2 fabricators serving spot-market buyers in Vietnam and Indonesia.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures with volume-scaled discounts and performance-guarantee clauses. Three-tier pricing separates electromechanical premium specifications from servo-hydraulic standard tiers and legacy mechanical economy options. Cost compression in the economy tier is intensifying because Chinese fabricators compete on proximity to Shandong tire clusters. Retread operators and rubber processors exhibit highest price sensitivity, while Japanese and South Korean OEMs prioritize bladder-precision specifications over unit economics.
Supply Chain Analysis
Strategic stockpiling of high-grade alloy castings and precision servo motors characterizes tier-1 integrator procurement, while tier-2 builders operate on just-in-time component flows. Critical electromechanical subsystems concentrate in Japan, Germany, and South Korea, creating single-source exposure for Chinese and Vietnamese press assemblers. The supply chain draws from specialty steel mills in Japan, precision motion-component houses in Germany, and thermal-system specialists in Italy. Tariff exposure on Chinese steel imports into Southeast Asia constrains cost-competitive positioning. Distribution runs through direct OEM procurement channels and localized assembly partnerships in Binh Duong and Dong Nai provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tire curing press market tracks a cyclical recovery pattern tied to passenger vehicle radialization waves across Southeast Asia. Replacement demand from EU F-Gas thermal system mandates and China's GB energy-efficiency retrofits provides sequential demand support.
For Market Incumbents: Shield margin pools in high-throughput radial lines through captive servo-hydraulic control technology and backward integration into precision mold-handling automation. Consolidate aftermarket service contracts before tire OEMs complete unbundling of bladder replacement and predictive analytics procurement. Electromechanical talent scarcity in Vietnam and Indonesia threatens deployment velocity. For New Entrants and Emerging Players: Anchor in India's Maharashtra and Tamil Nadu tire corridors where BIS machinery safety codes exclude non-certified imports and create compliant-supplier white space. Target specialty tire applications—aviation and electric two-wheeler segments—where automated mold shuttle systems enable economic batch sizes. Pursue automotive OEM direct sourcing relationships as tire manufacturers fragment vendor negotiations. For Investors and Strategic Acquirers: Servo-electric bladder control specialists with miniaturized precision systems represent the most defensible acquisition target archetype given Japanese component concentration and supply risk. Long-term viability hinges on electromechanical technology transfer velocity and regional assembly partnership scalability. Watch for EU carbon-border adjustment mechanism expansion as the inflection signal that accelerates thermal system replacement timelines beyond current regulatory baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Hydraulic Subsystems | Mitsubishi Heavy Industries and Himile Mechanical anchor competitive differentiation through captive control technology. |
| Localized Assembly Partnerships in Vietnam | Binh Duong and Dong Nai greenfield plants prioritize single-floor layouts with integrated mold shuttle robotics. |
| Ammonia-Based Heat Pump Transition | German and Italian tire builders front-load capital allocation ahead of EU F-Gas hydrofluorocarbon refrigerant bans. |
| Digital Twin Architecture Deployment | Predictive maintenance platforms compress unplanned downtime in high-throughput radial tire production lines. |
| Unbundled Aftermarket Service Contracts | Thai and Vietnamese operators source bladder replacements and analytics subscriptions separately from capital equipment. |
Study Parameters
Operator-level perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and thermal systems specialists anchored the qualitative base for this analysis. Primary interview findings triangulated against customs and trade data, MIIT machinery certification records, SEC filings from listed tire OEMs, and ECHA REACH compliance documentation. Bottom-up press deployment tracking across Shandong, Binh Duong, and North Rhine-Westphalia clusters converged with top-down tire production capacity models.
Sensitivity analysis tested forecast outputs against electromechanical adoption velocity, steel price volatility bands, and regulatory compliance timeline acceleration. Segmentation dimensions spanned technology platform, end-user archetype, application type, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and greenfield capacity announcements across the analysis window. Industry-specific inputs included bladder-precision specifications for run-flat architectures and thermal-loop efficiency benchmarks under EU F-Gas constraints.
Material uncertainties — abrupt refrigerant regulation phase-outs, alloy supply disruptions, or mechatronics talent pipeline collapses — sit outside the modeled envelope. Forecasts reflect documented assumptions on technology transfer rates and buyer consolidation trajectories. Revision becomes warranted when carbon-border adjustment mechanism coverage crosses thresholds that restructure total cost of ownership calculations for cross-border press procurement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Bicycle Rim Market