
 Tubeless Tire Market | 2026-2036
Tubeless Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Tubeless Tire Market Outlook
Skilled compound engineering talent is collapsing across mature manufacturing regions, tightening R&D pipelines for next-generation tread formulations. Continental AG leverages its in-house polymer research to sustain proprietary silica-silane bonding technologies. Bridgestone Corporation anchors high-volume production across Asian assembly corridors. Michelin Group differentiates through premium segment positioning in European OEM supply chains.
A tubeless tire seals air pressure through an integrated inner liner of halobutyl rubber rather than relying on a separate inner tube, with bead-seat construction creating an airtight seal against the wheel rim at inflation pressures typically ranging from 30 to 100 psi depending on vehicle class. Its primary commercial purpose is to reduce unsprung mass, eliminate puncture-related blowouts, and enable lower rolling resistance for fuel efficiency targets. Passenger car applications dominate volume absorption while heavy-duty truck specifications command concentrated margin pools due to retread compatibility demands and fleet lifecycle economics. Composite material layering represents the fastest-growing structural category as manufacturers substitute synthetic aramid fibers for traditional steel belting to achieve weight reduction without sacrificing load ratings.
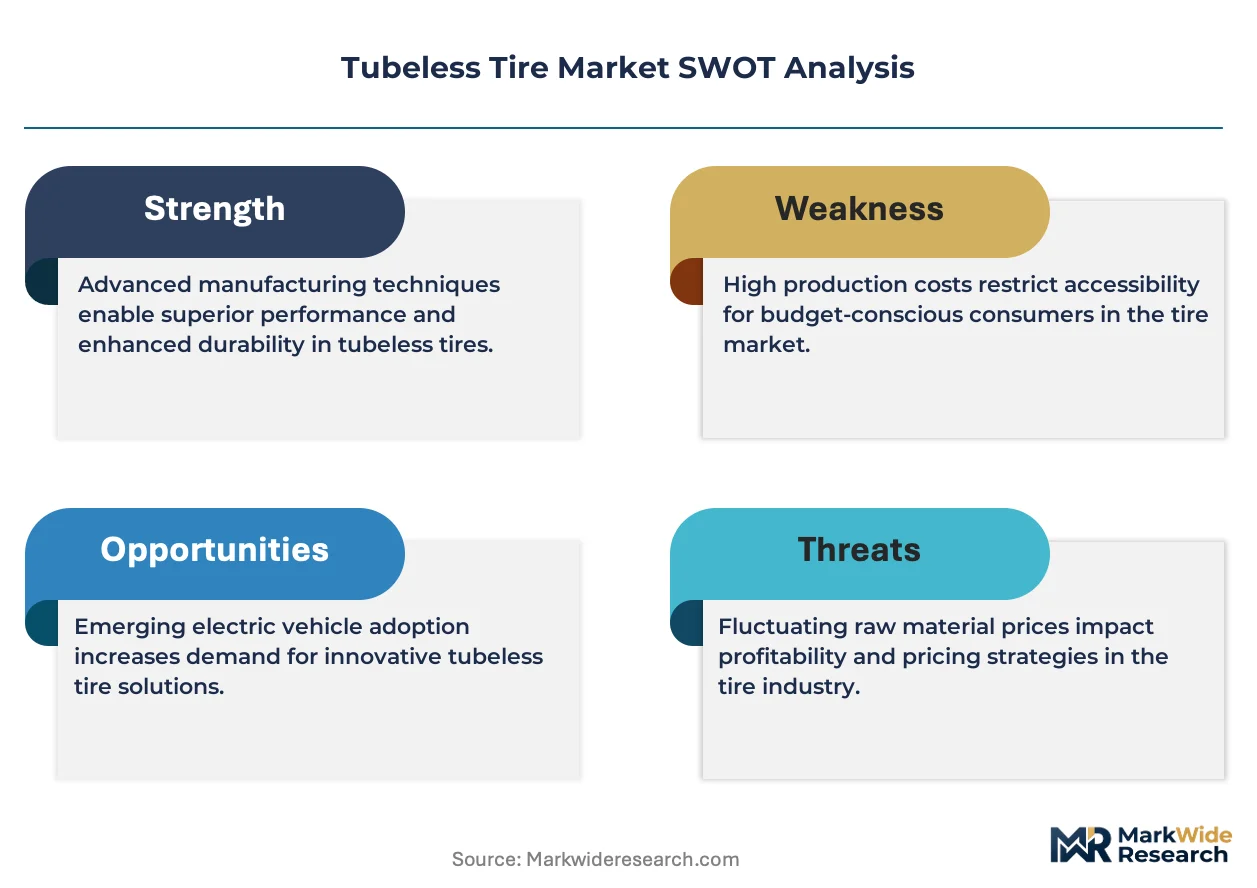
The US NHTSA maintains Federal Motor Vehicle Safety Standard No. 109 governing tire performance grading, while the EU's REACH framework restricts aromatic oils in tire compounds and the ECHA evaluates microplastic shedding from tread wear. These overlapping compliance obligations force manufacturers to maintain parallel certification laboratories and region-specific compound libraries. Stakeholders must monitor how California's pending tire wear microplastics regulation and the EU's evolving End-of-Life Vehicle Directive reshape material recovery obligations and extended producer liability frameworks.
Market Dynamics
Automakers are eliminating spare tire wells from vehicle platforms to cut unsprung mass and meet fleet efficiency mandates, forcing direct integration of run-flat and self-sealing tubeless architectures into OEM supply programs.
Growth Catalysts
- EV Platform Weight Budgets:Electric vehicle manufacturers prioritize every kilogram of mass reduction to extend range, accelerating specification of tubeless configurations that eliminate inner tube weight and enable thinner sidewall designs.
- F-Gas Regulation:Europe's phasedown of hydrofluorocarbon propellants in tire inflation systems is compelling manufacturers to redesign bead-seal interfaces for compatibility with nitrogen and compressed air systems.
- Aramid Fiber Substitution:Synthetic fiber belting is replacing traditional steel cord in premium passenger segments, enabling 15-20% weight reduction without load rating compromise.
Market Restraints
- Halobutyl Rubber Concentration:Three Southeast Asian petrochemical complexes supply over 70% of global halobutyl feedstock for inner liner compounds, creating single-source vulnerability.
- REACH Compliance Costs:The EU's restriction on polycyclic aromatic hydrocarbons in tire oils forces parallel compound libraries, adding 12-18 months to product development cycles.
- Retread Infrastructure Lock-in:Heavy-duty fleet operators maintain substantial capital in conventional casing management systems, slowing conversion to tubeless-compatible wheel and rim standards.
Strategic Opportunities
- India Two-Wheeler Conversion:The country's Bureau of Indian Standards is mandating tubeless fitment on motorcycles above 125cc displacement, opening 25 million annual unit demand.
- Tire-as-a-Service Models:Fleet management platforms are unbundling tire procurement from lifecycle maintenance, creating recurring revenue streams for pressure-monitoring-integrated tubeless systems.
- Carbon Border Adjustment:The EU's CBAM mechanism will penalize imported tires with high embodied carbon, rewarding European manufacturers with localized low-carbon rubber sourcing.
Industry Challenges
- Compound Engineering Talent Scarcity:Polymer chemistry expertise is concentrating at a handful of research universities, constraining R&D pipeline velocity for next-generation silica-silane bonding systems.
- Homologation Timeline Compression:OEMs are compressing tire development cycles from 36 to 24 months while adding durability testing for electric vehicle torque profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubeless Tire Market |
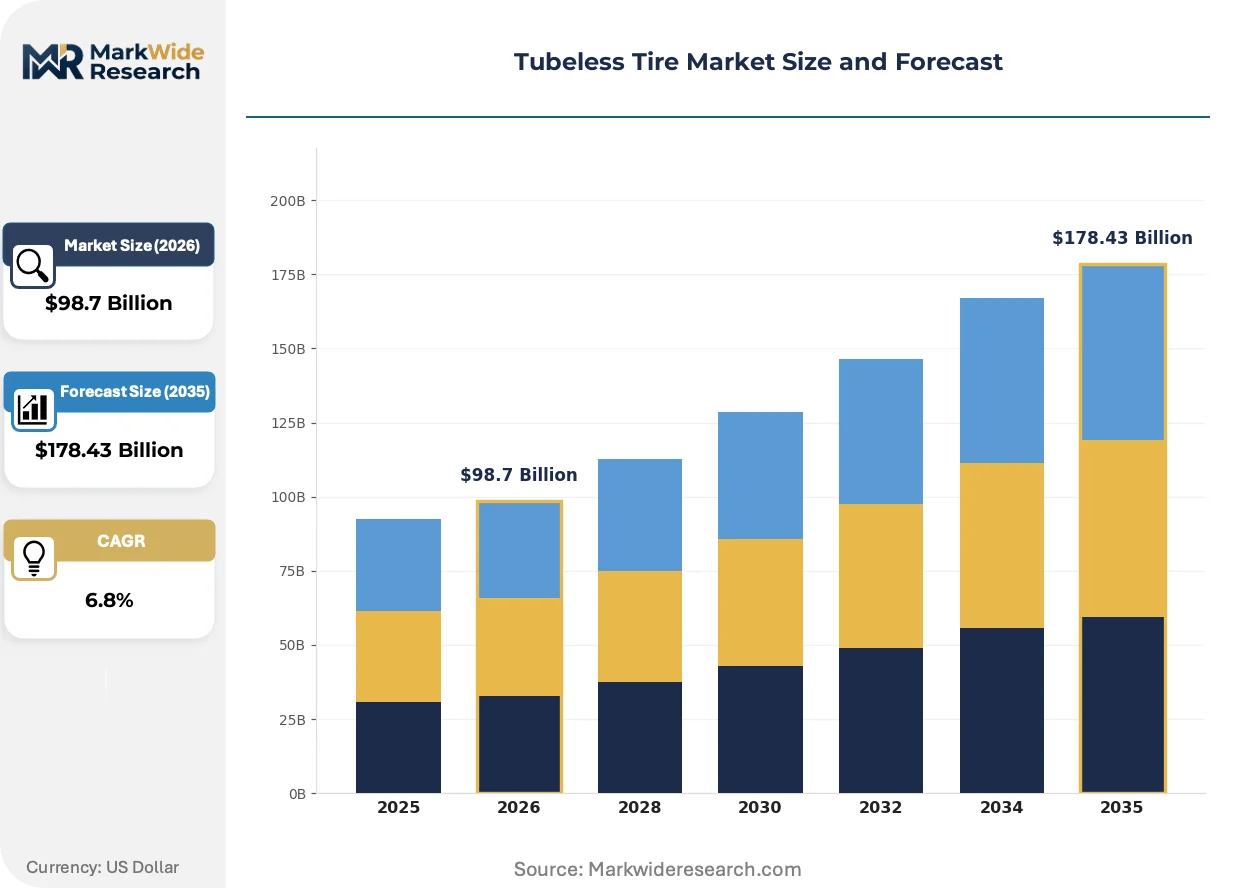
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Material: Rubber, Fabric, Steel, Composite End User: OEMs, Aftermarket Providers, Tire Retailers, Fleet Operators Distribution Channel: Online, Retail, Wholesale, Direct |
| Companies Covered | Continental AG, Sumitomo Rubber Industries Ltd., Bridgestone Corporation, Yokohama Rubber Company Ltd., Hankook Tire & Technology Co., Michelin Group, Pirelli & C. S.p.A., Giti Tire Pte. Ltd., Goodyear Tire & Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubeless Tire Market Strategic Shifts
Material science breakthroughs and regulatory chemistry restrictions are converging to rewrite tire construction specifications, with sustainability metrics now embedded in procurement scorecards alongside performance grading.
Self-sealing gel injection systems are supplanting conventional puncture repair kits in passenger vehicle aftermarkets. Fleet operators and ride-hailing platforms specify these configurations to minimize roadside service calls. The technology is compressing warranty claim rates and enabling tire manufacturers to capture service revenue previously lost to independent repair chains.
REACH microplastic shedding evaluations are forcing reformulation of tread compounds across European supply chains. The ECHA's 2025 methodology for quantifying tire wear particle emissions will become binding for type approval. Premium OEM suppliers are responding with proprietary low-wear polymer blends that sacrifice 3-5% rolling resistance for 40% particle reduction.
Fleet procurement departments are consolidating tire specifications across mixed vehicle pools to simplify inventory management. This pattern is displacing brand-agnostic purchasing with single-source framework agreements tied to telematics integration. The shift is most visible in German and French commercial logistics corridors, where digital tire pressure monitoring has become a contract prerequisite.
Tubeless Tire Market Segmentation
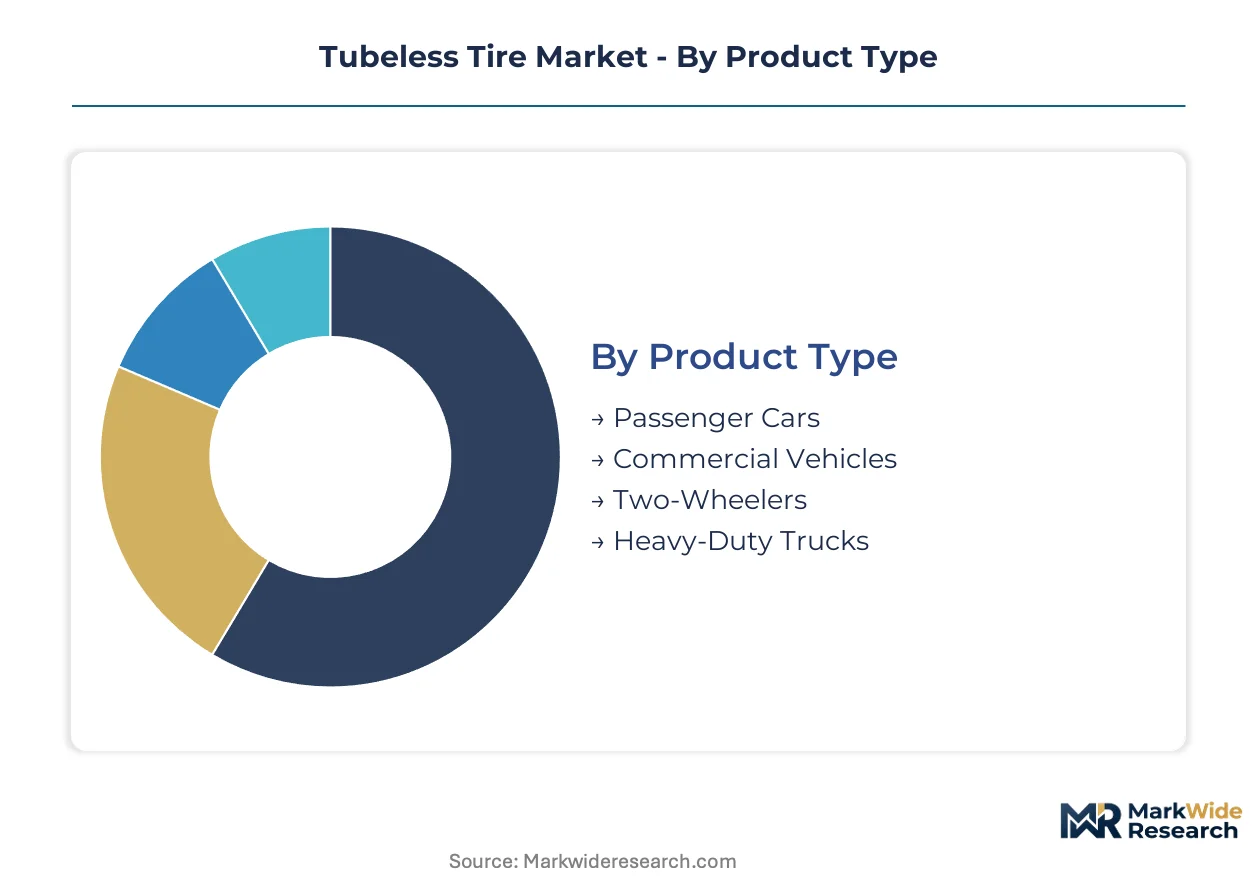
Tubeless tire procurement patterns diverge sharply across vehicle platforms and supply chain tiers, with specification requirements tightening around EV torque profiles and fleet telematics integration. Margin capture concentrates where compound engineering capabilities align with regulatory chemistry restrictions.
Product Type:
Margin pools concentrate in heavy-duty specifications where retread cycles and fleet lifecycle economics sustain premium pricing, while passenger car volumes anchor manufacturing scale.
- Passenger Cars:Specifications prioritize low rolling resistance compounds and thinner sidewall constructions to accommodate EV range targets. China's domestic EV manufacturers are driving the steepest specification evolution, demanding tires rated for instant torque delivery and regenerative braking heat cycles.
- Commercial Vehicles:Fleet procurement departments in Germany and France now mandate integrated pressure monitoring as a contract prerequisite, compressing supplier qualification timelines. Retread compatibility requirements lock in casing durability standards that filter available suppliers to established tier-one manufacturers.
- Two-Wheelers:India's BIS mandate for tubeless fitment on motorcycles above 125cc displacement is restructuring Southeast Asian supply chains toward this segment.
- Heavy-Duty Trucks:Load rating requirements and rim standard conversion costs slow adoption despite lifecycle fuel savings.
The dominant share belongs to Passenger Cars, while Two-Wheelers is closing the gap fastest.
Material:
Raw material selection determines compliance trajectory under REACH aromatic oil restrictions and ECHA microplastic shedding evaluations.
- Rubber:Halobutyl formulations for inner liner airtightness face feedstock concentration risk from three Southeast Asian petrochemical complexes. Compound engineers are reformulating silica-silane bonding systems to maintain seal integrity while reducing environmental impact.
- Composite:Aramid fiber substitution for steel belting enables 15-20% weight reduction without load rating compromise. European OEM supply chains are specifying composite-intensive constructions to meet fleet efficiency mandates.
- Fabric:Polyester and nylon carcass plies serve cost-sensitive segments with adequate durability for standard load cycles.
- Steel:Traditional cord belting retains share in heavy-duty applications where puncture resistance and retread structural integrity outweigh weight penalties.
Steel retains the largest installed base, though Composite is expanding most quickly as premium OEM specifications accelerate.
End User:
Procurement authority is consolidating toward fleet operators and OEMs as tire-as-a-service models displace transactional retail purchasing.
- OEMs:Automakers are compressing development cycles from 36 to 24 months while eliminating spare tire wells from vehicle platforms. Direct integration of run-flat and self-sealing architectures into supply programs locks in multi-year framework agreements.
- Fleet Operators:Digital tire pressure monitoring has become mandatory in German and French commercial logistics corridors. Telematics-integrated tubeless systems enable unbundled procurement from lifecycle maintenance, creating recurring revenue streams.
- Aftermarket Providers:Self-sealing gel injection systems are supplanting conventional puncture repair kits, capturing service revenue previously lost to independent repair chains.
- Tire Retailers:Inventory consolidation toward mixed-vehicle fleet specifications is displacing brand-agnostic purchasing with single-source agreements.
OEMs command the steepest pricing power, yet Fleet Operators are gaining procurement leverage fastest through telematics integration requirements.
Distribution Channel:
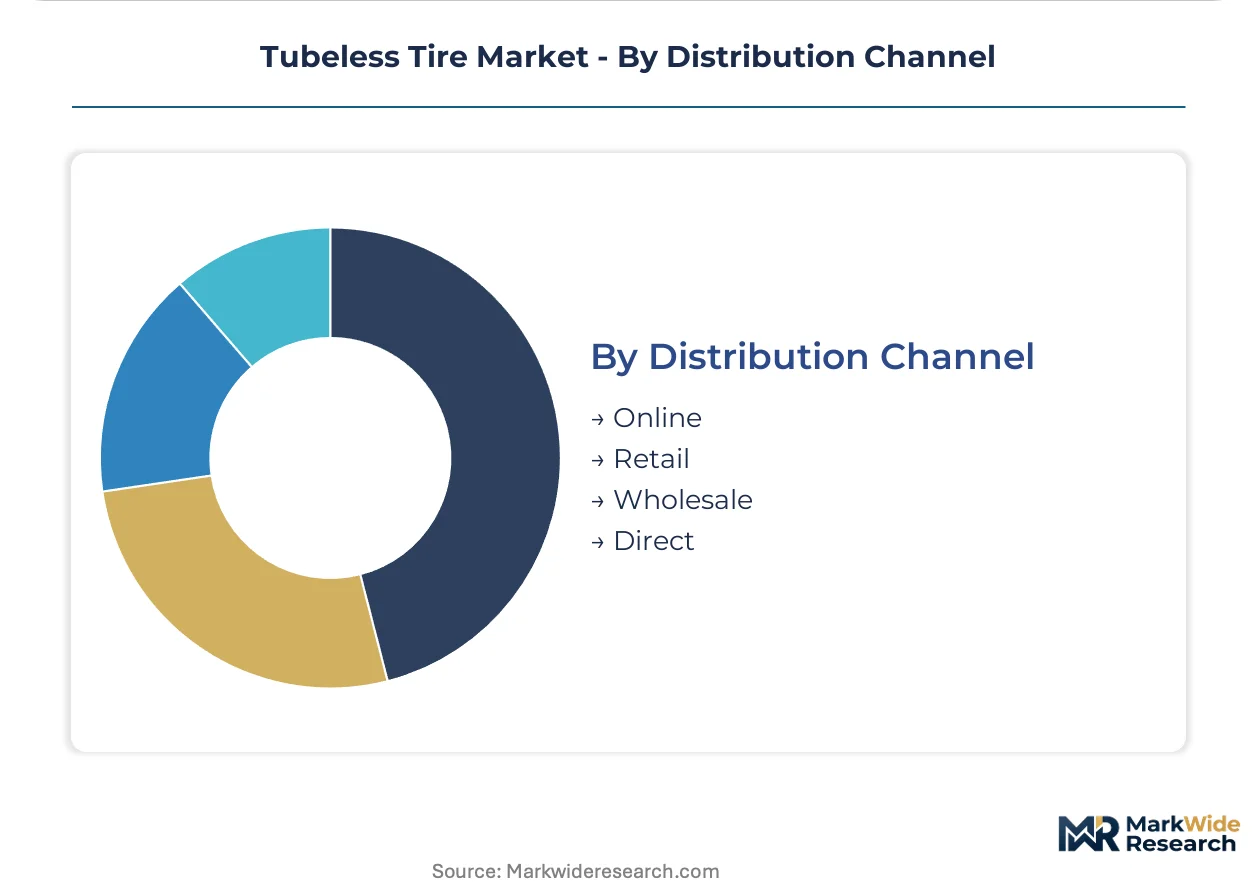
Channel economics shift as digital procurement platforms penetrate fleet segments and direct manufacturer relationships deepen.
- Direct:OEM supply programs and large fleet framework agreements bypass intermediary margins, capturing volume concentration benefits. Continental AG and Michelin Group anchor direct channels through European OEM supply chain integration.
- Wholesale:Distributors serving independent repair chains face compression as self-sealing technologies reduce roadside service call frequency.
- Retail:Physical storefronts retain relevance for consumer replacement cycles and warranty claim processing.
- Online:Digital platforms gain traction in aftermarket consumer segments with standardized fitment specifications.
Direct channels absorb the highest value concentration, while Online is climbing the fastest as fitment databases improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and the F-Gas Regulation anchor European regulatory gravity, while China's MIIT standards and India's BIS mandates reshape procurement specifications across distinct manufacturing corridors. Regional compliance obligations fragment supply chains into parallel certification tracks.
China
Domestic EV manufacturers specify tubeless tires rated for instant torque delivery and regenerative braking heat cycles. MIIT's GB standards enforce pressure monitoring integration on new energy vehicles. The Yangtze River Delta clusters tire R&D facilities alongside battery gigafactories, compressing OEM development cycles.
Germany
Commercial fleet operators mandate digital tire pressure monitoring as a contract prerequisite. KBA enforces UN ECE R64 run-flat homologation standards. The Stuttgart-Munich corridor concentrates premium OEM supply chain integration, locking in multi-year framework agreements with compound engineering specialists.
United States
Automakers eliminate spare tire wells to cut unsprung mass and meet NHTSA CAFE fleet efficiency mandates. California's pending tire wear microplastics regulation pressures reformulation timelines. Detroit's engineering centers compress tire development cycles from 36 to 24 months while adding EV durability testing.
India
BIS mandates tubeless fitment on motorcycles above 125cc displacement, opening 25 million annual unit demand. The PLI scheme incentivizes domestic rubber compounding capacity. Tamil Nadu and Gujarat host expanding tire manufacturing clusters serving Southeast Asian export corridors.
Japan
Automotive OEMs specify aramid fiber belting for weight reduction without load rating compromise. METI's dual carbon goals pressure low-emission compound reformulation. The Nagoya-Osaka industrial belt maintains precision manufacturing capabilities for premium passenger vehicle specifications.
Tubeless Tire Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. The market consolidates around integrated polymer research capabilities and high-volume Asian production corridors. Premium compound engineering specialists compete against scale-driven manufacturers on divergent vectors. Strategic moves concentrate on silica-silane bonding patents and nitrogen-compatible bead-seal redesigns.
Within the integrated research tier, Continental AG and Michelin Group exemplify proprietary compound development capabilities. Bridgestone Corporation anchors high-volume production positioning across Asian assembly corridors. These three entities occupy distinct competitive spaces—Continental AG and Michelin Group through European OEM supply chain integration, Bridgestone Corporation through manufacturing scale—without direct overlap in strategic emphasis.
| Leading Market Players |
|---|
| Continental AG |
| Sumitomo Rubber Industries Ltd. |
| Bridgestone Corporation |
| Yokohama Rubber Company Ltd. |
| Hankook Tire & Technology Co. |
| Michelin Group |
| Pirelli & C. S.p.A. |
| Giti Tire Pte. Ltd. |
| Goodyear Tire & Rubber Company |
| Others |
Value Chain & Pricing Dynamics
REACH aromatic oil restrictions gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to maintain parallel compound libraries that segment pricing across regulatory jurisdictions while embedding compliance costs into premium tier structures.
Pricing Analysis
European tubeless tires command 15-25% premiums over Southeast Asian equivalents due to REACH-certified compound reformulation costs. Pricing stratifies across premium OEM supply tiers, standard fleet specifications, and economy aftermarket replacements, with differentiation anchored in silica-silane bonding certification levels and pressure-monitoring integration. Cost compression in the standard tier is intensifying because Chinese EV manufacturers are compressing development cycles and squeezing supplier margins. Fleet operators exhibit the lowest price sensitivity due to lifecycle cost accounting, while independent aftermarket retailers face the highest margin pressure.
Supply Chain Analysis
Just-in-time halobutyl rubber delivery dominates premium European manufacturing, while strategic stockpiling of aramid fiber feedstock prevails among Asian producers managing petrochemical price volatility. Supply concentrates in Thailand, Singapore, and Belgium for halobutyl inner liner compounds, with aramid fiber drawing from Japan and the United States. Raw material dependencies center on synthetic rubber polymers, silica-silane bonding agents, and synthetic fiber belting. Single-source vulnerability from three Southeast Asian petrochemical complexes threatens feedstock security. Distribution runs through direct OEM supply programs for premium tiers, wholesale distributors for fleet procurement, and retail networks for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tubeless tire demand tracks automotive production cycles, with OEM procurement acceleration signaling recovery momentum as spare tire elimination and EV platform weight budgets drive specification upgrades.
For Market Incumbents: Fortify proprietary silica-silane bonding patent portfolios against emerging composite material specialists threatening premium positioning. Deepen backward integration into halobutyl rubber compounding to offset Southeast Asian feedstock concentration risk. Secure multi-year framework agreements with European OEMs before REACH microplastic regulations tighten qualification timelines.
For New Entrants and Emerging Players: UN ECE R64 run-flat certification fast-tracks entry into German and French fleet procurement corridors where digital pressure monitoring is now mandatory. Target India's two-wheeler conversion wave as the most penetrable volume segment, with BIS mandates opening 25 million annual units. Pursue tire-as-a-service partnerships with ride-hailing platforms seeking unbundled lifecycle maintenance contracts.
For Investors and Strategic Acquirers: California's pending tire wear microplastics regulation reshapes the acquisition landscape toward compound engineering specialists with low-wear polymer blend capabilities. Five-to-ten-year viability favors targets with captive silica-silane R&D and European OEM supply chain integration. Watch ECHA's 2025 tire wear particle methodology adoption as the inflection signal for premium reformulation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Silica-Silane Bonding Patent Expansion | Continental AG and Michelin Group defend premium positioning through proprietary compound chemistry IP. |
| Aramid Fiber Backward Integration | Japanese manufacturers secure synthetic fiber supply chains against steel cord price volatility. |
| Nitrogen-Compatible Bead-Seal Redesign | F-Gas Regulation compliance enables European market access without hydrofluorocarbon inflation systems. |
| Telematics-Integrated Pressure Monitoring | German fleet operators mandate digital systems as contract prerequisites, locking in supplier relationships. |
| India Two-Wheeler Manufacturing Footprint | Tamil Nadu and Gujarat clusters capture BIS-mandated tubeless conversion demand across Southeast Asia. |
Study Parameters
Cross-validation between primary interviews with tire compound engineers, OEM procurement directors, and fleet maintenance managers anchors the qualitative findings against secondary validation from NHTSA FMVSS filings, ECHA REACH submissions, MIIT GB standard disclosures, and customs trade data. Bottom-up triangulation across vehicle production databases and top-down reconciliation against petrochemical feedstock flows ensure segmentation integrity.
Sensitivity analysis around EV platform weight budgets and REACH compliance cost trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions span vehicle class, material composition, end-user procurement authority, and distribution channel structure. CAGRs derive from production volume modeling against replacement cycle dynamics, with electric vehicle torque profile durability testing and regenerative braking heat cycle specifications as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EV production acceleration or halobutyl feedstock supply stability would require recalibration. Forecasts reflect assumptions around regulatory enforcement timelines and OEM development cycle compression. Revision becomes warranted when ECHA microplastic methodology adoption or California tire wear regulations cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
All-Terrain Vehicle Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Tire Bead Wire Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Airless Tires Market