
 Rolling Stock LED Lights Market | 2026-2036
Rolling Stock LED Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Rolling Stock LED Lights Market Analytics
A shortage of rail-certified electrical engineers is redrawing competitive boundaries across the rolling stock LED lights sector. Toshiba leverages its semiconductor heritage to dominate high-reliability power management modules for train lighting systems. Osram sustains technology leadership through its deep specialization in automotive-grade LED platforms adapted for rail vibration tolerance. Koito competes aggressively in the Asian supplier tier by anchoring production scale around standardized interior cabin luminaires.
Rolling stock LED lights comprise solid-state illumination assemblies engineered to withstand rail-specific shock loads, electromagnetic interference, and temperature cycling between minus forty and plus seventy degrees Celsius, serving the primary purpose of passenger safety visibility and energy reduction in rail vehicle operations. Interior lights and smart lighting together command the dominant margin pools as transit authorities prioritize human-centric circadian illumination and remote diagnostics capability, while exterior lights remain the most mature segment with replacement-driven demand cycles. RGB LED technology is displacing monochrome cabin lighting fastest among technology tiers as operators seek configurable ambiance and wayfinding differentiation.
The EU Green Deal and REACH chemical compliance frameworks tighten material sourcing requirements for LED phosphors and thermal substrates in European rail supply chains, while the F-Gas Regulation accelerates refrigerant-linked HVAC-lighting integration mandates. The US Federal Railroad Administration enforces crashworthiness standards that directly shape LED housing design and mounting protocols for North American passenger cars. Stakeholders must monitor how emerging battery-electric multiple-unit platforms reshape voltage architectures and thus LED driver specifications across procurement pipelines.
Market Dynamics
Rail operators face a structural pivot as EU Green Deal mandates force wholesale LED retrofits across aging European fleets, while semiconductor supply bottlenecks constrain driver module availability and reshape vendor qualification timelines.
Growth Catalysts
- EU Green Deal fleet mandates:Binding energy-efficiency targets for rolling stock components accelerate LED conversion programs across German, French, and Italian rail networks.
- RGB LED cabin systems:Transit authorities deploy configurable ambiance lighting for passenger experience differentiation and dynamic wayfinding in urban metro systems.
- Battery-electric multiple-unit platforms:New voltage architectures in emerging train designs create specification windows for next-generation LED drivers with wider input ranges.
Market Restraints
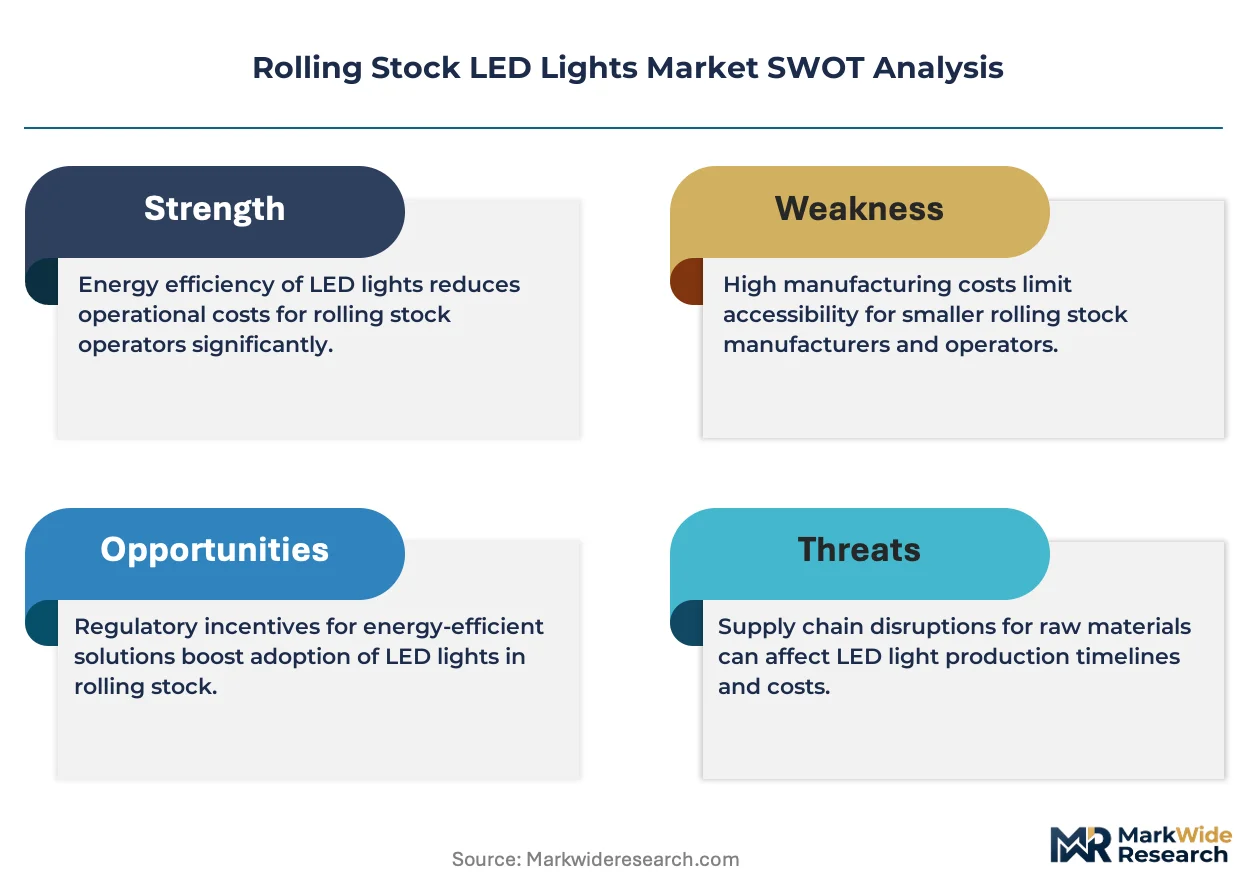
- Rail-certified engineer scarcity:Specialized electrical engineering talent concentrates in Germany and Japan, limiting supplier expansion into secondary markets.
- Phosphor material sourcing constraints:REACH compliance tightens supply chains for rare-earth phosphors used in high-CRI LED formulations.
- Legacy fluorescent fixture installed base:Decades-long service intervals in existing rolling stock delay replacement cycles despite efficiency advantages.
Strategic Opportunities
- Smart lighting diagnostics integration:Remote monitoring capabilities open recurring revenue streams through predictive maintenance contracts with fleet operators.
- Indian rail electrification:Indian Railways' massive fleet expansion creates demand for cost-optimized LED systems meeting tropical temperature cycling requirements.
- HVAC-lighting convergence:F-Gas Regulation compliance drives integrated environmental control procurement, favoring suppliers with dual-system expertise.
Industry Challenges
- EN 50155 certification timelines:Extended validation periods for railway electronic equipment delay product launches and compress development windows.
- Legacy 74-volt system integration:Mixed-voltage fleets require dual-specification LED drivers, complicating inventory management and technical support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rolling Stock LED Lights Market |
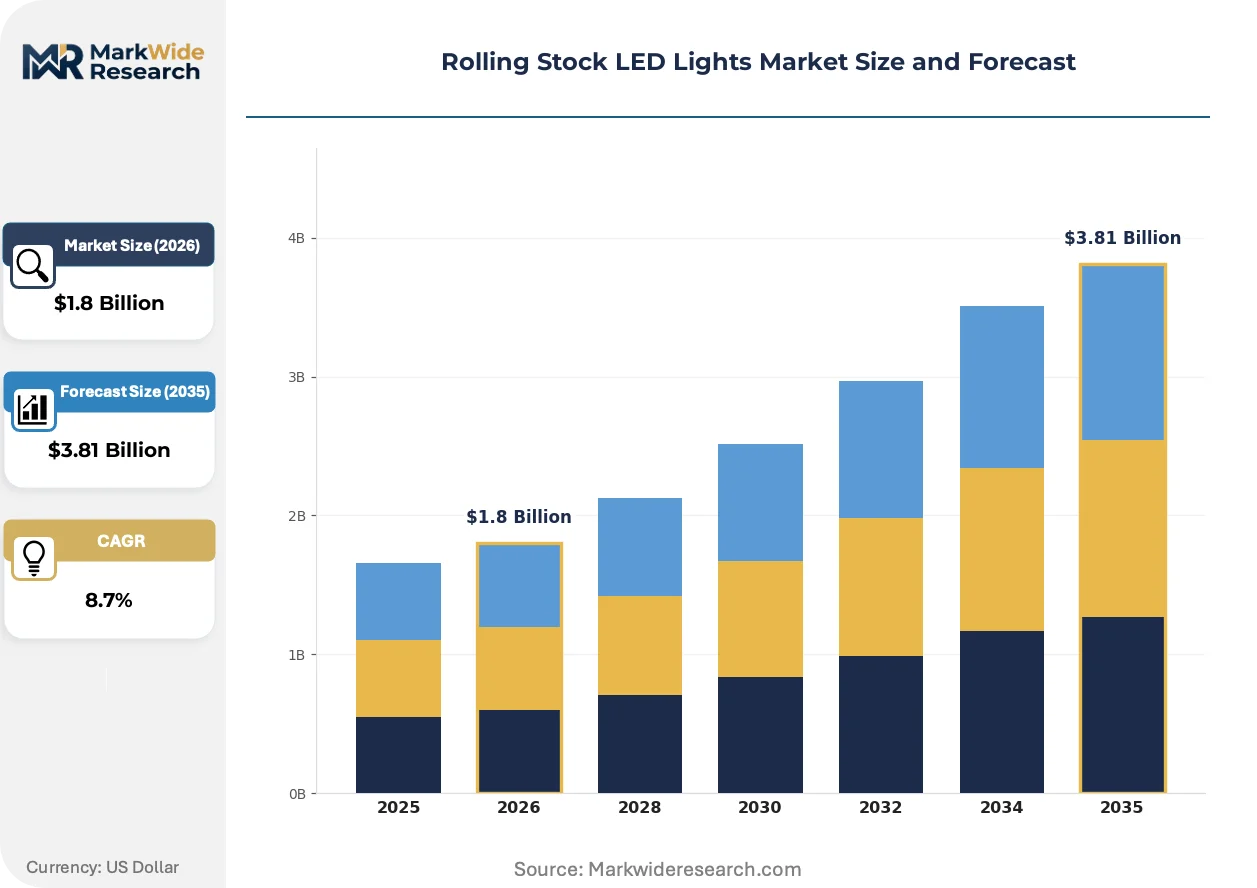
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Lights, Exterior Lights, Signal Lights, Brake Lights Application: Railway Vehicles, Trams, Light Rail, Coaches End User: Public Transport Authorities, Private Operators, Maintenance Service Providers, Manufacturers Technology: Smart Lighting, Solar-Powered, Dimmable LED, RGB LED |
| Companies Covered | Toshiba, General Electric, Hitachi, Koito, Osram, Grupo Antolin, Dräxlmaier, Teknoware, Autolite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rolling Stock LED Lights Market Evolving Landscape
Active developments across three vectors are compressing product lifecycles and rewiring supplier-buyer relationships in rail lighting procurement.
Silicon-carbide power semiconductors are displacing silicon-based LED drivers in premium rolling stock applications. Japanese Shinkansen operators and German ICE fleet managers specify SiC modules for superior thermal performance in compact housings. This transition is displacing incumbent driver architectures and forcing incumbent suppliers to retool manufacturing lines.
REACH chemical compliance frameworks now govern phosphor composition and thermal substrate selection across European supply chains. ECHA substance restrictions cascade through component specifications, compelling Asian LED packagers to reformulate products for EU market access. Interior cabin luminaires face the steepest reformulation costs due to human proximity exposure thresholds.
Performance-based maintenance contracts are fragmenting traditional equipment-only procurement. French and British transit authorities now unbundle lighting hardware from lifecycle service, favoring vendors with diagnostic platform capabilities. This model compresses upfront equipment margins while extending revenue capture through multi-year uptime guarantees.
Rolling Stock LED Lights Market Segmentation
Segmentation in rolling stock LED lights reveals how regulatory pressure and operational requirements fragment procurement patterns across rail networks. Voltage architectures, certification tiers, and passenger experience mandates create distinct specification clusters that reshape supplier positioning and margin capture.
Product Type:
EU Green Deal energy-efficiency mandates and EN 50155 certification requirements create divergent compliance burdens across illumination categories, with interior systems facing stricter human-exposure thresholds than exterior assemblies.
- Interior Lights:Circadian-tuned LED arrays with CRI exceeding 90 dominate cabin retrofits as German and French transit authorities mandate human-centric lighting for passenger wellbeing. Demand concentrates in urban metro fleets where RGB configurability supports dynamic wayfinding and brand differentiation.
- Exterior Lights:Heavy-duty sealed housings withstand minus forty to plus seventy degree Celsius cycling plus rail-specific shock loads; replacement cycles in North American freight corridors drive steady procurement despite slower technology turnover compared to cabin systems.
- Signal Lights:Fail-safe redundant LED modules meet strict railway signaling interoperability standards across interoperable European corridors.
- Brake Lights:High-intensity emergency illumination assemblies integrate with train control systems for automatic activation protocols.
Established volume favors Interior Lights; emerging adoption favors Exterior Lights.
Application:
Cost tier differentiation separates premium high-speed specifications from standardized urban transit configurations, with voltage architecture and vibration tolerance as primary price determinants.
- Railway Vehicles:Mainline passenger and freight rolling stock requiring full EN 50155 certification for electronic equipment; German ICE and Japanese Shinkansen procurement sets thermal performance benchmarks that cascade through supplier qualification programs.
- Trams:Street-level light rail with reduced voltage ranges and moderated shock specifications; European city networks in Italy and Poland drive volume through fleet standardization initiatives.
- Light Rail:Suburban connector systems balancing passenger capacity with energy constraints; battery-electric multiple-unit platforms create specification windows for wide-input-range LED drivers.
- Coaches:Intercity passenger cars with extended duty cycles; Indian Railways electrification programs generate tropical-grade thermal cycling requirements that reshape component sourcing.
Procurement scale concentrates in Railway Vehicles; technology refresh cycles run fastest in Light Rail.
End User:
Customer type determines contract structure, with public authorities favoring performance-based maintenance agreements while private operators prioritize capital expenditure minimization.
- Public Transport Authorities:State-owned urban transit operators in Germany, France, and Britain unbundle hardware from lifecycle service, mandating diagnostic platform integration for predictive maintenance contracts.
- Private Operators:Commercial rail franchises and open-access operators prioritizing total cost of ownership; procurement emphasizes standardized interior luminaires with compressed lead times.
- Maintenance Service Providers:Third-party fleet management contractors capturing retrofit opportunities in aging European rolling stock.
- Manufacturers:OEM integrators specifying LED systems at new-build stage; REACH compliance requirements cascade through component qualification for EU market access.
Contract value pools deepest with Public Transport Authorities; margin expansion potential sits with Maintenance Service Providers.
Technology:
Supply concentration in semiconductor fabrication and phosphor formulation creates tiered access to advanced capabilities, with SiC power modules and RGB configurability commanding premium positioning.
- Smart Lighting:Networked LED assemblies with remote diagnostics, circadian tuning, and occupancy-responsive dimming; French and British transit authorities mandate these platforms for performance-based maintenance contracts.
- RGB LED:Multi-channel color-mixing systems enabling configurable cabin ambiance and dynamic wayfinding; urban metro operators in Asia-Pacific deploy these for passenger experience differentiation.
- Dimmable LED:Phase-cut and 0-10V control protocols for energy management; legacy fleet retrofits favor this mature technology for compatibility with existing electrical architectures.
- Solar-Powered:Off-grid illumination for remote trackside and yard applications; limited penetration in mainline rolling stock due to reliability requirements.
Technology maturity favors Dimmable LED; steepest expansion trajectory belongs to Smart Lighting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes rolling stock LED lights through high-speed fleet modernization, while India deploys cost-optimized systems for tropical electrification programs, and Japan specifies silicon-carbide power modules for thermal performance in premium applications.
Germany
Deutsche Bahn's ICE fleet retrofit programs and urban metro expansion in Berlin, Munich, and Hamburg drive specification demand for EN 50155-certified interior systems. The EU Green Deal mandates binding energy-efficiency targets that accelerate LED conversion timelines across federal rail networks. Siemens Mobility and Knorr-Bremse anchor supplier relationships through Bavaria and Baden-Württemberg manufacturing clusters.
France
Paris Metro and RATP procurement unbundle lighting hardware from lifecycle service contracts, mandating diagnostic platform integration. The F-Gas Regulation accelerates HVAC-lighting convergence requirements for integrated environmental control systems. Alstom and industrial suppliers cluster around Île-de-France and Auvergne-Rhône-Alpes for high-speed and urban rail platforms.
India
Indian Railways' massive fleet electrification and Dedicated Freight Corridor expansion generate demand for wide-temperature-range LED drivers. The PLI scheme and domestic content requirements reshape component sourcing toward local assembly. Manufacturing concentrates in Maharashtra and Gujarat, where rail component suppliers adapt systems for tropical thermal cycling.
Japan
East Japan Railway and Central Japan Railway specify silicon-carbide power semiconductors for Shinkansen lighting systems requiring compact thermal performance. METI efficiency standards and JIS certification frameworks govern supplier qualification. Industrial activity clusters in Kanto around Tokyo and Kansai around Osaka for precision rail electronics.
United Kingdom
Network Rail and Transport for London prioritize performance-based maintenance contracts with predictive diagnostics for aging fleet retrofits. The CSRD and sustainability disclosure requirements cascade through supplier ESG qualification. Rolling stock engineering concentrates in the Midlands and North England, where refurbishment specialists capture upgrade cycles.
Rolling Stock LED Lights Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in rolling stock LED lights, with semiconductor heritage and automotive-grade platforms conferring advantage in certification-heavy procurement. The structure rewards EN 50155 validation capabilities and REACH-compliant supply chains over pure manufacturing scale. Three archetypes dominate: diversified electronics conglomerates with rail-certified power management, automotive lighting specialists adapting vibration-tolerant platforms, and focused rail component suppliers with deep fleet relationships. Competitive moves concentrate on silicon-carbide driver transitions and predictive maintenance service bundling.
Within the diversified electronics tier, Toshiba and Hitachi exemplify integrated players leveraging semiconductor and systems heritage for high-reliability specifications. Koito and Osram occupy positions bridging automotive and rail applications, with Koito representing Asian production-scale strategies and Osram anchoring European phosphor and thermal substrate expertise. General Electric sits within the industrial conglomerate archetype, drawing on broad transportation electrification portfolios.
| Leading Market Players |
|---|
| Toshiba |
| General Electric |
| Hitachi |
| Koito |
| Osram |
| Grupo Antolin |
| Dräxlmaier |
| Teknoware |
| Autolite |
| Others |
Value Network & Pricing Analysis
EN 50155 certification gates both supplier qualification and price differentiation in rolling stock LED procurement, compressing margins for uncertified Asian packagers while rewarding validated European vendors with premium positioning on German and French rail networks.
Pricing Analysis
Long-term performance-based contracts dominate procurement for public transport authorities, unbundling hardware from lifecycle service obligations. Price differentiation separates EN 50155-certified systems from uncertified alternatives, with silicon-carbide driver modules commanding further premiums for thermal performance. Pricing pressure stems from Indian Railways' cost-optimized tenders for tropical-grade systems. Private operators exhibit highest price sensitivity, while high-speed rail procurement shows lowest.
Supply Chain Analysis
Extended lead times for rail-certified LED drivers strain fleet retrofit schedules, particularly for semiconductor-dependent power management modules. Supply concentrates in Germany, Japan, and China, with phosphor substrates drawing from rare-earth processing in China and thermal substrate fabrication in Japan. Single-source vulnerability runs through silicon-carbide wafer supply. Distribution runs through OEM integrators and authorized rail component distributors with EN 50155 validation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based maintenance contracts are transforming rolling stock LED procurement into a platform-economics inflection, where diagnostic interoperability determines vendor lock-in and recurring revenue capture across French and British transit authorities.
For Market Incumbents: Shield certification moats by accelerating EN 50155 validation for silicon-carbide driver architectures before Asian competitors achieve qualification. Deepen backward integration into phosphor formulation to secure REACH-compliant supply chains against ECHA substance restrictions. Prioritize predictive maintenance platform development to defend service revenue streams from industrial software entrants.
For New Entrants and Emerging Players: Lead with cost-optimized LED systems for Indian Railways' electrification programs, where tropical thermal cycling requirements and domestic content mandates favor local assembly partnerships. Target maintenance service providers in aging European fleets as the most penetrable buyer segment, offering retrofit-compatible interior luminaires with compressed qualification timelines. Position through authorized distributor networks rather than direct OEM integration.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized rail lighting divisions lacking diagnostic platform capabilities. Long-term viability favors suppliers with dual HVAC-lighting integration expertise as F-Gas Regulation compliance intensifies. Watch for silicon-carbide driver adoption inflection in Japanese Shinkansen procurement as signal of technology transition acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Driver Transition | Shinkansen and ICE specifications are displacing silicon-based architectures and forcing manufacturing retooling. |
| Predictive Maintenance Platform Launch | French RATP unbundling creates recurring revenue streams through multi-year uptime guarantee contracts. |
| REACH-Compliant Phosphor Reformulation | ECHA substance restrictions compel Asian LED packagers to reformulate for EU market access. |
| HVAC-Lighting Integration Partnership | F-Gas Regulation mandates favor suppliers with dual environmental control system expertise. |
| Indian Local Assembly Scale-Up | PLI scheme and tropical thermal requirements reshape component sourcing toward Maharashtra and Gujarat. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with rail procurement managers at Deutsche Bahn and RATP, fleet engineering directors at East Japan Railway, LED driver specialists at semiconductor suppliers, and maintenance contractors in British rolling stock refurbishment. Secondary validation drew from EN 50155 certification databases, EU Green Deal implementation tracking, ECHA substance restriction registers, and Indian Railways tender disclosures. Bottom-up segment sizing triangulated against top-down rail fleet inventory analysis.
Across the analysis window, forecasts modeled product type segmentation by interior, exterior, signal, and brake illumination; application tier across high-speed, urban metro, tram, and coach platforms; technology trajectory from dimmable through RGB to smart lighting; and end-user contract structure variation. CAGRs derived from fleet replacement cycle analysis, regulatory mandate timelines, and voltage architecture transition assumptions in battery-electric multiple-unit platforms.
Forecasts assume regulatory continuity in EU Green Deal implementation and REACH compliance frameworks; material policy shifts or ECHA substance restriction expansions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Global Bearings Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Charge Air Coolers Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Child Seats Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Europe Automotive Lightweight Car Market