
 Automotive Wheel Alignment Service Market | 2026-2036
Automotive Wheel Alignment Service Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wheel Alignment Service Market Analysis
Multi-source procurement between captive OEM service bays and independent aftermarket chains is rebalancing how fleet operators secure wheel alignment capacity. Robert Bosch GmbH leverages its diagnostic-to-alignment equipment integration to anchor high-throughput workshop partnerships. Bridgestone Corporation sustains retail tire-and-alignment bundling that controls consumer touchpoints across North America. Continental AG competes through sensor calibration-linked alignment protocols that address ADAS recalibration requirements.
Automotive wheel alignment service encompasses the measurement and correction of wheel angles—camber, caster, and toe—to manufacturer specifications, typically performed with laser or digital imaging systems achieving tolerances within 0.1 degrees. The primary purpose is to ensure tire longevity, fuel efficiency, and vehicle stability under varying load conditions. Four-wheel alignment commands the dominant share of service revenue as all-wheel-drive and independent suspension architectures proliferate across passenger vehicles and SUVs. Digital alignment systems represent the fastest-expanding technology segment, displacing optical methods through faster bay turnover and integrated vehicle database connectivity. Heavy-duty vehicles concentrate margin pools where axle load regulations and tire replacement costs amplify the payback precision alignment delivers.
NHTSA enforces stability control system integrity that mandates post-repair alignment verification, while EPA fuel economy testing assumptions depend on factory alignment preservation that aftermarket services must replicate. ISO 9001 quality management and SAE J267 wheel alignment standards shape equipment certification and technician training thresholds that filter market access. Stakeholders must monitor how OEM over-the-air diagnostic updates redefine the boundary between dealership-exclusive and independent alignment service eligibility.
Market Dynamics
Fleet electrification is compressing alignment service intervals as battery weight distribution and torque-vectoring suspensions demand precision calibration protocols that legacy equipment cannot execute.
Growth Catalysts
- NHTSA ESC Mandates:Post-collision stability control recertification requires documented four-wheel alignment verification, creating mandatory service pull-through at collision repair facilities across the United States.
- ADAS Sensor Fusion:Camera-radar-lidar triangulation depends on geometric wheel position accuracy within 0.05 degrees, forcing recalibration workflows that bundle alignment with sensor validation.
- German OEM Workshop Networks:KBA-enforced precision standards for lane-keeping assist systems concentrate high-margin alignment demand in certified service channels.
Market Restraints
- Equipment Capex Concentration:Digital imaging alignment systems requiring $35,000-$80,000 bay investment create entry barriers for independent operators in secondary US markets.
- Technician Certification Scarcity:SAE J267 and manufacturer-specific ADAS calibration credentials limit service capacity expansion faster than equipment deployment.
- Optical System Stranded Assets:Laser-based alignment equipment faces accelerated obsolescence as vehicle databases require cloud-connected diagnostic integration.
Strategic Opportunities
- Mobile Alignment Units:Fleet operators in Texas and California are piloting on-site service deployment that eliminates downtime from depot-to-workshop transport.
- India Commercial Vehicle Segment:Axle load enforcement tightening on national highways creates compliance-driven demand for heavy-duty alignment services.
- ISO 9001 Integration:Quality management certification is becoming a procurement filter for logistics contracts, favoring workshop networks with documented process control.
Industry Challenges
- ADAS Calibration Complexity:Dynamic radar alignment requires controlled environment conditions—level floors, specific target placement, and minimal RF interference—that many existing bays cannot guarantee.
- Technician Retention Pressure:Electrical diagnostics competency and mechanical alignment skill convergence commands wage premiums that erode workshop margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wheel Alignment Service Market |
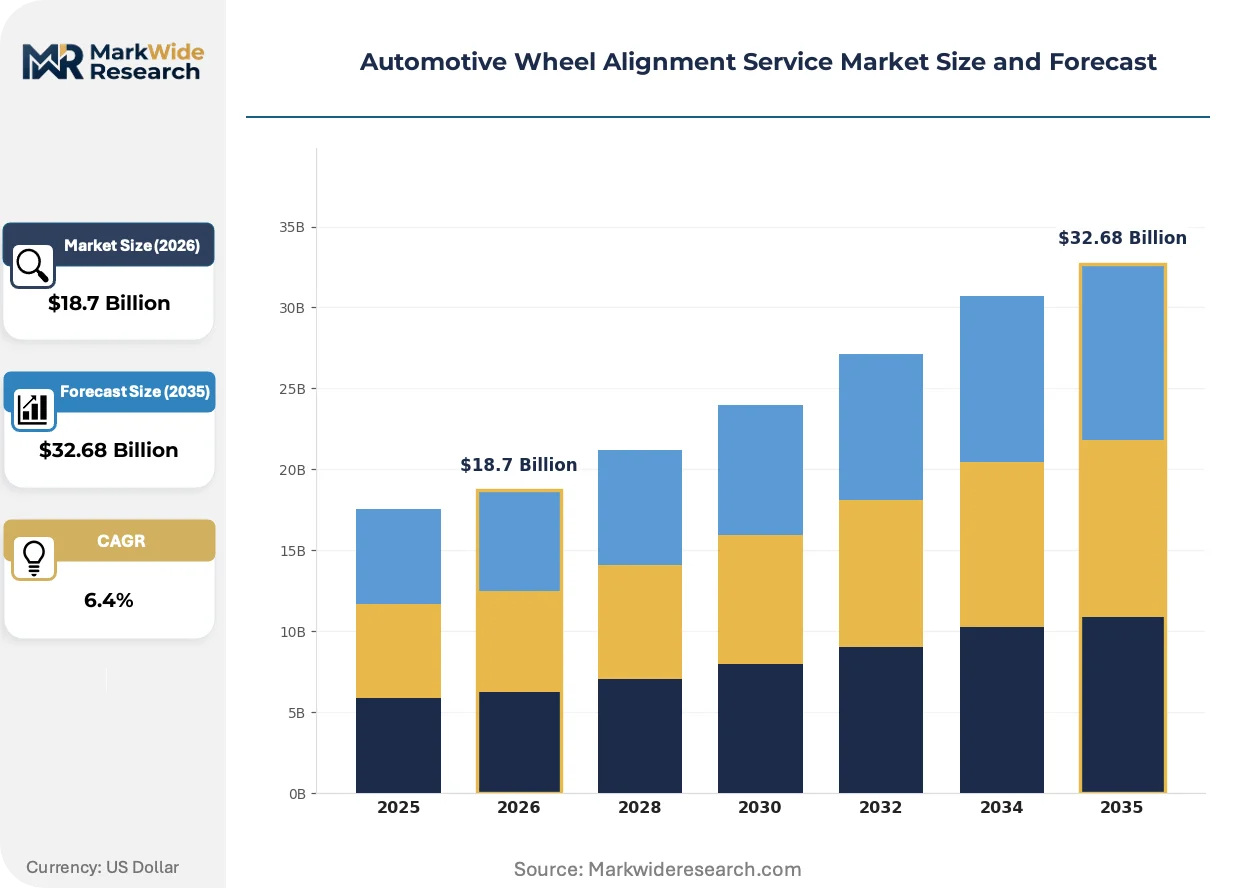
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Two-Wheel Alignment, Four-Wheel Alignment, Computerized Alignment, Steering Angle Reset End User: Individual Car Owners, Automotive Workshops, Fleet Operators, Online Service Platforms Technology: Laser Alignment, Optical Alignment, Adjustable Alignment Ramps, Digital Alignment Systems Vehicle Type: Passenger Vehicles, Commercial Trucks, SUVs, Heavy-Duty Vehicles |
| Companies Covered | Robert Bosch GmbH, General Motors, Bridgestone Corporation, Mercedes-Benz, Toyota Motor Corporation, The Goodyear Tire and Rubber Company, Ford Motor Company, Volkswagen AG, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wheel Alignment Service Market Emerging Trajectories
Service delivery models are fragmenting as vehicle connectivity enables remote diagnostic pre-qualification and as fleet operators demand uptime guarantees that reshape how alignment capacity is contracted and consumed.
Cloud-connected alignment platforms are unifying vehicle specification databases with real-time measurement systems, eliminating manual VIN entry errors and reducing bay setup time. High-volume fleet service providers in Michigan and Ohio are deploying these systems to compress turnaround below twelve minutes per vehicle. This unification is compressing the competitive advantage of dealership-exclusive technical information, democratizing precision service access.
EU F-Gas Regulation phase-down is accelerating refrigerant recovery equipment integration with alignment service bays, as combined HVAC-suspension service workflows reduce vehicle handling cycles. Workshop operators in Stuttgart and Wolfsburg are consolidating these functions to maximize bay utilization rates. Heavy-duty commercial segments face the steepest compliance cost escalation, driving consolidation toward multi-service-capable facilities.
Fleet procurement centralization is displacing transactional service relationships with multi-year alignment capacity contracts that specify uptime penalties and preventive maintenance intervals. Third-party logistics providers operating across the US Midwest are consolidating vendor panels to three or fewer approved workshop networks per region. This concentration is most visible in refrigerated transport, where tire wear costs dominate total cost of ownership calculations.
Automotive Wheel Alignment Service Market Segmentation
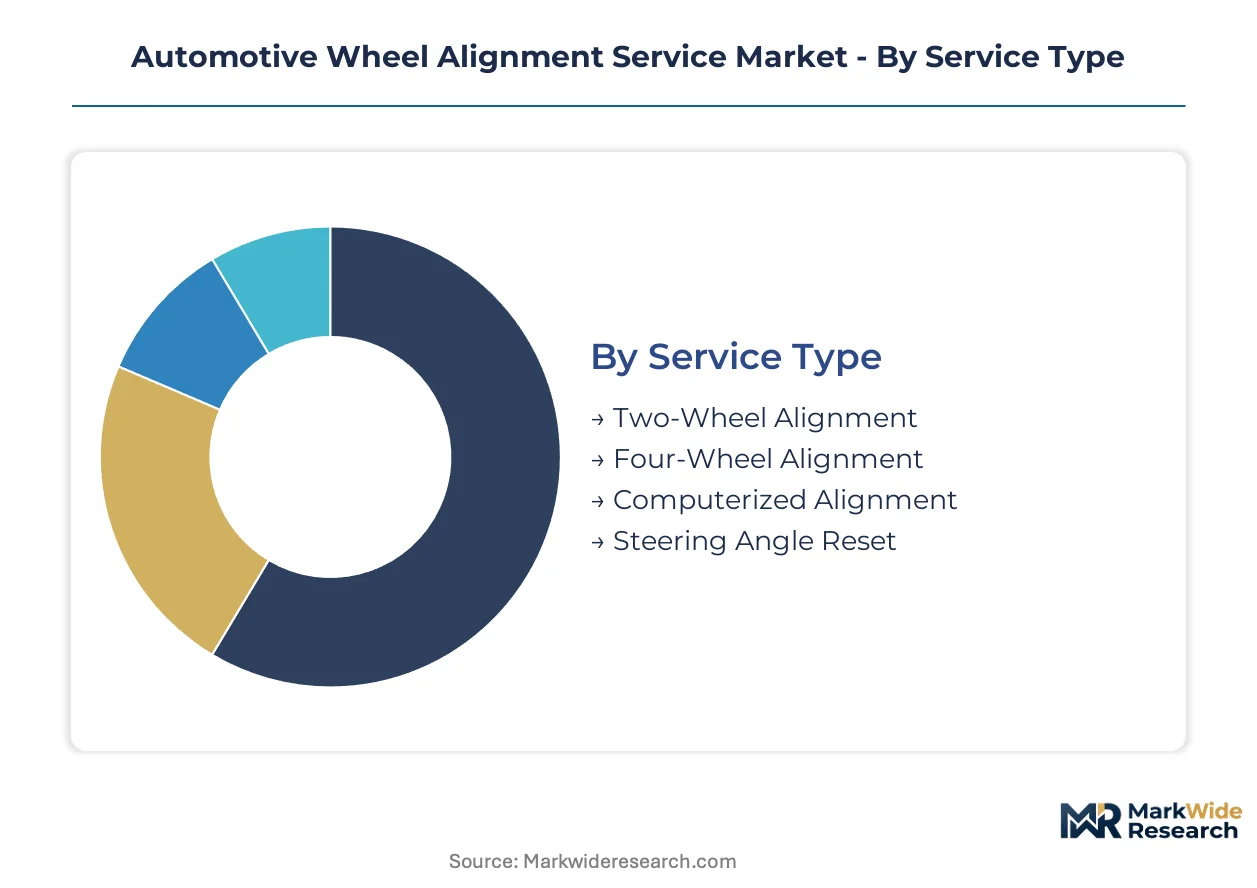
Service providers configure equipment and technician training around distinct operational profiles. Segment boundaries determine margin capture, with embedded ADAS calibration workflows commanding premium positioning against standalone mechanical adjustment.
Service Type:
Standalone alignment services operate on transactional pricing, while sensor-integrated workflows embed within broader diagnostic protocols.
- Two-Wheel Alignment:Front-axle-only angle correction for solid-rear-axle vehicles. Quick-lube chains in Texas and Florida deploy this format for high-turnover consumer service at compressed price points.
- Four-Wheel Alignment:Comprehensive camber, caster, and toe adjustment across all axles with thrust angle verification. Independent suspension architectures on all-wheel-drive SUVs and EVs in California and Germany concentrate demand here, with NHTSA post-collision mandates forcing documentation standards that favor precision equipment.
- Computerized Alignment:Database-driven specification retrieval with automated measurement logging. Workshop networks in Michigan and Ohio leverage cloud-connected platforms to eliminate manual VIN entry errors and compress bay setup below three minutes.
- Steering Angle Reset:Electronic stability control recalibration following mechanical adjustment. German KBA enforcement of lane-keeping assist precision standards makes this mandatory for ADAS-equipped vehicles in OEM-certified channels.
Four-wheel alignment leads volumes today; steering angle reset is gaining share fastest.
End User:
Customer type dictates contract structure, from retail walk-in pricing to multi-year uptime guarantees with penalty clauses.
- Individual Car Owners:Transactional demand triggered by tire replacement or vibration complaints. Tire retailers in North America bundle alignment with purchase to secure recurring touchpoints and warranty compliance.
- Automotive Workshops:Independent service bays and dealership service departments with fixed overhead absorption requirements. SAE J267 certification thresholds in the United States filter market access, concentrating volume in networks with documented technician training.
- Fleet Operators:Centralized procurement of preventive maintenance capacity with specified intervals. Third-party logistics providers across the US Midwest consolidate vendor panels to three approved networks per region, embedding uptime penalties for depot downtime.
- Online Service Platforms:Digital booking interfaces aggregating workshop capacity for price-transparent comparison. Mobile alignment pilots in Texas and California eliminate transport downtime through on-site deployment.
Fleet operators anchor revenue concentration today; online platforms are expanding most quickly.
Technology:
Equipment vintage determines service eligibility for ADAS-equipped vehicles, with cloud connectivity becoming a hard requirement.
- Laser Alignment:Optical beam projection systems with manual target interpretation. Legacy installations face stranded asset risk as vehicle databases require internet-connected specification retrieval that laser platforms cannot support.
- Optical Alignment:Camera-based measurement with analog gauge displays. Secondary US markets retain these systems where equipment capex barriers block digital upgrade cycles.
- Adjustable Alignment Ramps:Physical height and angle modification infrastructure for heavy-duty axle access. Commercial vehicle enforcement on Indian national highways drives compliance demand where axle load regulations amplify precision payback.
- Digital Alignment Systems:Integrated imaging sensors with real-time database connectivity and automated reporting. High-throughput fleet providers compress turnaround below twelve minutes per vehicle, displacing optical methods through faster bay turnover.
Digital alignment systems lead replacement demand; adjustable ramps dominate heavy-duty margins.
Vehicle Type:
Weight distribution and suspension complexity determine calibration protocol intensity and service interval compression.
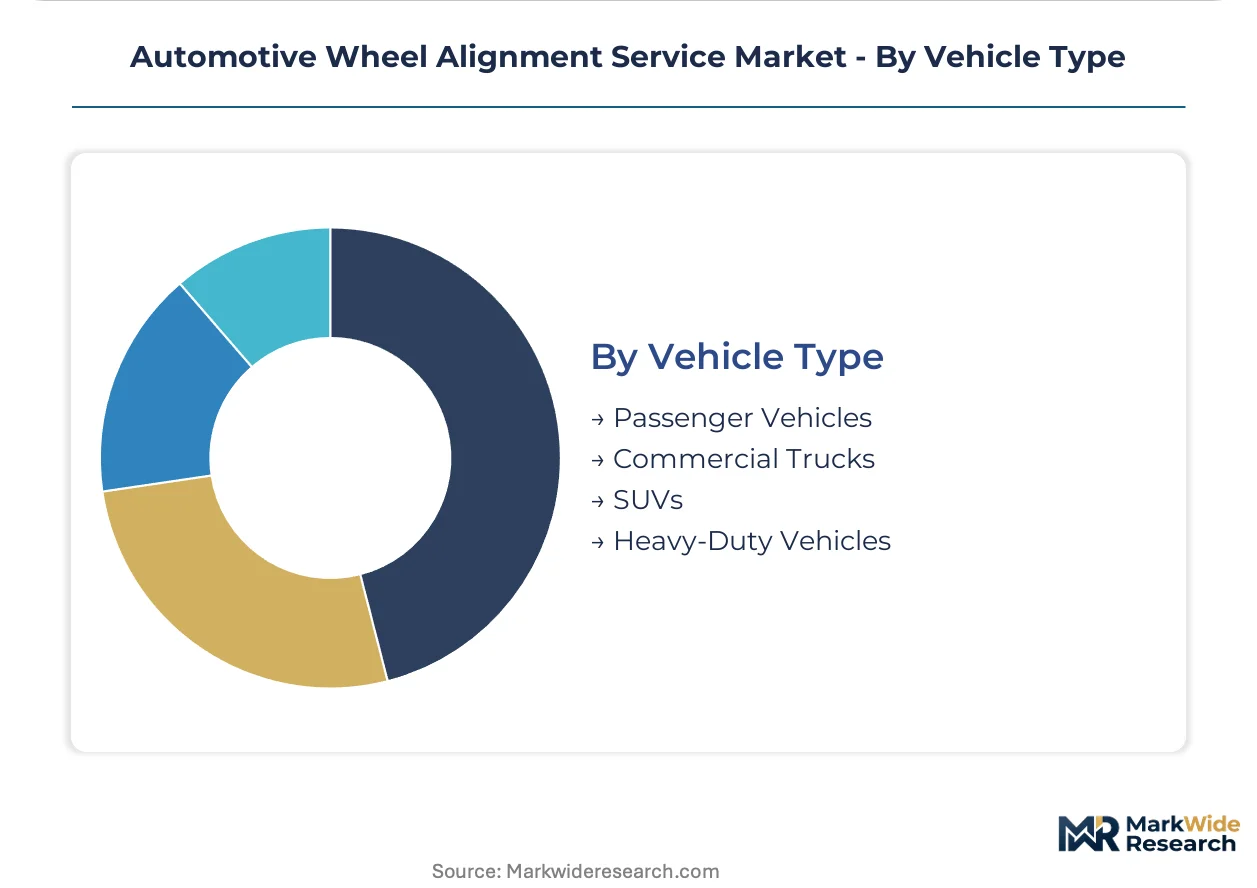
- Passenger Vehicles:Standard independent front suspension with optional rear multi-link configurations. German OEM workshop networks enforce precision standards that concentrate high-margin demand in certified channels.
- Commercial Trucks:Solid axle architectures with leaf spring or air suspension variants. Axle load enforcement in India and tire replacement cost economics in refrigerated US transport drive preventive maintenance contracting.
- SUVs:All-wheel-drive powertrains with torque-vectoring differentials requiring thrust angle precision. Battery weight distribution in electrified SUVs demands calibration protocols that legacy equipment cannot execute.
- Heavy-Duty Vehicles:Multi-axle configurations with tag and pusher axle arrangements. EU F-Gas Regulation phase-down accelerates consolidation toward multi-service-capable facilities in Stuttgart and Wolfsburg combining HVAC and suspension workflows.
Passenger vehicles dominate transaction volumes; heavy-duty vehicles concentrate margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor automotive corridor anchors North American wheel alignment service demand through dense OEM service networks and collision repair concentration. Fleet electrification across Michigan and Ohio compresses service intervals as battery weight distribution mandates precision calibration protocols.
United States
NHTSA electronic stability control mandates drive post-collision alignment verification at repair facilities nationwide. EPA fuel economy testing assumptions require factory alignment preservation that aftermarket services must replicate. Texas and California pilot mobile alignment units that eliminate fleet downtime from depot-to-workshop transport.
Germany
KBA-enforced precision standards for lane-keeping assist systems concentrate high-margin demand in OEM-certified workshop networks. EU F-Gas Regulation phase-down accelerates refrigerant recovery equipment integration with alignment bays in Stuttgart and Wolfsburg. Continental AG competes through sensor calibration-linked alignment protocols addressing ADAS recalibration requirements.
India
Axle load enforcement tightening on national highways creates compliance-driven demand for heavy-duty alignment services. BIS quality standards shape equipment certification thresholds filtering market access for independent operators. Commercial vehicle clusters in Maharashtra and Gujarat drive preventive maintenance contracting as tire replacement costs amplify precision payback.
Japan
METI industrial standards enforce diagnostic equipment interoperability that shapes workshop technology procurement patterns. JIS certification requirements filter technician training thresholds limiting service capacity expansion. Kanto region fleet operators centralize procurement through multi-year alignment capacity contracts with uptime penalty clauses.
China
MIIT vehicle connectivity mandates enable remote diagnostic pre-qualification that fragments traditional service delivery models. GB standards for suspension system safety tighten compliance requirements for independent workshops. Yangtze River Delta logistics hubs concentrate fleet operator demand for compressed turnaround alignment services.
Automotive Wheel Alignment Service Market Vendor Landscape
Global majors compete with regional champions across equipment integration and service network density. The vendor base spans consolidated diagnostic equipment manufacturers, tire-retail bundling specialists, and OEM-captive service operations. Three archetypes dominate: integrated diagnostic-to-alignment system providers, tire-centric retail bundlers, and sensor calibration protocol specialists. Strategic moves center on cloud-connected platform deployment and technician certification program expansion.
Within the integrated systems tier, Robert Bosch GmbH and Continental AG exemplify diagnostic-to-alignment equipment convergence that anchors high-throughput workshop partnerships. Bridgestone Corporation occupies the retail-bundling position, controlling consumer touchpoints through tire-and-alignment service packaging. These three entities represent distinct competitive vectors—equipment integration, retail channel capture, and ADAS protocol specialization—that structure how market participants secure alignment service capacity.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| General Motors |
| Bridgestone Corporation |
| Mercedes-Benz |
| Toyota Motor Corporation |
| The Goodyear Tire and Rubber Company |
| Ford Motor Company |
| Volkswagen AG |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Fleet procurement centralization across the US Midwest is compressing vendor panels to three approved workshop networks per region, forcing equipment manufacturers to consolidate distribution partnerships and compress margin structures for independent operators.
Pricing Analysis
Input-cost pass-through from digital imaging sensor arrays and cloud-connected vehicle databases is intensifying margin pressure on legacy equipment tiers. Pricing stratifies across premium ADAS-certified, standard four-wheel, and economy two-wheel alignment tiers, with SAE J267 certification commanding measurable premiums. Cost compression in the economy tier reflects quick-lube chain consolidation in Texas and Florida. Fleet operators exhibit lowest price sensitivity due to uptime penalty clauses, while individual car owners drive transactional price competition.
Supply Chain Analysis
Freight cost escalation from German and Japanese precision component hubs is amplifying landed costs for digital alignment systems in North American secondary markets. Manufacturing concentrates in Germany, Japan, and China, with sensor calibration modules drawing from semiconductor foundries in Taiwan and South Korea. Single-source vulnerability sits with cloud-connected vehicle specification databases controlled by OEM technical information gatekeepers. Distribution runs through captive OEM service bay networks, independent aftermarket chains, and emerging mobile service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive wheel alignment service market compounds steadily as ADAS penetration mandates recurring precision calibration across expanding vehicle fleets.
For Market Incumbents: Lock in technician certification pipeline advantages by expanding SAE J267 and manufacturer-specific ADAS credential programs before independent operators can match capacity. Deepen backward integration into cloud-connected vehicle database subscriptions to neutralize OEM technical information exclusivity threats. Consolidate high-throughput fleet partnerships in Michigan and Ohio through multi-year uptime guarantee contracts with penalty structures that emerging entrants cannot underwrite. For New Entrants and Emerging Players: Launch via mobile alignment units targeting Texas and California fleet depots where transport downtime elimination commands premium pricing. White-space concentration sits in India commercial vehicle corridors where axle load enforcement tightening creates compliance-driven demand underserved by precision-capable networks. Penetrate through ISO 9001 quality certification as a procurement filter for logistics contracts that incumbent quick-lube chains lack documentation to satisfy. For Investors and Strategic Acquirers: Asymmetric upside sits with regional workshop networks possessing captive fleet relationships and documented technician training infrastructure. Long-term viability hinges on ADAS calibration workflow integration that sustains pricing power as mechanical alignment commoditizes. Monitor NHTSA rulemaking on over-the-air diagnostic updates as the critical inflection signal determining dealership-exclusive versus independent service eligibility boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Program Expansion | SAE J267 and OEM-specific ADAS credentials filter market access faster than equipment deployment cycles. |
| Cloud-Connected Platform Integration | Real-time vehicle database connectivity compresses bay setup time below three minutes for high-throughput operators. |
| Mobile Service Deployment | On-site alignment units eliminate fleet downtime from depot-to-workshop transport in Texas and California pilots. |
| Fleet Capacity Contract Consolidation | Multi-year uptime guarantee contracts with penalty clauses lock in revenue concentration across Midwest logistics hubs. |
| ADAS Calibration Workflow Bundling | Sensor validation-linked alignment protocols address Continental AG-competitive positioning in German OEM-certified channels. |
Methodological Framework
Multiple input streams — structured interviews with OEM platform engineers and aftermarket distributor operations heads, technical discussions with Tier 1 supplier procurement leads, and validation sessions with fleet maintenance directors — were reconciled against secondary sources including NHTSA regulatory filings, EPA fuel economy test procedures, and vehicle production databases from IHS Markit. Bottom-up service volume estimates from workshop network capacity analysis were triangulated with top-down market sizing from equipment shipment tracking.
Data-stream reconciliation across service type, technology vintage, vehicle architecture, and regional regulatory cluster dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from installed base growth, service interval compression factors, and ADAS penetration curves. Forecast inputs incorporated fleet electrification weight distribution effects and KBA-enforced precision standard adoption timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated OEM over-the-air diagnostic update deployment or disruptive mobile service platform scaling. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tire Retreading Market
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
High Performance Wheels Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Global Tires Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
All-Terrain Vehicle Tire Market