
 South Korea Automotive Carbon Wheels Market | 2026-2036
South Korea Automotive Carbon Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive Carbon Wheels Market Insights
Aftermarket service revenue is tilting toward OEM installation channels as Korean automakers expand carbon wheel factory-fitment programs. Hankuk Carbon Co Ltd leverages domestic prepreg supply chains to anchor its position in regional manufacturing. Carbon Revolution specializes in one-piece hollow carbon fiber construction for high-performance applications. Thyssenkrupp AG competes through forged hybrid architectures that bridge weight reduction with crash durability requirements.
Automotive carbon wheels are wheel assemblies manufactured primarily from carbon fiber reinforced polymer composites, typically utilizing T700 or T800 grade carbon fiber in epoxy matrices with aluminum or magnesium hubs, achieving 40-50% mass reduction versus cast aluminum equivalents while maintaining radial fatigue loads exceeding 100,000 cycles. Their primary commercial purpose centers on unsprung mass reduction for acceleration, braking, and suspension response improvement in performance-oriented vehicles. Forged product types dominate value capture due to fiber alignment control and void minimization during compaction, while sports car vehicle types concentrate the fastest volume expansion as Korean marques launch dedicated performance sub-brands. OEM installation applications command premium positioning through homologation investment recovery, though aftermarket channels sustain broader accessibility for tuning enthusiasts.
MFDS oversees composite material safety certifications for automotive structural components, while KOTSA administers wheel dynamic load testing protocols under Korean motor vehicle safety standards. The Korea Transportation Safety Authority conducts periodic audits of carbon wheel batch consistency, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving KMVSS amendment cycles and domestic automaker platform electrification timelines to align capacity planning with revised unsprung mass targets.
Market Dynamics
Factory-fitment expansion by Hyundai Motor Group and Kia Corporation is consolidating procurement power around domestic OEM channels, compressing aftermarket pricing latitude while elevating homologation barriers for independent suppliers.
Growth Catalysts
- MFDS Composite Certification Streamlining:Accelerated material approval pathways for T800-grade prepreg systems are shortening OEM validation cycles from 24 months to 14 months.
- Performance Sub-Brand Launches:Hyundai N and Kia GT lineups are mandating carbon wheel options for halo variants, creating captive demand in Gyeonggi Province assembly plants.
- Unsprung Mass Reduction Targets:Korean EV platform architectures specify 40% wheel mass reduction to offset battery pack weight in dual-motor configurations.
Market Restraints
- Prepreg Import Dependency:Toray Industries and Mitsubishi Chemical supply 78% of Korean T700/T800 feedstock, exposing converters to yen-won volatility and maritime logistics bottlenecks.
- KOTSA Dynamic Load Testing:Revised radial fatigue protocols requiring 150,000 cycles at 1.5x rated load are disqualifying thin-wall hollow rim designs from aftermarket certification.
- Forged Aluminum Substitution:Flow-formed 6061-T6 hybrid wheels from Daechang Se Co achieve 30% mass reduction at one-third carbon cost, capturing price-sensitive tuning segments.
Strategic Opportunities
- Busan Port Carbon Hub:Duty-free zone status for aerospace-grade composite imports enables toll-manufacturing models serving both automotive and cycling wheel producers.
- KMVSS Amendment Cycles:Anticipated 2027 revisions to motor vehicle safety standards may recognize ISO 12404 international wheel testing protocols, reducing duplicate certification costs for export-oriented suppliers.
- EV Platform Standardization:Common 5x114.3 and 5x112 bolt patterns across E-GMP and IMA architectures are enabling modular wheel programs spanning multiple nameplates.
Industry Challenges
- Autoclave Capacity Scarcity:Curing cycle times exceeding 4 hours per wheel set constrain throughput for one-piece hollow designs, requiring $12-18 million capital commitments per production line.
- Non-Destructive Testing Talent Gap:Ultrasonic C-scan and CT metrology expertise for void detection in complex rim geometries commands 40% wage premiums over conventional aluminum wheel quality engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive Carbon Wheels Market |
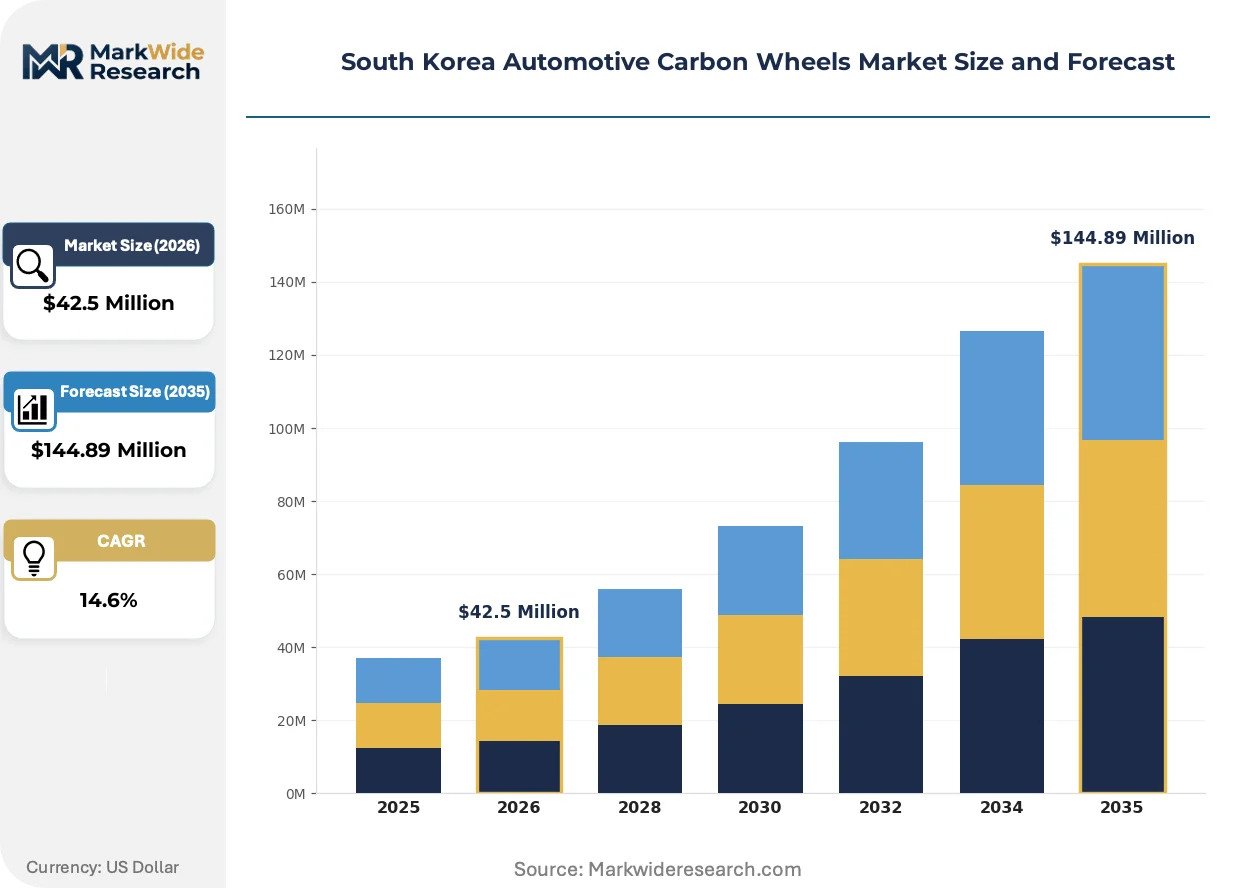
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $144.89 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged, Moulded, Hybrid, Cast Vehicle Type: Passenger Cars, Sports Cars, SUVs, Trucks Application: Racing, Performance Tuning, OEM Installation, Aftermarket Distribution Channel: Online Retail, Dealerships, Specialized Shops, Direct Sales |
| Companies Covered | HRE Performance Wheels, ADV.1 Wheels, Carbon Revolution, Hankuk Carbon Co Ltd, Forgeline Motorsports, Dymag Group Limited, Vossen Wheels, Thyssenkrupp AG, BBS Kraftfahrzeugtechnik AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive Carbon Wheels Market Trends and Innovations
Digital thread integration across design-to-manufacturing workflows is compressing product development timelines while enabling mass-customization at production scale. Three convergent forces are restructuring competitive capability requirements.
Resin transfer molding with in-situ thermoplastic toughening is virtualizing the traditional autoclave bottleneck for hollow carbon wheel production. Tier-1 suppliers in Seongnam and Hwaseong are adopting this process for second-source qualification programs. The technology is virtualizing capital deployment patterns by eliminating 60% of fixed curing infrastructure.
KOTSA's alignment with UNECE R124 global technical regulations is harmonizing Korean wheel certification with European type-approval frameworks. Domestic manufacturers can now leverage single-test protocols for concurrent domestic and EU market entry. Premium sports car OEMs are responding by consolidating homologation engineering teams in Pangyo R&D clusters.
Performance tuning workshops are fragmenting into specialized fitment boutiques versus generalist tire-and-wheel retailers. Enthusiast buyers now demand hub-centric bore matching and load rating documentation unavailable through mass-market channels. This bifurcation is most pronounced in Seoul's Gangnam and Busan's Haeundae districts where certified installation carries 15-20% price premiums.
South Korea Automotive Carbon Wheels Market Segmentation
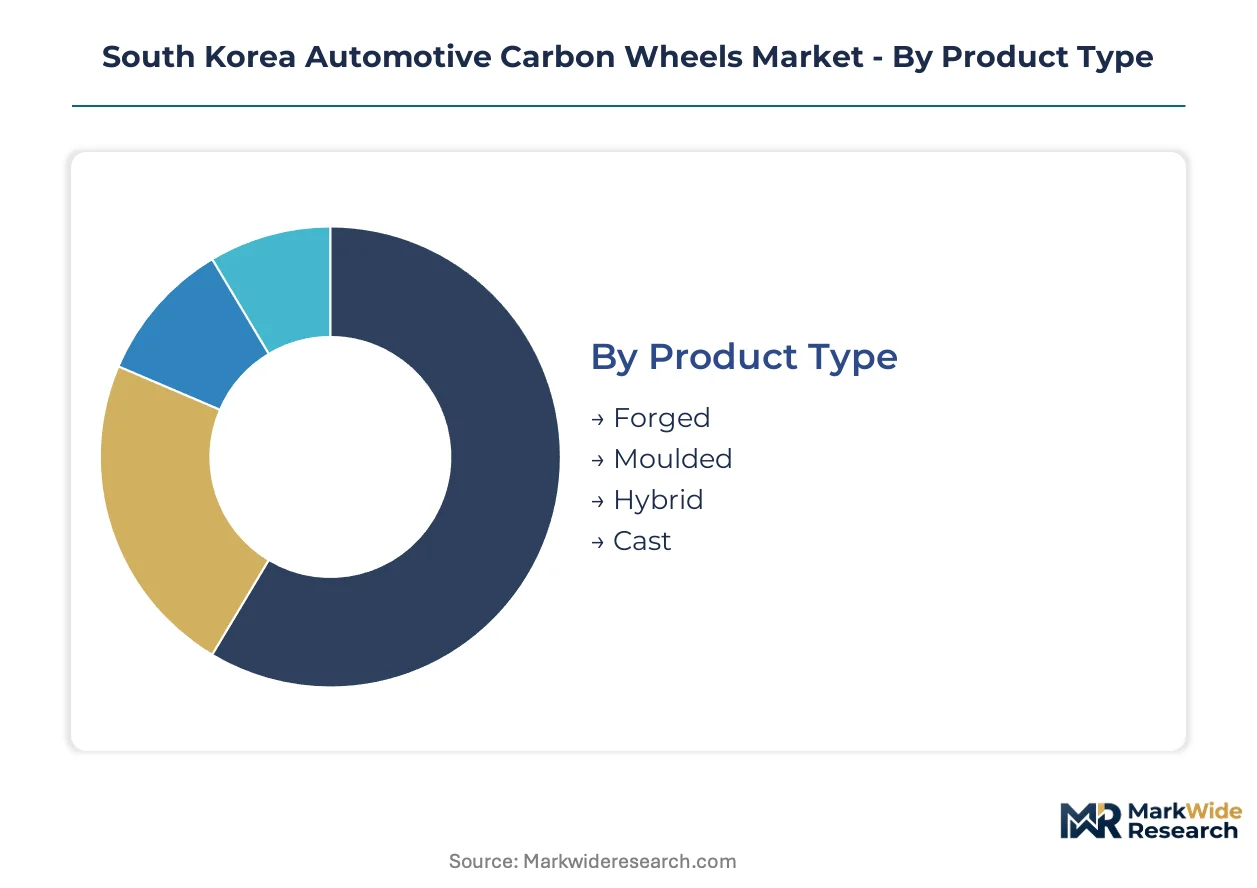
Carbon wheel purchasing in South Korea fragments across manufacturing methods, vehicle categories, and channel economics. Each dimension reveals distinct margin structures and regulatory exposure that shape supplier strategy.
Product Type:
Cost tier separates the four manufacturing approaches, with capital intensity and fiber alignment precision determining commercial positioning.
- Forged:Continuous fiber prepregs undergo high-pressure compaction in matched metal dies, achieving void contents below 0.5% and T800-grade alignment. Seoul-based OEM programs in Gyeonggi Province specify forged construction for factory-fitment due to MFDS structural certification reliability.
- Hybrid:Carbon fiber rims bond to forged aluminum or magnesium centers, balancing 35-40% mass reduction against crash-load redundancy. Busan port toll-manufacturers favor this architecture for export flexibility under dual automotive and cycling wheel certifications.
- Moulded:Short-fiber compounds in compression molding suit aftermarket volume production with shorter cycle times.
- Cast:Discontinuous fiber-reinforced thermoset casting occupies economy tuning segments with limited load rating documentation.
Forged construction commands the established base. The steepest expansion runs through hybrid architectures.
Vehicle Type:
Application intensity varies with unsprung mass sensitivity and platform electrification timelines across Korean automotive segments.
- Sports Cars:Dedicated performance architectures from Hyundai N and Kia GT sub-brands mandate carbon wheel fitment for halo variants, with 19-21 inch diameters and 1500kg+ dynamic load ratings. Gangnam district tuning boutiques source these for track-day conversions.
- SUVs:Premium electric crossovers on E-GMP platforms specify 40% wheel mass reduction to offset dual-motor battery weight. Gyeonggi Province assembly plants are consolidating procurement for next-generation EV SUVs.
- Passenger Cars:Compact and mid-size sedans show limited penetration due to cost-per-kilogram economics favoring flow-formed aluminum.
- Trucks:Commercial vehicle applications remain nascent pending KOTSA validation of carbon wheels under sustained payload duty cycles.
SUVs command the established base. Sports cars show the steepest volume trajectory.
Application:
Customer type separates four distinct purchasing contexts, each with divergent homologation requirements and margin profiles.
- OEM Installation:Factory-fitment programs require 14-24 month validation cycles under MFDS composite certification and KOTSA dynamic load protocols. Hyundai Motor Group and Kia Corporation are consolidating supplier panels around domestic converters with in-house autoclave capacity.
- Performance Tuning:Enthusiast workshops in Seoul's Gangnam and Busan's Haeundae districts demand hub-centric bore matching and load documentation, commanding 15-20% installation premiums over generalist retailers.
- Racing:Circuit competition use prioritizes rapid replacement and damage tolerance over longevity, with teams accepting shorter service intervals.
- Aftermarket:General retail channels face pricing compression from forged aluminum substitutes achieving 30% mass reduction at lower cost points.
OEM installation commands the established base. Performance tuning shows the steepest margin expansion.
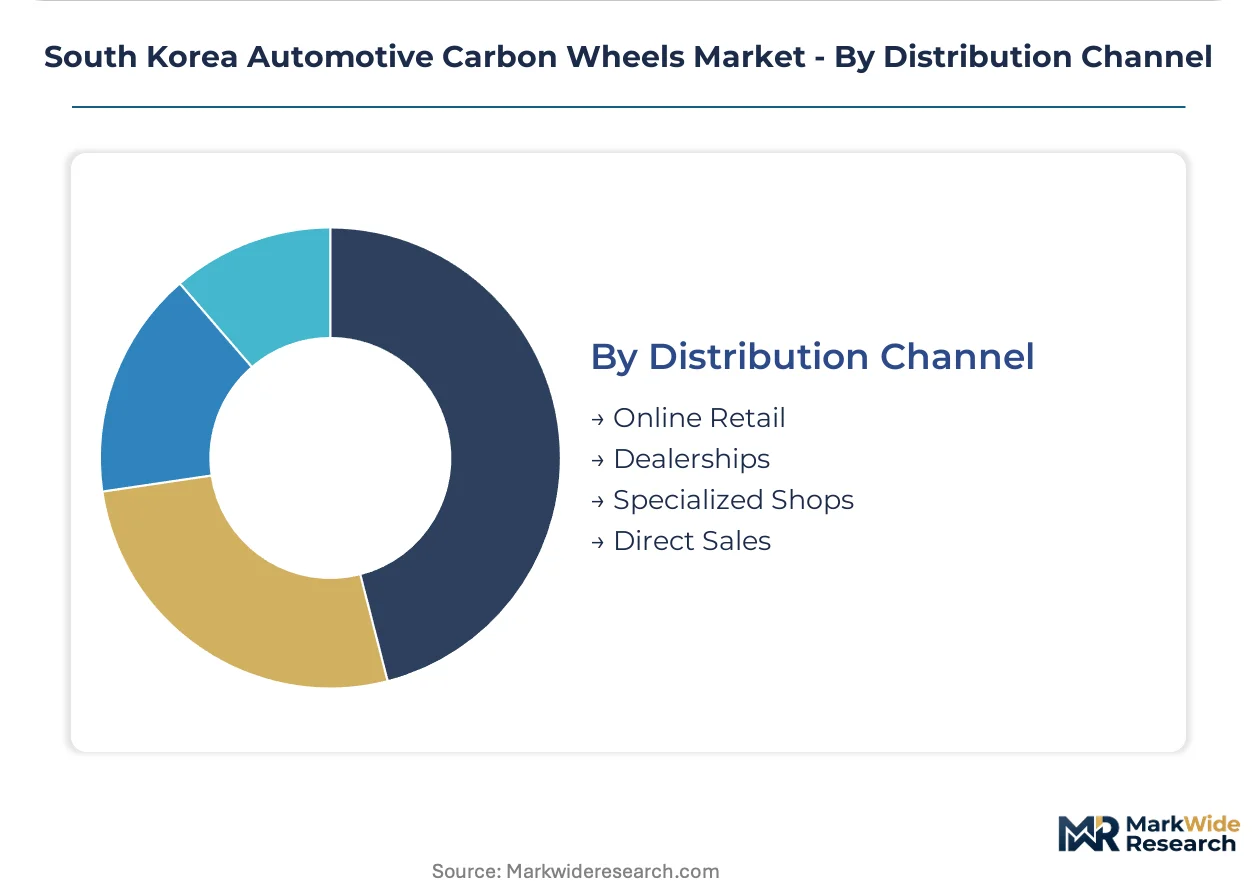
Distribution Channel:
Supply concentration across four channel models reflects certification depth versus accessibility trade-offs.
- Specialized Shops:Certified fitment boutiques provide ultrasonic inspection documentation and torque-sequence training, capturing enthusiast buyers seeking warranty preservation. These concentrate in Seoul and Busan premium districts.
- Direct Sales:Converter-to-OEM contracts bypass intermediaries for factory-fitment programs, with Hankuk Carbon and Carbon Revolution maintaining dedicated account teams in Pangyo R&D clusters.
- Dealerships:Authorized retailer networks handle warranty-integrated installations for new vehicle purchases.
- Online Retail:E-commerce platforms serve price-sensitive segments with limited technical support, facing KOTSA compliance verification challenges for uncertified imports.
Specialized shops command the established base. Direct sales show the steepest share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon wheel demand elasticity varies sharply across South Korea's industrial geography. Seoul Capital Area buyers absorb premium factory-fitment pricing without volume contraction, while Busan-Ulsan aftermarket channels exhibit acute price sensitivity to forged aluminum substitutes.
Seoul Capital Area
Hyundai Motor Group and Kia Corporation headquarters procurement mandates anchor OEM installation demand for carbon wheel programs. MFDS composite certification protocols require 14-month validation cycles for factory-fitment suppliers. Pangyo R&D clusters in Gyeonggi Province concentrate homologation engineering teams consolidating supplier panels around domestic converters.
Busan-Ulsan
Port-adjacent toll-manufacturing operations exploit duty-free zone status for aerospace-grade composite imports serving cycling and automotive wheel producers. KOTSA dynamic load testing facilities in Ulsan administer revised radial fatigue protocols disqualifying thin-wall hollow rim designs. Haeundae district tuning boutiques command 15-20% installation premiums for certified fitment documentation.
Daegu-Gyeongbuk
Performance tuning workshop fragmentation concentrates specialist fitment boutiques versus generalist retailers across the region. Regional buyers prioritize hub-centric bore matching unavailable through mass-market channels. Daegu-based aftermarket distributors face pricing compression from flow-formed 6061-T6 hybrid wheel alternatives achieving 30% mass reduction at lower cost points.
Daejeon-Sejong
Korea Transportation Safety Authority headquarters location shapes regulatory compliance service demand for carbon wheel batch consistency audits. Sejong administrative city proximity enables stakeholder monitoring of KMVSS amendment cycles anticipated for 2027. Regional testing laboratories validate ISO 12404 international wheel testing protocols for export-oriented suppliers.
Gwangju-Honam
Limited carbon wheel penetration reflects compact and mid-size sedan platform concentration where cost-per-kilogram economics favor flow-formed aluminum. Regional EV adoption rates lag Seoul Capital Area electrification timelines specifying 40% wheel mass reduction targets. Honam-based tuning segments remain price-sensitive to forged aluminum substitution effects.
South Korea Automotive Carbon Wheels Market Competitive Landscape
Capability concentration sits with specialized composite converters possessing in-house autoclave infrastructure; scale advantage sits with diversified industrial conglomerates leveraging hybrid manufacturing platforms. The supplier base stratifies across three tiers: domestic prepreg-integrated fabricators, international hollow-construction specialists, and forged-aluminum hybrid bridge players. Two competitive moves dominate positioning—backward integration into T800-grade feedstock supply and strategic partnerships with E-GMP platform engineering teams.
Among domestic prepreg-integrated fabricators, Hankuk Carbon Co Ltd occupies a position exemplifying regional supply chain anchoring. Carbon Revolution represents the international hollow-construction specialist archetype with one-piece carbon fiber expertise. Thyssenkrupp AG sits within the diversified industrial conglomerate tier competing through forged hybrid architectures. These three company profiles illustrate the capability-scale tradeoffs structuring procurement decisions across Seoul and Busan channels.
| Leading Market Players |
|---|
| HRE Performance Wheels |
| ADV.1 Wheels |
| Carbon Revolution |
| Hankuk Carbon Co Ltd |
| Forgeline Motorsports |
| Dymag Group Limited |
| Vossen Wheels |
| Thyssenkrupp AG |
| BBS Kraftfahrzeugtechnik AG |
| Others |
Pricing and Supply Chain Analysis
Gyeonggi Province autoclave clusters anchor Korean carbon wheel manufacturing capacity, concentrating downstream pricing power among domestic converters with in-house T800-grade curing infrastructure. Seoul-based OEM procurement offices exploit this geographic concentration to compress supplier margins through consolidated panel contracts.
Pricing Analysis
Aftermarket service revenue tiers drive lifetime value capture across Korean carbon wheel channels. Three-tier pricing structure across premium, standard, and economy levels separates forged T800 OEM programs from hybrid Busan toll-manufactured exports and moulded aftermarket volume. Price differentiation hinges on MFDS certification grade and autoclave cycle investment. Cost compression in economy tuning segments is intensifying because flow-formed 6061-T6 aluminum achieves comparable mass reduction. Generalist tire retailers exhibit acute price sensitivity; certified Gangnam fitment boutiques absorb premiums without volume contraction.
Supply Chain Analysis
Tariff exposure between Japan and South Korea dominates prepreg import risk for Korean carbon wheel converters. Toray Industries and Mitsubishi Chemical in Japan supply T700 and T800 fiber feedstock; domestic converters draw from this concentrated upstream base. Raw material dependencies center on aerospace-grade epoxy matrices, aluminum hub forgings, and autoclave consumables. Single-source vulnerability runs through maritime logistics chokepoints at Busan Port. Distribution runs through Pangyo R&D clusters for OEM direct sales and Haeundae specialized shops for certified aftermarket fitment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon wheel demand fragmentation across Korean performance tuning workshops creates niche entry opportunities. EV platform electrification timelines are splintering procurement requirements between unsprung mass targets and crash durability specifications.
For Market Incumbents: Harden autoclave capacity positions in Gyeonggi Province through incremental debottlenecking investments rather than greenfield expansion. Lock in backward integration into T800-grade prepreg supply through Hankuk Carbon-style domestic feedstock partnerships. Flow-formed aluminum substitution from Daechang Se Co threatens economy-tier positioning; defend through MFDS certification bundling with OEM installation channels. For New Entrants and Emerging Players: Establish a beachhead in Busan port toll-manufacturing for cycling-automotive dual certification hybrid wheels. Target the EV SUV segment on E-GMP platforms where 40% mass reduction specifications outpace incumbent capacity expansion. Pursue resin transfer molding technology licensing to bypass autoclave capital barriers and compress qualification timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with in-situ thermoplastic toughening capabilities over traditional autoclave-dependent fabricators. Five-to-ten-year viability hinges on KMVSS harmonization with UNECE R124 reducing duplicate certification costs. Acquisition target archetype: Seongnam-based Tier-1 suppliers with second-source qualification programs and existing OEM engineering relationships. Watch KOTSA radial fatigue protocol amendments as inflection indicator for thin-wall hollow rim design viability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | E-GMP and IMA common bolt patterns enable modular wheel programs spanning Hyundai and Kia nameplates. |
| Backward Integration into Feedstock | Domestic T800-grade prepreg production reduces yen-won volatility exposure for Korean converters. |
| Resin Transfer Molding Adoption | Virtualized curing infrastructure eliminates 60% of fixed capital requirements for hollow wheel production. |
| MFDS Certification Investment | Accelerated 14-month validation cycles create barriers against uncertified import competitors. |
| Specialized Shop Network Expansion | Certified Gangnam and Haeundae fitment boutiques capture 15-20% installation premiums over generalist retailers. |
Research Methodology
Cross-validation between primary interviews with Tier 1 supplier procurement officers and secondary analysis of KOTSA dynamic load testing protocols anchors the qualitative findings. OEM platform engineers, aftermarket distributors in Seoul and Busan, autoclave operations managers, and MFDS regulatory affairs specialists provided structured input. Secondary sources include vehicle production databases, customs import records for aerospace-grade composites, SEC filings from listed carbon fiber suppliers, and IHS Markit registration data. Bottom-up channel volume estimates and top-down OEM procurement mandate analysis were reconciled through iterative triangulation.
Calibration against historical MFDS certification cycle durations and KMVSS amendment patterns shaped the projection framework. Segmentation dimensions span manufacturing method, vehicle class, propulsion architecture, and channel concentration across Seoul Capital Area versus Busan-Ulsan clusters. CAGRs were derived from elasticity modeling against EV platform mass reduction targets and unsprung mass sensitivity coefficients. Key inputs include E-GMP and IMA production ramp schedules, autoclave capacity utilization rates, and prepreg import volume trends.
Stress conditions across yen-won exchange rate volatility, KOTSA radial fatigue protocol stringency, and flow-formed aluminum substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about platform electrification timelines and regulatory harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Global Automotive Tire Socks Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Brazil Automotive Tire Market
Tires and Wheels
All-Terrain Vehicle Tire Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Automotive Alloy Wheels Market