
 Run Flat Tire Inserts Market | 2026-2036
Run Flat Tire Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Run Flat Tire Inserts Market Analytics
Military fleet procurement is recalibrating as defense operators prioritize mobility continuity for armored and tactical vehicles. Hutchinson Industries anchors this shift through its established defense supply relationships and specialized run-flat engineering. Pirelli & C. S.p.A. competes across both civilian and military channels with advanced polymer-based insert systems. RunFlat International specializes in retrofit solutions that extend fleet readiness without full tire replacement.
Run flat tire inserts are mechanical or elastomeric rings installed inside standard tire assemblies that support vehicle weight and maintain drivability following air loss, typically manufactured through compression molding of high-tensile rubber compounds or reinforced polymer composites to withstand dynamic loads at zero inflation pressure. Self-supporting inserts dominate current military and commercial procurement due to proven load-bearing capacity, while smart inserts with integrated pressure monitoring represent the fastest-growing category as telematics integration becomes standard. The material dimension shows polymer composites capturing margin pools from conventional rubber as weight reduction and thermal stability requirements intensify across heavy-duty applications.
NHTSA tire safety standards shape US product certification requirements for extended mobility performance, while EU REACH regulations govern chemical composition limits in rubber and polymer formulations. Germany's KBA enforces type-approval protocols that determine market access for aftermarket inserts across European member states. ISO 16992 provides international test benchmarks for run-flat system durability that manufacturers must satisfy for OEM qualification. Stakeholders should monitor how evolving defense procurement specifications and emissions-linked material restrictions will reshape supplier qualification criteria and production geography.
Market Dynamics
Military procurement offices are consolidating supplier qualification around zero-pressure mobility systems, compressing vendor lists and elevating technical certification barriers for run-flat insert manufacturers serving defense and heavy commercial fleets.
Growth Catalysts
- NHTSA Extended Mobility Standards:Tightening US federal performance requirements for tire systems under loss-of-pressure conditions are mandating run-flat capability in new federal vehicle acquisitions, expanding addressable demand for certified insert suppliers.
- Defense Fleet Modernization:NATO member defense ministries are embedding run-flat specifications into armored vehicle replacement programs, with Germany's KBA type-approval protocols creating reference standards adopted across European procurement frameworks.
- Polymer Composite Maturation:Advanced fiber-reinforced elastomer formulations are achieving weight parity with conventional rubber while delivering superior thermal dissipation, enabling penetration into weight-sensitive commercial truck segments previously closed to insert systems.
Market Restraints
- Raw Material Concentration:High-tensile aramid fiber supply concentrates among a limited set of specialty chemical producers, exposing insert manufacturers to input cost volatility and allocation risk during defense procurement surges.
- Technical Compatibility Limits:Run-flat inserts impose maximum speed and distance constraints that disqualify their use in long-haul highway applications, capping addressable market share against self-supporting tire alternatives.
- REACH Compliance Burden:EU chemical registration requirements for rubber compound additives extend product development timelines and elevate formulation costs for manufacturers seeking European aftermarket access.
Strategic Opportunities
- Telematics Integration:Smart inserts embedding pressure sensors and RFID tracking are converging with fleet management platforms, creating recurring data-service revenue streams beyond hardware sales.
- Indian Defense Indigenization:India's PLI scheme for automotive components and defense procurement localization mandates are opening qualification pathways for domestic insert manufacturing capacity serving armored vehicle programs.
- Retrofit Channel Expansion:Municipal emergency services and cash-constrained defense operators are adopting insert retrofit kits to extend existing tire inventories, bypassing full wheel assembly replacement costs.
Industry Challenges
- ISO 16992 Certification Timelines:Extended durability testing protocols for run-flat system qualification create 18-24 month product validation cycles that strain R&D budgets and delay revenue recognition.
- Integration Complexity:Insert systems require precise rim dimension matching and mounting equipment calibration, generating field installation failures and warranty disputes when service networks lack specialized training.
- Patent Thickets:Overlapping intellectual property claims on polymer composite layup geometries and bead-lock mechanisms are forcing licensing negotiations that erode margin structures for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Run Flat Tire Inserts Market |
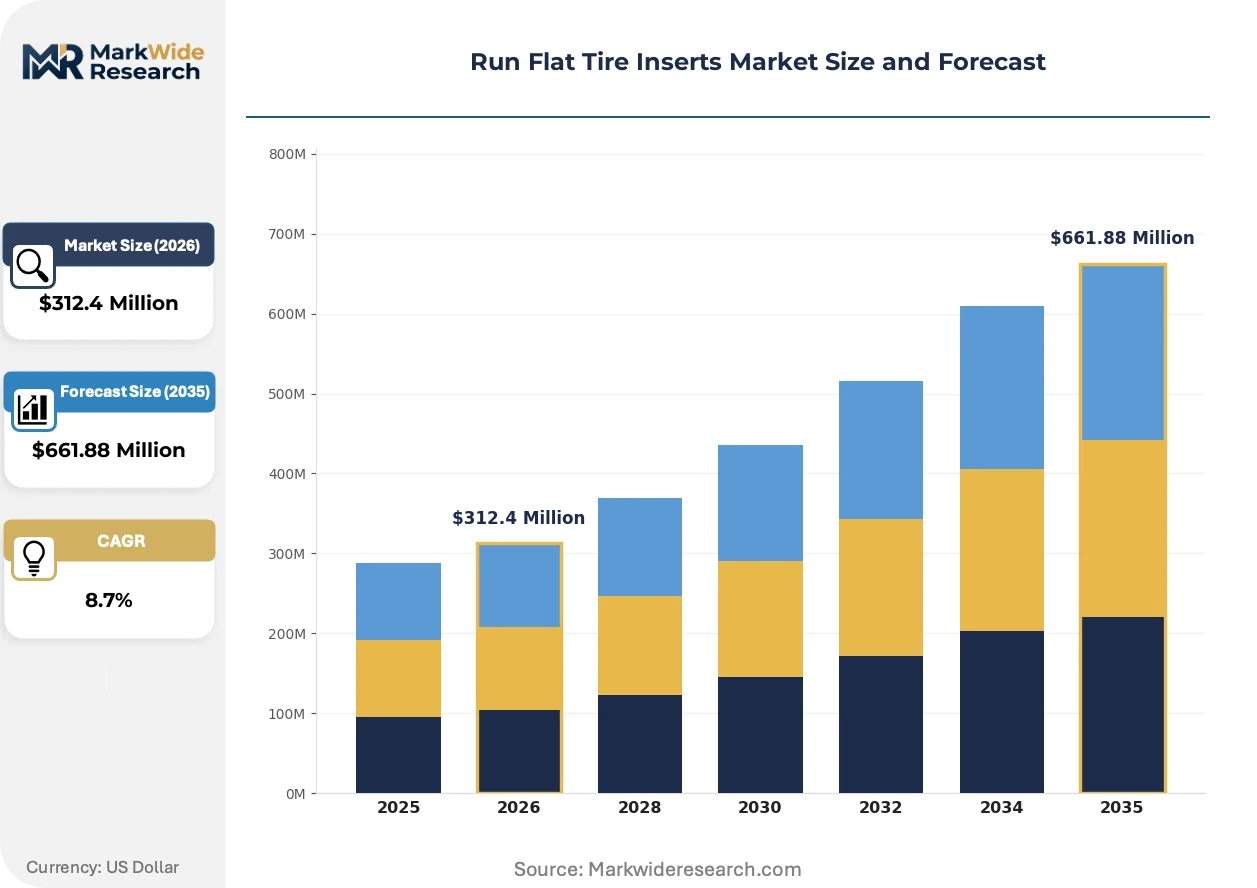
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-supporting Inserts, Airless Inserts, Reinforced Inserts, Smart Inserts Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Vehicles Material: Rubber, Polymer, Foam, Composite Distribution Channel: Online Retail, Auto Parts Stores, OEMs, Distributors |
| Companies Covered | Bulldog Direct Protective Systems, Hutchinson Industries, TAC Run Flat Tire Systems, Briscoe Technologies, Terra Track, RODGARD, Pirelli & C. S.p.A., Mas Makina, RunFlat International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Run Flat Tire Inserts Market Evolving Landscape
Active materials science and embedded sensor architectures are displacing passive mechanical designs across the run-flat insert category, redefining performance benchmarks and supplier capability requirements.
Carbon-fiber-reinforced thermoplastic elastomer cores are rewriting load-bearing efficiency standards for heavy-duty applications. Defense contractors in Germany and the United States are specifying these materials for next-generation tactical vehicle programs. The technology is compressing the performance gap between insert systems and full self-supporting run-flat tires.
EU REACH chemical restriction schedules are accelerating reformulation investments across rubber compound supply chains. Manufacturers must substitute legacy plasticizers and vulcanization accelerators ahead of sunset dates. Aftermarket distributors in European member states are consolidating supplier relationships around REACH-compliant product lines to preempt inventory obsolescence.
Fleet operators are unbundling tire lifecycle management from vehicle procurement contracts, creating standalone service agreements for mobility continuity systems. Third-party fleet management providers are displacing OEM service networks as the primary channel for insert specification and installation. This pattern concentrates in German commercial logistics clusters where total-cost-of-ownership analytics dominate procurement decisions.
Run Flat Tire Inserts Market Segmentation
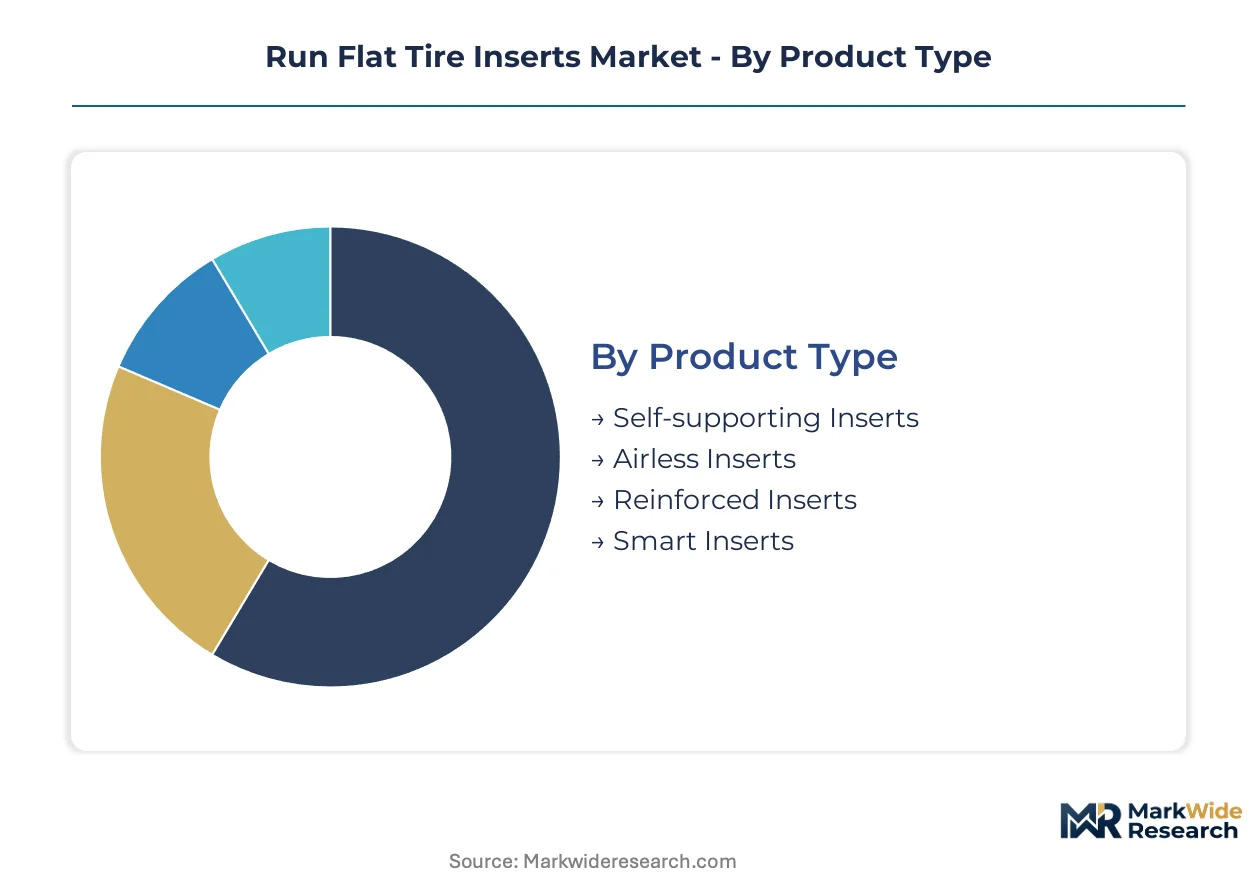
Run flat tire inserts serve divergent mobility requirements across defense, commercial logistics, and consumer vehicle fleets. Segment boundaries reflect fundamental trade-offs between retrofit flexibility and integrated performance. Procurement patterns vary sharply by whether inserts deploy as aftermarket add-ons or OEM-specified systems.
Product Type:
Standalone insert systems dominate military retrofit programs where wheel assembly replacement proves cost-prohibitive. Embedded smart architectures are penetrating new vehicle specifications as telematics integration becomes mandatory for fleet operators.
- Self-supporting Inserts:Compression-molded high-tensile rubber rings that bear full vehicle weight at zero inflation pressure. NATO armored vehicle programs in Germany specify these for tactical fleet continuity requirements. Load-bearing capacity exceeds 4,000 kg per wheel assembly in heavy-duty configurations.
- Smart Inserts:Elastomeric cores embedding pressure sensors and RFID tracking modules for real-time fleet monitoring. Municipal emergency services in the United States are specifying these for ambulance and fire apparatus retrofits. Data-service revenue streams extend hardware margins through recurring telemetry subscriptions.
- Airless Inserts:Cellular polymer structures eliminating pneumatic dependency entirely. Mining haul trucks in Australia deploy these for puncture-prone off-highway environments.
- Reinforced Inserts:Aramid-fiber-strengthened rings for extreme load conditions. Heavy construction equipment in Canada utilizes these for gravel-hauling operations.
Self-supporting inserts lead volumes today; smart inserts are gaining share fastest.
Application:
Defense procurement concentrates on heavy-duty platforms where mobility continuity carries mission-critical weight. Commercial logistics operators balance insert costs against downtime avoidance in regional distribution networks.
- Heavy-Duty Vehicles:Armored personnel carriers and tactical trucks requiring zero-pressure mobility over 50+ kilometer evacuation distances. Germany's KBA type-approval protocols govern European defense specifications. Thermal dissipation requirements intensify as gross vehicle weights exceed 15 metric tons.
- Commercial Vehicles:Regional delivery trucks and urban freight carriers prioritizing schedule reliability over maximum speed capability. Last-mile operators in the United States are retrofitting existing fleets to bypass full tire replacement costs.
- Passenger Vehicles:VIP transport and diplomatic security details specifying discrete protection layers. Armored sedan conversions in Brazil utilize low-profile insert configurations.
- Motorcycles:Military scout and courier applications where single-wheel failure proves catastrophic. Special operations units in the United Kingdom specify these for desert patrol configurations.
Heavy-duty vehicles anchor current procurement volumes; commercial vehicles show the steepest expansion trajectory.
Material:
Weight reduction imperatives are displacing conventional rubber formulations in applications where unsprung mass directly impacts fuel efficiency. Thermal stability requirements favor polymer composites in sustained high-speed operations.
- Polymer:Fiber-reinforced elastomer formulations achieving weight parity with rubber while delivering superior heat dissipation. Commercial truck segments previously closed to insert systems are opening as weight penalties diminish.
- Composite:Carbon-fiber-reinforced thermoplastic cores specified for next-generation tactical vehicle programs. Defense contractors in Germany and the United States are rewriting load-bearing efficiency standards through these materials.
- Rubber:Conventional high-tensile compounds with established compression molding infrastructure. Aftermarket distributors maintain inventory depth around these proven formulations.
- Foam:Cellular polyurethane structures for lightweight auxiliary vehicles. Golf course maintenance fleets in Japan utilize these for puncture protection without speed-rated performance requirements.
Polymer leads installed base volumes; composite materials are climbing the fastest.
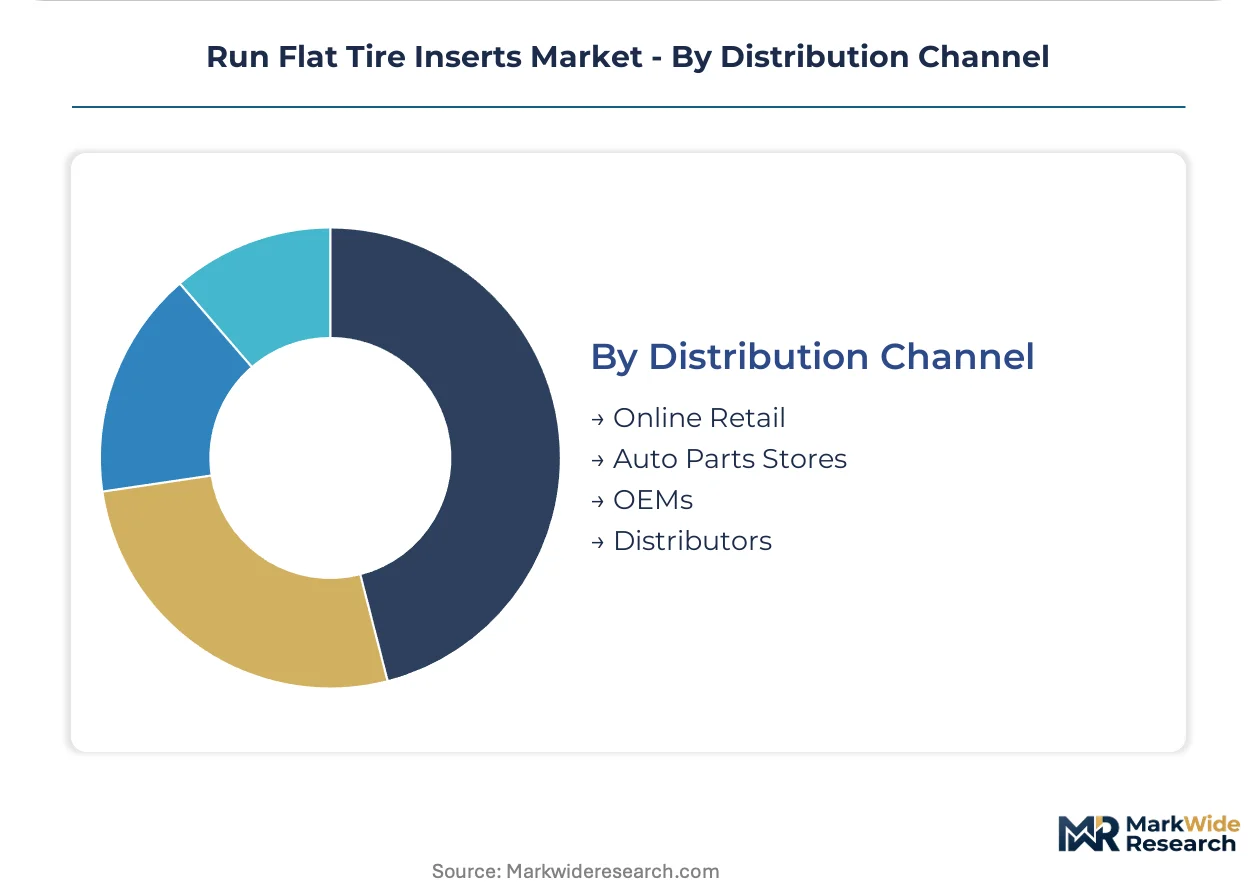
Distribution Channel:
Channel selection determines installation quality assurance and warranty coverage terms. OEM relationships lock in specification authority for new vehicle platforms while aftermarket channels serve retrofit demand.
- OEMs:Original equipment manufacturers embedding insert specifications into new vehicle build configurations. Defense procurement offices consolidate supplier qualification around zero-pressure mobility systems through these channels.
- Distributors:Specialized commercial vehicle parts networks with mounting equipment and technician certification programs. Regional logistics clusters in Germany concentrate procurement through these intermediaries.
- Auto Parts Stores:Retail counter sales for consumer and light commercial retrofit applications. Installation guidance variability creates field failure risks in this channel.
- Online Retail:Direct-to-fleet procurement platforms with specification tools and volume pricing. Municipal emergency services consolidate purchasing through these channels for standardization across dispersed vehicle pools.
OEMs dominate value capture today; distributor networks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as REACH compliance costs in Europe push compound formulation investments toward jurisdictions with lighter chemical registration burdens. Manufacturers are relocating compounding capacity to exploit these cost-of-compliance gaps while maintaining European market access through finished goods imports.
United States
NHTSA extended mobility standards are mandating run-flat capability for federal vehicle acquisitions, expanding certified insert demand. Defense procurement offices consolidate supplier qualification around zero-pressure mobility systems for tactical fleets. Detroit-area automotive clusters anchor commercial retrofit programs for regional logistics operators.
Germany
KBA type-approval protocols govern European defense specifications and create reference standards adopted across NATO procurement frameworks. EU REACH chemical restrictions are accelerating reformulation investments in rubber compound supply chains. Stuttgart and Munich automotive corridors concentrate OEM specification authority for new vehicle platforms.
China
MIIT industrial standards for automotive safety components are tightening performance requirements for extended mobility products. Domestic mining haul truck operators deploy airless inserts for puncture-prone off-highway environments. Yangtze River Delta manufacturing clusters host compression molding capacity serving regional commercial vehicle demand.
India
PLI scheme incentives for automotive components and defense procurement localization mandates are opening qualification pathways for domestic insert manufacturing. BIS certification requirements for automotive safety parts shape product development timelines. Tamil Nadu and Maharashtra industrial corridors concentrate emerging fabrication capacity for armored vehicle programs.
United Kingdom
Special operations procurement specifications for military scout and courier applications sustain demand for motorcycle run-flat configurations. The country's national automotive regulator enforces type-approval alignment with EU technical standards post-Brexit. Midlands defense engineering clusters maintain retrofit service networks for NATO-compatible vehicle pools.
Run Flat Tire Inserts Market Competitive Landscape
Strategic partnerships dominate the current landscape as tiered supplier networks form around defense procurement consolidation. The vendor base organizes into three distinct tiers: integrated polymer compounders with captive raw material supply, specialized insert fabricators focused on military qualification, and regional retrofit service providers. Technology licensing and capacity expansion represent the primary competitive vectors as manufacturers seek ISO 16992 certification breadth.
Among defense-specialized fabricators, Hutchinson Industries and RunFlat International occupy positions within the military qualification tier, while Pirelli & C. S.p.A. exemplifies the diversified compounder archetype spanning civilian and defense channels. These anchors reflect the market's bifurcation between pure-play defense suppliers and multi-segment polymer engineers.
| Leading Market Players |
|---|
| Bulldog Direct Protective Systems |
| Hutchinson Industries |
| TAC Run Flat Tire Systems |
| Briscoe Technologies |
| Terra Track |
| RODGARD |
| Pirelli & C. S.p.A. |
| Mas Makina |
| RunFlat International |
| Others |
Value Network & Pricing Analysis
Carbon-fiber-reinforced thermoplastic elastomer cores are compressing unit economics while concentrating production capability among compounders with captive polymer formulation expertise. This material transition simultaneously elevates certification costs for tier-two fabricators and rewards integrated manufacturers with pricing power in defense procurement channels.
Pricing Analysis
Distributor margin layers absorb 15-25 points between compounder and fleet operator in European aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 16992 certification grade and aramid fiber content. Cost compression in standard-grade rubber formulations is intensifying because REACH-compliant additive substitutes carry 12-18 percent raw material premia. Municipal emergency services exhibit highest price sensitivity due to budget-cycle constraints; NATO defense procurement offices show lowest sensitivity given mission-critical mobility requirements.
Supply Chain Analysis
Aramid fiber supply rests on specialty chemical producers in the United States, Germany, and Japan, with limited qualified alternative sources for defense-grade specifications. High-tensile rubber compound production draws from petrochemical feedstocks and carbon black suppliers concentrated in the Yangtze River Delta and Gulf Coast corridors. Single-source vulnerability in aramid fiber allocation creates procurement risk during defense modernization surges. Distribution runs through OEM specification channels for new vehicle platforms and specialized distributor networks for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Run flat tire inserts function as a stable compounder category anchored by defense procurement cycles with decade-long vehicle replacement horizons and regulatory mandates that embed supplier relationships.
For Market Incumbents: Anticipate margin compression from polymer composite maturation by securing backward integration into carbon-fiber-reinforced thermoplastic compounding capacity in Germany or the United States. Prioritize ISO 16992 certification breadth across smart insert architectures to preempt emerging entrants from qualifying for NATO procurement frameworks. Channel control through exclusive distributor relationships in regional logistics clusters offers defensive positioning against price erosion. For New Entrants and Emerging Players: Begin with municipal emergency services retrofit channels in the United States, where specification authority fragments across dispersed vehicle pools and installation service gaps create entry points. Target India's PLI scheme incentives for domestic armored vehicle component manufacturing, leveraging localization mandates to bypass established European supplier relationships. A direct-to-fleet online retail go-to-market angle with volume pricing tools can displace legacy distributor margins in cash-constrained public sector segments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier rubber compounders lacking smart insert telemetry capabilities but holding defense qualification relationships. The five-to-ten year viability window favors compounders with demonstrated KBA type-approval success and established aramid fiber supply agreements. Acquisition target archetype: European aftermarket distributors with REACH-compliant inventory depth and technician certification infrastructure. The signal to watch is India's defense procurement localization enforcement intensity as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive carbon-fiber-reinforced thermoplastic capacity secures margin pools from specialty chemical suppliers. |
| Smart Insert Telemetry Platform Development | Embedded pressure sensors and RFID modules create recurring data-service revenue beyond hardware sales. |
| ISO 16992 Certification Expansion | Broad qualification scope locks out emerging competitors from NATO defense procurement frameworks. |
| India Manufacturing Footprint Establishment | PLI scheme incentives and localization mandates open qualification pathways for armored vehicle programs. |
| REACH-Compliant Formulation Transition | Preemptive additive substitution ahead of sunset dates prevents European inventory obsolescence risk. |
Research Methodology
Coverage spans the United States, Germany, China, India, and the United Kingdom, with primary inputs from each market. Defense procurement officers, Tier 1 automotive supplier executives, fleet maintenance directors, and aftermarket distributor principals provided qualitative demand and specification intelligence. Secondary validation drew from NHTSA regulatory filings, KBA type-approval registers, EU REACH restriction schedules, and MIIT industrial standard notifications. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Rate-of-change decomposition across product type, application, material, and distribution channel dimensions shaped volume and value projections. CAGRs were derived from segment-level growth rate blending weighted by current procurement volumes. Defense fleet modernization timelines, commercial logistics fleet replacement cycles, and polymer composite adoption curves served as industry-specific forecast inputs throughout the modeling period.
Caveats apply where defense procurement budget reallocations or accelerated REACH chemical restriction schedules could materially shift the outlook. Forecasts reflect assumptions around aramid fiber supply availability and ISO 16992 certification timeline stability. A small set of triggers—India PLI enforcement intensity, NATO armored vehicle program acceleration, and smart insert telematics standardization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Performance Tires Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
Automotive All-Season Tire Market
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
Agricultural Tires Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Global Bead Wire (Tyre Bead Wire) Market