
 Global Automotive Tires Market | 2026-2036
Global Automotive Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Tires Market Analysis
Southeast Asia is fragmenting as Thailand and Indonesia add radial tire capacity to serve Japanese and Korean automaker supply chains. Bridgestone Corporation leverages its integrated rubber plantation network to stabilize raw material costs across ASEAN manufacturing hubs. Michelin Group sustains premium positioning through sustained R&D allocation toward airless tire architectures. Goodyear Tire & Rubber Company anchors North American replacement demand via controlled wholesale distributor relationships with national fleet operators.
Automotive tires are composite structures comprising rubber compounds reinforced with steel belts, textile plies, and silica-loaded tread formulations manufactured through calendering, extrusion, and vulcanization processes designed to transmit vehicle loads, absorb road irregularities, and maintain traction across temperature and friction variations. Radial tires dominate volume economics due to lower rolling resistance and extended tread life, while run-flat configurations command margin premiums in premium passenger car and SUV fitments where mobility-after-puncture functionality reduces roadside assistance dependency. All-season tires occupy the broadest replacement channel footprint, though winter tire regulations in specific northern climates sustain seasonal demand spikes.
EPA fuel economy standards and NHTSA safety ratings in the United States compel manufacturers to reduce rolling resistance coefficients, while EU REACH restrictions on aromatic oils and ECHA-classified substances constrain compound formulation flexibility across European supply chains. China's GB standards and MIIT energy consumption regulations enforce domestic labeling requirements that segment products by efficiency grade. Stakeholders must monitor how evolving multi-jurisdictional labeling regimes alter procurement criteria for original equipment manufacturers and fleet buyers.
Market Dynamics
Radial tire manufacturing capacity is concentrating in Southeast Asian production clusters as Japanese and Korean automakers localize supply chains, compressing lead times for original equipment fitments while reshaping competitive positioning among compound suppliers.
Growth Catalysts
- EU REACH compliance mandates:Sustainable compound formulations incorporating bio-based oils and silica-loaded treads are gaining preference among European fleet procurement officers seeking regulatory alignment.
- Commercial vehicle fleet expansion:Logistics corridors across India and Brazil are scaling original equipment tire volumes as domestic automotive production accelerates.
- Run-flat tire technology:Premium passenger car and SUV segments are absorbing mobility-after-puncture configurations that reduce roadside assistance dependency.
Market Restraints
- Natural rubber price volatility:Plantation yield fluctuations across Thailand and Indonesia transmit cost instability into compound manufacturing economics.
- EU F-Gas Regulation constraints:Refrigerant and processing gas restrictions are limiting vulcanization process flexibility for European production facilities.
- Steel cord supply concentration:Metallurgical input dependence on specific East Asian steel producers creates vulnerability in belt reinforcement sourcing.
Strategic Opportunities
- India domestic production scaling:Automotive manufacturing clusters in Pune and Chennai present underpenetrated demand for radial tire localization.
- Airless tire architecture convergence:R&D allocation toward non-pneumatic structures intersects with fleet operator total cost of ownership reduction objectives.
- China MIIT efficiency labeling:Domestic energy consumption grade segmentation creates procurement criteria differentiation for tier-1 suppliers.
Industry Challenges
- Compound formulation certification timelines:ECHA substance evaluation procedures extend new material approval cycles beyond product development windows.
- Vulcanization equipment capex intensity:Press modernization requirements for reduced rolling resistance specifications demand capital redeployment from smaller manufacturers.
- Multi-jurisdictional labeling integration:Reconciling EPA fuel economy coefficients with EU tire labeling and China GB standards strains product portfolio complexity management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Tires Market |
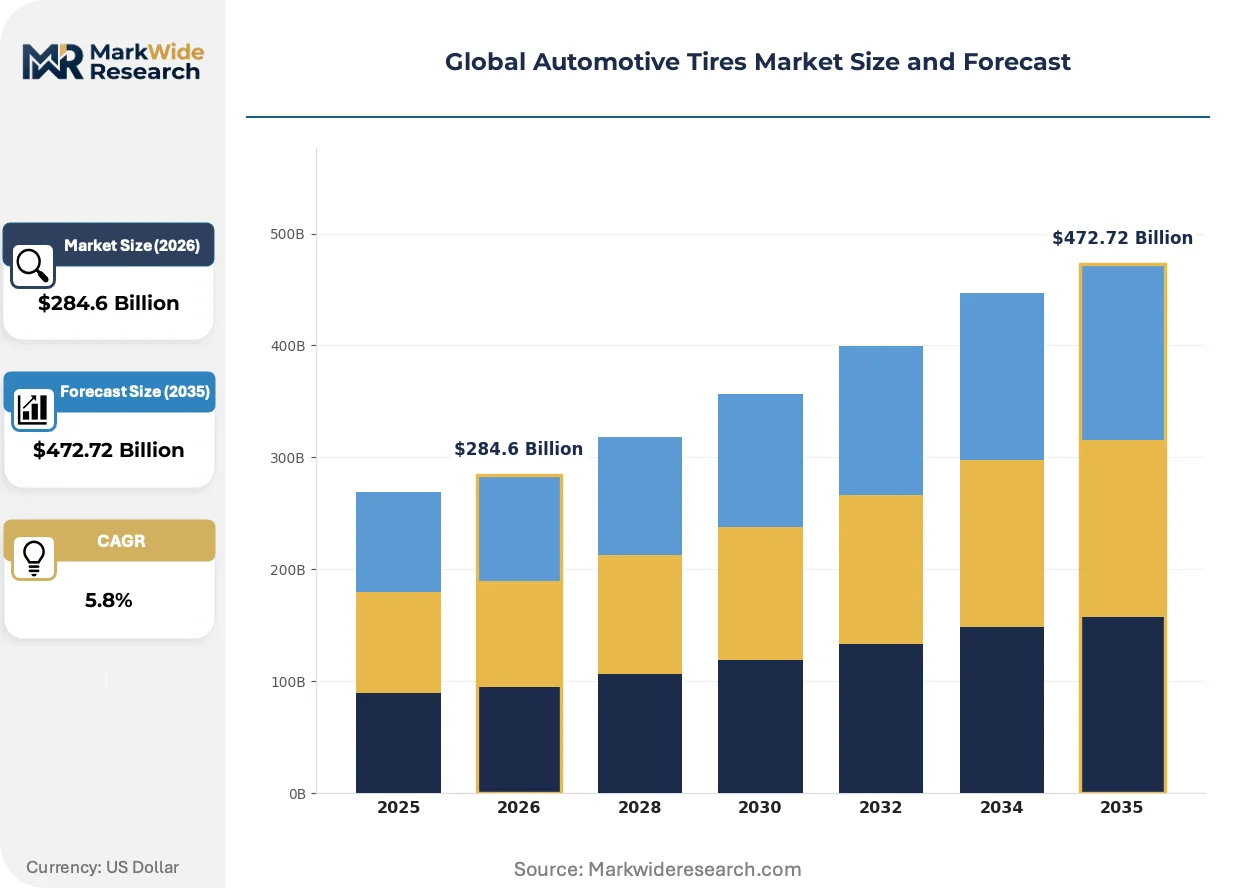
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $472.72 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Winter Tires, Summer Tires, All-Season Tires, Performance Tires Vehicle Type: Passenger Cars, Light Trucks, SUVs, Commercial Vehicles Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Service Stations Tire Technology: Radial Tires, Bias Tires, Solid Tires, Run-Flat Tires |
| Companies Covered | Bridgestone Corporation, Michelin Group, Goodyear Tire & Rubber Company, Continental AG, Pirelli & C. S.p.A., Sumitomo Rubber Industries, Hankook Tire & Technology, Yokohama Rubber, ZC Rubber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Tires Market Emerging Trajectories
Material science advances and regulatory labeling convergence are compressing product development cycles while fragmenting procurement criteria across regional compliance regimes.
Silica-silane coupling systems are replacing carbon black as the dominant tread reinforcement mechanism, delivering reduced rolling resistance coefficients without sacrificing wet grip performance. Tier-1 original equipment manufacturers are specifying these compounds in platform development programs. Conventional high-aromatic oil formulations are rendering obsolete across European supply chains as REACH restrictions harden.
EPA fuel economy standards and NHTSA safety ratings in the United States are tightening rolling resistance coefficient ceilings for passenger vehicle fitments. Tire manufacturers must recalibrate compound recipes and belt architectures to maintain traction ratings while meeting Corporate Average Fuel Economy compliance pathways. Light truck and SUV segments face the steepest redesign requirements as footprint-based standards intensify.
Fleet operators are consolidating tire procurement through national distributor relationships with embedded lifecycle cost analytics replacing unit price negotiation. Direct manufacturer-to-fleet contracts are displacing fragmented wholesale channel purchasing in North American commercial vehicle segments. Large logistics operators with centralized maintenance facilities are capturing this shift most aggressively.
Global Automotive Tires Market Segmentation
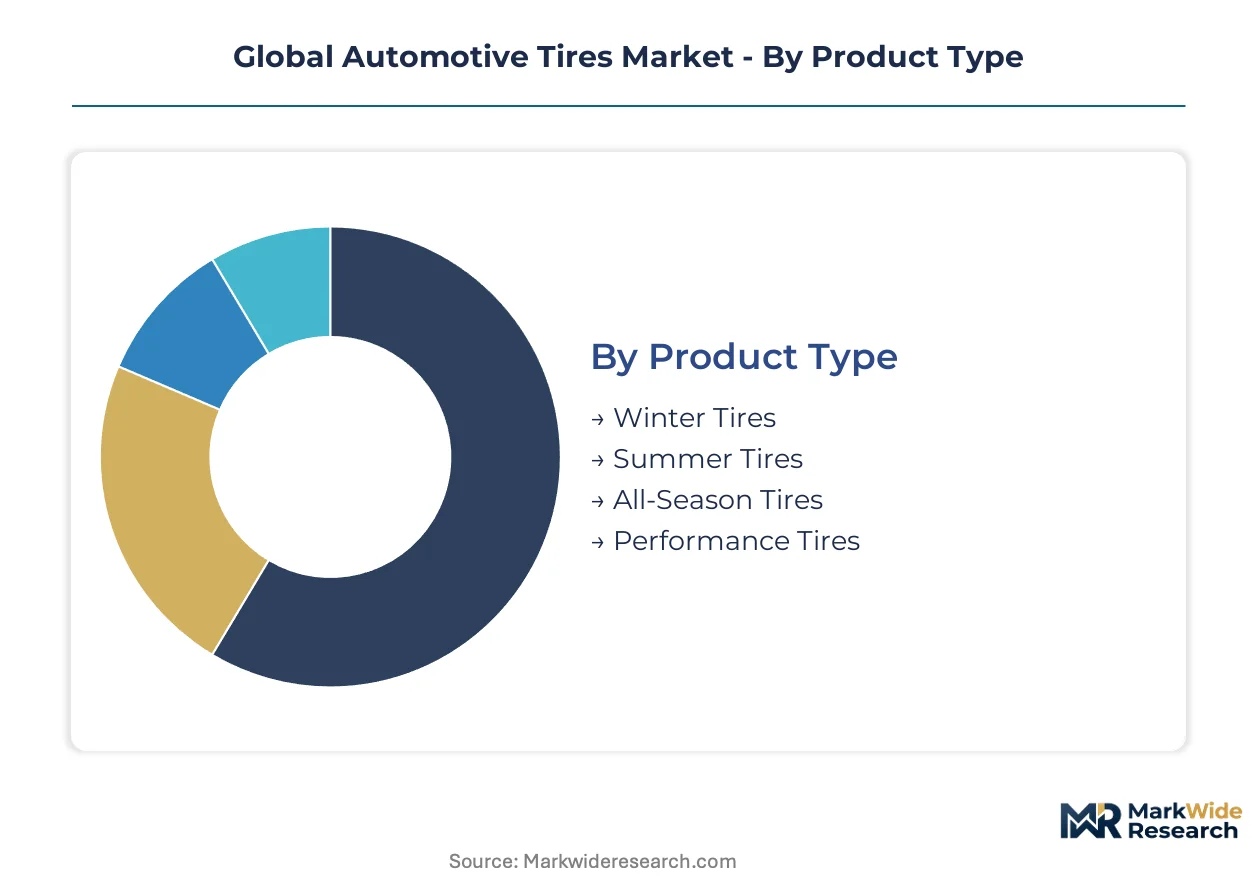
Product differentiation across automotive tires follows replacement cycle velocity, with seasonal and performance variants commanding premium positioning against commoditized all-season volumes. Fleet procurement criteria and regulatory labeling regimes fragment demand across technical specifications and distribution channels.
Product Type:
Replacement cycles compress toward seasonal specialists while all-season variants extend service intervals through multi-climate tolerance.
- Winter Tires:Specialized tread compounds incorporating natural rubber blends and siped patterns maintain elasticity below 7°C. Nordic countries and alpine regions mandate fitment during designated months, creating concentrated procurement spikes. Regulatory frameworks in Germany and Canada enforce seasonal compliance.
- Summer Tires:Asymmetric tread blocks and silica-loaded compounds optimize dry and wet grip in temperate conditions. Southern European and Southeast Asian markets concentrate demand where winter temperature thresholds rarely trigger mandatory seasonal swaps.
- All-Season Tires:M+S rated tread patterns compromise extreme performance for year-round convenience across moderate climates.
- Performance Tires:Ultra-high-speed ratings and reinforced sidewalls serve sports car and premium sedan fitments.
All-season tires dominate installed base. Winter tires are where expansion concentrates.
Vehicle Type:
Load rating requirements and duty cycle intensity separate commercial applications from passenger vehicle replacement economics.
- Commercial Vehicles:Multi-axle configurations and retread-compatible casings prioritize total cost of ownership over unit acquisition price. Logistics corridors across India and Brazil scale fleet procurement through centralized maintenance contracts.
- SUVs:Higher center-of-gravity dynamics and all-terrain capability specifications drive reinforced sidewall constructions and aggressive tread patterns. North American and Middle Eastern markets concentrate fitment volumes.
- Passenger Cars:Rolling resistance optimization dominates OEM specification criteria under EPA and EU labeling regimes.
- Light Trucks:Dual-purpose highway and worksite duty cycles demand hybrid tread compounds balancing wear resistance with load capacity.
Passenger cars dominate installed base. Commercial vehicles are where expansion concentrates.
Distribution Channel:
Channel economics separate high-touch installation requirements from transactional replacement purchasing.
- Wholesale Distributors:National fleet contracts and volume pricing tiers consolidate procurement for commercial vehicle operators. North American logistics networks embed lifecycle cost analytics into distributor relationships.
- Specialty Stores:Technical consultation and alignment services capture premium passenger tire replacement. European independent dealers maintain positioning through brand-exclusive fitment expertise.
- Service Stations:Convenience-driven replacement at fuel and maintenance touchpoints captures emergency and unplanned demand.
- Online Retail:Price transparency and direct-to-consumer logistics reshape commoditized segment purchasing.
Wholesale distributors dominate installed base. Online retail is where expansion concentrates.
Tire Technology:
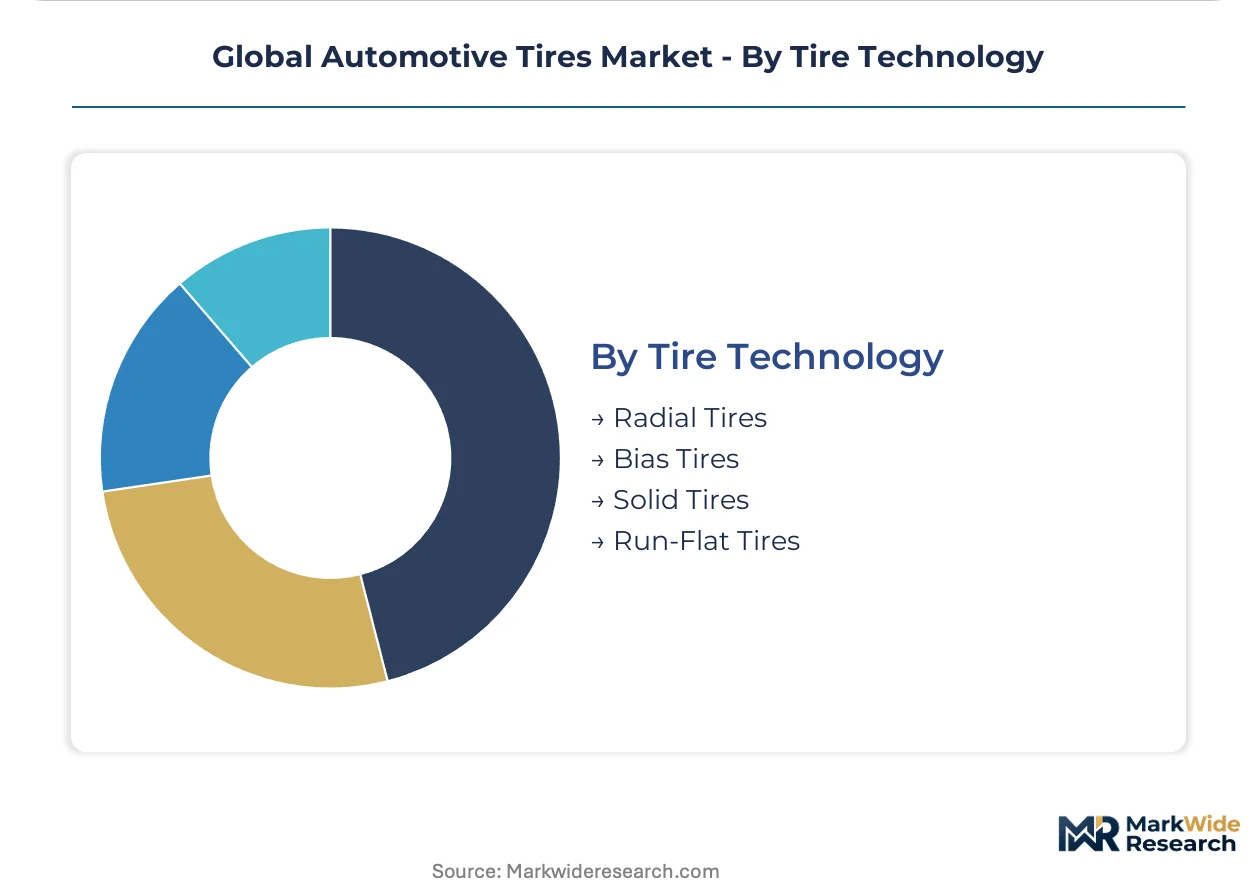
Manufacturing process differentiation separates molded-cord radial constructions from legacy bias-ply and solid alternatives.
- Radial Tires:Perpendicular cord plies and stabilizer belts reduce rolling resistance and extend tread life through uniform ground contact. Southeast Asian production clusters concentrate capacity to serve Japanese and Korean automaker supply chains.
- Run-Flat Tires:Reinforced sidewall structures and bead retention systems enable limited mobility after pressure loss. Premium passenger car and SUV segments absorb mobility-after-puncture functionality that reduces roadside assistance dependency.
- Bias Tires:Cross-ply cord angles suit low-speed agricultural and industrial applications with minimal highway exposure.
- Solid Tires:Molded rubber compounds eliminate pneumatic pressure maintenance for material handling and construction equipment.
Radial tires dominate installed base. Run-flat tires are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radial tire manufacturing capacity clusters in Thailand and Indonesia serve Japanese and Korean automaker supply chains. Compound suppliers face reformulation pressures from EU REACH and China MIIT regulations simultaneously. Fleet procurement in India and Brazil scales through centralized maintenance contracts.
United States
Commercial vehicle fleet operators consolidate procurement through national distributor relationships with embedded lifecycle cost analytics. EPA fuel economy standards and NHTSA safety ratings tighten rolling resistance coefficient ceilings for passenger fitments. Southeast manufacturing corridors in South Carolina and Tennessee anchor radial production for domestic OEM supply.
Germany
Premium passenger car and SUV segments absorb run-flat configurations that reduce roadside assistance dependency. EU REACH restrictions on aromatic oils and ECHA-classified substances constrain compound formulation flexibility. Industrial clusters in Baden-Württemberg and Lower Saxony concentrate R&D allocation toward airless tire architectures.
China
Domestic automotive production scaling in Yangtze River Delta and Pearl River Delta corridors drives radial tire localization demand. MIIT energy consumption regulations enforce labeling requirements that segment products by efficiency grade. GB standards compliance shapes procurement criteria for tier-1 suppliers serving state-owned automakers.
India
Logistics corridors across Maharashtra and Tamil Nadu scale original equipment tire volumes as domestic automotive production accelerates. BIS certification requirements and PLI scheme incentives shape localization decisions for compound manufacturers. Pune and Chennai manufacturing clusters present underpenetrated demand for radial tire capacity expansion.
Brazil
Commercial vehicle fleet expansion across São Paulo and Minas Gerais industrial corridors concentrates procurement through centralized maintenance contracts. ANVISA regulatory alignment with international compound safety standards affects import substitution dynamics. Domestic production scaling reduces lead times for South American distribution networks.
Global Automotive Tires Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in compound and reinforcement supply. The market structure concentrates among integrated manufacturers with captive rubber sourcing and regional production networks. Three archetypes dominate: plantation-integrated compounders stabilizing raw material costs, R&D-intensive architects of airless structures, and distributor-anchored fleet service providers. Competitive moves center on Southeast Asian capacity expansion and strategic partnerships for run-flat technology licensing.
Within the plantation-integrated tier, Bridgestone Corporation and Michelin Group exemplify upstream control over natural rubber supply chains. Among distributor-anchored operators, Goodyear Tire & Rubber Company occupies a position linking national fleet contracts to replacement channel economics. These three entities represent distinct strategic postures: backward integration into agricultural inputs, sustained premium positioning through architecture innovation, and controlled wholesale relationships capturing commercial vehicle procurement consolidation.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin Group |
| Goodyear Tire & Rubber Company |
| Continental AG |
| Pirelli & C. S.p.A. |
| Sumitomo Rubber Industries |
| Hankook Tire & Technology |
| Yokohama Rubber |
| ZC Rubber |
| Others |
Supply Flow & Price Mechanics
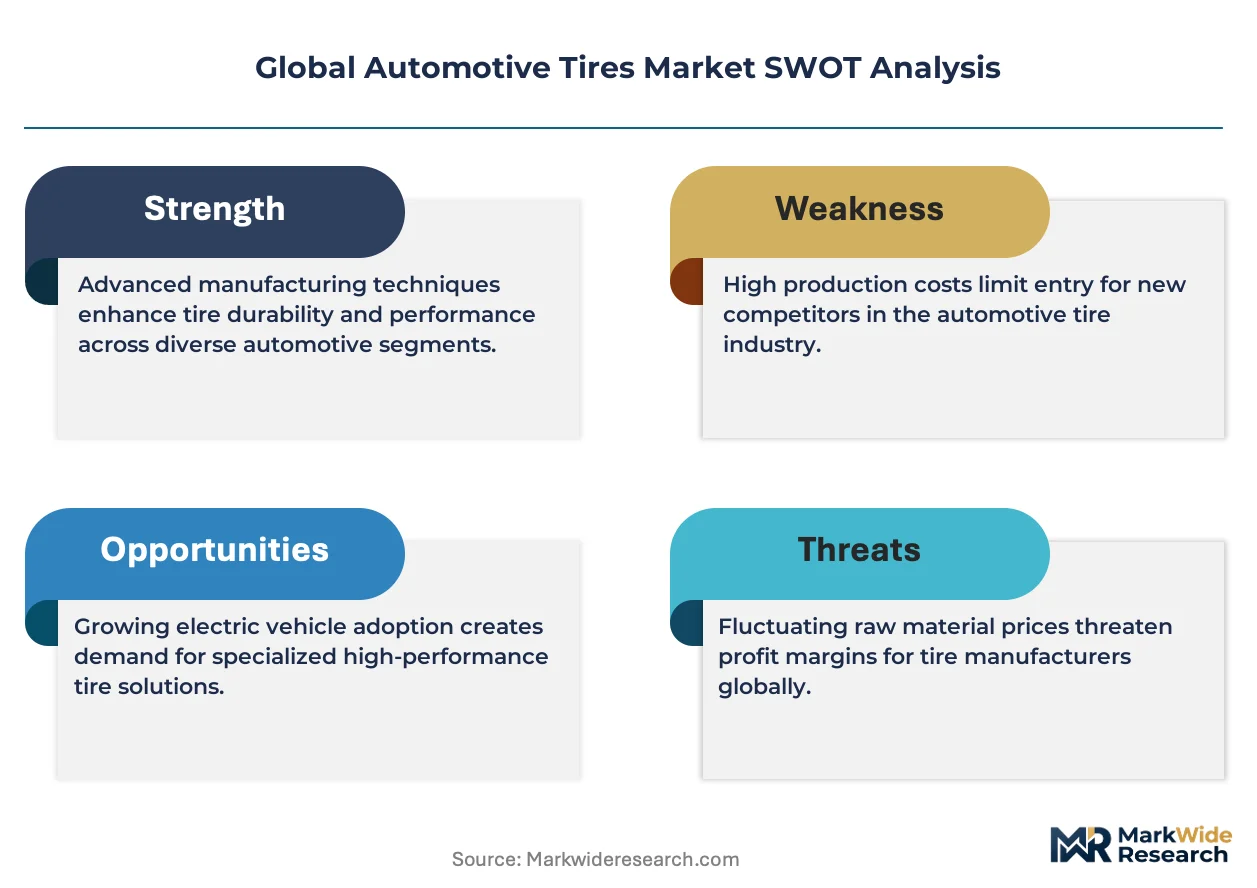
Natural rubber price volatility across Thai and Indonesian plantations dictates both the spread between premium and economy tire tiers and the geographic clustering of vulcanization capacity. Compound manufacturers facing feedstock instability compress margin structures at the low end while plantation-integrated producers capture pricing power through captive supply security.
Pricing Analysis
EU REACH compliance mandates dictate the pricing tier structure across European supply chains, with aromatic oil restrictions forcing reformulation investments that stratify products across premium, standard, and economy levels. Price differentiation rests on certification grade and brand premium, with ECHA-classified substance clearance separating premium compound suppliers from commodity producers. Cost compression in economy tiers is intensifying because of natural rubber feedstock instability, while fleet procurement officers demonstrate lowest price sensitivity due to total cost of ownership analytics embedded in distributor contracts.
Supply Chain Analysis
Export-control restrictions on advanced vulcanization press technology limit equipment flows into emerging manufacturing hubs, concentrating production capacity among established Southeast Asian and East Asian producers. Geographic supply centers on Thailand, Indonesia, and China, with compound manufacturing drawing from natural rubber plantations, steel cord metallurgy, and silica-loaded tread formulations. Single-source vulnerability in East Asian steel belt reinforcement creates structural exposure, while distribution runs through national wholesale networks consolidating fleet procurement in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around EU REACH and China MIIT certification creates sticky supplier relationships that resist displacement.
For Market Incumbents: Build captive plantation networks to insulate compound costs from Thai and Indonesian yield fluctuations. Anchor distributor relationships with lifecycle cost analytics that embed switching costs for commercial fleet operators. Defend against airless tire architecture substitution through sustained R&D allocation toward non-pneumatic structures. For New Entrants and Emerging Players: Radial tire localization gaps in Pune and Chennai manufacturing clusters represent the most penetrable entry point for compound suppliers serving accelerating domestic automotive production. Online retail channels for commoditized all-season replacement tires offer direct-to-consumer bypass of entrenched wholesale networks. Pursue BIS certification early to qualify for PLI scheme incentives shaping procurement criteria. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors plantation-integrated compounders with captive raw material security. Long-term viability hinges on backward integration depth and regional production network density. Watch for airless tire architecture licensing agreements as inflection signals for technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Plantations | Captive Thai and Indonesian supply stabilizes compound manufacturing economics against feedstock volatility. |
| Airless Tire Architecture R&D | Michelin and Bridgestone patent positions in non-pneumatic structures reshape premium segment competition. |
| EU REACH Compliance Certification | ECHA substance clearance separates premium compound suppliers from reformulation-lagged competitors. |
| Fleet Distributor Consolidation | Goodyear's national contracts embed lifecycle analytics that displace fragmented wholesale purchasing. |
| Southeast Asian Capacity Expansion | Thai and Indonesian radial production clusters compress lead times for Japanese and Korean automaker supply chains. |
Methodological Framework
A standing panel of tire manufacturing plant managers, OEM platform engineers, aftermarket distributor operations heads, and fleet procurement officers provided ongoing calibration across primary fieldwork. Secondary validation drew from vehicle production databases, customs and trade flow records, SEC 10-K filings of listed manufacturers, and IHS Markit registration data. Bottom-up volume modeling and top-down value reconciliation triangulated outputs across the analysis window.
Scenario bracketing anchored the projection framework, with segmentation dimensions spanning vehicle class, tire technology architecture, distribution channel type, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline production volumes and replacement cycle velocity assumptions. Forecast inputs incorporated natural rubber futures pricing trajectories and MIIT efficiency labeling adoption curves.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, logistics freight indices, or plantation yield patterns would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Material shifts in EU F-Gas Regulation implementation or airless tire commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Global Pneumatic Tires Market