
 Global Off-Highway Vehicle Telematics Market | 2026-2036
Global Off-Highway Vehicle Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Off-Highway Vehicle Telematics Market Foresight
Equipment-as-a-service financing and subscription-based telematics leasing is narrowing the competitive field to capitalized platforms that can underwrite hardware upfront. Caterpillar Inc. leverages its dealer network to bundle telematics with extended service contracts, locking in recurring revenue streams. Komatsu Ltd. anchors its KOMTRAX platform through deep integration with hydraulic system diagnostics, creating switching costs for mining operators. Trimble Inc. competes on precision agriculture workflows, extending its GNSS expertise into construction machine control.
Off-highway vehicle telematics encompasses GPS-enabled hardware, cellular or satellite connectivity modules, and cloud-based software platforms that transmit machine location, engine hours, fault codes, and productivity metrics to centralized dashboards. The technology serves primarily to maximize equipment uptime, reduce unplanned maintenance, and enforce operational compliance across dispersed job sites. Construction Equipment dominates current installed base volume due to the segment's high asset values and fragmented contractor ownership, while Predictive Maintenance represents the fastest-expanding technology category as OEMs monetize prognostic algorithms through recurring software licenses. Fleet Optimization applications command the strongest margin pools because they integrate fuel, labor, and scheduling data into unified analytics layers that command premium pricing.
EPA Tier 4 Final and EU Stage V emissions regulations are mandating onboard diagnostics and remote reporting capabilities, forcing telematics penetration into base equipment configurations rather than optional add-ons. Japan's METI energy-efficiency standards and India's CEA construction equipment safety directives are adding compliance layers that favor integrated OEM-supplied systems over aftermarket installations. Stakeholders must evaluate whether to build captive telematics stacks or partner with specialized platform providers as regulatory data-reporting obligations expand beyond emissions into operator safety and carbon accounting.
Market Dynamics
Equipment rental firms are consolidating fleet management under unified telematics platforms, compressing vendor selection cycles and privileging integrated OEM-supplied systems over fragmented aftermarket installations across construction and agricultural operations.
Growth Catalysts
- EPA Tier 4 Final mandates:Onboard diagnostics and remote emissions reporting requirements are embedding telematics hardware as standard equipment in diesel-powered construction and agricultural machinery sold in the United States.
- Predictive maintenance algorithms:Mining operators are subscribing to prognostic software licenses that convert vibration and hydraulic pressure data into failure predictions, reducing unplanned downtime.
- EU Stage V compliance layers:European construction equipment manufacturers must integrate real-time particulate matter monitoring, accelerating factory-fit telematics penetration versus dealer-installed alternatives.
Market Restraints
- Cellular connectivity cost volatility:Satellite and LTE module expenses fluctuate with semiconductor foundry capacity constraints, squeezing hardware margins for platform providers.
- Aftermarket installer concentration:Third-party telematics retrofitting in Brazil and India depends on fragmented local electronics distributors with inconsistent calibration capabilities.
- Legacy fleet incompatibility:Pre-Tier 4 equipment lacks standardized CAN bus architectures, limiting remote diagnostic depth for older hydraulic excavators and wheel loaders.
Strategic Opportunities
- Carbon accounting mandates:The EU CSRD requires Scope 1 emissions disclosure from construction firms, creating demand for telematics platforms that aggregate fuel burn and idle time into audit-ready reports.
- Precision agriculture convergence:GNSS-guided planting and variable-rate fertilization in the US Corn Belt are pulling telematics into unified farm management information systems.
- Equipment-as-a-service financing:Subscription-based telematics leasing allows rental firms to defer hardware capital outlays while locking in recurring software revenue streams.
Industry Challenges
- Telematics-technician shortage:Fleet managers lack personnel trained to interpret fault code hierarchies and hydraulic diagnostic parameters transmitted from remote job sites.
- Cross-platform data standardization:OEMs deploy proprietary data protocols that resist integration with contractor enterprise resource planning systems, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Off-Highway Vehicle Telematics Market |
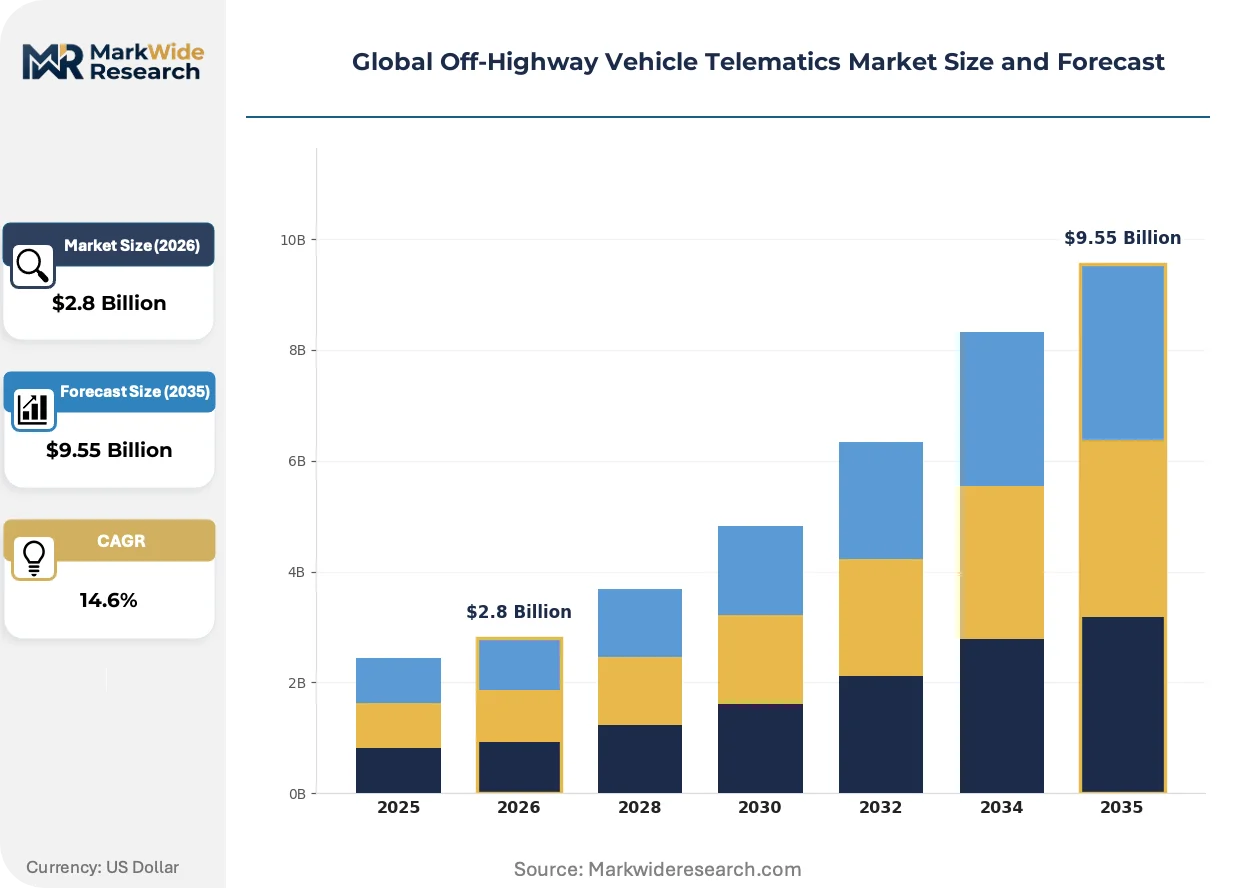
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Construction Equipment, Agricultural Machinery, Mining Equipment, Forestry Vehicles, Material Handling Machines Technology: GPS Tracking, Fleet Management, Remote Diagnostics, Predictive Maintenance, Asset Utilization Monitoring Application: Fleet Optimization, Safety & Security, Fuel Management, Regulatory Compliance, Theft Prevention End User: Contractors, Equipment Rental Firms, Agricultural Producers, Mining Operators, Forestry Companies |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Deere & Company, CNH Industrial N.V., Volvo Construction Equipment AB, Trimble Inc., TomTom International BV, ORBCOMM Inc., Trackunit A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Off-Highway Vehicle Telematics Market Shifts & Advancements
Edge computing architectures and satellite IoT constellations are compressing latency thresholds for off-highway asset monitoring, enabling real-time intervention in remote mining and forestry operations previously beyond cellular coverage.
AI-driven prognostic algorithms are rendering obsolete scheduled maintenance intervals based on engine hours alone. Mining operators in Western Australia now subscribe to condition-based service triggers derived from hydraulic oil particle counts and pump vibration signatures. This compression of maintenance planning cycles is collapsing traditional parts inventory models.
Japan's METI energy-efficiency standards now mandate operational data logging for construction equipment above specified power thresholds. Domestic OEMs must embed telematics modules capable of transmitting fuel consumption and work-mode utilization to centralized registries. This regulatory architecture favors integrated factory-fit systems over aftermarket retrofitting in the Japanese market.
Rental fleet procurement is consolidating around outcome-based utilization guarantees rather than standalone hardware purchases. Major equipment lessors in Germany now specify uptime commitments and fuel-efficiency benchmarks in telematics platform selection criteria. This behavioral shift is compressing vendor qualification timelines and privileging vertically integrated OEM offerings.
Global Off-Highway Vehicle Telematics Market Segmentation
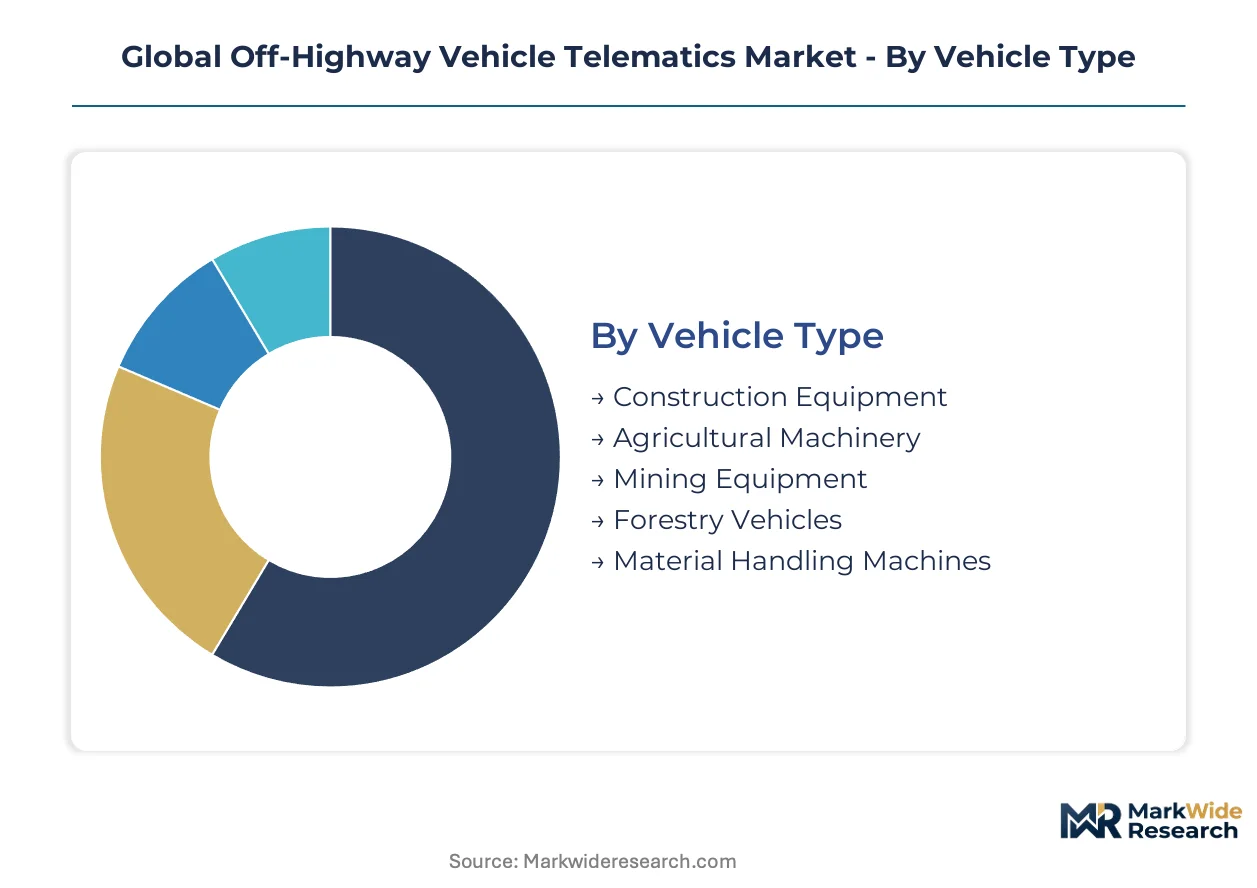
Off-highway telematics vendors configure product roadmaps around four distinct segmentation axes. Vehicle type determines hardware ruggedization requirements and sensor payload. Technology selection governs recurring revenue potential through software licensing tiers.
Vehicle Type:
Construction Equipment commands the shortest replacement cycles among major categories, while Mining Equipment stretches asset life across decades of continuous operation.
- Construction Equipment:Hydraulic excavators, wheel loaders, and motor graders transmit engine hours, fault codes, and idle-time metrics through integrated CAN bus architectures. Fleet managers in the United States deploy these systems to enforce EPA Tier 4 Final emissions reporting across dispersed job sites. High asset values and fragmented contractor ownership concentrate demand here.
- Agricultural Machinery:Tractors and combines integrate GNSS-guided planting data with fuel consumption telemetry. Variable-rate fertilization workflows in the US Corn Belt pull telematics into unified farm management information systems. Precision agriculture convergence accelerates platform adoption.
- Mining Equipment:Ultra-class haul trucks operate in cellular dead zones, requiring satellite IoT backhaul for real-time payload and engine diagnostics.
- Forestry Vehicles:Feller bunchers and forwarders transmit location and productivity data from remote timber harvest zones.
- Material Handling Machines:Forklifts and telehandlers in warehouse yards prioritize theft prevention and operator safety compliance over predictive maintenance depth.
Construction Equipment dominates installed base. Agricultural Machinery is where expansion concentrates.
Technology:
Cost tier separation runs deepest in this category, with predictive maintenance commanding premium subscription rates against commoditized GPS tracking.
- Predictive Maintenance:AI-driven algorithms convert vibration signatures and hydraulic oil particle counts into failure predictions. Mining operators in Western Australia subscribe to condition-based service triggers that collapse traditional parts inventory models. This category captures the steepest expansion trajectory.
- Remote Diagnostics:OEM-embedded modules transmit standardized fault code hierarchies to centralized service desks. EU Stage V mandates require real-time particulate matter monitoring, accelerating factory-fit penetration over aftermarket alternatives. Regulatory compliance layers sustain pricing power.
- GPS Tracking:Location-only modules face margin compression from smartphone-integrated alternatives.
- Fleet Management:Unified dashboards aggregate fuel, labor, and scheduling data for rental fleet consolidation.
- Asset Utilization Monitoring:Engine hour logging and work-mode classification support equipment-as-a-service financing structures.
Remote Diagnostics anchors OEM recurring revenue. Predictive Maintenance is climbing the fastest.
Application:
Customer type dictates which applications command budget priority — rental firms emphasize utilization metrics while owner-operators focus on compliance automation.
- Fleet Optimization:Analytics layers integrating fuel burn, idle time, and operator productivity command premium pricing. German equipment lessors now specify uptime commitments and fuel-efficiency benchmarks in platform selection criteria. Outcome-based procurement compresses vendor qualification timelines.
- Regulatory Compliance:EU CSRD Scope 1 emissions disclosure mandates require audit-ready aggregation of fuel consumption and carbon intensity. Construction firms deploy telematics to automate reporting workflows. Compliance automation reduces administrative overhead.
- Safety & Security:Operator behavior monitoring and geofencing prevent unauthorized equipment operation.
- Fuel Management:Real-time consumption tracking identifies inefficient work modes and fuel theft.
- Theft Prevention:Geolocation and remote immobilization protect high-value assets in unsecured yards.
Fleet Optimization captures the strongest margin pools. Regulatory Compliance is gaining share fastest.
End User:
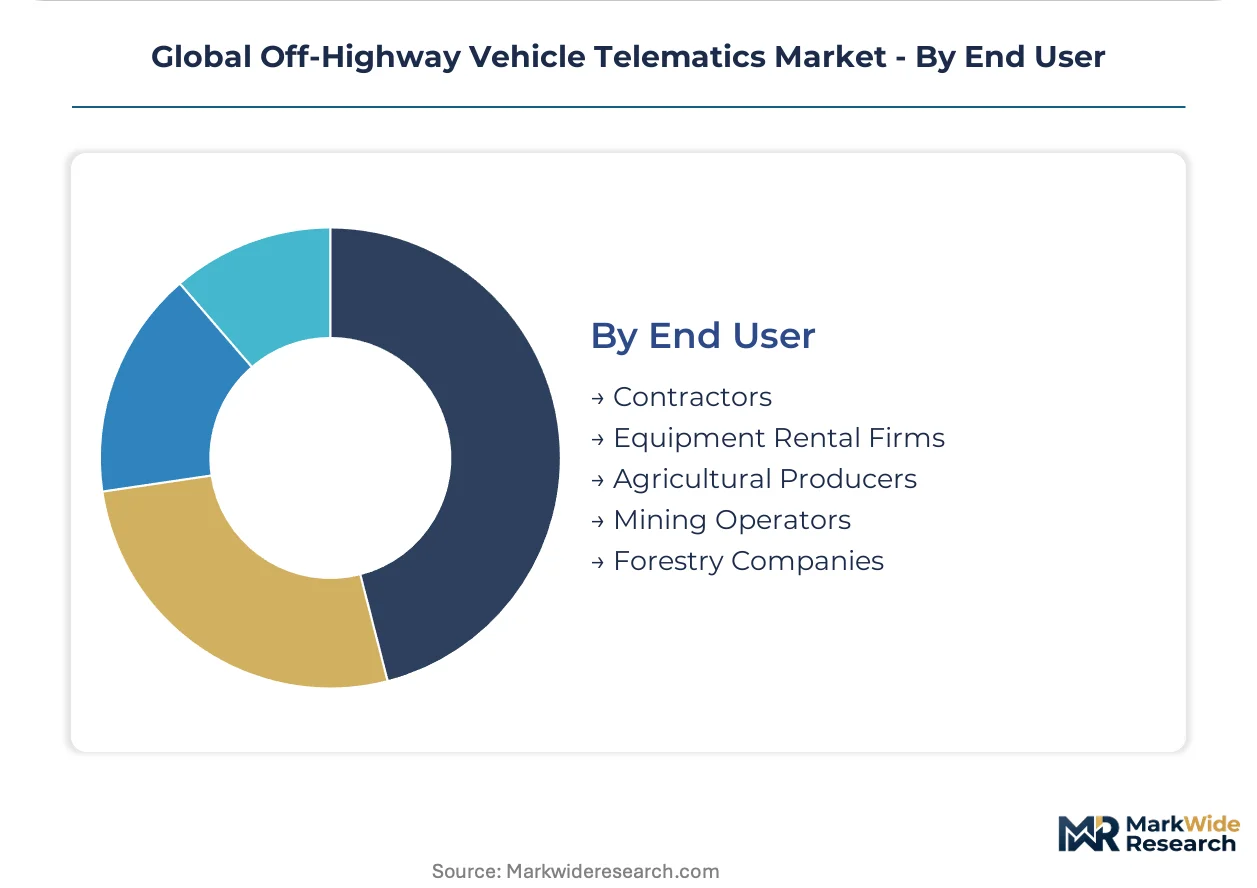
Volume concentration varies sharply — equipment rental firms consolidate thousands of units under unified platforms while forestry companies deploy specialized configurations for remote operations.
- Equipment Rental Firms:Unified telematics platforms compress vendor selection cycles and privilege integrated OEM-supplied systems. Subscription-based leasing models defer hardware capital outlays while locking in recurring software revenue. Fleet scale drives platform standardization.
- Mining Operators:Condition-based maintenance subscriptions reduce unplanned downtime in continuous extraction environments. Western Australian iron ore producers anchor demand for prognostic algorithms. Operational intensity justifies premium technology investment.
- Contractors:Fragmented ownership patterns favor dealer-installed aftermarket systems with lower upfront commitment.
- Agricultural Producers:Seasonal utilization patterns limit willingness to pay for year-round connectivity subscriptions.
- Forestry Companies:Remote harvest locations require satellite backhaul and extended battery autonomy.
Equipment Rental Firms dominate procurement volume. Mining Operators are where technology premium concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment rental firms and mining operators concentrate procurement power in the United States, Germany, and Australia, while regulatory mandates in Japan and Brazil accelerate factory-fit telematics penetration over aftermarket alternatives.
United States
Large-scale construction contractors and agricultural operations drive premium telematics deployments across the Midwest and Sun Belt. EPA Tier 4 Final mandates embed onboard diagnostics hardware as standard equipment in diesel-powered machinery. Dallas-Fort Worth and Atlanta anchor major equipment rental consolidation hubs where unified fleet platforms compress vendor selection cycles.
Germany
Equipment lessors specify uptime commitments and fuel-efficiency benchmarks in telematics procurement criteria. EU Stage V regulations require real-time particulate matter monitoring, accelerating factory-fit penetration over dealer-installed systems. Munich and Stuttgart host OEM engineering centers integrating remote diagnostics with hydraulic system architectures.
Australia
Iron ore producers in Western Australia subscribe to condition-based maintenance algorithms that convert vibration signatures into failure predictions. Satellite IoT backhaul enables real-time payload monitoring in cellular dead zones. Perth anchors mining technology procurement decisions that cascade through Asia-Pacific contractor networks.
Japan
Domestic construction equipment manufacturers embed telematics modules to transmit fuel consumption and work-mode utilization under METI energy-efficiency standards. Tokyo and Nagoya concentrate OEM headquarters where integrated factory-fit systems displace aftermarket retrofitting. Regulatory data logging mandates favor captive telematics stacks over third-party platforms.
Brazil
Agricultural machinery fleets in Mato Grosso and São Paulo states transmit GNSS-guided planting data alongside fuel telemetry. Fragmented local electronics distributors struggle with consistent calibration capabilities for aftermarket installations. São Paulo anchors dealer networks bundling telematics with extended service contracts.
Global Off-Highway Vehicle Telematics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. Vertically integrated OEMs leverage dealer networks to bundle hardware with recurring service contracts. Specialized platform providers compete on precision workflows and satellite connectivity architectures. Independent telematics vendors target retrofit opportunities in legacy fleets. Dominant competitive moves include strategic partnerships for connectivity infrastructure and portfolio diversification into predictive maintenance software licensing.
Within the integrated OEM tier, Caterpillar Inc. and Komatsu Ltd. exemplify channel-control strategies that lock in recurring revenue through dealer-embedded service contracts. Trimble Inc. occupies a specialist position where GNSS expertise extends into unified farm management information systems. These three anchors represent divergent archetypes: heavy machinery incumbents bundling telematics as standard equipment versus precision technology specialists monetizing software workflows.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Deere & Company |
| CNH Industrial N.V. |
| Volvo Construction Equipment AB |
| Trimble Inc. |
| TomTom International BV |
| ORBCOMM Inc. |
| Trackunit A/S |
| Others |
Supply & Pricing Matrix
Shanghai-to-Los Angeles container freight corridors transmit semiconductor foundry cost volatility directly into telematics hardware pricing, compressing margins for platform providers while amplifying price differentiation between integrated OEM systems and fragmented aftermarket alternatives. Supply concentration in East Asian electronics manufacturing feeds downstream tiering across premium factory-fit modules, mid-tier dealer-bundled configurations, and economy retrofit installations.
Pricing Analysis
Cost-plus contracts with quarterly indexation to semiconductor commodity benchmarks dominate OEM-supplier agreements for cellular and satellite connectivity modules. Three-tier pricing structure across premium, standard, and economy levels separates integrated factory-fit systems with embedded diagnostics from dealer-installed alternatives and bare-bones GPS tracking. Pricing pressure stems from LTE module cost compression as foundry capacity constraints ease. Equipment rental firms exhibit highest price sensitivity due to fleet-scale procurement leverage, while mining operators accept premium subscriptions for predictive maintenance depth.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for cellular modem and GNSS chip sourcing. Manufacturing concentrates in China, Taiwan, and South Korea for semiconductor components, with final assembly distributed across Mexico, Poland, and Thailand. Raw material dependencies center on rare earth elements for magnet assemblies, lithium-ion cells for battery backup systems, and specialized aluminum alloys for ruggedized enclosures. Distribution runs through captive OEM dealer networks and independent telematics distributors serving retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, EU Stage V, and METI compliance architectures creates white-space opportunities for specialized platform providers. Equipment rental consolidation and carbon accounting mandates fragment demand into distinct buyer archetypes with diverging technology priorities.
For Market Incumbents: Harden predictive maintenance algorithm differentiation through deeper hydraulic system integration, raising switching costs for mining operators. Secure captive satellite IoT capacity agreements to defend against connectivity cost volatility. Expand dealer-embedded service contract penetration to lock out aftermarket retrofit competitors before EU CSRD disclosure mandates accelerate.
For New Entrants and Emerging Players: Brazilian agricultural machinery fleets represent underpenetrated demand for GNSS-integrated telematics platforms, with fragmented local electronics distributors failing to meet calibration requirements for precision planting workflows. Target Mato Grosso soybean operations with subscription-based equipment-as-a-service financing that defers hardware capital outlays. Partner with regional dealer networks for installation capacity rather than building captive service infrastructure.
For Investors and Strategic Acquirers: Specialist platform providers with proven satellite backhaul architectures and mining sector customer concentration offer the strongest acquisition profile for portfolio exposure to prognostic software licensing growth. Long-term viability hinges on regulatory data-reporting obligations expanding beyond emissions into operator safety and carbon accounting. Monitor EU CSRD enforcement intensity and Scope 1 disclosure audit failure rates as inflection indicators for compliance automation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Algorithm Development | AI-driven prognostics convert vibration data into failure predictions for Western Australian iron ore producers. |
| Satellite IoT Capacity Partnership | Real-time payload monitoring in cellular dead zones requires dedicated constellation bandwidth agreements. |
| Dealer Network Service Contract Bundling | Caterpillar's extended warranty integration locks in recurring revenue across fragmented contractor ownership. |
| Carbon Accounting Platform Integration | EU CSRD Scope 1 disclosure mandates create audit-ready fuel burn aggregation for construction firms. |
| Precision Agriculture Workflow Convergence | GNSS-guided planting data integration pulls telematics into unified farm management information systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of OEM technical documentation, EPA and EU regulatory filings, and semiconductor trade flow data. Fleet managers at equipment rental firms, mining operations technology officers, agricultural producer cooperatives, and construction contractor procurement leads provided operational perspective. Secondary validation drew from SEC 10-K equipment segment disclosures, customs import records for telematics hardware, and METI energy-efficiency compliance registries. Bottom-up unit economics and top-down market sizing triangulate volume and value estimates.
Forecast inputs span vehicle type replacement cycles, technology licensing tier penetration rates, and application-specific willingness-to-pay across fleet optimization and regulatory compliance use cases. Segmentation dimensions include construction equipment versus agricultural machinery versus mining vehicle categories, predictive maintenance versus remote diagnostics versus GPS tracking technology tiers, and equipment rental firm versus contractor versus mining operator end-user archetypes. CAGRs derive from regression analysis of historical installed base growth against regulatory mandate implementation timelines and satellite IoT constellation deployment schedules.
Practitioners should monitor EPA Tier 5 proposal developments, EU CSRD audit enforcement patterns, and semiconductor foundry capacity expansion announcements for early signals of forecast deviation risk. Material shifts in emissions regulation stringency, carbon disclosure liability frameworks, or cellular connectivity cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Off-Highway Vehicle Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Snow Scooter Market