
 North America 2-Wheeler Tire Market | 2026-2036
North America 2-Wheeler Tire Market Size, Share, and Industry Trends Forecast 2026-2036
North America 2-Wheeler Tire Market Analytics
Modular tire-and-wheel bundling is pivoting how fleet buyers and individual riders evaluate replacement cycles. Michelin leverages its premium manufacturing scale to supply OEM fitments across major motorcycle brands. Bridgestone anchors its position through deep distribution partnerships with independent dealers throughout the United States and Canada. Dunlop competes aggressively in the performance segment, sustaining brand loyalty among sportbike enthusiasts.
North America 2-wheeler tires are pneumatic structures comprising vulcanized rubber compounds reinforced with nylon or steel belting, designed to withstand dynamic loads across varying road surfaces and thermal conditions while transmitting engine torque to the pavement. Motorcycle tires command the largest revenue share given higher unit values and replacement frequency, while scooter tires are gaining ground as urban mobility platforms proliferate in dense metropolitan corridors. The all-weather feature category leads volume in northern climates where seasonal versatility reduces fleet downtime, whereas performance-oriented variants concentrate margin pools in the aftermarket channel.
The National Highway Traffic Safety Administration (NHTSA) mandates Federal Motor Vehicle Safety Standard No. 119 for motorcycle tire construction and labeling, while Transport Canada enforces parallel CMVSS requirements that shape cross-border product homologation. California's Air Resources Board (CARB) imposes stringent criteria on tire-related rolling resistance for electric two-wheelers, pressuring suppliers to reformulate tread compounds. Stakeholders must monitor how state-level zero-emission vehicle incentives redirect fleet procurement toward electric platforms with distinct load-bearing and wear characteristics.
Market Dynamics
Last-mile logistics operators across the United States and Canada are consolidating fleet procurement around standardized tire specifications, compressing replacement cycles and forcing suppliers to align volume contracts with telematics-driven wear monitoring systems.
Growth Catalysts
- EPA emission standards for small displacement engines:Manufacturers are reformulating rubber compounds to reduce rolling resistance on internal combustion two-wheelers, creating replacement demand for compliant tire designs.
- Gig-economy delivery expansion:Food and parcel delivery platforms in California and Texas are scaling dedicated two-wheeler fleets, driving bulk tire procurement through centralized fleet management programs.
- Silica-silane tread compounds:Advanced wet-grip formulations are extending replacement intervals while meeting NHTSA wet-traction requirements, reducing total cost of ownership for high-mileage operators.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and currency fluctuations are compressing margins on economy-tier products, forcing suppliers to absorb input cost spikes or risk volume loss.
- Domestic distribution concentration:Independent dealer networks in the Midwest and Mountain states control shelf access, creating gatekeeper friction for new market entrants without established route-to-market relationships.
- Load rating limitations on scooter tires:Electric two-wheeler battery packs exceed legacy weight specifications, restricting tire compatibility and forcing premature platform-specific redesign cycles.
Strategic Opportunities
- Canadian urban zero-emission zones:Municipal fleet electrification mandates in Toronto and Vancouver are creating first-mover advantage for suppliers with certified low-rolling-resistance tire portfolios.
- Subscription-based tire-as-a-service:Fleet operators are piloting per-mile pricing models that bundle installation, rotation, and replacement, shifting revenue from unit sales to recurring service contracts.
- Connected tire pressure monitoring:Integration with telematics platforms is enabling predictive replacement scheduling, opening data-monetization channels alongside hardware revenue.
Industry Challenges
- Compound formulation talent scarcity:Specialized rubber chemists with motorcycle-specific dynamic load expertise are concentrated at legacy suppliers, constraining R&D velocity at mid-tier competitors.
- CARB certification timelines:California's rolling resistance testing protocols require 18-24 month validation cycles, delaying product launches and freezing specification decisions ahead of model-year changeovers.
- Cross-border homologation complexity:Divergent NHTSA and Transport Canada labeling requirements force dual SKU maintenance, fragmenting production runs and inflating inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America 2-Wheeler Tire Market |
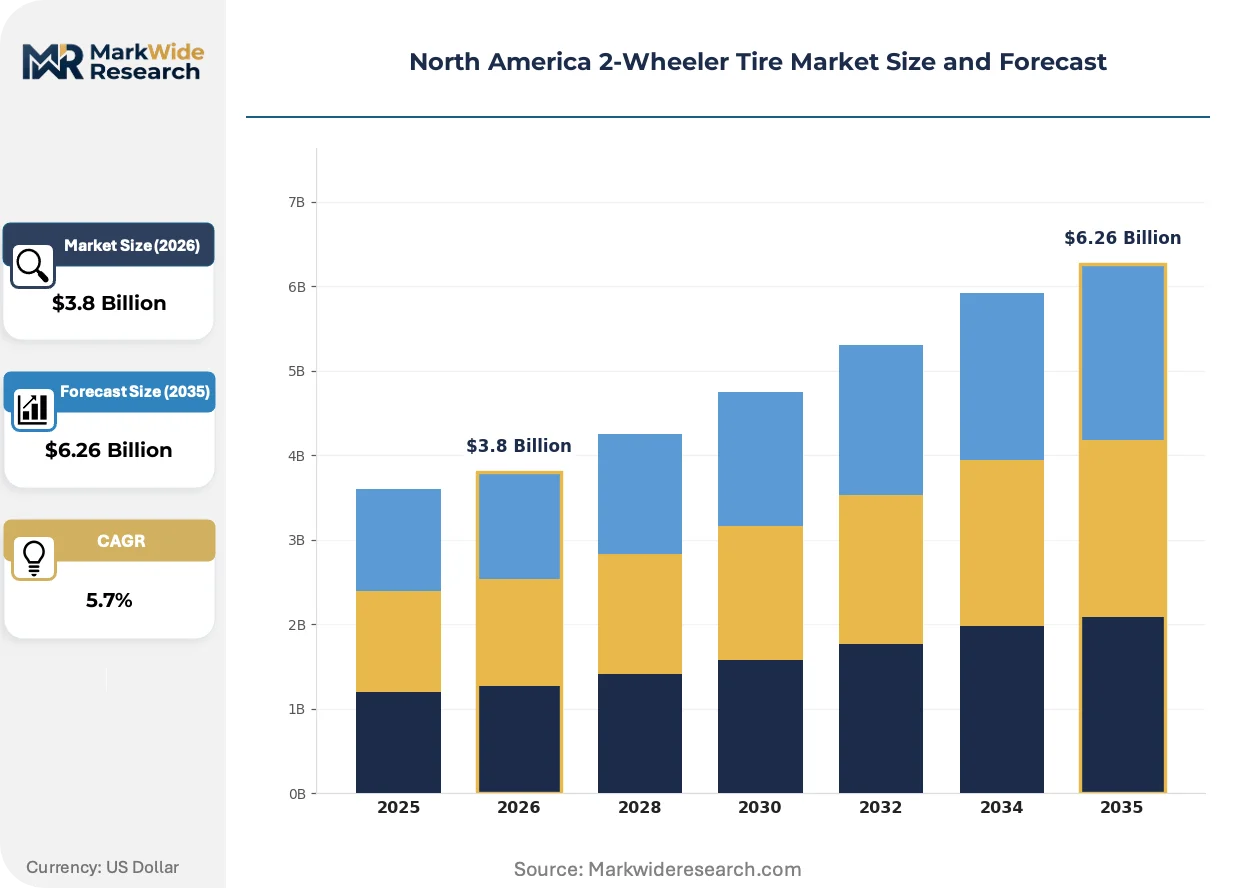
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scooter Tires, Motorcycle Tires, Moped Tires, Bicycle Tires Material: Rubber, Nylon, Polyester, Steel Feature: All-Weather, Performance, Off-Road, Touring End User: Private Owners, Rental Services, Delivery Services, Fleet Operators |
| Companies Covered | Michelin, Bridgestone, Goodyear, Continental, Pirelli, Apollo Tyres, BFGoodrich, Cooper Tires, Dunlop, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America 2-Wheeler Tire Market Evolving Landscape
Material science breakthroughs and regulatory pressure on rolling resistance are converging to redefine tire architecture, while fleet digitization is compressing the traditional replacement decision cycle from visual inspection to algorithmic prediction.
Multi-layer aramid belt constructions are electrifying sportbike tire performance by enabling thinner sidewalls without sacrificing stability under cornering loads. Track-day enthusiasts and canyon riders in California and Colorado are adopting these designs at accelerating rates, displacing traditional steel-belted configurations in the premium aftermarket segment. The structural consequence is a margin pool compression in mid-tier performance products as buyers concentrate spending at the specification extreme.
Transport Canada's evolving CMVSS labeling requirements for motorcycle tires are mandating QR-code-linked digital certificates that trace manufacturing batch and compound formulation. This policy is forcing suppliers to retrofit production lines with serialization infrastructure and cloud-based verification platforms. The aftermarket channel, particularly independent dealers in Ontario and Quebec, faces the steepest compliance burden as legacy inventory requires manual recertification or write-off.
Fleet procurement teams at delivery platforms are consolidating supplier relationships around integrated tire-and-service contracts that bundle installation, roadside assistance, and predictive replacement. This behavioral shift is displacing the traditional dealer-mediated transaction model in high-volume urban corridors. The transformation is most visible in Texas, where Dallas and Houston-based logistics operators are piloting direct manufacturer partnerships that bypass regional distribution tiers entirely.
North America 2-Wheeler Tire Market Segmentation
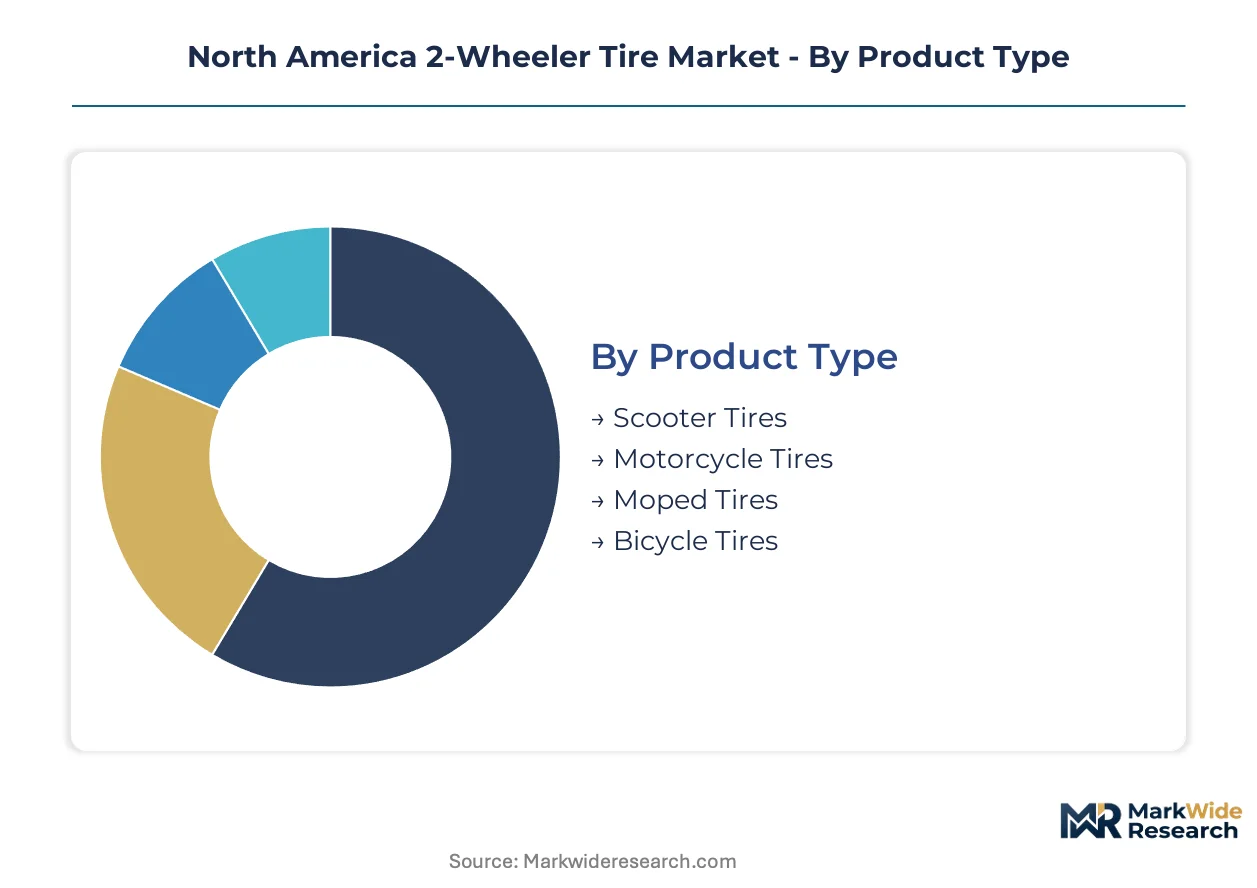
Tire specification decisions in North America increasingly hinge on load-bearing requirements, rolling resistance mandates, and fleet telematics integration. Segmentation clarity enables suppliers to align compound formulations and distribution investments with distinct performance thresholds across vehicle platforms and operating environments.
Product Type:
Supply concentration tilts toward motorcycle tire production, where higher unit values justify dedicated curing presses and specialized mold inventories at major manufacturing facilities.
- Motorcycle Tires:Multi-layer aramid and steel-belted constructions handle dynamic cornering loads and sustained highway speeds. Demand clusters in California canyons and Texas touring corridors, where replacement cycles accelerate under high thermal stress and abrasive road surfaces.
- Scooter Tires:Reinforced sidewall designs accommodate electric powertrain weight distribution and instant torque delivery. Toronto and Vancouver municipal electrification mandates are redirecting procurement toward low-rolling-resistance formulations certified under emerging urban zero-emission frameworks.
- Moped Tires:Narrow-section bias-ply constructions optimize fuel efficiency on sub-50cc displacement platforms common in dense northeastern urban cores.
- Bicycle Tires:High-thread-count casings with tubeless-ready beads serve recreational and commuter segments across Colorado and Pacific Northwest trail networks.
Today's leader: Motorcycle Tires. Tomorrow's challenger: Scooter Tires.
Material:
Cost tier differentiation separates commodity rubber compounds from engineered polymer blends commanding premium positioning in performance and fleet segments.
- Rubber:Natural and synthetic elastomer formulations provide base traction and damping characteristics across all product tiers. CARB rolling resistance protocols are pressuring suppliers toward solution-polymerized styrene-butadiene blends that reduce hysteresis loss without sacrificing wet-grip performance on California roadways.
- Steel:High-tensile bead wires and belt plies maintain structural integrity under centrifugal loads at sustained elevated speeds. Texas-based fleet operators specify steel-reinforced constructions for delivery motorcycles accumulating high annual mileage on interstate connectors.
- Nylon:Chafer and ply materials offer puncture resistance and flexibility in bias-ply scooter and moped applications.
- Polyester:Lightweight body ply substitutes reduce rotating mass in economy-tier bicycle and entry-level motorcycle fitments.
Rubber formulations dominate volume. Steel reinforcement commands margin.
Feature:
Application-driven specification splits the market between year-round versatility and specialized performance envelopes.
- All-Weather:Silica-enriched tread compounds with siped patterns maintain pliability across temperature extremes from Minnesota winters to Arizona summers. NHTSA wet-traction requirements shape groove geometry and compound hardness specifications for cross-climate certification.
- Performance:Track-derived rubber formulations with rapid warm-up characteristics and progressive breakaway behavior serve sportbike enthusiasts in California and Colorado mountain corridors. These constructions sacrifice tread life for cornering confidence, compressing replacement intervals and sustaining aftermarket revenue concentration.
- Off-Road:Knobby tread patterns with self-cleaning lug designs penetrate loose surfaces across Pacific Northwest logging roads and desert Southwest terrain.
- Touring:Harder compound centers with softer shoulders balance mileage and grip for long-distance riders traversing interstate corridors.
All-Weather holds volume leadership. Performance captures aftermarket premium.
End User:
Customer type determines procurement channel, pricing tolerance, and service bundling expectations across the value chain.
- Fleet Operators:Centralized procurement teams at last-mile logistics platforms negotiate volume contracts with telematics-linked wear monitoring and predictive replacement scheduling. Dallas and Houston delivery networks are consolidating supplier relationships around integrated tire-and-service agreements that bypass traditional dealer intermediaries.
- Delivery Services:Gig-economy platforms in California and Texas operate dedicated two-wheeler fleets with compressed replacement cycles driven by high daily mileage and curb-impact damage frequency.
- Private Owners:Dealer-mediated purchases dominate, with brand loyalty and peer recommendation influencing specification decisions in enthusiast segments.
- Rental Services:Shared mobility operators prioritize durability and vandalism resistance over performance characteristics in urban deployment zones.
Fleet Operators drive specification consolidation. Delivery Services expand fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The two-wheeler tire industry traces its North American scaling to post-war motorcycle manufacturing clusters in the Midwest and California, where domestic rubber compounding expertise merged with Japanese and European OEM expansion during the 1970s and 1980s.
United States
California's gig-economy delivery density and Texas's interstate touring corridors generate divergent demand profiles—urban scooter fleets versus high-mileage cruiser replacement. NHTSA's Federal Motor Vehicle Safety Standard No. 119 governs construction and labeling requirements nationwide. Dallas and Houston logistics operators are piloting direct manufacturer partnerships that bypass traditional regional distribution tiers entirely.
Canada
Toronto and Vancouver municipal electrification mandates are redirecting fleet procurement toward low-rolling-resistance formulations for electric two-wheelers. Transport Canada's CMVSS requirements enforce parallel labeling standards that shape cross-border product homologation. Ontario and Quebec independent dealers face compliance burdens as legacy inventory requires manual recertification under evolving QR-code-linked digital certificate protocols.
Mexico
Manufacturing cost advantages and USMCA trade integration position northern border states as emerging supply chain nodes for North American distribution. The country's national automotive regulator aligns safety standards with NHTSA frameworks to facilitate export compatibility. Mexico City Metro's dense urban mobility patterns are stimulating scooter tire demand among last-mile delivery platforms operating in constrained street grids.
North America 2-Wheeler Tire Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compound formulation sophistication and OEM fitment access. The market structure consolidates around legacy suppliers with deep manufacturing scale and established route-to-market relationships, while mid-tier competitors face gatekeeper friction from independent dealer networks. Three archetypes dominate: integrated rubber compounders with captive R&D pipelines, brand licensors leveraging trademark value without manufacturing ownership, and regional distributors controlling shelf access in fragmented geographies. Competitive moves center on telematics integration partnerships and subscription-based tire-as-a-service contracts that shift revenue from unit sales to recurring service relationships.
Within the premium manufacturing tier, Michelin and Bridgestone occupy positions as scale-driven compounders with extensive OEM fitment relationships across major motorcycle brands. Dunlop exemplifies the performance-specialist archetype, anchoring brand loyalty among sportbike enthusiasts through track-derived positioning. These three entities represent the dominant competitive anchors against which mid-tier and private-label alternatives benchmark pricing and specification decisions.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone |
| Goodyear |
| Continental |
| Pirelli |
| Apollo Tyres |
| BFGoodrich |
| Cooper Tires |
| Dunlop |
| Others |
Value Network & Pricing Analysis
Silica-silane tread compound adoption across premium motorcycle lines is compressing curing cycle times while concentrating production among compounders with captive R&D pipelines. This technology transition simultaneously raises fixed-cost thresholds for mid-tier suppliers and rewards scale-driven manufacturers with pricing power in fleet contract negotiations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by compound sophistication and OEM certification status. Price differentiation centers on CARB rolling resistance compliance tiers and telematics integration bundling. Cost compression in economy-tier products is intensifying because Southeast Asian natural rubber volatility forces margin absorption. Fleet operators exhibit highest price sensitivity due to centralized procurement leverage, while private sportbike enthusiasts show lowest sensitivity to unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Texas and California fleet operators require suppliers to qualify secondary compound formulations across multiple manufacturing sites. Geographic supply concentration spans Thailand, Indonesia, and Vietnam for natural rubber feedstock, with steel belting sourced from domestic mills in Ohio and Alabama. Raw material dependencies include styrene-butadiene rubber, carbon black, and silica fillers. Single-source vulnerability in aramid fiber supply creates exposure to aerospace demand surges. Distribution runs through independent dealer networks in Midwest and Mountain states, with direct manufacturer partnerships emerging in Dallas and Houston urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as fleet procurement shifts toward premium low-rolling-resistance specifications for electric two-wheeler compatibility.
For Market Incumbents: Hedge against commodity margin erosion by deepening backward integration into solution-polymerized styrene-butadiene production and securing exclusive telematics partnership rights with California delivery platforms. Prioritize CARB certification pipeline investment to defend specification lock-in ahead of model-year changeovers.
For New Entrants and Emerging Players: Enter via white-space targeting of Toronto and Vancouver municipal fleet electrification mandates, where first-mover advantage in low-rolling-resistance portfolios remains uncontested. Pursue direct service contracts with Dallas and Houston logistics operators piloting bypass distribution models, leveraging predictive replacement algorithms as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors controlling shelf access in fragmented Mountain and Midwest geographies, where telematics integration capex requirements strain family-owned balance sheets. Long-term viability favors acquisition targets with established NHTSA and Transport Canada homologation capabilities. Monitor CARB certification timeline compression as the signal for specification consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Formulation | Captive silica-silane production secures margin control against Southeast Asian feedstock volatility. |
| Telematics Platform Partnership | Integration with fleet wear-monitoring systems locks in predictive replacement revenue streams. |
| CARB Certification Acceleration | Early compliance with California rolling resistance protocols captures electric two-wheeler specification share. |
| Direct Fleet Service Contract | Bypassing independent dealer networks in Texas urban corridors compresses customer acquisition cost. |
| Cross-Border Homologation Harmonization | Unified NHTSA-Transport Canada SKU reduction lowers inventory carrying cost for Ontario distribution. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged tire compound R&D directors, fleet procurement managers at California and Texas delivery platforms, independent dealer principals in Ontario and Quebec, and aftermarket distribution executives. Secondary validation drew from NHTSA FMVSS 119 documentation, Transport Canada CMVSS amendment records, EPA small displacement engine rulemakings, and customs trade data on natural rubber imports. Bottom-up segment sizing triangulated against top-down OEM fitment forecasts.
Segment-weighting approaches modeled motorcycle, scooter, moped, and bicycle tire demand across product type, material composition, feature category, and end-user archetype dimensions. CAGRs were derived from installed base projections, replacement interval assumptions, and fleet electrification penetration curves across the analysis window. Industry-specific inputs included CARB regulatory timeline assumptions, telematics adoption rates among logistics operators, and silica compound cost curves.
Inputs from fleet procurement managers and dealer network operators were available through the study window; gaps in electric two-wheeler battery weight specification standardization introduce uncertainty bands around scooter tire load rating forecasts. Deviation in CARB certification timeline compression or natural rubber supply disruption severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Bicycle Rim Market
Tires and Wheels
Connected Tire Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Smart Tire Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Global Electric Vehicle Tire Market