
 Europe Telematics Market | 2026-2036
Europe Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Telematics Market Analysis
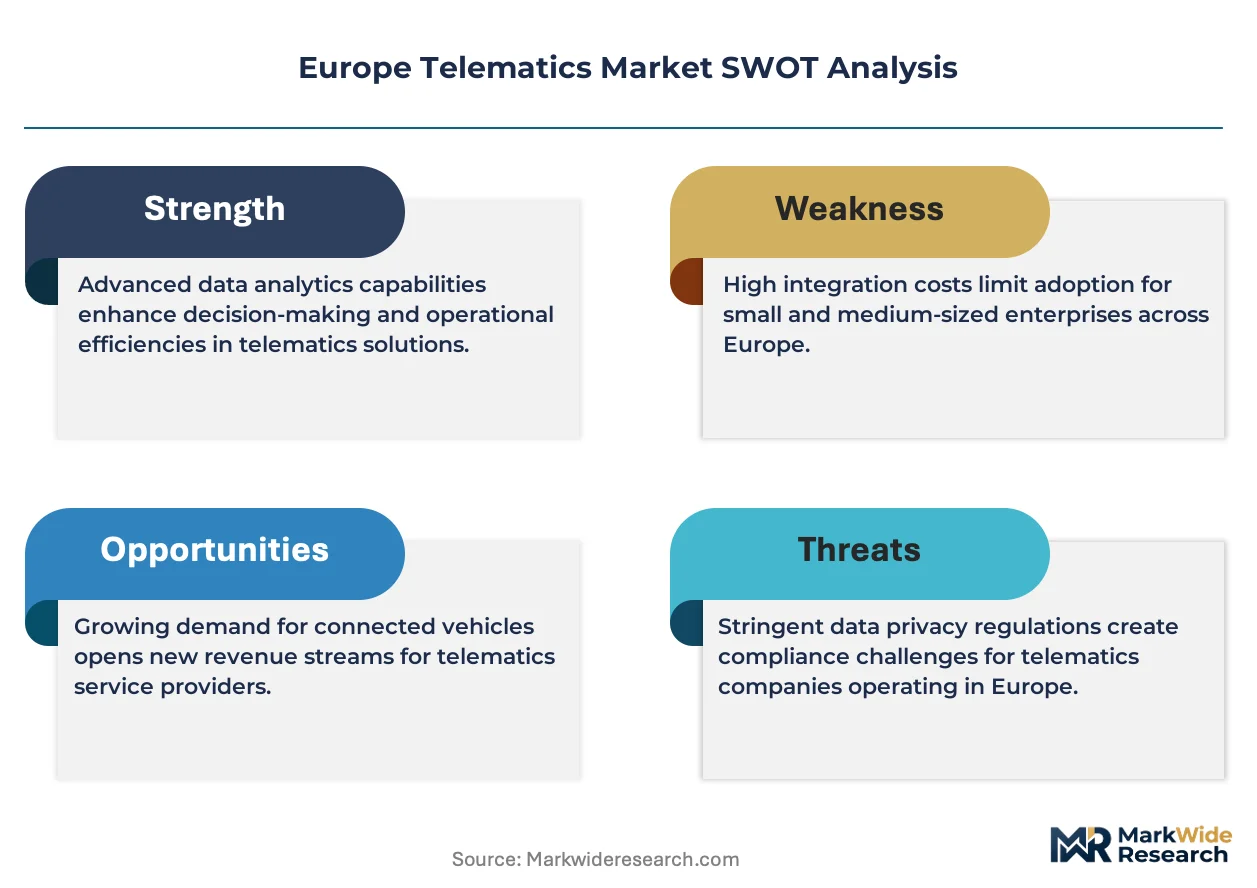
Embedded 5G connectivity is tilting the telematics technology stack toward real-time edge computing and over-the-air update architectures. Geotab Inc. leverages its open-platform ecosystem to anchor cloud-based fleet analytics across European commercial vehicle segments. TomTom International BV competes through its map-data heritage and HD positioning layers for autonomous-ready navigation. OCTO Telematics specializes in usage-based insurance telemetry, sustaining strong relationships with European underwriters.
Telematics denotes the integrated hardware-software systems that transmit vehicle location, performance, and behavioral data via cellular or satellite networks to centralized platforms for analysis and control. These systems typically incorporate GPS receivers, OBD-II interfaces, and TCUs processing data at sub-second intervals to enable real-time fleet visibility, predictive maintenance, and driver safety scoring. Fleet Management Solutions command the deepest margin pools due to recurring SaaS revenues and sticky enterprise contracts, while Insurance Companies represent the fastest-growing end-user channel as pay-as-you-drive models displace traditional risk pooling. Cloud Computing underpins the scalability shift, allowing providers to aggregate multi-million vehicle datasets for AI-driven route optimization and claims automation.
The EU Green Deal and the F-Gas Regulation shape vehicle emissions monitoring mandates, while GDPR imposes strict data governance on cross-border telematics flows. EMA and national transport regulators in Germany, France, and Italy enforce type-approval standards for aftermarket OBD devices and connected safety systems. Stakeholders must weigh compliance investments against the revenue upside from monetizing driver-behavior data within tightening privacy frameworks.
Market Dynamics
Embedded 5G modules are compressing latency thresholds across European fleet networks, forcing hardware suppliers to consolidate edge-computing capabilities into single telematics control units or surrender margin to cloud-native platform providers.
Growth Catalysts
- EU Green Deal:Mandatory emissions monitoring for commercial fleets in Germany and France is accelerating replacement cycles for legacy OBD hardware with connected monitoring systems.
- Usage-based insurance:Underwriters in Italy and Spain are expanding pay-as-you-drive contracts, pulling telematics penetration into passenger vehicle segments previously served by traditional risk pooling.
- Edge AI chipsets:On-vehicle inference engines processing driver-behavior data locally are reducing cellular bandwidth costs for fleet operators managing cross-border routes.
Market Restraints
- Semiconductor concentration:TCUs depend on specialty automotive-grade processors sourced from concentrated Asian foundries, exposing European assemblers to allocation volatility.
- GDPR friction:Cross-border data flows between member states trigger divergent national interpretations by CNIL, KBA, and Italian privacy authorities, complicating pan-European platform architectures.
- Aftermarket device saturation:Low-cost Chinese OBD-II dongles flooding Southern European channels erode pricing power for type-approved hardware meeting EMA safety standards.
Strategic Opportunities
- Eastern European fleet digitization:Polish and Romanian logistics operators lag Western counterparts in connected vehicle adoption, presenting first-mover expansion terrain for integrated platform providers.
- F-Gas Regulation alignment:Refrigerated transport fleets must retrofit temperature-monitoring telematics to comply with leak-detection mandates, opening specialized hardware demand.
- V2X convergence:Integration of C-V2X roadside units with fleet management platforms is creating unified traffic safety and logistics optimization stacks for autonomous-ready corridors.
Industry Challenges
- Embedded software engineering scarcity:Functional safety certification for automotive TCUs under ISO 26262 requires specialized firmware talent concentrated in German and French automotive clusters.
- Legacy fleet integration:Pre-CAN-bus commercial vehicles in aging Southern European fleets resist standard OBD-II connectivity, forcing expensive custom harness development.
- Multi-jurisdiction type approval:KBA, ANSM, and Italian transport ministry diverge on aftermarket device certification timelines, delaying product launches by 6-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Telematics Market |
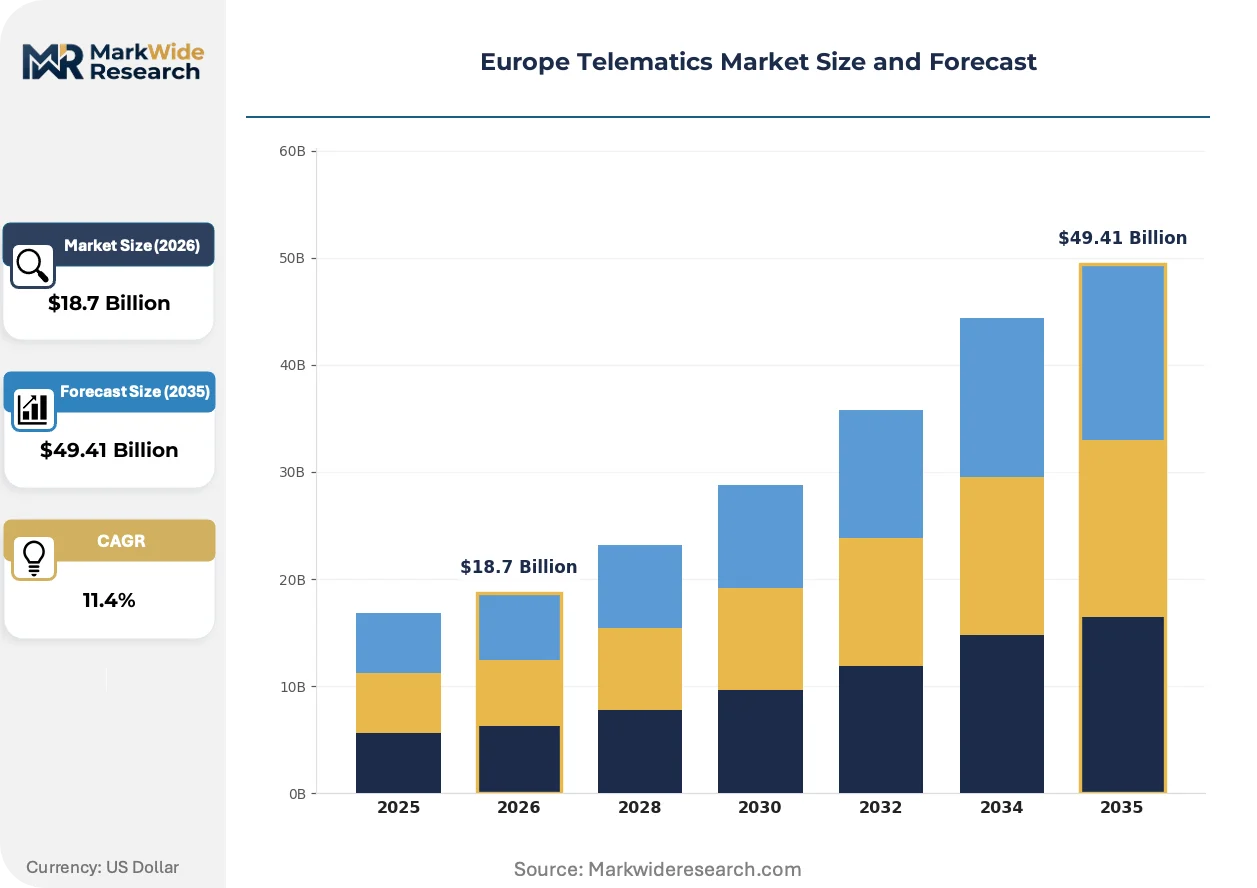
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OBD Devices, Navigation Systems, Fleet Management Solutions, Telematics Control Units End User: Automotive OEMs, Fleet Operators, Insurance Companies, Government Agencies Technology: GPS, GSM, Cloud Computing, RFID Application: Vehicle Tracking, Driver Behavior Monitoring, Remote Diagnostics, Dashboard Navigation |
| Companies Covered | Masternaut Limited, Geotab Inc., Targa Telematics S.p.A., Trimble Inc., TomTom International BV, Webfleet Solutions B.V., ABAX UK Ltd., OCTO Telematics, Verizon Connect, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Telematics Market Emerging Trajectories
Telematics architectures are pivoting from data transmission pipes to decision-making platforms, compressing the gap between vehicle-edge inference and enterprise cloud analytics.
Cellular vehicle-to-everything (C-V2X) modules operating in 5.9 GHz spectrum are rendering obsolete siloed GPS tracking units that lacked real-time roadside infrastructure negotiation. German commercial vehicle OEMs are embedding these modules as standard equipment on 2024 production lines. The technology is rendering obsolete aftermarket retrofit business models dependent on periodic batch uploads rather than continuous streaming.
The EU AI Act's risk-classification framework for automated decision systems is imposing algorithmic transparency requirements on driver-scoring models used by insurance telematics providers. Fleet safety platforms must now document training data provenance and bias-testing protocols to maintain regulatory clearance. French and Dutch insurers are most advanced in restructuring their scoring engines to satisfy these documentation burdens.
Subscription-based hardware provisioning is displacing upfront capital purchases among mid-sized fleet operators in Spain and Portugal. Leasing providers bundle TCU installation, cellular connectivity, and SaaS analytics into per-vehicle monthly fees. This consumption-pattern shift is most visible in temperature-controlled logistics, where operators prioritize cash-flow predictability over asset ownership.
Europe Telematics Market Segmentation
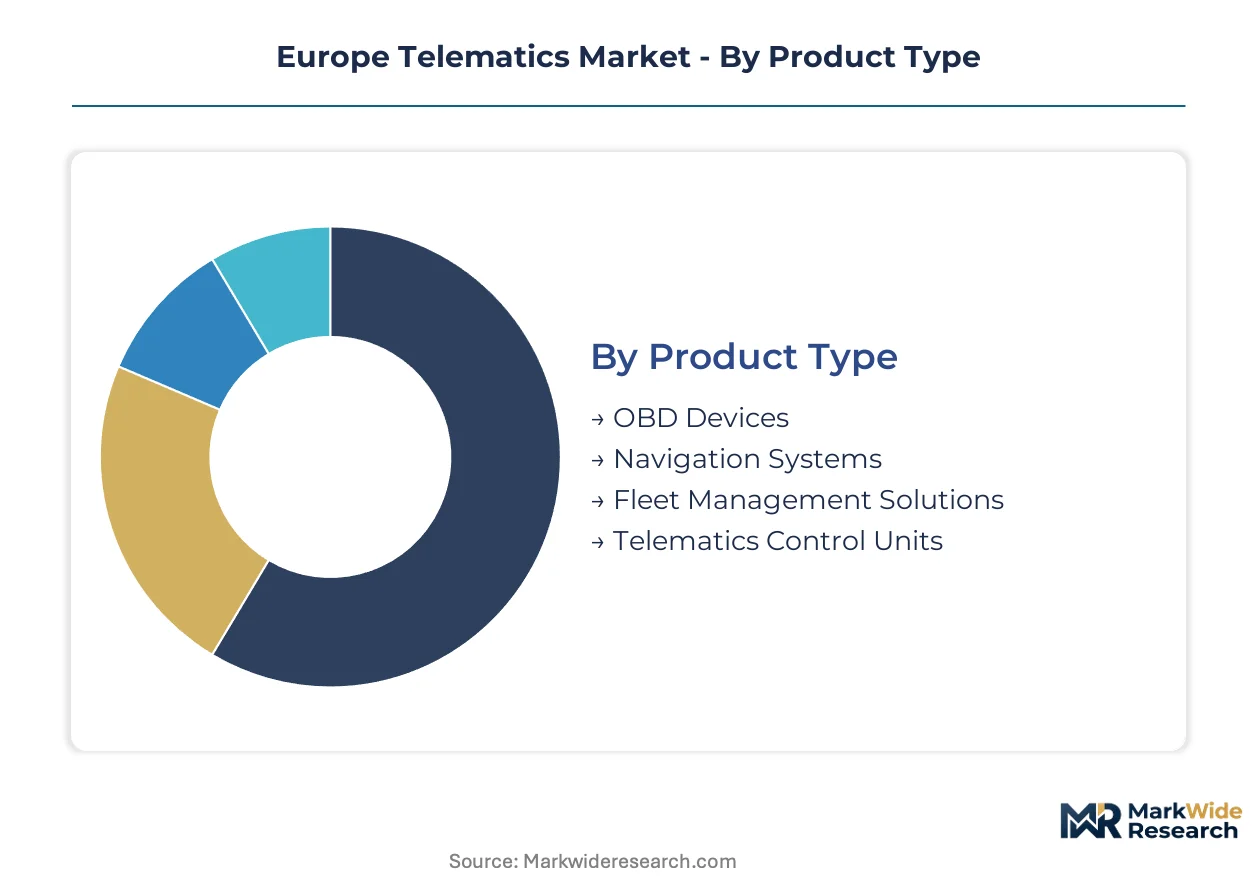
Telematics market segmentation reveals divergent technology maturities and margin architectures across hardware, software, and service layers. Fleet operators and insurance underwriters prioritize different performance specifications, forcing providers to calibrate R&D investments against channel-specific requirements.
Product Type:
Mature hardware categories face margin compression from embedded alternatives, while emerging integrated platforms capture recurring revenue streams.
- Fleet Management Solutions:Cloud-native platforms aggregate GPS tracking, fuel consumption analytics, and compliance reporting into unified dashboards. German and French logistics operators drive demand as EU Green Deal mandates tighten emissions documentation requirements.
- Telematics Control Units:Single-board computers integrating cellular modems, GPS receivers, and edge processors into sealed automotive-grade enclosures. TCU suppliers compete on ISO 26262 functional safety certification and thermal resilience for engine-bay mounting.
- OBD Devices:Aftermarket dongles plug into standardized diagnostic ports for retrofitted connectivity.
- Navigation Systems:Embedded or portable units providing turn-by-turn routing with real-time traffic overlay.
Fleet Management Solutions retain volume leadership; Telematics Control Units hold the steepest expansion curve as OEMs embed connectivity at the factory.
End User:
Customer archetypes span capital-intensive asset owners to risk-transfer intermediaries, each imposing distinct procurement criteria and contract structures.
- Fleet Operators:Commercial vehicle owners managing 50-5,000+ assets demand predictive maintenance algorithms and driver safety scoring. Polish and Romanian logistics companies represent underpenetrated expansion terrain as Western European standards diffuse eastward.
- Insurance Companies:Underwriters in Italy and Spain deploy pay-as-you-drive models using granular acceleration, braking, and cornering telemetry. GDPR-compliant data architectures and algorithmic transparency under the EU AI Act constrain platform design choices.
- Automotive OEMs:Vehicle manufacturers specify embedded modules for new production lines.
- Government Agencies:Public sector fleets and regulatory bodies procure monitoring systems for compliance enforcement.
Fleet Operators retain volume leadership; Insurance Companies are climbing the fastest as usage-based contracts displace traditional risk pooling.
Technology:
Technology layers stratify between proven location services and emerging cloud-native architectures reshaping data economics.
- Cloud Computing:Distributed server infrastructure enables real-time ingestion of millions of vehicle data streams for AI-driven route optimization. Cellular bandwidth costs and GDPR data residency rules shape provider selection criteria across German, French, and Benelux deployments.
- GPS:Satellite positioning remains foundational for location tracking and geofencing applications.
- GSM:Cellular networks transmit compressed telemetry packets from vehicle to platform.
- RFID:Short-range identification supports yard management and asset authentication.
Cloud Computing retains volume leadership; GPS holds the steepest expansion curve through multi-constellation receiver integration.
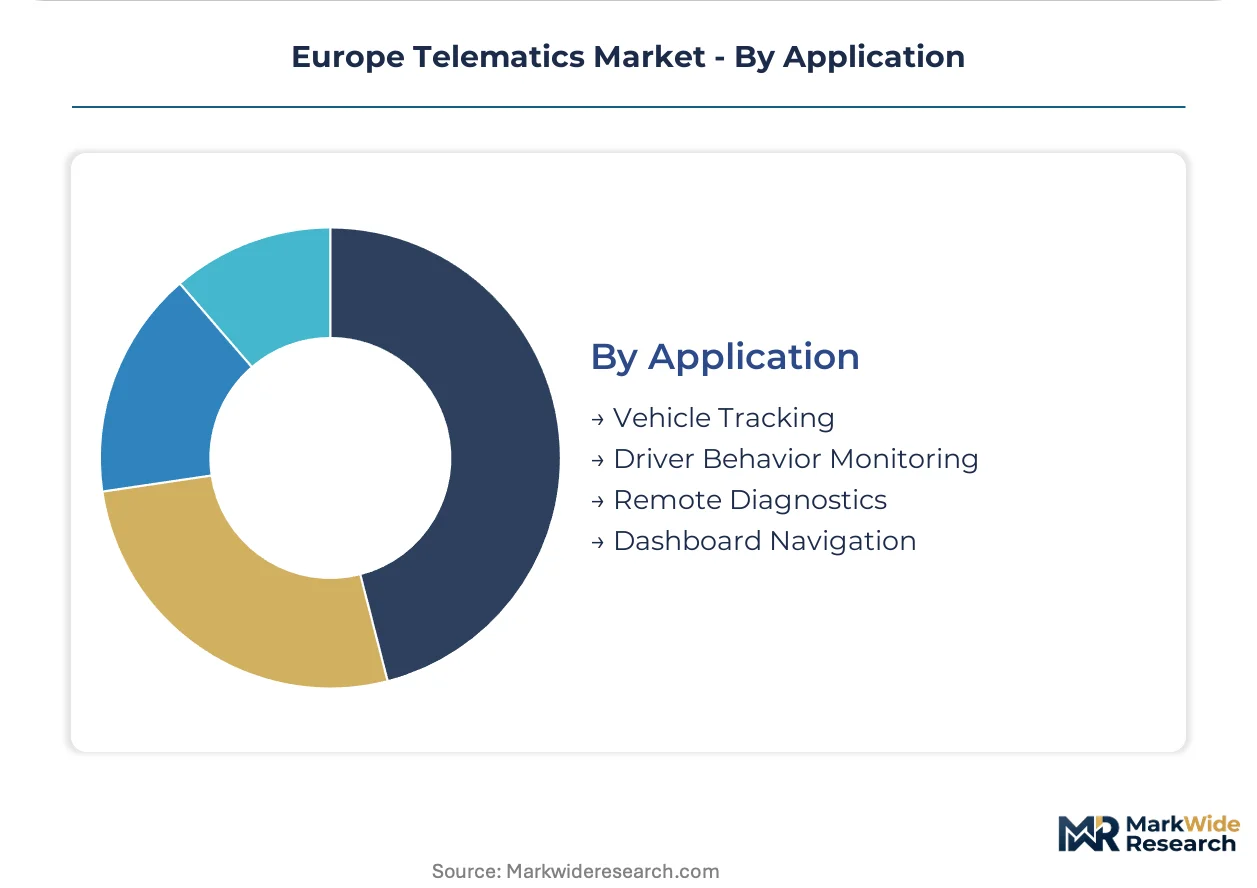
Application:
Functional use cases range from passive monitoring to active intervention systems with divergent hardware and software requirements.
- Driver Behavior Monitoring:Accelerometer and gyroscope fusion detects harsh braking, rapid acceleration, and cornering events for safety scoring. French and Dutch insurers lead restructuring of algorithmic models to satisfy EU AI Act documentation burdens on automated decision systems.
- Remote Diagnostics:OBD-II data streaming enables fault code interpretation and predictive maintenance scheduling. Refrigerated transport fleets under F-Gas Regulation mandates drive specialized temperature-monitoring variants.
- Vehicle Tracking:Real-time location monitoring for asset recovery and route compliance.
- Dashboard Navigation:Embedded or portable systems providing driver-facing routing guidance.
Driver Behavior Monitoring retains volume leadership; Remote Diagnostics gains share fastest as predictive maintenance contracts displace reactive service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and insurance underwriters cluster distinctly across Western and Eastern Europe, with regulatory enforcement intensity and embedded connectivity penetration creating divergent buyer archetypes by sub-region.
Germany
Commercial vehicle OEMs and Tier-1 logistics providers drive embedded TCU demand as KBA enforces stringent type-approval standards for aftermarket OBD devices. The EU Green Deal mandates emissions documentation for fleets exceeding 50 vehicles. Stuttgart and Munich automotive clusters concentrate edge-AI chipset development for driver-behavior inference engines.
France
Pay-as-you-drive insurance models expand through CNIL-supervised data governance frameworks that constrain algorithmic transparency requirements. The EU AI Act risk-classification rules impose documentation burdens on automated driver-scoring systems. Lyon and Paris host insurance-telemetrics integration labs restructuring scoring engines for compliance.
Italy
Usage-based insurance penetration accelerates fastest among Southern European markets as underwriters displace traditional risk pooling with granular telemetry contracts. National transport ministry type-approval timelines diverge from German KBA standards, delaying product launches. Milan and Turin concentrate telematics provider engineering centers serving Mediterranean fleet operators.
Poland
Logistics operators managing cross-border routes to Germany and Czechia represent underpenetrated expansion terrain for integrated platform providers. GDPR data residency rules shape cloud provider selection for pan-European architectures. Warsaw and Wrocław distribution hubs drive aftermarket OBD device demand from aging commercial fleets resisting embedded retrofits.
Spain
Subscription-based hardware provisioning displaces upfront capital purchases among mid-sized temperature-controlled logistics operators prioritizing cash-flow predictability. F-Gas Regulation leak-detection mandates drive specialized telematics retrofits for refrigerated transport. Barcelona and Valencia port logistics clusters anchor Mediterranean fleet digitization pilots.
Europe Telematics Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where cloud-native platform providers capture recurring SaaS revenues while hardware suppliers face margin compression from embedded alternatives. The vendor base stratifies between open-ecosystem orchestrators, map-data heritage specialists, and insurance-telemetry pure-plays. Dominant competitive moves include strategic partnerships with cellular module suppliers and geographic expansion into Eastern European lag markets.
Within the open-platform tier, Geotab Inc. and TomTom International BV exemplify divergent archetypes: the former anchors cloud-based fleet analytics through API-first architectures, while the latter occupies a position leveraging HD positioning layers for navigation-centric deployments. OCTO Telematics represents the insurance-telemetry specialization vector, sustaining underwriter relationships through usage-based insurance data pipelines. These three entities collectively illustrate how competitive positioning fragments across fleet-management, mapping, and risk-transfer channels.
| Leading Market Players |
|---|
| Masternaut Limited |
| Geotab Inc. |
| Targa Telematics S.p.A. |
| Trimble Inc. |
| TomTom International BV |
| Webfleet Solutions B.V. |
| ABAX UK Ltd. |
| OCTO Telematics |
| Verizon Connect |
| Others |
Supply Flow & Price Mechanics
Asian foundry concentration for automotive-grade processors concentrates margin capture with semiconductor suppliers, forcing European TCU assemblers to absorb cost volatility or cede pricing power to cloud-native platform providers downstream. This upstream chokepoint shapes contract structures across hardware tiers and determines which buyer segments retain procurement leverage.
Pricing Analysis
Long-term supply agreements with quarterly indexation to memory and cellular module spot markets dominate procurement between Tier-1 fleet operators and embedded TCU suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified units from commercial-grade alternatives and unbranded aftermarket dongles. Cost compression in economy-tier OBD devices intensifies because low-cost Chinese imports saturate Southern European channels. Mid-sized logistics operators in Spain and Portugal exhibit highest price sensitivity through subscription-based hardware provisioning, while German commercial OEMs prioritize functional safety certification over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities allow Taiwanese and South Korean semiconductor foundries to lock in allocation priority with automotive TCU manufacturers ahead of European assemblers. Processor wafers, cellular modems, and multi-constellation GPS receivers anchor bill-of-materials exposure. Single-source vulnerability concentrates in specialty automotive-grade chipsets qualified under AEC-Q100 standards. Distribution runs through Tier-1 electronics distributors holding regional inventory buffers in Rotterdam and Hamburg logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a replacement-cycle recovery as EU Green Deal mandates force accelerated hardware refresh timelines across aging commercial fleets. Fleet operators face compressed decision windows between compliance deadlines and technology upgrade paths.
For Market Incumbents: Entrench cloud-native platform stickiness by embedding predictive maintenance algorithms deeper into fleet operator ERP systems, neutralizing the threat from standalone hardware suppliers. Prioritize backward integration into edge-AI chipset design partnerships with Stuttgart and Munich automotive clusters to defend margin pools against commoditization of connectivity modules.
For New Entrants and Emerging Players: Polish and Romanian cross-border logistics operators represent the most penetrable entry point for integrated platform providers, given underpenetrated telematics adoption relative to Western European benchmarks. Temperature-controlled transport fleets under F-Gas Regulation compliance pressure offer specialized hardware retrofit demand with less entrenched incumbent presence. Pursue direct sales partnerships with Warsaw and Wrocław distribution hub operators rather than competing for saturated German fleet operator accounts.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed insurance-telemetry pure-plays holding concentrated underwriter relationships in Italy and Spain. Five-to-ten year viability hinges on successful EU AI Act compliance restructuring for algorithmic transparency in driver-scoring models. Monitor CNIL and Dutch data protection authority enforcement patterns as early signals of regulatory risk differentiation between portfolio companies.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified fleet management dashboards incorporating EU Green Deal compliance reporting reduce customer churn for German logistics operators. |
| Geographic Expansion | Eastern European market entry captures Polish and Romanian fleet digitization lag before incumbent saturation. |
| Regulatory Certification Investment | ISO 26262 functional safety qualification opens embedded TCU supply contracts with Stuttgart commercial vehicle OEMs. |
| Strategic Partnership | C-V2X roadside unit integration with fleet platforms creates autonomous-ready corridor offerings for German transport ministries. |
| Acquisition of Specialist Firm | Edge-AI chipset developers in Munich automotive clusters add on-vehicle inference capabilities for bandwidth cost reduction. |
Methodological Framework
Cross-validation between primary interviews with fleet operations directors, insurance underwriter technology leads, and Tier-1 automotive procurement managers anchors the qualitative findings against secondary data from EMA type-approval databases, KBA certification registries, and EU Green Deal implementation trackers. Bottom-up aggregation of fleet operator deployment plans triangulates with top-down analysis of cellular module shipment data and automotive production forecasts across the analysis window.
Calibration against historical adoption curves for connected vehicle platforms shapes the projection framework across hardware type, end-user segment, and application layer throughout the forecast period. Segmentation dimensions span product architecture, customer procurement archetype, and technology stack maturity. CAGRs derive from regression analysis of replacement cycle timing, regulatory mandate enforcement intensity, and insurance contract penetration rates.
Practitioners should monitor semiconductor allocation volatility, GDPR enforcement divergence across CNIL-KBA-Italian privacy authority interpretations, and EU AI Act algorithmic transparency rulemaking for early signals of forecast deviation. Macroeconomic freight volume contraction, regulatory timeline slippage, or 5G network rollout delays would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Smart Telematics Gateway Market
Telematics and Infotainment
GCC Commercial Telematics Market
Telematics and Infotainment
GPS Tracker Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Global in Dash Navigation System Market