
 Wheel Market | 2026-2036
Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Market Insights
Fleet operators and EV original equipment manufacturers is rotating toward larger-diameter forged and alloy configurations, displacing traditional steel-intensive buyer profiles in premium segments. Ronal Group leverages its European casting network to sustain high-margin supply contracts with German luxury automakers. Borbet GmbH anchors its position through specialized flow-forming expertise for lightweight performance applications. Maxion Wheels competes aggressively on cost-engineered steel wheel platforms for commercial vehicle fleets across North America and emerging markets.
A wheel is a circular structural component, typically comprising an rim, disc, and hub assembly, engineered from aluminum alloys, steel, or magnesium and manufactured through casting, forging, or flow-forming processes to transmit vehicle loads, absorb road shocks, and maintain rotational integrity at operational speeds. Alloy wheels command premium positioning in passenger vehicle fitments due to strength-to-weight ratios that improve fuel efficiency and handling dynamics, while steel wheels retain dominance in commercial and fleet applications where cost durability and repairability outweigh mass reduction priorities. Forged wheels represent the fastest-expanding product category among motorsport teams and high-performance aftermarket retailers, where defect tolerance and structural uniformity justify substantial price premiums over cast alternatives.
The US NHTSA and EPA impose stringent fatigue testing and emissions-linked fuel economy standards that directly incentivize wheel mass reduction across OEM supply chains. Europe's REACH regulation and ECHA substance restrictions constrain coating chemistries and aluminum smelter inputs, compelling suppliers to requalify material streams and surface treatment processes. Stakeholders must monitor evolving regulatory thresholds for recycled content mandates and carbon border adjustments that will reshape sourcing economics and supplier qualification timelines across major automotive production regions.
Market Dynamics
Electric vehicle manufacturers are forcing a material pivot across wheel supply chains, as battery range anxiety makes every kilogram of unsprung mass a target for elimination. This pressure is compressing traditional steel-forged margins while elevating aluminum and magnesium alloy specialists.
Growth Catalysts
- EPA fuel economy standards:Corporate average fuel economy mandates in the United States compel OEMs to specify lighter wheel architectures across passenger car portfolios.
- EV platform proliferation:Battery electric vehicle architectures require forged aluminum configurations to offset battery pack mass and extend driving range.
- Ningbo-Taizhou foundry cluster:Concentrated domestic production capacity in China's Zhejiang Province accelerates export fulfillment and raw material access.
Market Restraints
- Magnesium price volatility:Primary magnesium smelter concentration in Shanxi Province exposes alloy wheel producers to supply disruption and input cost spikes.
- REACH substance restrictions:ECHA limitations on hexavalent chromium surface treatments force costly requalification of coating chemistries for European market access.
- Steel wheel substitution ceiling:Commercial fleet operators resist alloy migration where repairability and impact tolerance outweigh mass reduction benefits.
Strategic Opportunities
- India commercial vehicle retrofit:Underpenetrated aftermarket demand for lightweight steel-alternative wheels in long-haul trucking corridors offers volume expansion.
- Closed-loop aluminum recycling:EU Green Deal recycled content mandates create first-mover advantage for suppliers with captive scrap reprocessing.
- Flow-forming hybrid processes:Convergence of casting economies with forging strength characteristics opens mid-market pricing tiers previously unreachable.
Industry Challenges
- Heat treatment certification backlog:TÜV and KBA validation timelines for new alloy formulations extend product launch windows by 8-14 months.
- Die engineering talent scarcity:Specialized forging die design expertise concentrates in aging workforces across Stuttgart and Turin supplier ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Market |
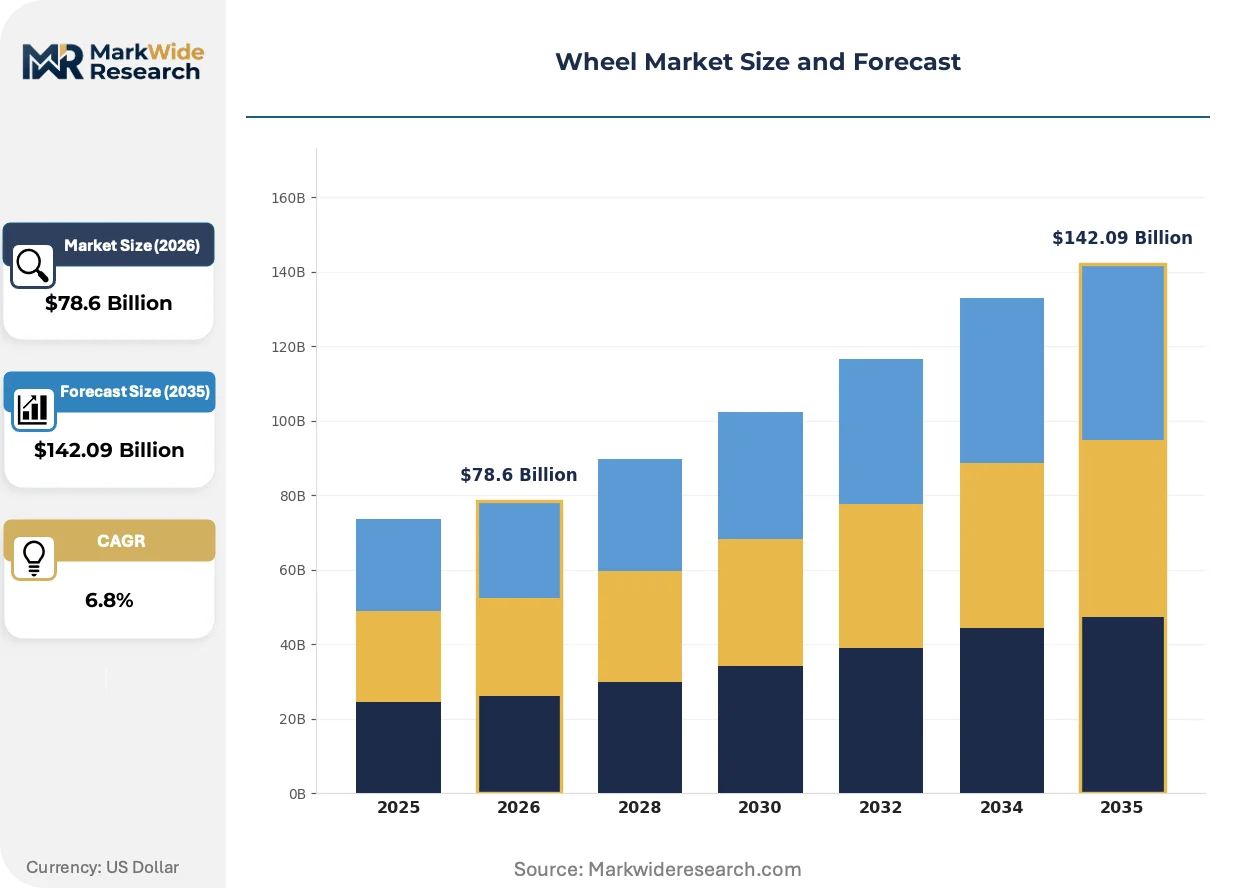
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Wheels, Steel Wheels, Forged Wheels, Cast Wheels End User: Automobile Manufacturers, Aftermarket Retailers, Distributors, Motorsport Teams Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Racing Vehicles Size: 14 Inch, 15 Inch, 16 Inch, 17 Inch |
| Companies Covered | Ronal Group, Borbet GmbH, Enkei Corporation, Maxion Wheels, Superior Industries, CITIC Dicastal, Topy Industries, Zhejiang Wanfeng Auto Wheel, Steel Strips Wheels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Market Trends and Innovations
Manufacturing process hybridization is compressing the traditional cast-versus-forged binary, creating intermediate performance tiers that reshape procurement segmentation. Three forces are actively restructuring competitive positioning.
Flow-forming technology is decomposing the historic trade-off between unit cost and structural integrity in wheel production. Tier-one suppliers serving German premium OEMs are adopting rotary forging machines at accelerating rates. This process convergence is collapsing the price gap between entry cast and premium forged configurations.
REACH authorization requirements for nickel and cobalt compounds in wheel coatings are forcing formulation reformulation across European supply chains. Surface treatment providers must qualify trivalent chromium and silane-based alternatives. Aftermarket retailers in Germany and France face inventory obsolescence risk on legacy-coated stock.
Fleet procurement departments are consolidating wheel specifications across vehicle classes to compress supplier management overhead. Standardization is displacing bespoke fitment programs in North American commercial vehicle operations. This behavioral shift concentrates contract volumes with multi-platform capable manufacturers at the expense of specialized single-application suppliers.
Wheel Market Segmentation
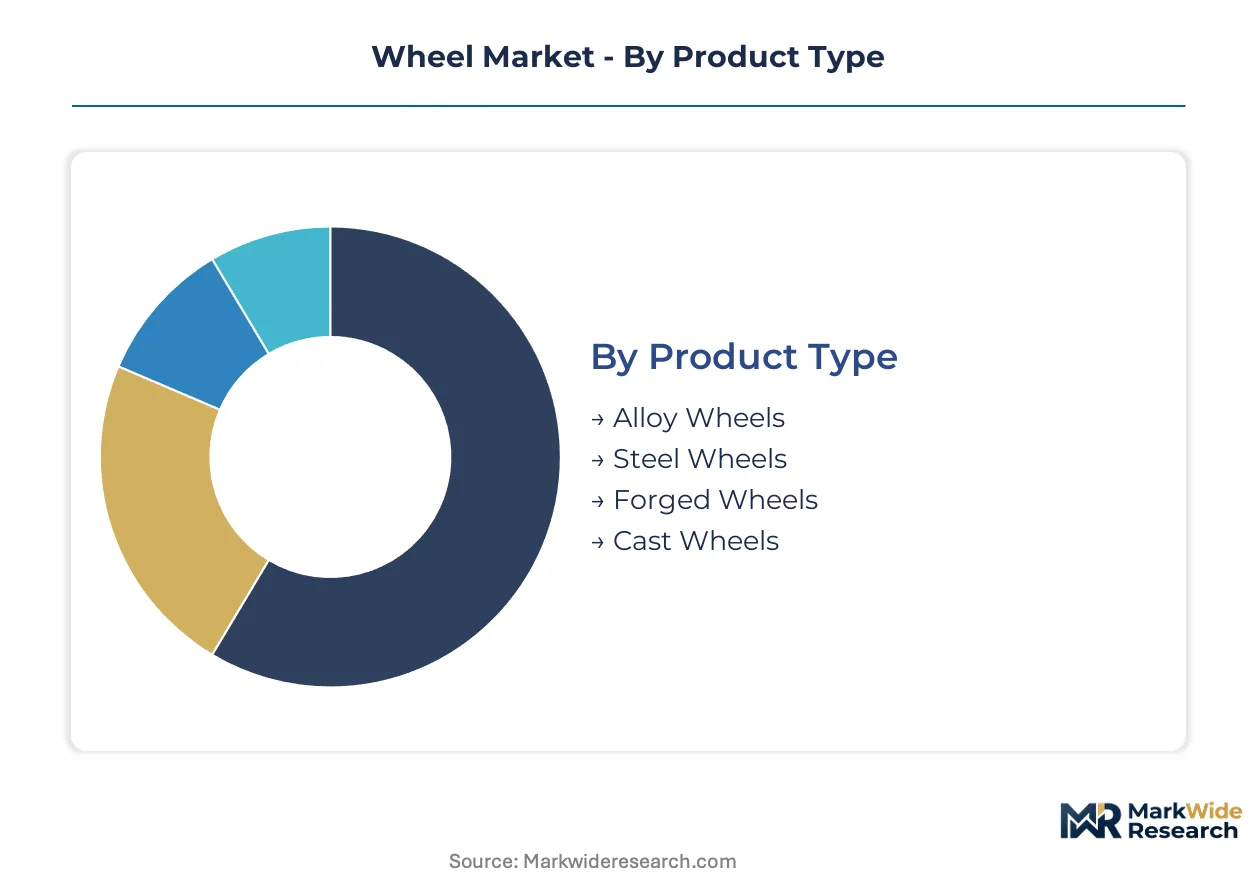
Wheel procurement patterns fragment sharply across material specifications, end-user technical requirements, and diameter configurations. Understanding these fault lines exposes where substitution threats and margin compression concentrate most intensely.
Product Type:
Steel wheel configurations face the most severe substitution pressure as EV manufacturers systematically eliminate unsprung mass from their platforms.
- Alloy Wheels:Aluminum-magnesium compositions deliver superior strength-to-weight ratios for passenger vehicle fitments. Demand concentrates with German and Chinese EV original equipment manufacturers seeking range extension through rotational mass reduction.
- Steel Wheels:Carbon steel constructions retain cost advantages and impact tolerance for commercial fleet operators. Procurement remains anchored in North American long-haul trucking corridors where repairability outweighs mass considerations.
- Forged Wheels:High-pressure forming creates grain-aligned microstructures for motorsport and luxury applications.
- Cast Wheels:Gravity and low-pressure casting serves volume passenger vehicle production with shorter cycle times.
Steel wheels retain volume leadership; forged wheels hold the steepest expansion curve.
End User:
Procurement concentration varies dramatically by customer technical sophistication and volume scale.
- Automobile Manufacturers:Tier-one OEMs specify wheels through platform-level sourcing agreements with multi-year qualification timelines. Contract structures favor suppliers with captive foundry capacity in China and Eastern Europe.
- Aftermarket Retailers:Independent distributors and specialty shops serve replacement demand and styling upgrades. Inventory exposure concentrates on diameter and bolt pattern fragmentation across regional vehicle parc variations.
- Distributors:Wholesale intermediaries aggregate smaller fleet and repair shop orders.
- Motorsport Teams:Formula and endurance racing programs demand defect-free forged configurations with batch-level material certification.
Automobile manufacturers command procurement volume; motorsport teams generate the highest unit margins.
Application:
Duty cycle severity and regulatory exposure create distinct performance thresholds across vehicle categories.
- Passenger Vehicles:Light-duty fitments prioritize aerodynamic efficiency and styling differentiation. EPA fuel economy standards directly incentivize alloy adoption across sedan and crossover portfolios.
- Commercial Vehicles:Heavy-duty trucks and buses require wheels rated for sustained high-load operation. Fleet operators in India and Brazil resist alloy migration where road conditions punish structural fragility.
- Off-Road Vehicles:Agricultural and construction equipment demands beadlock-compatible rim designs.
- Racing Vehicles:Track applications require thermal management and rapid tire change compatibility.
Passenger vehicles anchor volume demand; racing vehicles exhibit the most rapid specification evolution.
Size:
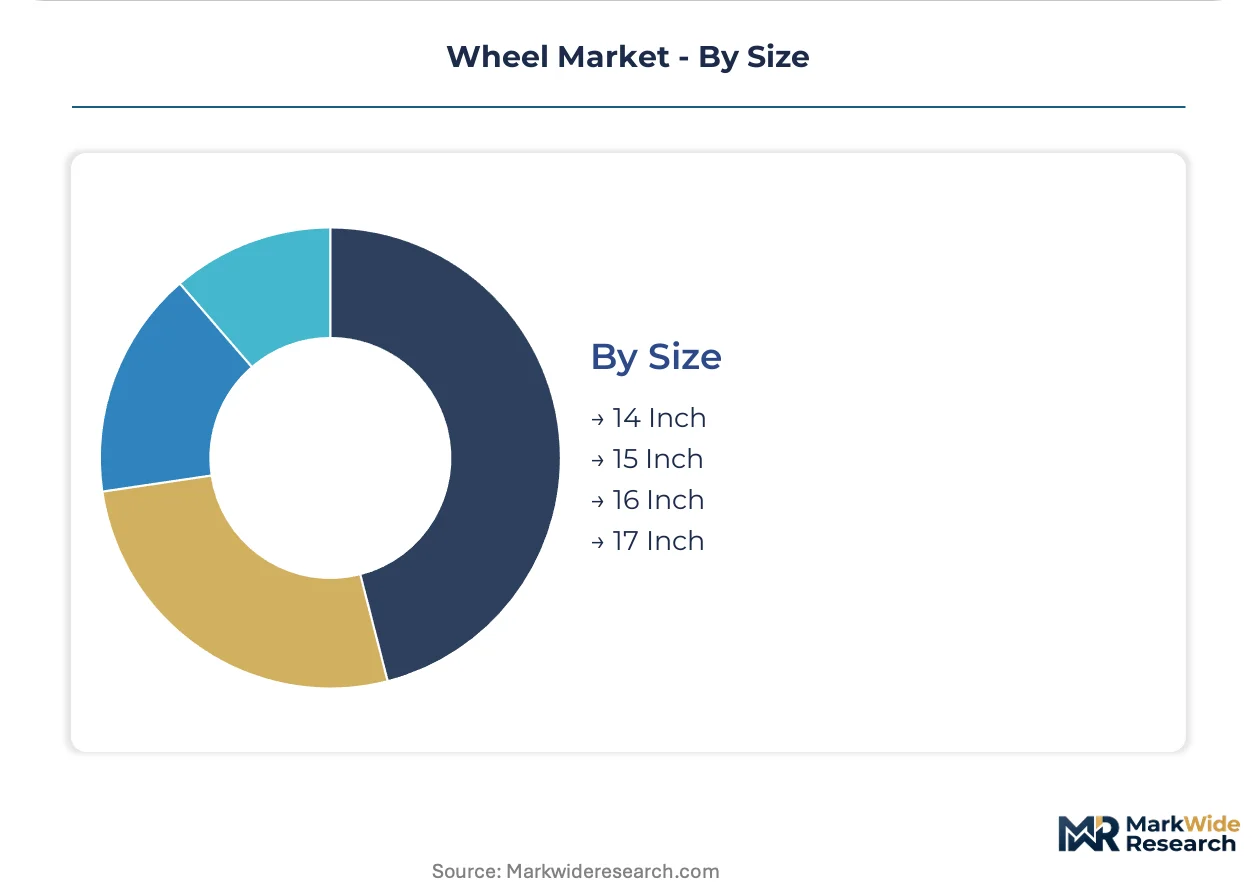
Diameter selection tracks vehicle class segmentation and brake package clearances.
- 14 Inch:Compact car and entry crossover fitments dominate this specification tier.
- 15 Inch:Mid-size sedans and light commercial vehicles standardize around this diameter.
- 16 Inch:Premium compact and standard crossover platforms concentrate procurement here.
- 17 Inch:Performance variants and luxury segments specify this diameter for brake clearance and aesthetic presence.
16-inch configurations hold the broadest vehicle coverage; 17-inch specifications expand most quickly into mass-market platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement departments in Germany anchor premium alloy demand, while Chinese foundry clusters feed export volumes. North American commercial operators sustain steel wheel consumption despite EV-driven substitution elsewhere.
China
Ningbo and Taizhou foundries concentrate aluminum casting capacity for export-oriented automakers. MIIT dual carbon goals pressure smelters to decarbonize primary aluminum inputs. Zhejiang Province suppliers are expanding flow-forming capacity to capture mid-market alloy demand from European EV manufacturers.
Germany
Luxury automakers in Bavaria and Baden-Württemberg specify forged aluminum configurations for performance variants. KBA validation requirements extend qualification timelines for new alloy formulations. Stuttgart supplier ecosystems face die engineering talent scarcity as aging workforces approach retirement.
United States
Commercial fleet operators in the Midwest and Southeast resist alloy migration where repairability outweighs mass reduction. NHTSA fatigue testing standards and EPA fuel economy mandates create conflicting pressures on wheel specification. Detroit-area OEMs are consolidating supplier contracts across multi-platform portfolios.
Japan
Domestic automakers in the Chubu and Kansai regions prioritize rotational mass reduction for hybrid platform efficiency. METI industrial standards govern surface treatment chemistries for corrosion resistance. Nagoya-based suppliers are qualifying trivalent chromium alternatives ahead of anticipated regulatory tightening.
India
Long-haul trucking corridors in Maharashtra and Gujarat present underpenetrated aftermarket demand for lightweight wheel retrofits. BIS certification requirements for commercial vehicle components create entry barriers for unqualified imports. Tamil Nadu automotive clusters are attracting alloy wheel investments serving export markets.
Wheel Market Competitive Landscape
Player mix skews toward European and Asian specialists with captive foundry capacity and established OEM qualification relationships. Market structure exhibits tiered consolidation, with premium forged specialists commanding margin premiums while scale operators compete on cost-engineered steel platforms. Strategic archetypes include flow-forming technology leaders, vertically integrated aluminum smelter-wheel producers, and multi-material portfolio diversifiers. Dominant competitive moves encompass geographic expansion into Chinese industrial corridors and technology licensing agreements for hybrid manufacturing processes.
Within the European specialist tier, Ronal Group and Borbet GmbH exemplify premium-tier positioning through regional casting networks and specialized forming expertise. Ronal Group occupies a position among German luxury automaker supply chains, while Borbet GmbH anchors flow-forming capability for lightweight performance applications. Maxion Wheels sits within the scale-driven segment, representing cost-engineered steel platform specialists serving commercial vehicle fleets across price-sensitive markets. These three entities collectively illustrate the strategic divergence between premium alloy specialization and volume steel competitiveness.
| Leading Market Players |
|---|
| Ronal Group |
| Borbet GmbH |
| Enkei Corporation |
| Maxion Wheels |
| Superior Industries |
| CITIC Dicastal |
| Topy Industries |
| Zhejiang Wanfeng Auto Wheel |
| Steel Strips Wheels |
| Others |
Pricing and Supply Chain Analysis
REACH substance restrictions and ECHA authorization timelines gate both supplier qualification and price differentiation across European wheel procurement. Compliance investments compress margins for coating specialists while creating tiered access premiums for pre-qualified suppliers serving German luxury automakers.
Pricing Analysis
Cast-to-forged-to-flow-formed technology generations define pricing stratification across the wheel market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from OEM platform sourcing. Cost compression in steel wheel tiers is intensifying because EV manufacturers systematically displace carbon steel configurations with aluminum alternatives. Commercial fleet operators exhibit highest price sensitivity, while motorsport teams and German premium OEMs absorb substantial premiums for batch-certified forged configurations.
Supply Chain Analysis
Magnesium smelter concentration in Shanxi Province creates a single-source vulnerability for alloy wheel producers dependent on primary magnesium inputs. Manufacturing gravity draws from China's Ningbo-Taizhou foundry cluster, Germany's Stuttgart supplier ecosystem, and Mexico's export-oriented stamping operations. Raw material dependencies rest on primary aluminum ingot, magnesium alloy billets, and trivalent chromium surface treatment chemistries. Distribution runs through Tier 1 supplier direct-to-OEM contracts, with aftermarket channels fragmenting across regional distributors and specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive production cycles are recovering from inventory destocking, with EV platform proliferation driving replacement demand for lightweight wheel architectures across passenger vehicle portfolios.
For Market Incumbents: Fortify captive foundry capacity in China's Zhejiang Province to secure raw material access and accelerate flow-forming technology adoption. Deepen backward integration into aluminum scrap reprocessing to capture EU Green Deal recycled content premiums. Defend against emerging Chinese export-oriented specialists by accelerating TÜV and KBA heat treatment certification pipelines.
For New Entrants and Emerging Players: Lead with flow-forming hybrid process licensing to access mid-market pricing tiers previously unreachable by pure cast or pure forged specialists. Target India's underpenetrated long-haul trucking corridors with steel-alternative retrofit programs. Establish go-to-market partnerships with Tamil Nadu automotive clusters serving export markets.
For Investors and Strategic Acquirers: EU carbon border adjustment implementation reshapes the acquisition landscape toward suppliers with captive decarbonized aluminum supply. Long-term viability favors vertically integrated specialists with OEM qualification relationships and multi-platform contract structures. Monitor MIIT dual carbon goal enforcement timelines as the inflection signal for Chinese supplier competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Flow-Forming Capacity Expansion | Captures mid-market alloy demand from European EV manufacturers seeking forged performance at cast economics. |
| Closed-Loop Aluminum Recycling | Positions suppliers ahead of EU Green Deal recycled content mandates with captive scrap reprocessing infrastructure. |
| Trivalent Chromium Coating Qualification | Ensures REACH compliance for European market access ahead of hexavalent chromium phase-out deadlines. |
| India Commercial Vehicle Retrofit Program | Addresses underpenetrated aftermarket demand in Maharashtra and Gujarat long-haul corridors. |
| Die Engineering Talent Acquisition | Offsets aging workforce concentration in Stuttgart and Turin supplier ecosystems. |
Research Methodology
Operator-level perspectives from Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and foundry operations managers anchored the qualitative base. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from publicly traded wheel manufacturers. Bottom-up demand modeling triangulated against top-down industry aggregation across material type, end-user category, and regional production cluster dimensions.
Sensitivity analysis tested forecast outputs against alternative EV penetration trajectories and magnesium price volatility scenarios throughout the forecast period. Segmentation dimensions modeled include material specification, manufacturing process, vehicle class, propulsion architecture, and regional regulatory cluster. CAGRs derived from installed base rotation rates and replacement cycle analysis, with EV platform proliferation and EPA fuel economy standards as primary demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained EV adoption acceleration or prolonged magnesium supply disruption would require recalibration. Forecasts reflect documented assumptions regarding OEM platform sourcing timelines and regulatory enforcement trajectories. Practitioners should keep alternative scenarios live as REACH authorization timelines and MIIT dual carbon enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
High Performance Wheels Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Self-Sealing Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Automotive Intelligent Tires Market