
 Europe Paper Packaging Market | 2026-2036
Europe Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Paper Packaging Market Intelligence
Barrier-coated paper technology is rewriting how moisture-sensitive goods ship without plastic laminates. Mondi Group leverages its integrated kraft pulp network to supply grease-resistant grades for protein packs. Smurfit Westrock anchors European corrugated volume through its recycled containerboard mills in Ireland and the Netherlands. Lucart S.p.A. specializes in natural greaseproof papers derived from certified fiber streams for quick-service chains.
Europe paper packaging comprises engineered fiber-based structures—typically 80–400 gsm kraft, testliner, or coated grades—formed through corrugating, folding, or thermo-molding processes to contain, protect, and present goods across supply chains. Kraft paper grades dominate fresh produce and e-commerce void fill where tear resistance and printability matter equally. Recycled paper feeds the corrugated backbone of grocery retail and industrial shipping, though contamination thresholds limit closed-loop recovery rates. Food and beverage end users drive format innovation as brands eliminate polyethylene windows and switch to fiber-based transparent films.
EMA, ECHA, and the EU Packaging and Packaging Waste Regulation collectively enforce recyclability targets, extended producer responsibility fees, and restricted substance lists that determine which paper structures qualify for circular labeling. REACH compliance on coating chemistries and the EU Green Deal's 2035 packaging neutrality goals push converters toward water-based barriers and mono-material designs. Stakeholders must track how delegated acts under the revised PPWR redefine 'recyclable by design' before committing capital to new coating lines or regional mill upgrades.
Market Dynamics
Barrier-coated paper technology is compressing plastic laminate demand across European fresh food supply chains. ECHA's evolving restricted substance list under REACH is forcing converters to abandon fluorochemical barriers before 2025 compliance deadlines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability-by-design mandates are pulling fiber-based tray formats into German protein retail chains. Mondi Group's integrated kraft pulp network supplies grease-resistant grades meeting these specifications.
- Quick-service restaurant chains:Natural greaseproof paper demand from certified fiber streams is accelerating across France, Italy, and Spain. Lucart S.p.A.'s specialized production lines serve this segment directly.
- Lyon pharmaceutical corridor:Sterile barrier paper formats for medical device packaging are concentrating demand in France's Rhône-Alpes cluster. EMA's device packaging guidelines favor fiber-based sterile barriers.
Market Restraints
- Recycled fiber contamination thresholds:Closed-loop recovery rates for corrugated grocery retail packaging remain structurally capped. Recycled containerboard mills in Ireland and the Netherlands face input quality constraints.
- Polyethylene window substitution lag:Fiber-based transparent films for food and beverage display packaging carry 15-40% cost premiums versus plastic laminates. Brand procurement teams delay full conversion.
- Water-based barrier performance gaps:Moisture vapor transmission rates for protein packs in chilled supply chains exceed acceptable thresholds during extended distribution. Converters retain hybrid structures.
Strategic Opportunities
- Poland and Romania e-commerce void fill:Kraft paper grades for protective packaging remain underpenetrated in Central European fulfillment networks. Tear-resistant 120-200 gsm specifications offer entry points.
- EU Green Deal packaging neutrality incentives:Delegated acts under the revised PPWR will reward mono-material designs with reduced extended producer responsibility fees. Early coating line investments capture this tailwind.
- Pharmaceutical serialization convergence:Integration of fiber-based packaging with track-and-trace inkjet systems creates white space in secondary packaging. Smart paper substrates with embedded markers enable authentication.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for water-based barriers that match silicone release properties resides with a narrow specialist pool. Mill R&D teams compete for experienced hires.
- Regional mill upgrade capex cycles:Thermo-molding equipment for fiber-based tray formats requires 18-24 month installation timelines. Capital commitment precedes delegated act clarity on recyclability definitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Paper Packaging Market |
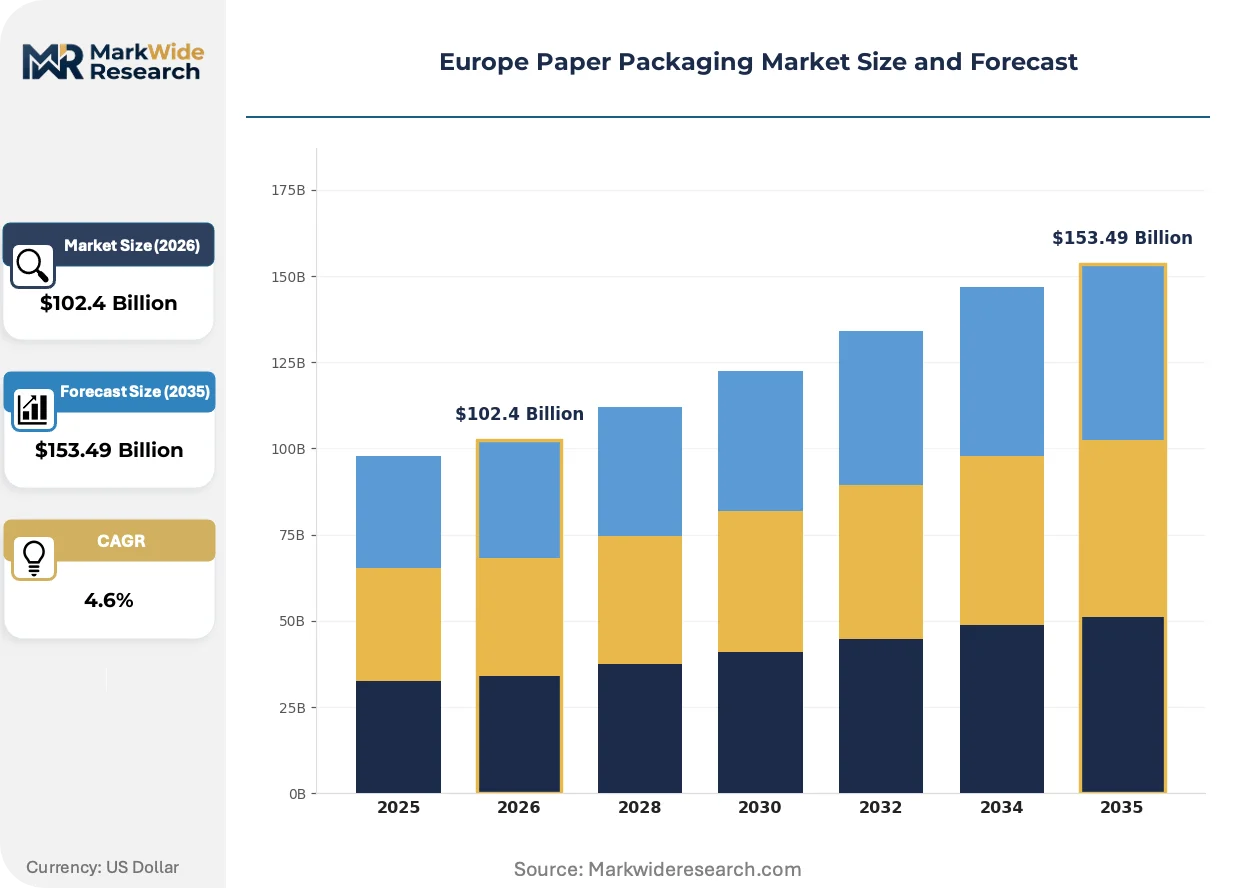
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $153.49 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wraps, Pallets End User: Food & Beverage, Healthcare, Consumer Goods, Retail Material: Kraft Paper, Recycled Paper, Coated Paper, Cardboard Application: Packaging, Printing, Labeling, Shipping |
| Companies Covered | Mayr-Melnhof Karton AG, Progroup AG, Mondi Group, Lucart S.p.A., Graphic Packaging Holding Company, Smurfit Westrock, Svenska Cellulosa Aktiebolaget SCA, Palm GmbH & Co. KG, International Paper Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Paper Packaging Market Strategic Shifts & Innovations
Digital printing integration is collapsing minimum order quantities for customized corrugated displays. Fiber-based packaging is digitizing across three parallel vectors: production workflow, regulatory compliance, and buyer-procurement interfaces.
High-speed inkjet systems for direct-to-corrugate printing are digitizing short-run brand campaigns that previously required flexographic plate costs. German discount grocery chains now order seasonal displays in sub-5,000 unit batches. Lead times compress from six weeks to seventy-two hours.
CSRD disclosure requirements are digitizing supply chain traceability for paper packaging converters. Scope 3 emissions reporting mandates fiber provenance documentation from certified sources. French pharmaceutical packagers near Lyon deploy blockchain-linked batch records to satisfy auditor demands.
Brand procurement teams are consolidating supplier panels and demanding outcome-based packaging performance contracts. Unit-price negotiations give way to total cost-of-damage metrics. Dutch corrugated volume buyers now penalize suppliers for in-transit product loss rather than rewarding lowest per-unit bids.
Europe Paper Packaging Market Segmentation
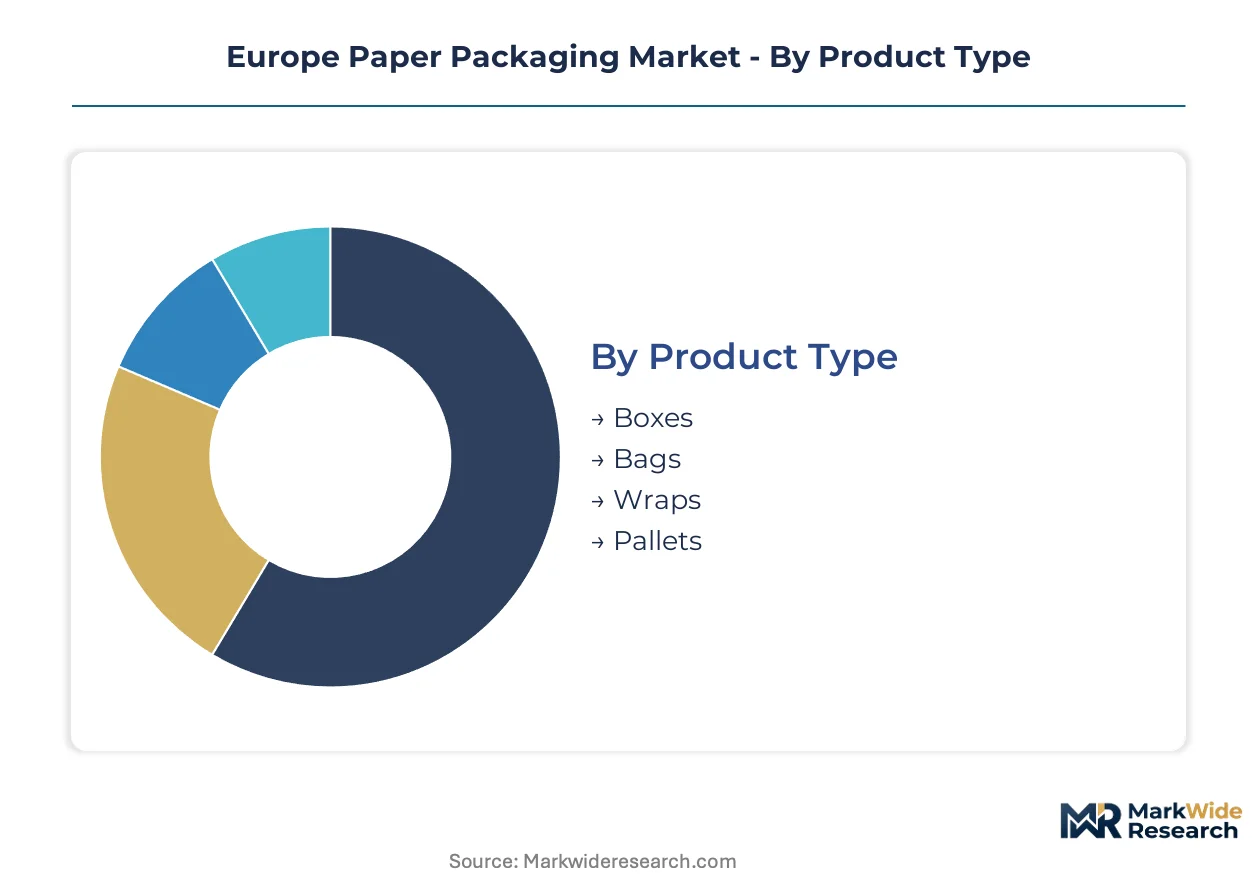
Europe paper packaging demand fragments across product formats, end-use sectors, and material specifications. Each segment carries distinct technical requirements and regulatory exposure under EU Packaging and Packaging Waste Regulation mandates. Procurement teams prioritize segments with proven recyclability credentials and established collection infrastructure.
Product Type:
After-sales-service intensity varies sharply across product categories, with corrugated boxes demanding field engineering support for automated fulfillment integration while bags and wraps require minimal technical assistance beyond specification guidance.
- Boxes:Corrugated and solid fiberboard structures span 80–400 gsm grades for containment and stacking strength. German discount grocery chains deploy seasonal display boxes in sub-5,000 unit batches through digital print workflows. Demand concentrates in automated e-commerce fulfillment networks where dimensional optimization reduces shipping costs.
- Bags:Multiwall sacks and pinch-bottom formats handle 10–50 kg industrial payloads. French agricultural cooperatives specify natural kraft bags for grain and feed distribution. Recycled fiber content thresholds limit closed-loop recovery rates for grocery retail applications.
- Wraps:Grease-resistant and barrier-coated sheets protect moisture-sensitive goods. Lucart S.p.A. supplies certified fiber streams to quick-service chains across Italy and Spain.
- Pallets:Honeycomb and corrugated fiberboard platforms substitute wooden units in closed-loop pool systems. Lightweight designs reduce air freight surcharges for pharmaceutical exports from Lyon.
By volume, Boxes leads. By growth pace, Wraps is expanding most quickly as protein retail chains eliminate plastic laminates.
End User:
Cost tier differentiation separates premium pharmaceutical specifications from commodity grocery formats, with healthcare buyers paying 15–40% premiums for sterile barrier compliance.
- Food & Beverage:Chilled supply chains drive barrier-coated tray demand. Fresh food chains across Germany switch to fiber-based formats as ECHA fluorochemical deadlines approach.
- Healthcare:Sterile barrier papers for medical device packaging dominate France's Rhône-Alpes corridor. EMA guidelines favor fiber-based sterile barriers over polymer alternatives.
- Consumer Goods:E-commerce void fill specifications prioritize tear-resistant 120–200 gsm kraft grades. Polish and Romanian fulfillment networks remain underpenetrated.
- Retail:Point-of-sale displays integrate high-speed inkjet for campaign customization. Dutch corrugated buyers now penalize suppliers for in-transit damage rather than rewarding lowest unit bids.
Food & Beverage generates the highest absolute tonnage. Healthcare climbs the fastest as serialization and authentication requirements expand.
Material:
Supply concentration favors integrated kraft pulp networks in Nordic and Iberian regions, while recycled paper feeds depend on municipal collection quality.
- Kraft Paper:Virgin fiber delivers tear resistance and printability for produce and protective packaging. Mondi Group's integrated network supplies grease-resistant grades to protein packers.
- Recycled Paper:Testliner and fluting grades form the corrugated backbone. Mills in Ireland and the Netherlands face input contamination constraints.
- Coated Paper:Water-based barrier formulations replace polyethylene windows. Performance gaps in moisture vapor transmission rates delay full conversion.
- Cardboard:Folding carton and rigid box formats serve premium cosmetics and pharmaceuticals. CSRD disclosure mandates drive fiber provenance documentation.
Recycled Paper dominates tonnage. Coated Paper gains share fastest as REACH compliance forces fluorochemical abandonment.
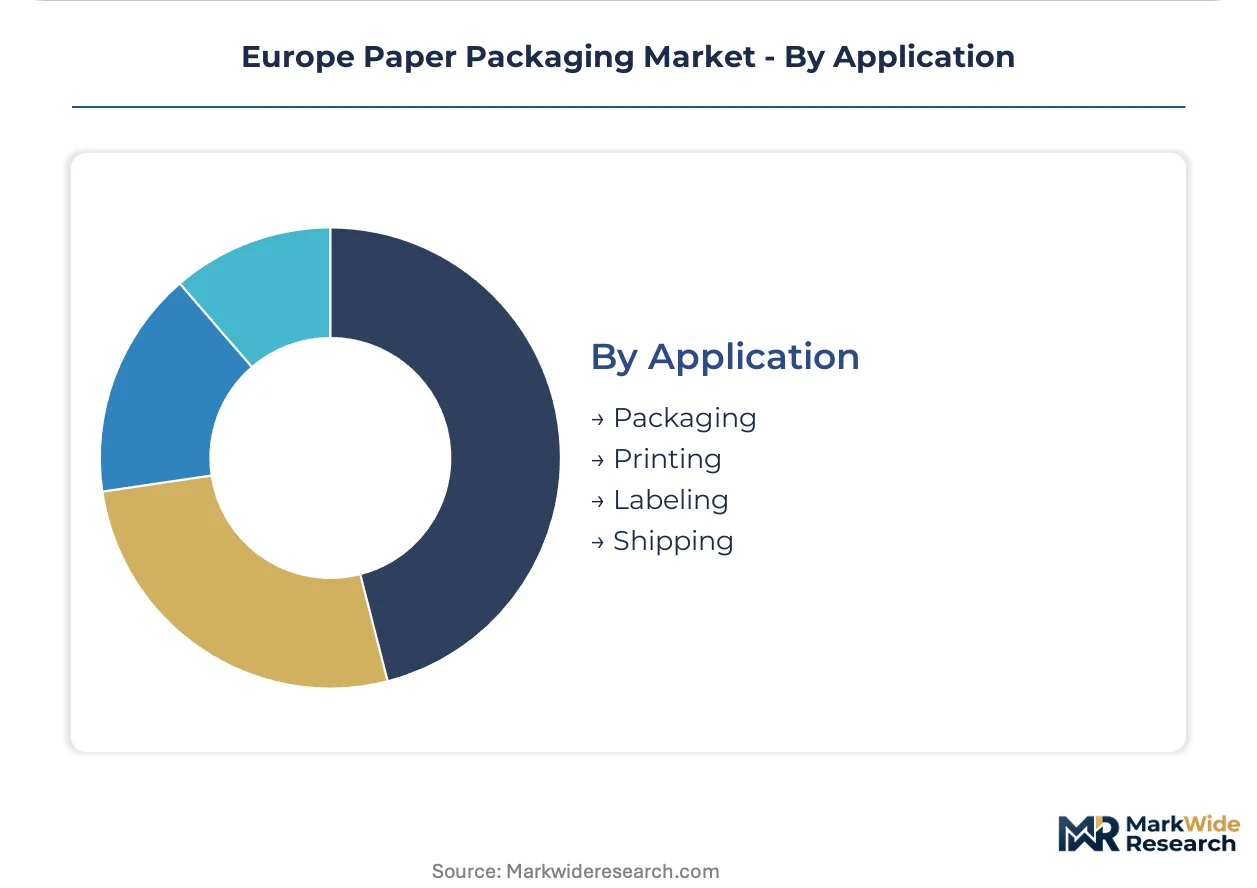
Application:
Customer type separates brand-owner specifications from converter procurement, with direct retail relationships demanding outcome-based performance contracts.
- Packaging:Primary and secondary containment functions span tray, carton, and sack formats. EU Green Deal packaging neutrality incentives reward mono-material designs with reduced extended producer responsibility fees.
- Printing:Direct-to-corrugate inkjet collapses minimum order quantities. Lead times compress from six weeks to seventy-two hours for seasonal campaigns.
- Labeling:Smart paper substrates with embedded markers enable pharmaceutical authentication. Blockchain-linked batch records satisfy auditor demands near Lyon.
- Shipping:Protective void fill and dunnage specifications prioritize tear resistance. Central European fulfillment networks offer entry points for kraft grade suppliers.
Packaging absorbs the greatest material volume. Labeling shows the steepest expansion trajectory as serialization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish kraft paper exports flow into German e-commerce fulfillment networks, creating a trade corridor that reshapes Central European supply dynamics. This cross-border fiber movement concentrates capacity planning around corridor nodes rather than national boundaries.
Germany
Discount grocery chains digitize corrugated display procurement through sub-5,000 unit batch orders. ECHA fluorochemical deadlines under REACH force protein packers to abandon plastic laminates by 2025. Fresh food retail clusters in North Rhine-Westphalia convert to fiber-based tray formats.
France
Pharmaceutical serialization mandates expand sterile barrier paper demand for medical devices. EMA packaging guidelines favor fiber-based sterile barriers over polymer alternatives. The Lyon-Rhône-Alpes corridor concentrates contract packaging operations serving export markets.
Italy
Quick-service restaurant chains source natural greaseproof papers from certified fiber streams. CSRD disclosure requirements push converters toward blockchain-linked batch documentation. Northern Italian packaging districts near Milan supply barrier-coated formats for chilled protein distribution.
Netherlands
Recycled containerboard mills face input contamination thresholds that cap closed-loop recovery rates. EU Green Deal packaging neutrality incentives reward mono-material designs with reduced extended producer responsibility fees. Rotterdam-area converters test water-based barrier formulations for export specifications.
Poland
E-commerce void fill specifications for tear-resistant 120-200 gsm kraft grades remain underpenetrated in fulfillment networks. Delegated acts under the revised PPWR create regulatory uncertainty ahead of recyclability definition finalization. Warsaw logistics hubs anchor Central European protective packaging distribution.
Europe Paper Packaging Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct capability tiers. Integrated pulp-to-packaging networks anchor volume positions in kraft and containerboard grades. Specialist converters occupy niches in barrier-coated formats and pharmaceutical sterile barriers. Strategic moves concentrate on coating line investments for water-based barriers and thermo-molding equipment for fiber-based tray expansion.
Among Austria-based integrated producers, Mayr-Melnhof Karton AG exemplifies the channel-controlling archetype through captive board supply. Mondi Group and Smurfit Westrock occupy positions spanning multiple European geographies with mill networks that straddle recycled and virgin fiber streams. These three entities represent the scale-driven tier where backward integration into pulp generation defines competitive position.
| Leading Market Players |
|---|
| Mayr-Melnhof Karton AG |
| Progroup AG |
| Mondi Group |
| Lucart S.p.A. |
| Graphic Packaging Holding Company |
| Smurfit Westrock |
| Svenska Cellulosa Aktiebolaget SCA |
| Palm GmbH & Co. KG |
| International Paper Company |
| Others |
Cost & Logistics Intelligence
Nordic integrated kraft pulp networks anchor upstream supply concentration, directing margin pools toward barrier-coated specialty grades and away from commodity containerboard. German discount grocery chains and French pharmaceutical packers capture downstream value through specification control, while recycled fiber mills in Ireland and the Netherlands face persistent input quality constraints that compress their pricing power.
Pricing Analysis
Prior-generation polyethylene-laminated formats trade at 15-40% discounts to emerging water-based barrier grades, though next-generation mono-material designs command premium positioning as EU Green Deal incentives reduce extended producer responsibility fees. Three-tier pricing structure across premium sterile barriers, standard corrugated, and economy recycled grades reflects certification level and fiber provenance documentation. Pricing pressure stems from fluorochemical abandonment deadlines under ECHA's REACH restrictions, forcing converters to absorb reformulation costs. Quick-service restaurant chains exhibit highest price sensitivity due to thin operating margins, while pharmaceutical buyers near Lyon accept substantial premiums for EMA-compliant sterile barrier compliance.
Supply Chain Analysis
Export-control regimes on fluorochemical barrier technologies limit technology transfer to non-EU coating specialists, reshaping equipment procurement patterns. Geographic supply concentrates in Sweden, Finland, and Austria for virgin kraft pulp, with Germany and Italy hosting downstream converting capacity. Raw material dependencies center on certified fiber streams, water-based barrier chemistries, and thermo-molding equipment components. Single-source vulnerability runs through specialized coating chemist talent pools concentrated in German and Dutch mill R&D centers. Distribution runs through Rotterdam and Hamburg port complexes for Atlantic trade, with overland corridors serving Central European fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
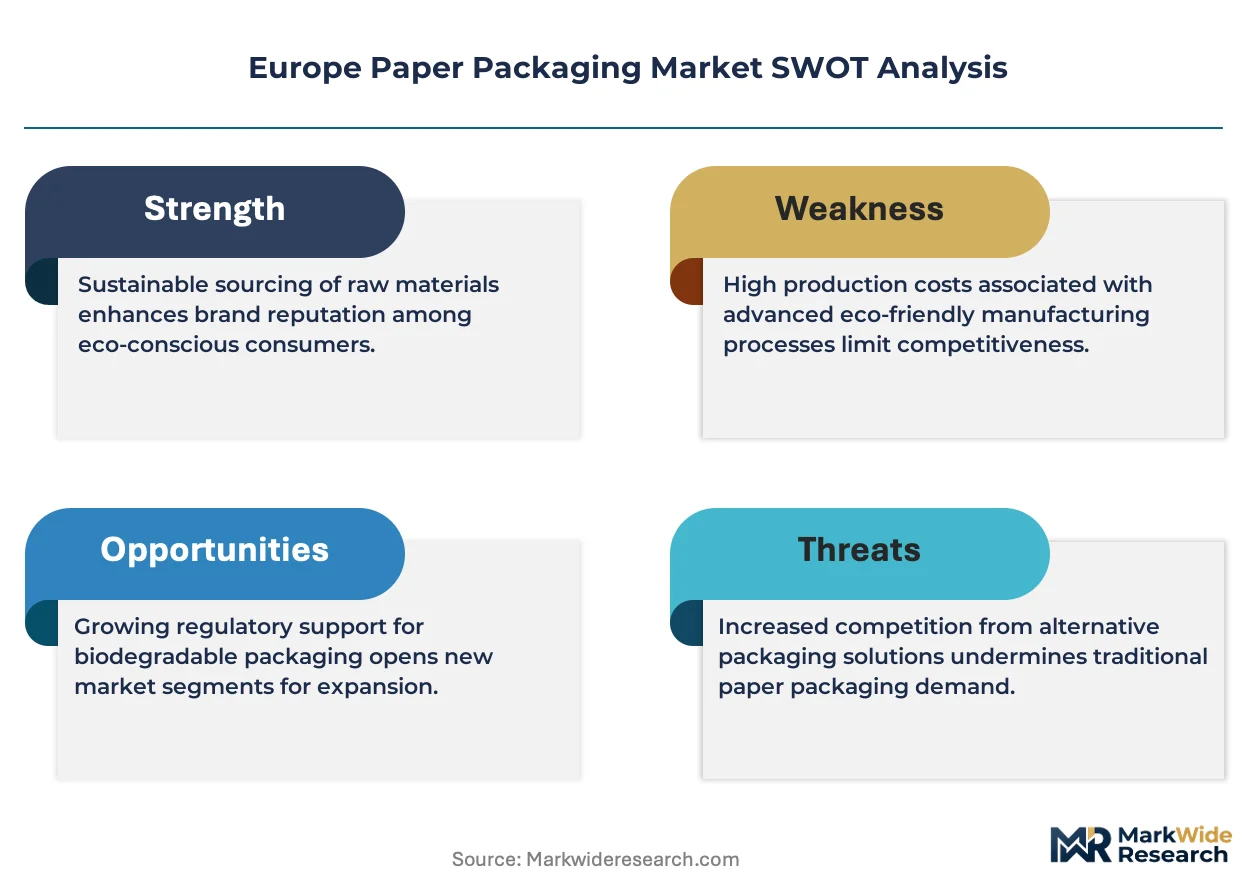
Plastic laminate substitution represents the core defensive imperative for fiber-based packaging incumbents, as polyethylene window retention in food and beverage display applications threatens volume erosion. Market participants must navigate this substitution threat through capability investments that close performance gaps in moisture vapor transmission rates.
For Market Incumbents: Build regulatory moats through early water-based barrier line investments that capture delegated act clarity on recyclability definitions before competitors commit capital. Mondi Group's integrated kraft pulp network demonstrates how backward integration into certified fiber sourcing defends margin position against input cost volatility. Prioritize thermo-molding equipment installation for fiber-based tray formats in German protein retail corridors where ECHA fluorochemical deadlines accelerate format conversion.
For New Entrants and Emerging Players: Build out protective packaging capabilities in Polish and Romanian e-commerce fulfillment networks where tear-resistant 120-200 gsm kraft specifications remain underpenetrated. Target quick-service restaurant chains in Italy and Spain through natural greaseproof paper offerings that leverage Lucart S.p.A.'s certified fiber stream model as a reference architecture. Pursue outcome-based performance contracts with Dutch corrugated buyers that penalize in-transit damage rather than competing on unit price.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across barrier-coated specialty grades as coating line investments and thermo-molding equipment absorb disproportionate capital deployment. Long-term viability favors integrated pulp-to-packaging networks with captive fiber supply and established pharmaceutical sterile barrier relationships. Acquisition targets should display water-based barrier formulation expertise and EMA-compliant production infrastructure. Monitor ECHA delegated act publication timelines as the critical inflection signal for recyclability definition finalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Line Investment | Captures EU Green Deal packaging neutrality incentives before delegated act clarity emerges. |
| Certified Fiber Stream Integration | Secures CSRD-compliant provenance documentation for pharmaceutical and quick-service restaurant supply. |
| Thermo-Molding Equipment Deployment | Enables fiber-based tray formats for German protein retail chains facing ECHA fluorochemical deadlines. |
| Digital Print Workflow Integration | Collapses minimum order quantities for German discount grocery seasonal display campaigns. |
| Pharmaceutical Serialization Convergence | Positions fiber-based substrates for Lyon-Rhône-Alpes track-and-trace inkjet system integration. |
Research Approach
The analysis maps kraft paper grades, recycled containerboard, barrier-coated formats, and sterile barrier papers, each validated through mill operations directors, brand procurement managers, and regulatory affairs specialists at EMA and ECHA. Primary interviews with quick-service restaurant supply chain heads and pharmaceutical packaging engineers in the Lyon corridor combined with secondary validation from EU Packaging and Packaging Waste Regulation delegated act drafts, CSRD disclosure frameworks, and REACH compliance databases. Bottom-up fiber grade demand modeling triangulated against top-down corrugated volume estimates from Irish and Dutch mill networks.
Assumption sets held ECHA fluorochemical restriction timelines and EU Green Deal packaging neutrality incentive structures fixed while varying fiber contamination threshold scenarios and e-commerce fulfillment network penetration rates across the projection horizon. Segmentation dimensions modeled include product format, end-use sector, material specification, and regional regulatory cluster. CAGRs derived from volume-weighted average growth across fiber grade categories, with specific inputs including barrier-coated paper adoption curves in German fresh food retail and pharmaceutical serialization mandate implementation in France.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by integrated Nordic pulp networks or accelerated fluorochemical substitution by plastic laminate producers would shift outcomes. Material shifts in ECHA delegated act finalization timelines or REACH coating chemistry restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
Kitchen Roll Market
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
Tracing Paper Market