
 Commercial Paper Bags Market | 2026-2036
Commercial Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Paper Bags Market Outlook
Aftermarket custom-printing services is reshaping margin pools away from commodity plain bags toward branded packaging solutions. Smurfit Kappa leverages its European corrugated network to anchor paper bag distribution across grocery and retail channels. International Paper sustains manufacturing scale through integrated pulp-to-bag operations in North America. Mondi competes on specialty barrier coatings that extend paper bag utility into grease-resistant food service applications.
Commercial paper bags are fabricated from kraft paper, typically ranging from 30 to 120 grams per square meter in basis weight, using multiwall or single-ply construction with twisted paper handles or die-cut grips for load-bearing capacity; they serve as primary consumer-facing packaging for retail merchandise, prepared foods, and wholesale goods distribution. Block bottom bags occupy the dominant structural position in grocery and bulk retail due to their self-standing geometry and stacking efficiency. Biodegradable packaging types capture the fastest expansion as restaurants and food service operators face mandates to eliminate conventional plastic. Custom printed variants concentrate margin pools through brand-owner willingness to pay premium unit economics for differentiated shelf presence.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance requirements in the United States impose divergent compliance pathways that fragment formulation standards and testing protocols across Atlantic supply chains. REACH chemical restrictions and state-level extended producer responsibility laws in California and New York further complicate material sourcing decisions for multinational converters. Stakeholders must monitor evolving biodegradability certification schemes and substrate weight reduction targets that will determine which production assets retain competitive viability through the forecast horizon.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing plastic bag volumes while redirecting food service procurement toward fiber-based alternatives, forcing converters to requalify barrier coatings and substrate grades across Atlantic supply chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Binding reduction targets for single-use plastics are compelling quick-service restaurants to convert carryout operations to paper-based solutions ahead of statutory deadlines.
- Kraft pulp availability:Sustained capacity expansion in Nordic and North American pulp mills is stabilizing input costs for bag manufacturers serving grocery and retail channels.
- Quick-service restaurant channel:Major chains in Germany and the United States are mandating sustainable packaging transitions across franchise networks, creating concentrated demand pull for grease-resistant paper bag constructions.
Market Restraints
- Pulp price volatility:Energy cost spikes and logistics disruptions in Scandinavian supply corridors transmit directly to bag converter margins, compressing working capital flexibility.
- Barrier coating technical limitations:Current water-based and bio-based coatings fail to match polyethylene grease resistance at high-temperature food contact, restricting paper bag penetration in fried food segments.
- REACH chemical restrictions:ECHA substance evaluations are disqualifying legacy fluorinated treatments, forcing reformulation cycles that delay product requalification with major retail buyers.
Strategic Opportunities
- California extended producer responsibility laws:State-level packaging fee structures are incentivizing lightweight substrate development and closed-loop collection systems for grocery bag applications.
- E-commerce secondary packaging:Corrugated-to-paper bag substitution in last-mile delivery is opening volume opportunities for block-bottom constructions with enhanced tear resistance.
- Digital print convergence with barrier coating:Inline flexographic systems are enabling short-run customization for regional retail chains previously served by plain commodity bags.
Industry Challenges
- Compostability certification timelines:Multi-jurisdiction validation requirements for TÜV OK Compost and BPI labels are extending new product introduction cycles by 8-14 months.
- Skilled technician scarcity:Operators capable of calibrating high-speed bottomer machines with precision glue pattern control command premium wages in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Paper Bags Market |
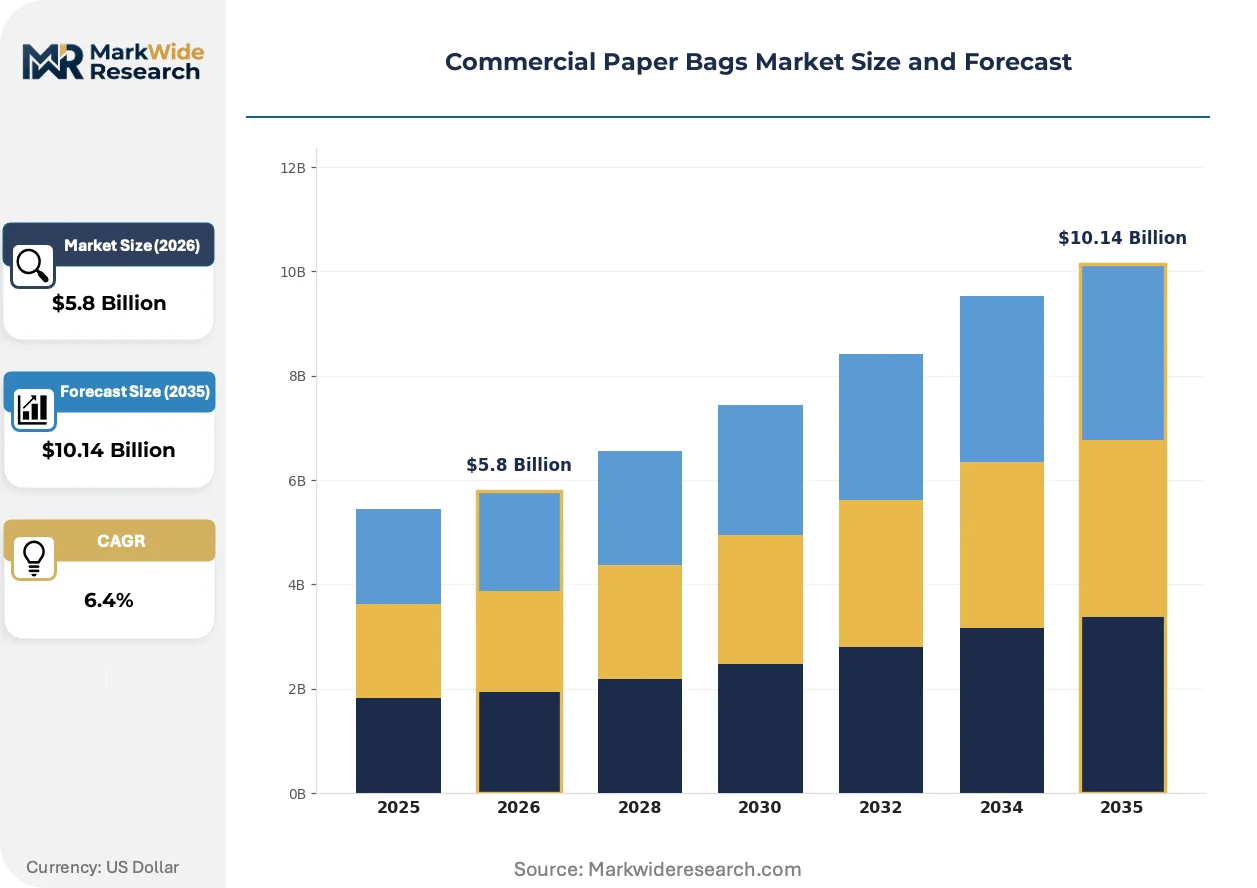
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
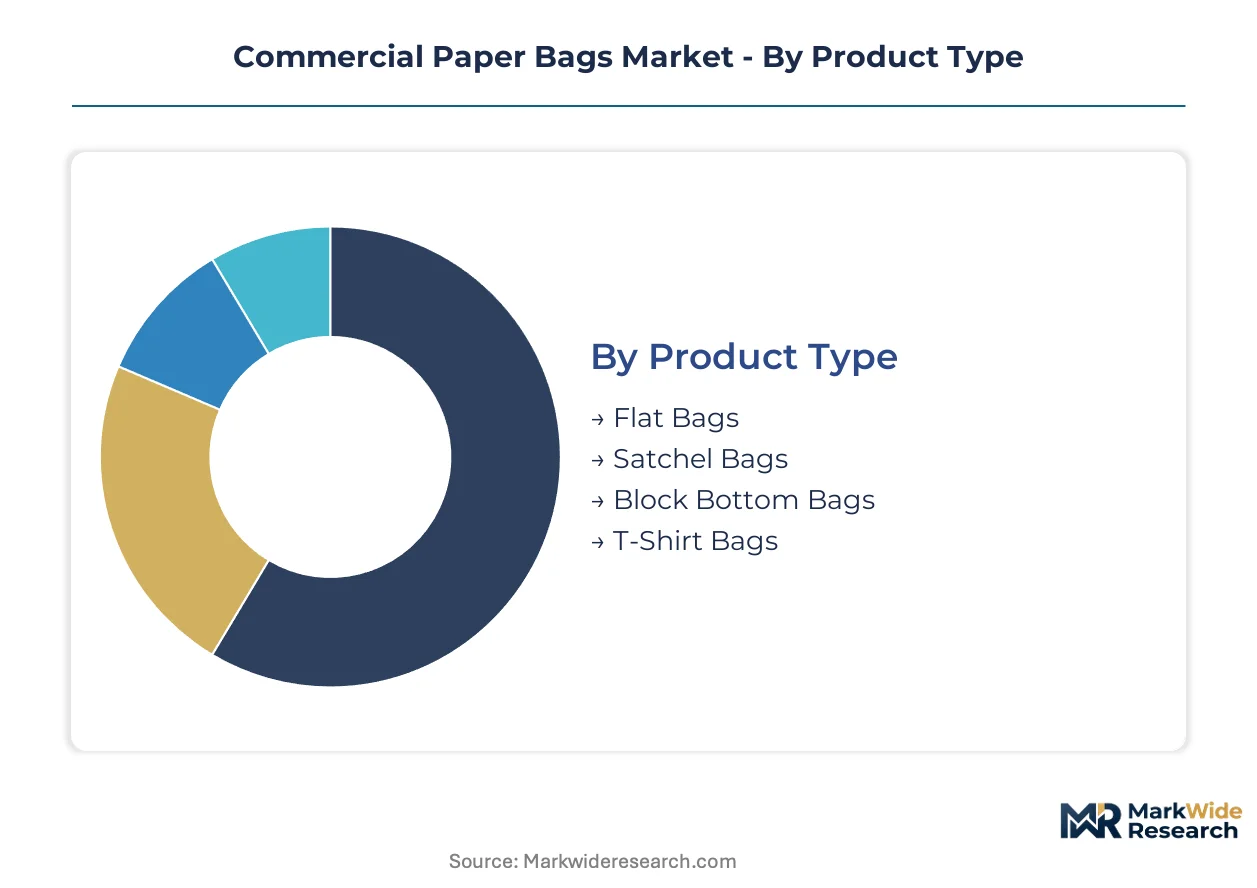
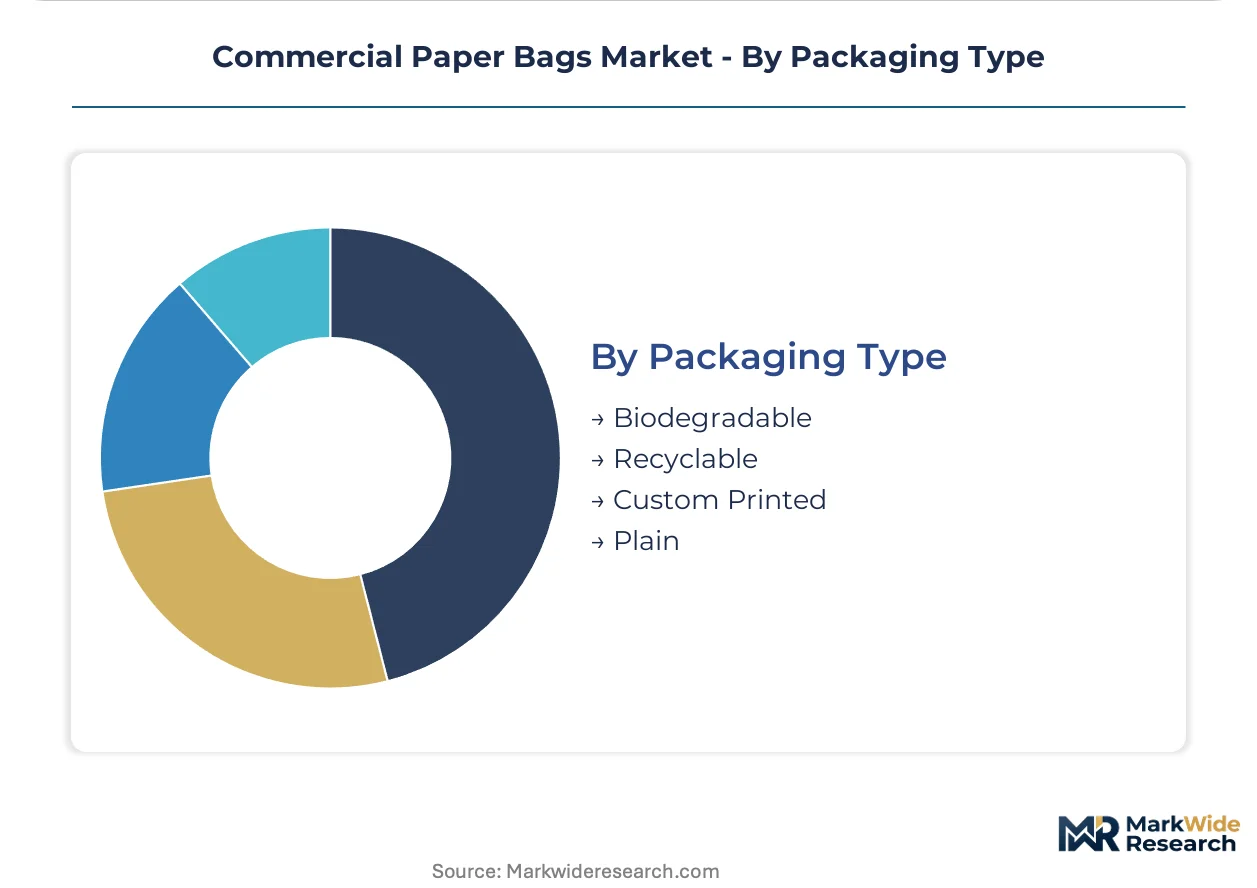
| Segmentation | Product Type: Flat Bags, Satchel Bags, Block Bottom Bags, T-Shirt Bags Application: Retail, Food Service, Wholesale, Industrial Packaging End User: Restaurants, Grocery Stores, E-Commerce, Manufacturers Packaging Type: Biodegradable, Recyclable, Custom Printed, Plain |
| Companies Covered | International Paper, Smurfit Kappa, Mondi, WestRock, Novolex, DS Smith, Oji Holdings Corporation, Stora Enso, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Paper Bags Market Strategic Shifts
Digital workflow integration is collapsing traditional prepress timelines while enabling mass customization at unit economics previously reserved for long-run commodity production.
Water-based barrier coatings with nanoparticle clay reinforcement are virtualizing the functional performance of conventional polyethylene laminates. Quick-service chains in Germany and France are specifying these constructions for hot sandwich and fried food applications. The technology is virtualizing the historical trade-off between recyclability and grease resistance, permitting municipal paper stream disposal without separation requirements.
REACH restriction proposals targeting per- and polyfluoroalkyl substances are eliminating legacy oil-repellent chemistries from food-contact applications. Bag converters face forced migration to silicone-based or bio-wax alternatives with inferior performance profiles. Prepared food operators in Northern Europe are responding by shortening specification renewal cycles and demanding accelerated qualification data from substrate suppliers.
Brand-owner procurement teams are consolidating vendor relationships around converters offering integrated design-to-delivery platforms. Regional grocery cooperatives are displacing fragmented local supply arrangements with multi-year framework agreements spanning private-label and promotional bag programs. This concentration is most visible in United States Midwest markets where retailer-owned distribution networks favor single-source accountability for quality and compliance documentation.
Commercial Paper Bags Market Segmentation
Paper bag specifications diverge sharply across end-use contexts, with structural geometry and barrier performance determining competitive viability in each channel. Segmentation reveals how converters allocate capital between mature commodity formats and emerging premium constructions.
Product Type:
Mature formats dominate volume flows while emerging geometries capture specification upgrades in regulated channels.
- Block Bottom Bags:Self-standing square-base construction using 70-120 gsm kraft with multiwall reinforcement enables vertical stacking in grocery aisles and warehouse racking. German and United States supermarket chains mandate this format for private-label bulk goods, driving concentrated demand pull from centralized procurement teams.
- T-Shirt Bags:Die-cut handle designs with twisted paper grips serve quick-service restaurant carryout operations requiring one-handed load bearing. Chains across France and California specify grease-resistant barrier coatings for hot food contact, pushing substrate innovation toward bio-wax and nanoparticle clay alternatives.
- Flat Bags:Single-ply 30-50 gsm constructions without gussets handle lightweight retail merchandise and document protection.
- Satchel Bags:Envelope-style closures with adhesive strips target apparel and soft goods distribution in e-commerce secondary packaging.
Block Bottom Bags handles the majority of throughput; T-Shirt Bags is the fastest mover on share.
Application:
Cost tier stratification separates premium food-contact specifications from economy wholesale bulk handling.
- Food Service:Grease-resistant barrier coatings and FDA food-contact compliance distinguish quick-service restaurant specifications from commodity retail formats. Nordic pulp integration enables converters to meet California and New York state mandates for fiber-based alternatives to polyethylene.
- Retail:Custom-printed block bottom constructions with four-color flexography serve brand-owner shelf presence requirements in United States Midwest grocery cooperatives.
- Wholesale:Plain unprinted multiwall bags with twisted handles handle bulk dry goods distribution for industrial procurement.
- Industrial Packaging:Heavy-duty 120 gsm constructions with reinforced seams protect hardware and automotive components during transit.
Food Service commands the steepest expansion trajectory; Retail retains the largest installed base of converting assets.
End User:
Customer type concentration shapes converter sales force deployment and technical service intensity.
- Grocery Stores:Private-label block bottom programs with seasonal promotional variations require high-volume, low-changeover production lines. United States retailer-owned distribution networks favor single-source accountability spanning design-to-delivery documentation.
- Restaurants:Quick-service chains in Germany and France specify short-run digital print capabilities for regional menu variations alongside standardized barrier performance.
- E-Commerce:Corrugated-to-paper substitution in last-mile delivery drives demand for tear-resistant satchel constructions with inline tracking codes.
- Manufacturers:Industrial procurement teams prioritize unit cost minimization over print customization, sourcing plain multiwall formats through competitive tender.
Grocery Stores anchor volume commitments; Restaurants generate the fastest specification upgrade cycles.
Packaging Type:
Margin tier separation between certified sustainable formats and commodity plain constructions determines converter portfolio strategy.
- Biodegradable:TÜV OK Compost and BPI certification requirements extend new product introduction timelines but unlock premium positioning in EU-regulated channels. Water-based coatings with clay nanoparticle reinforcement match polyethylene grease resistance without compromising municipal paper stream compatibility.
- Custom Printed:Inline flexographic systems enable mass customization at unit economics previously reserved for long-run commodity production, collapsing traditional prepress timelines for regional retail chains.
- Recyclable:Standard kraft constructions without barrier coatings serve price-sensitive wholesale and industrial segments.
- Plain:Unprinted single-ply bags compete on substrate weight and handle tensile strength alone.
Biodegradable formats capture the fastest share gains; Custom Printed variants concentrate margin pools away from commodity plain bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France absorb premium pricing for certified biodegradable formats without volume elasticity, while procurement teams in India and Southeast Asia prioritize unit cost minimization over barrier performance specifications.
United States
Quick-service restaurant chains across California and New York mandate fiber-based carryout packaging ahead of state extended producer responsibility deadlines. FDA food-contact substance requirements impose testing protocols that disqualify legacy fluorinated barrier coatings. Chicago and Dallas metropolitan clusters concentrate converting capacity serving Midwest grocery cooperatives with private-label block bottom programs.
Germany
Supermarket chains in Bavaria and North Rhine-Westphalia specify TÜV OK Compost certification for all private-label packaging, creating concentrated demand pull for water-based coated constructions. The EU Packaging and Packaging Waste Regulation binds national reduction targets for single-use plastics that compress polyethylene bag volumes. Hamburg anchors Nordic pulp import flows that stabilize input costs for domestic bag manufacturers.
France
Quick-service operators in Île-de-France and Auvergne-Rhône-Alpes specify short-run digital print capabilities for regional menu variations alongside standardized grease resistance. ANSM food-contact evaluations align with ECHA REACH restrictions that disqualify per- and polyfluoroalkyl substance treatments. Lyon and Marseille industrial zones host converters reformulating silicone-based alternatives for hot sandwich applications.
China
E-commerce fulfillment centers in Yangtze River Delta and Pearl River Delta substitute corrugated with tear-resistant satchel constructions for last-mile delivery. GB standards for food-contact paper impose divergent testing protocols from Atlantic supply chains. Shanghai and Shenzhen clusters concentrate capacity for lightweight substrate development serving domestic quick-service chains.
India
Price-sensitive wholesale procurement in Maharashtra and Gujarat prioritizes plain unprinted multiwall formats for bulk dry goods distribution. FSSAI food-contact regulations lag EU and US stringency, permitting legacy barrier chemistries in domestic food service applications. Ahmedabad and Mumbai industrial corridors host commodity converters competing on substrate weight and handle tensile strength alone.
Commercial Paper Bags Market Competitive Environment
Capability concentration sits with integrated pulp-to-bag operators commanding barrier coating formulation expertise; scale advantage sits with corrugated network players leveraging distribution density across grocery channels. The vendor base stratifies into three archetypes: Nordic pulp-integrated specialists, North American scale converters, and Asia-Pacific commodity fabricators. Dominant competitive moves include capacity expansion in water-based coating lines and strategic partnerships with quick-service restaurant procurement consortia.
Within the integrated pulp-to-bag tier, International Paper and Georgia-Pacific exemplify scale-driven positioning through captive kraft pulp supply. Smurfit Kappa represents corrugated network leverage, converting European distribution density into paper bag channel access. Mondi occupies a specialty position, with barrier coating expertise that extends paper bag utility into grease-resistant food service applications previously served by polyethylene laminates.
| Leading Market Players |
|---|
| International Paper |
| Smurfit Kappa |
| Mondi |
| WestRock |
| Novolex |
| DS Smith |
| Oji Holdings Corporation |
| Stora Enso |
| Georgia-Pacific |
| Others |
Value Chain & Pricing Dynamics
Scandinavian pulp freight corridors from Gothenburg and Helsinki transmit energy cost volatility directly to bag converter margins, concentrating pricing power among Nordic-integrated operators while fragmenting downstream price differentiation across biodegradable-certified and commodity plain tiers.
Pricing Analysis
Long-term offtake contracts with German and United States grocery chains anchor volume commitments for block bottom formats, while spot market transactions dominate plain unprinted wholesale procurement in India and Southeast Asia. Price differentiation rests on TÜV OK Compost certification tier and grease-resistant barrier performance, with quick-service chains absorbing premium positioning for clay-nanoparticle coated constructions. Cost compression in commodity tiers is intensifying because pulp price spikes transmit immediately to non-integrated converters. Industrial procurement teams in Maharashtra and Gujarat exhibit highest price sensitivity; California quick-service operators show lowest elasticity for certified biodegradable specifications.
Supply Chain Analysis
Integrated contract-manufacturing concentration sits with Smurfit Kappa's European corrugated network, International Paper's North American pulp-to-bag operations, and Mondi's specialty coating facilities in Germany and France. Geographic supply concentration centers on Sweden, Finland, and the United States for kraft pulp; China and India for lightweight substrate fabrication. Raw material dependencies draw from Nordic softwood pulp, water-based barrier chemistries, and twisted paper handle components. Single-source vulnerability runs through Scandinavian pulp corridors exposed to energy cost shocks. Distribution runs through retailer-owned networks in the United States Midwest and centralized procurement consortia serving EU grocery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation mandates are compressing plastic alternatives at a pace that outstrips converter capacity expansion, creating a high-growth disruption anchored in regulatory technology substitution rather than organic demand evolution.
For Market Incumbents: Entrench barrier coating formulation expertise through captive R&D investment in silicone-based and bio-wax alternatives, as REACH restrictions on fluorinated chemistries threaten legacy product lines. Consolidate vendor relationships with quick-service restaurant procurement consortia in Germany and France to lock in multi-year framework agreements before qualification cycles extend further. For New Entrants and Emerging Players: Establish a beachhead in e-commerce secondary packaging for satchel constructions with tear-resistant substrates, where corrugated-to-paper substitution in Chinese and Indian last-mile delivery remains underpenetrated by established converters. Target California extended producer responsibility compliance services as a go-to-market angle, offering lightweight substrate development bundled with closed-loop collection documentation. For Investors and Strategic Acquirers: Carve-out targets emerge from corrugated network parents seeking to monetize paper bag distribution capabilities without full vertical integration into pulp production. Long-term viability favors operators with water-based coating line capacity and pre-qualified biodegradable certifications. Watch for accelerated qualification data releases from substrate suppliers as the inflection signal indicating reformulation cycle completion.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Line Expansion | REACH-compliant barrier performance unlocks EU quick-service restaurant procurement contracts. |
| Digital Print Platform Integration | Inline flexographic systems collapse prepress timelines for regional retail chain customization. |
| Backward Integration into Nordic Pulp | Captive kraft supply stabilizes input costs against Scandinavian energy corridor volatility. |
| Biodegradable Certification Fast-Track | TÜV OK Compost and BPI labels compress 8-14 month validation cycles for competitive positioning. |
| Quick-Service Restaurant Consortium Partnership | Multi-year framework agreements with German and French chains secure volume commitments ahead of statutory deadlines. |
Study Parameters
Cross-validation between primary interviews with paper bag converters, quick-service restaurant procurement directors, and grocery chain sustainability officers anchors the qualitative findings against secondary validation from EU Packaging and Packaging Waste Regulation filings, FDA food-contact substance databases, and Nordic pulp mill capacity disclosures. Bottom-up triangulation across substrate grade specifications and top-down reconciliation against end-use channel demand estimates produces integrated volume and value outputs.
Calibration against historical pulp price volatility patterns and barrier coating adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product geometry, barrier performance tier, certification status, end-use channel, and regional regulatory cluster. CAGRs derive from slope analysis of substitution elasticities between paper and polyethylene formats, with pulp cost pass-through coefficients and quick-service restaurant mandate compliance timelines as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Scandinavian energy costs, Baltic freight rates, or EU ETS carbon pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and coating technology performance thresholds. Quarterly review of REACH restriction proposal advancement and compostability certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market