
 Flowpack Paper Packaging Market | 2026-2036
Flowpack Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Flowpack Paper Packaging Market Foresight
Plastic film is consolidating its displacement by coated and uncoated paper substrates across European confectionery and personal care lines. Mondi Group leverages integrated pulp-to-pack operations across Austria and Germany to sustain cost advantages in kraft paper flowpack output. Smurfit Kappa Group anchors its position through recycled fiber expertise and pan-European converting capacity. DS Smith competes via circular design protocols that align with retailer sustainability scorecards.
Flowpack paper packaging denotes a continuous-web wrapping format wherein paper substrates—typically 30–80 gsm kraft, waxed, or greaseproof grades—are formed around products on horizontal or vertical form-fill-seal equipment, with heat-sealable coatings or mechanical crimping providing closure integrity; the format serves primary protective and display functions for food, pharmaceutical, and consumer goods items. Kraft paper dominates volume owing to tensile strength suitability for industrial supply weights, while greaseproof paper captures margin concentration in butter and chocolate applications where fat-barrier performance commands specification premiums. Laminated paper variants are gaining traction in pharmaceutical end uses where moisture vapor transmission rates must meet stability protocols.
EMA packaging guidelines, EU Green Deal circularity targets, and REACH chemical compliance frameworks collectively elevate barrier-coating scrutiny and recyclability certification requirements for paper-based primary packaging. Germany's national packaging regulator enforces strict dual-system participation fees that favor mono-material paper formats over multi-layer alternatives. Stakeholders must monitor evolving EN 13432 compostability standards and pending revisions to the Packaging and Packaging Waste Regulation to anticipate substrate qualification shifts before compliance windows narrow.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing plastic film viability across European confectionery and pharmaceutical packaging lines, redirecting capital toward heat-sealable paper substrate qualification and mono-material format development.
Growth Catalysts
- EMA packaging guidelines:Barrier-coating standards for pharmaceutical stability are elevating specification requirements for laminated paper flowpacks in prescription drug distribution.
- Confectionery processors:Chocolate and butter manufacturers in Germany and France are expanding greaseproof paper orders ahead of Extended Producer Responsibility compliance deadlines.
- Kraft paper substrate advances:Tensile strength improvements in 30–50 gsm grades are enabling industrial supply weight applications previously reserved for plastic films.
Market Restraints
- Pulp input cost volatility:Softwood kraft pulp pricing fluctuations compress margin stability for integrated and non-integrated converters alike.
- Heat-seal coating technical limitation:Current bio-based barrier coatings fail to match plastic film moisture vapor transmission rates in tropical distribution climates.
- REACH chemical compliance friction:Fluorochemical coating phase-outs under ECHA restrictions are forcing rapid reformulation without proven drop-in replacements.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-stable paper flowpack formats for biologics distribution represent underpenetrated specification territory.
- Dual-system participation fee structure:Germany's packaging regulator fee differentials favor mono-material paper investments over multi-layer alternatives.
- Compostable certification convergence:EN 13432 compliance alignment with retailer sustainability scorecards opens private-label confectionery contracts.
Industry Challenges
- Barrier-coating formulation talent scarcity:Polymer chemistry expertise for heat-sealable paper applications concentrates with legacy plastic film suppliers.
- Form-fill-seal line reconfiguration capex:Converting equipment from plastic to paper web handling requires mechanical retrofit investment and downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flowpack Paper Packaging Market |
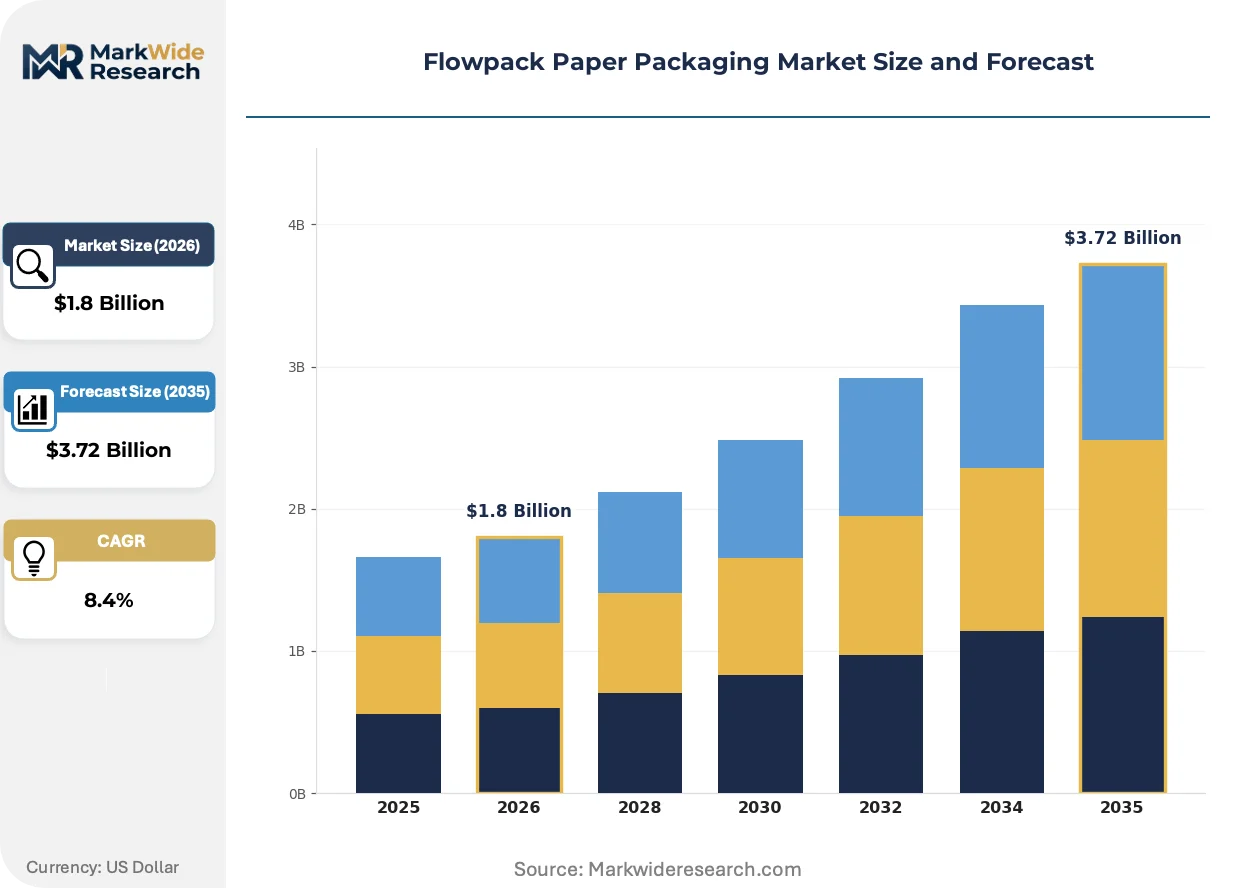
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Waxed Paper, Kraft Paper, Greaseproof Paper, Glassine Paper, Tissue Paper, Laminated Paper Application: Confectionery, Pharmaceuticals, Personal Care, Household Products, Stationery, Industrial Supplies End User: Food Processors, Cosmetic Manufacturers, Pharmaceutical Producers, Stationery Companies, Textile Plants, Chemical Plants Distribution Channel: Direct Sales, Distributors, E-commerce, Retail Chains, Wholesalers, Specialty Stores |
| Companies Covered | Mondi Group, Smurfit Kappa Group, DS Smith, International Paper Company, BillerudKorsnäs, SUDPACK, WestRock, SURICATE, Hugo Beck Maschinenbau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flowpack Paper Packaging Market Shifts & Advancements
Active coating technologies and regulatory compliance automation are compressing development cycles for barrier-functional paper formats, while procurement criteria harden around recyclability certification and carbon footprint disclosure.
Water-based heat-seal coatings with bio-derived polymer backbones are absorbing specification share in medium-barrier confectionery applications. Swiss and Austrian chocolate manufacturers are piloting these formats for count-line products. The technology is absorbing volume from wax-laminated alternatives by eliminating separation steps in standard recycling streams.
REACH restrictions on per- and polyfluoroalkyl substances are forcing coating reformulation across European pharmaceutical packaging lines. Industrial consequence includes accelerated R&D spend on cellulose-based barrier layers. High-value pharmaceutical stability protocols in Germany and France are most affected, with brand owners demanding interim compliance roadmaps from suppliers.
Retailer sustainability scorecards are hardening procurement criteria for private-label confectionery and personal care lines. Centralized buying teams at German and French grocery chains now mandate recyclability certification and carbon footprint disclosure as table stakes. Butter and chocolate applications in Western Europe show the most visible preference compression, with uncertified formats losing shelf placement.
Flowpack Paper Packaging Market Segmentation
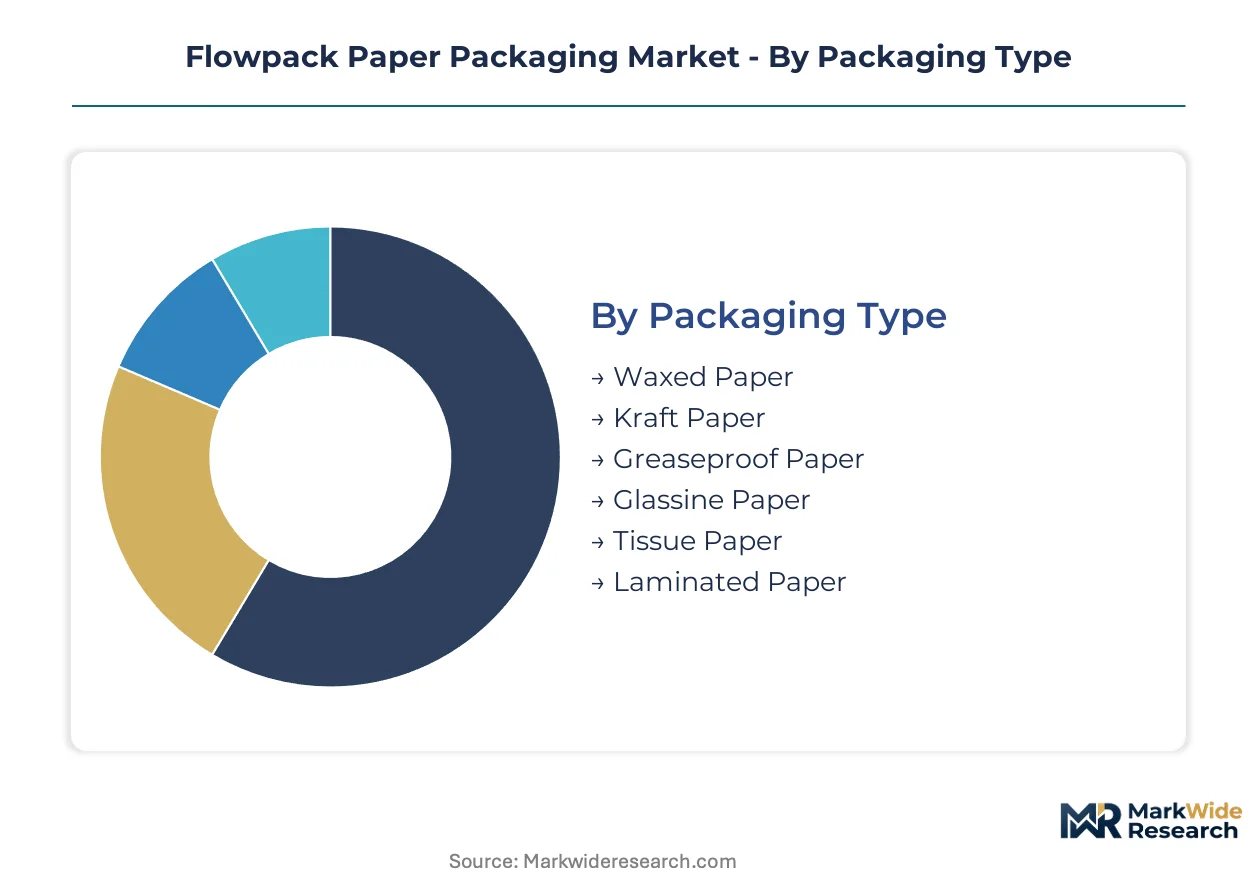
Flowpack paper packaging segmentation reveals divergent technical requirements across substrate grades and end-use specifications. Kraft paper dominates industrial tonnage while greaseproof and laminated variants capture pharmaceutical margin premiums. Understanding these tiered demand patterns enables targeted capacity allocation and coating technology investment.
Packaging Type:
Volume concentration clusters in commodity kraft grades, with premium capture flowing to barrier-functional specialty papers.
- Kraft Paper:Unbleached sulfate pulp construction delivers 30–80 gsm tensile strength suitable for industrial supply weights and heavy confectionery lines. German food processors are expanding orders for 40–50 gsm kraft flowpacks ahead of EPR compliance deadlines, displacing plastic film in count-line chocolate applications.
- Greaseproof Paper:Chemically treated wood pulp achieves fat-barrier performance without wax lamination, enabling direct recycling stream compatibility. Butter and chocolate manufacturers in France specify greaseproof formats where moisture vapor transmission tolerance permits, commanding specification premiums over standard kraft.
- Laminated Paper:Multi-layer constructions with aluminum or polymer barriers serve pharmaceutical stability protocols where EMA guidelines mandate moisture protection.
- Waxed Paper:Paraffin or vegetable-based coatings provide medium barrier for bakery and fresh produce lines.
- Glassine Paper:Supercalendered smoothness suits high-visibility confectionery display windows.
- Tissue Paper:Lightweight protection for stationery and delicate consumer goods.
Mature deployment sits with Kraft Paper across industrial and food processing lines. Newer deployment is concentrated in Laminated Paper as pharmaceutical cold-chain expansion accelerates.
Application:
Application segmentation tracks regulatory pressure intensity, with confectionery and pharmaceutical lines facing the tightest compliance windows.
- Confectionery:Chocolate, butter, and sugar-based products demand greaseproof or waxed paper formats with fat-barrier integrity. Swiss and Austrian manufacturers are piloting water-based heat-seal coatings to eliminate separation steps in recycling streams ahead of retailer sustainability scorecard enforcement.
- Pharmaceuticals:Prescription drug and biologics distribution requires laminated paper flowpacks meeting EMA barrier-coating standards for stability. German pharmaceutical producers are demanding interim compliance roadmaps from suppliers as REACH fluorochemical restrictions force coating reformulation.
- Personal Care:Soap, cosmetics, and hygiene products utilize kraft and tissue grades with brand-focused print surfaces.
- Household Products:Cleaning supplies and hardware employ industrial-weight kraft formats.
- Stationery:Paper and office goods use lightweight tissue and glassine protection.
- Industrial Supplies:Mechanical components and hardware specify heavy kraft constructions for supply chain durability.
Volume leadership belongs to Confectionery as plastic film displacement accelerates. Steepest expansion trajectory is emerging in Pharmaceuticals where temperature-stable formats for biologics distribution remain underpenetrated.
End User:
End user segmentation reflects procurement sophistication variance, from centralized retail-facing food processors to fragmented industrial buyers.
- Food Processors:Integrated chocolate, butter, and bakery manufacturers drive greaseproof and kraft specification at scale. French and German processors are consolidating supplier relationships around dual-system participation fee optimization.
- Pharmaceutical Producers:Brand owners and contract packagers demand laminated paper compliance with EMA stability protocols. German pharmaceutical producers face the most acute REACH reformulation pressure.
- Cosmetic Manufacturers:Personal care brand owners specify premium print surfaces for shelf differentiation.
- Stationery Companies:Paper goods distributors prioritize cost-efficient tissue and glassine protection.
- Textile Plants:Fabric and garment producers use industrial kraft for shipping protection.
- Chemical Plants:Industrial supply houses specify heavy-duty formats for hardware distribution.
Procurement consolidation concentrates with Food Processors as EPR deadlines approach. Technical specification complexity is intensifying among Pharmaceutical Producers.
Distribution Channel:
Channel segmentation tracks buyer scale and service intensity requirements, from direct mill relationships to fragmented retail procurement.
- Direct Sales:Large-volume food processors and pharmaceutical producers contract directly with integrated paper converters for customized specification and volume commitment.
- Distributors:Pan-European packaging distributors aggregate demand from mid-size confectionery and personal care manufacturers, offering inventory buffering and technical support.
- E-commerce:Digital procurement platforms serve small-batch buyers and specialty converters with standard grade availability.
- Retail Chains:Centralized buying teams at German and French grocery chains mandate recyclability certification as procurement table stakes.
- Wholesalers:Regional paper merchants stock commodity kraft grades for industrial supply customers.
- Specialty Stores:Niche packaging retailers serve artisan food producers and boutique cosmetic brands.
Channel leverage is consolidating with Direct Sales among high-volume processors. Digital procurement penetration is climbing fastest among small-batch specialty buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western European confectionery and pharmaceutical processors generate the densest demand concentration for flowpack paper packaging, with German and French food manufacturers expanding orders ahead of Extended Producer Responsibility compliance deadlines.
Germany
Chocolate and butter manufacturers in Bavaria and North Rhine-Westphalia are scaling greaseproof paper flowpack procurement as dual-system participation fees favor mono-material formats. The national packaging regulator enforces strict fee differentials that penalize multi-layer alternatives. Industrial converters in the Hamburg cluster are retrofitting form-fill-seal lines to handle 40–50 gsm kraft webs for count-line applications.
France
Confectionery processors in Île-de-France and Auvergne-Rhône-Alpes specify chemically treated greaseproof grades where fat-barrier performance commands specification premiums. ANSM pharmaceutical packaging guidelines align with EMA stability protocols for laminated paper formats. The Lyon industrial basin hosts pilot programs for water-based heat-seal coatings in medium-barrier chocolate applications.
Switzerland
Swiss chocolate manufacturers in the Zurich and Vevey regions are advancing bio-derived polymer coating trials to eliminate separation steps in standard recycling streams. Swissmedic pharmaceutical regulations drive laminated paper qualification for prescription drug distribution. The Lake Geneva corridor concentrates R&D investment in cellulose-based barrier layers.
Austria
Pulp-to-pack integrated operations across Upper Austria supply kraft paper flowpacks with cost advantages in tensile-critical industrial applications. EU Green Deal circularity targets accelerate mono-material format development among domestic converters. The Linz industrial cluster sustains captive fiber supply for 30–80 gsm grade production.
United Kingdom
Pharmaceutical contract packagers in the Midlands and Southeast England demand interim compliance roadmaps from suppliers as REACH fluorochemical restrictions force coating reformulation. Retailer sustainability scorecards from major grocery chains mandate recyclability certification for private-label confectionery lines. The Manchester packaging corridor adapts former plastic film capacity to paper web handling.
Flowpack Paper Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated pulp-to-pack operators and recycled fiber specialists race to capture plastic film displacement volume. The market structure consolidates around three strategic tiers: integrated multinationals with captive fiber supply, pan-European converters with recycled expertise, and regional specialists in barrier-coating technology. Strategic archetypes include backward-integrated giants, circular-design leaders, and coating formulation boutiques. M&A activity and form-fill-seal line reconfiguration capex represent the dominant competitive moves.
Within the integrated multinational tier, Mondi Group exemplifies pulp-to-pack cost advantages through Austrian and German operations, while Smurfit Kappa Group anchors pan-European recycled fiber capacity. DS Smith occupies a position emphasizing circular design protocols aligned with retailer sustainability scorecards.
| Leading Market Players |
|---|
| Mondi Group |
| Smurfit Kappa Group |
| DS Smith |
| International Paper Company |
| BillerudKorsnäs |
| SUDPACK |
| WestRock |
| SURICATE |
| Hugo Beck Maschinenbau |
| Others |
Supply & Pricing Matrix
Softwood kraft pulp futures on the CME Group exchange cascade through European flowpack converters into three distinct pricing tiers, with integrated pulp-to-pack operators in Austria and Germany capturing margin insulation unavailable to merchant-dependent competitors.
Pricing Analysis
Volume-mass kraft paper flowpacks trade on thin margins anchored to spot pulp indices, while greaseproof and laminated pharmaceutical grades command specification premiums tied to barrier performance certification. Price differentiation separates EMA-compliant pharmaceutical formats from standard confectionery grades, with REACH fluorochemical restrictions compressing margins on reformulating coatings. Pricing pressure stems from bio-based heat-seal coating R&D costs as converters absorb qualification expenses ahead of retailer sustainability scorecard enforcement. Small-batch artisan food processors exhibit acute price sensitivity, whereas pharmaceutical brand owners prioritize stability protocol compliance over unit cost.
Supply Chain Analysis
Bleached and unbleached kraft pulp supply rests on Nordic softwood producers, Austrian integrated operators, and Brazilian eucalyptus plantations, with coating chemistry dependencies concentrated among German and Swiss specialty chemical suppliers. Raw material inputs span sulfate pulp, bio-derived barrier polymers, and fluorochemical alternatives under ECHA restriction. Single-source vulnerability concentrates in heat-seal coating formulation expertise, where legacy plastic film suppliers control polymer chemistry talent pools. Distribution runs through direct mill relationships for high-volume food processors, with pan-European distributors buffering mid-tier confectionery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier-coating formulation talent scarcity props pricing power for qualified suppliers, as pharmaceutical and confectionery processors face narrowing compliance windows without drop-in technical replacements.
For Market Incumbents: To counter REACH fluorochemical phase-outs without proven cellulose-based alternatives, prioritize captive R&D partnerships with polymer chemistry specialists in the Lake Geneva corridor and accelerate EN 13432 compostability certification for private-label confectionery contracts. Secure backward integration into bio-derived heat-seal coating supply through offtake agreements with Swiss and Austrian pilot facilities. For New Entrants and Emerging Players: Enter via temperature-stable paper flowpack formats for biologics cold-chain distribution, the most underpenetrated specification territory within pharmaceutical applications. Target German pharmaceutical contract packagers demanding interim compliance roadmaps, leveraging coating formulation partnerships as the primary go-to-market angle against established laminated paper suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with EN 13432 certification and existing pharmaceutical customer relationships in Bavaria and North Rhine-Westphalia, where dual-system participation fee differentials sustain mono-material format demand. Watch for pulp input cost volatility spikes as the inflection indicator triggering consolidation among non-integrated merchant converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Austrian and German integrated operators sustain cost advantages against merchant-dependent competitors. |
| Pharmaceutical Barrier Coating Qualification | EMA stability protocol compliance opens prescription drug distribution contracts ahead of fluorochemical restrictions. |
| Compostable Certification Investment | EN 13432 alignment secures shelf placement with German and French retailer sustainability scorecards. |
| Form-Fill-Seal Line Retrofit | Mechanical web handling adaptation captures plastic film displacement volume in count-line chocolate applications. |
| Regional Distribution Partnership | Pan-European distributor relationships buffer mid-tier confectionery manufacturers against direct sales consolidation. |
Research Methodology
Independent corroboration across primary interviews with paper converter operations managers, pharmaceutical packaging procurement leads, and confectionery brand sustainability officers, combined with secondary validation from EU Green Deal implementation tracking, EMA packaging guideline updates, and Nordic pulp futures exchange data, underwrites the qualitative findings. Bottom-up capacity assessments at Austrian and German mill clusters triangulate against top-down demand modeling from EPR compliance deadline schedules.
Rate-of-change decomposition across substrate grade, application specification, end-user procurement sophistication, and distribution channel intensity structures the analytical framework. CAGRs derive from segmented volume trajectories calibrated to plastic film displacement rates in confectionery and pharmaceutical lines, with pulp input cost elasticity and coating technology substitution curves as industry-specific forecast inputs throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH fluorochemical restriction timelines or sustained softwood pulp price volatility. A small set of named triggers warrants ongoing watch: ECHA coating reformulation guidance, EN 13432 standard revisions, and German packaging regulator fee structure adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Cold Waxed Paper Cups Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Shredded Paper Filler Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Freezer Paper Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Japan Paper Packaging Market