
 France Glass Packaging Market | 2026-2036
France Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
France Glass Packaging Market Foresight
Modular bottle configurators and small-batch decoration services are repositioning how mid-sized beverage brands approach procurement. Verallia France leverages its furnace network across multiple French sites to sustain proximity supply for wine cooperatives. O-I France anchors volume production through its long-standing relationships with mass-market beverage accounts. Saverglass differentiates via decorated and prestige glass formats for cosmetics and premium spirits clients.
France glass packaging comprises silica-soda-lime containers formed through blow-and-blow or press-and-blow processes, typically featuring wall thicknesses of 2–5 mm and thermal shock resistance up to 42°C for standard beverage grades, serving primarily as inert, impermeable barriers for liquid and semi-solid contents. The bottle segment dominates volume throughput due to entrenched wine, beer, and spirits distribution infrastructure, while amber and flint material grades command margin concentration in pharmaceutical and premium cosmetic applications. Jar formats compete in food processing channels where hermetic sealing and microwave compatibility requirements have intensified specification debates.
France's packaging sector operates under extended producer responsibility frameworks administered by Citeo, with ANSM enforcing pharmaceutical glass purity standards and EU REACH and MDR regulations governing chemical composition and medical device contact materials. These frameworks elevate compliance costs for imported glass while rewarding domestic recyclate integration. Stakeholders must monitor forthcoming revisions to France's national packaging waste prevention plan and their implications for minimum recycled content thresholds.
Market Dynamics
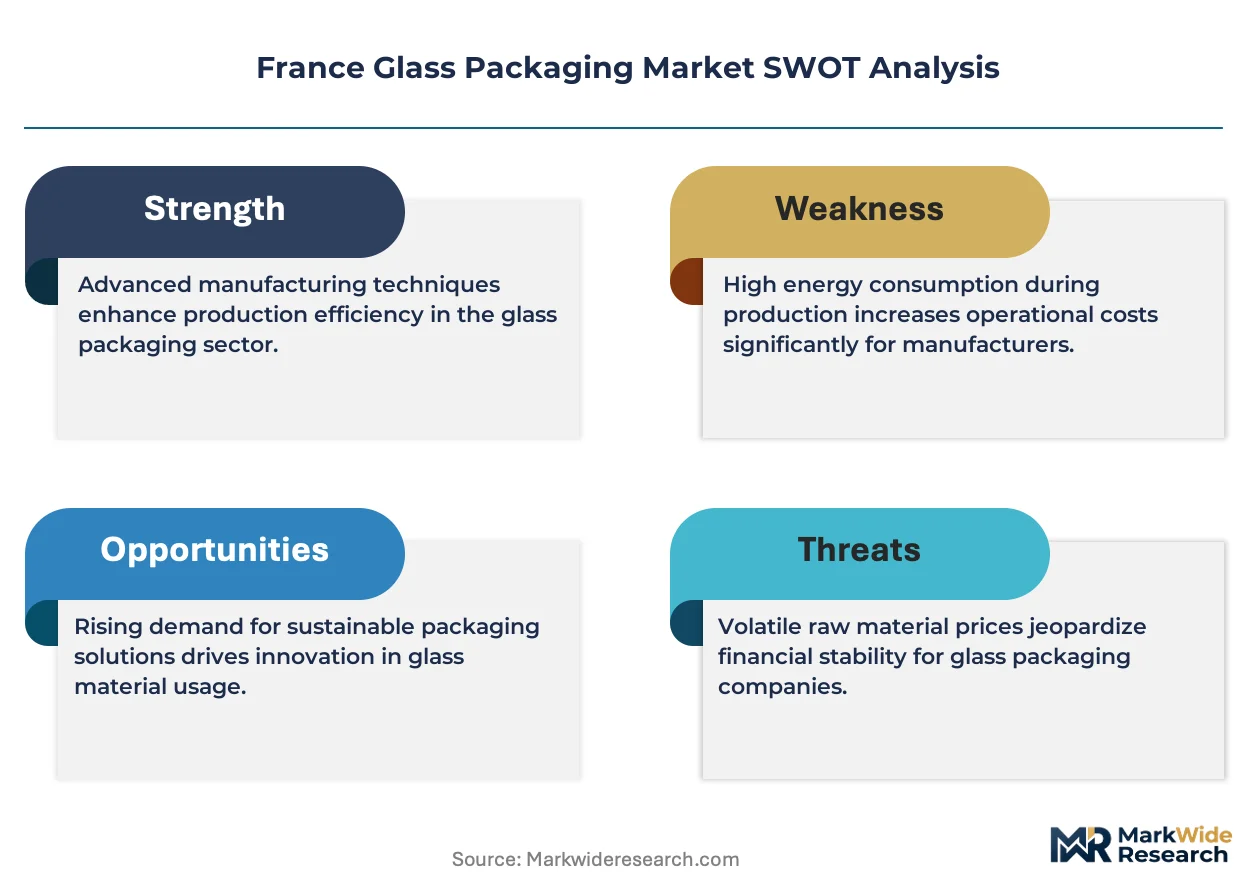
France's glass packaging sector faces intensifying pressure from Citeo's extended producer responsibility mandates, which are forcing furnace operators to reconfigure batch formulations around higher post-consumer cullet ratios without compromising thermal performance or color consistency.
Growth Catalysts
- EPR Threshold Escalation:Citeo's tightening recycled content minimums are pulling investment toward cullet beneficiation infrastructure across northern glassmaking basins.
- Champagne Method Expansion:Protected designation of origin bottling protocols in Champagne-Ardenne are sustaining specialized heavy-wall bottle demand that resists lightweighting pressures.
- Electrification Pilots:Hybrid furnace trials at multiple French sites are demonstrating oxy-fuel combustion viability for carbon footprint reduction ahead of EU ETS phase-in.
Market Restraints
- Natural Gas Cost Volatility:Furnace operations remain exposed to TTF-linked energy contracts that compress margin predictability during heating season spikes.
- Silica Sand Supply Concentration:High-purity silica extraction concentrates in specific Loire Valley deposits, creating geographic vulnerability to transport disruption or local permitting delays.
- Aluminum Substitution in Beer:Mass-market brewers are migrating volume share to aluminum cans for logistics efficiency, eroding standard flint bottle offtake.
Strategic Opportunities
- Cosmetic Pharma Convergence:ANSM's evolving purity standards for dermal-contact glass are opening specification gaps between pharmaceutical-grade and premium cosmetic packaging.
- Normandy Cider Export Channel:AOC cider producers in Calvados and surrounding zones represent underpenetrated demand for heritage-format bottles with regional embossing.
- Digital Decoration Integration:Direct-to-glass inkjet systems are converging with small-batch logistics platforms to enable run-length flexibility for craft spirits launches.
Industry Challenges
- Furnace Refractory Expertise Gap:Specialized crown and regenerator maintenance knowledge is concentrating among retiring cohorts, complicating asset life extension strategies.
- REACH Compliance Documentation:Substance of very high concern declarations for imported colorants and surface treatments are extending qualification timelines for new decoration chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Glass Packaging Market |
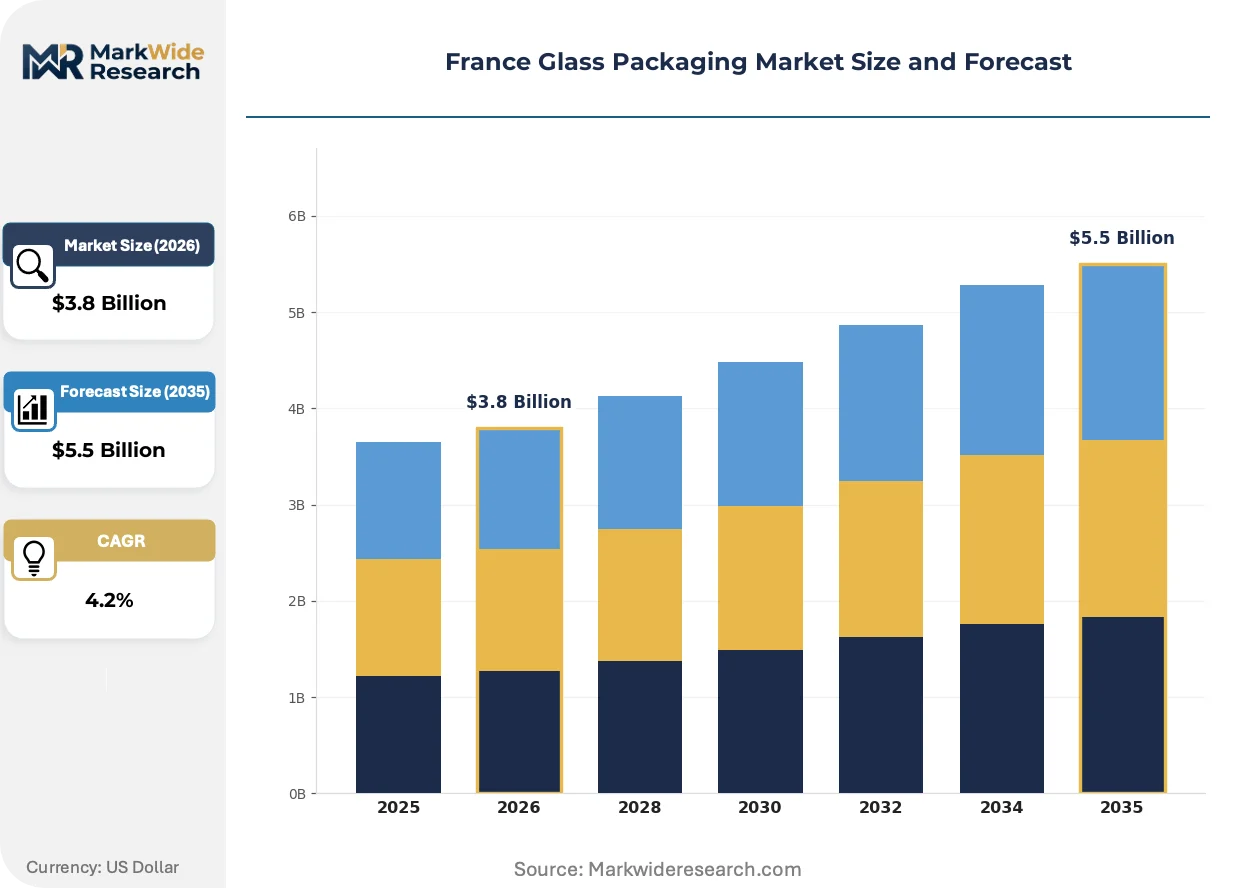
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottle, Jar, Tube, Vial, Flask Material Grade: Flint, Amber, Green, Cranberry, Cobalt Blue End Use Industry: Beverages, Cosmetics, Pharmaceuticals, Food Processing, Chemicals Distribution Channel: Wholesale, Retail Stores, Online Platforms, Direct Manufacturer Sales, Export |
| Companies Covered | Verallia France, O-I France, Ardagh Glass Packaging Europe, Saverglass, Stoelzle Glass Group, Gerresheimer, SGD Pharma, BA Glass, Vetropack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Glass Packaging Market Shifts & Advancements
Active transformation in French glass packaging centers on furnace technology reinvention, regulatory compliance automation, and procurement model fragmentation that privileges proximity supply over consolidated volume contracts.
Lightweighting algorithms derived from finite element stress modeling are converging with real-time forming process control to enable wall-thinning down to 1.8 mm in non-pressurized applications. Sparkling wine producers in Epernay and Reims are piloting these formats for secondary-label releases. This convergence is compressing the traditional trade-off between material efficiency and mechanical durability that has governed bottle design for decades.
France's national packaging waste prevention plan revisions are mandating digital traceability integration for all packaging placed on market, with Citeo administering verification protocols. Glass manufacturers must deploy batch-level serialization to demonstrate recycled content claims. Pharmaceutical and spirits segments are absorbing the highest compliance costs due to dual ANSM and customs documentation requirements.
Cooperative wineries in Languedoc-Roussillon are fragmenting procurement across multiple mid-cap glassmakers rather than consolidating with single-source national contracts. This pattern is displacing the historical volume-rebate structure that favored O-I and Verallia dominance. The shift is most visible in organic and biodynamic wine verticals where provenance storytelling extends to packaging origin.
France Glass Packaging Market Segmentation
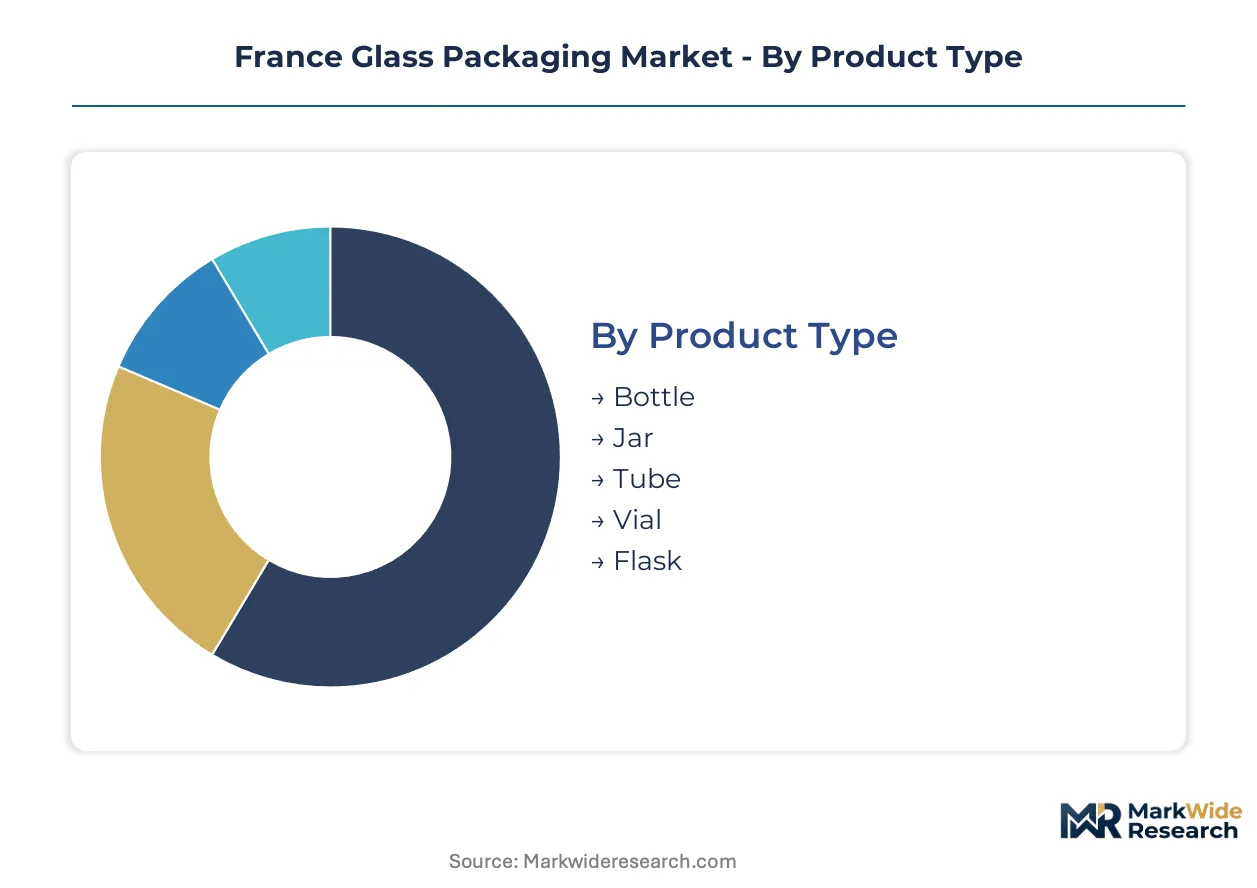
Glass packaging segmentation in France reflects divergent technical requirements across beverage heritage formats, pharmaceutical purity mandates, and cosmetic prestige positioning. Each category channels distinct furnace configurations, decoration capabilities, and regulatory compliance burdens that reshape procurement patterns among end-users.
Product Type:
Volume throughput concentrates in standardized beverage containers, while premium positioning drives specialized formats with heavier wall specifications and custom embossing.
- Bottle:Silica-soda-lime containers formed through blow-and-blow or press-and-blow processes, typically 2–5 mm wall thickness with thermal shock resistance to 42°C. Demand concentrates in Champagne-Ardenne for protected designation of origin wine and spirits, where heavy-wall specifications resist lightweighting pressures from Citeo mandates.
- Jar:Wide-mouth containers with hermetic sealing profiles for viscous and semi-solid contents. Food processing channels in Normandy and Brittany are intensifying microwave compatibility and vacuum seal specifications, compressing margin structures against plastic substitution.
- Tube:Cylindrical formats with narrow aperture ratios for pharmaceutical and cosmetic dispensing. ANSM purity standards for dermal-contact applications are elevating surface treatment documentation requirements.
- Vial:Small-volume precision containers for injectable and diagnostic applications. Pharmaceutical-grade borosilicate specifications concentrate demand around ANSM-inspected facilities with dedicated forming lines.
- Flask:Specialty curved-wall formats for spirits and laboratory applications. Limited production runs favor decorated glass specialists with small-batch furnace flexibility.
Mature deployment sits with Bottle formats across mass-market beverage infrastructure. Newer deployment is concentrated in Vial segments responding to ANSM's evolving pharmaceutical purity protocols.
Material Grade:
Color consistency requirements segment furnace batch formulations between high-clarity pharmaceutical grades and UV-protective amber for light-sensitive contents.
- Flint:High-transparency clear glass with iron oxide content below 0.05% for premium beverage and pharmaceutical visibility. Champagne houses in Epernay specify flint for prestige cuvée presentation, though natural gas cost volatility compresses margin predictability on dedicated furnace campaigns.
- Amber:Iron-sulfur amber with 560 nm cutoff wavelength for UV protection. Pharmaceutical and craft beer segments in northern France are absorbing the highest post-consumer cullet integration costs under Citeo thresholds without compromising color consistency.
- Green:Chromium-iron coloration for wine and olive oil heritage positioning. Loire Valley cooperatives maintain steady offtake for regional appellation bottling.
- Cranberry:Selenium-derived pink tones for cosmetic and limited-edition spirits differentiation. Small-batch production concentrates at decorated glass specialists.
- Cobalt Blue:Cobalt oxide coloration for pharmaceutical and premium cosmetic distinction. REACH compliance documentation for imported colorants extends qualification timelines.
Standard flint and amber grades dominate volume furnace campaigns. Cobalt Blue and Cranberry are climbing the fastest as craft spirits and cosmetic pharma convergence opens specification gaps.
End Use Industry:
Application-specific performance requirements fragment procurement between mass-market beverage volume contracts and specialized pharmaceutical purity certifications.
- Beverages:Wine, beer, spirits, and non-alcoholic drinks commanding the dominant share of furnace throughput. Aluminum substitution in mass-market beer is eroding standard flint bottle offtake while Champagne-Ardenne heavy-wall demand sustains specialized production.
- Cosmetics:Premium fragrance and skincare packaging with decoration-intensive specifications. Direct-to-glass inkjet systems are converging with small-batch logistics for craft brand launches.
- Pharmaceuticals:Injectable, oral, and diagnostic containers under ANSM enforcement of purity standards. Dual documentation requirements with customs protocols absorb the highest compliance costs.
- Food Processing:Preserves, sauces, and condiments with hermetic sealing and thermal shock requirements. Microwave compatibility debates intensify specification pressures against polymer alternatives.
- Chemicals:Laboratory and industrial reagent containers with chemical resistance specifications. Limited demand concentrates at borosilicate-capable facilities.
Established demand concentrates in Beverages with entrenched distribution infrastructure. Pharmaceuticals represent the steepest expansion trajectory as ANSM standards tighten and domestic recyclate integration rewards localized supply.
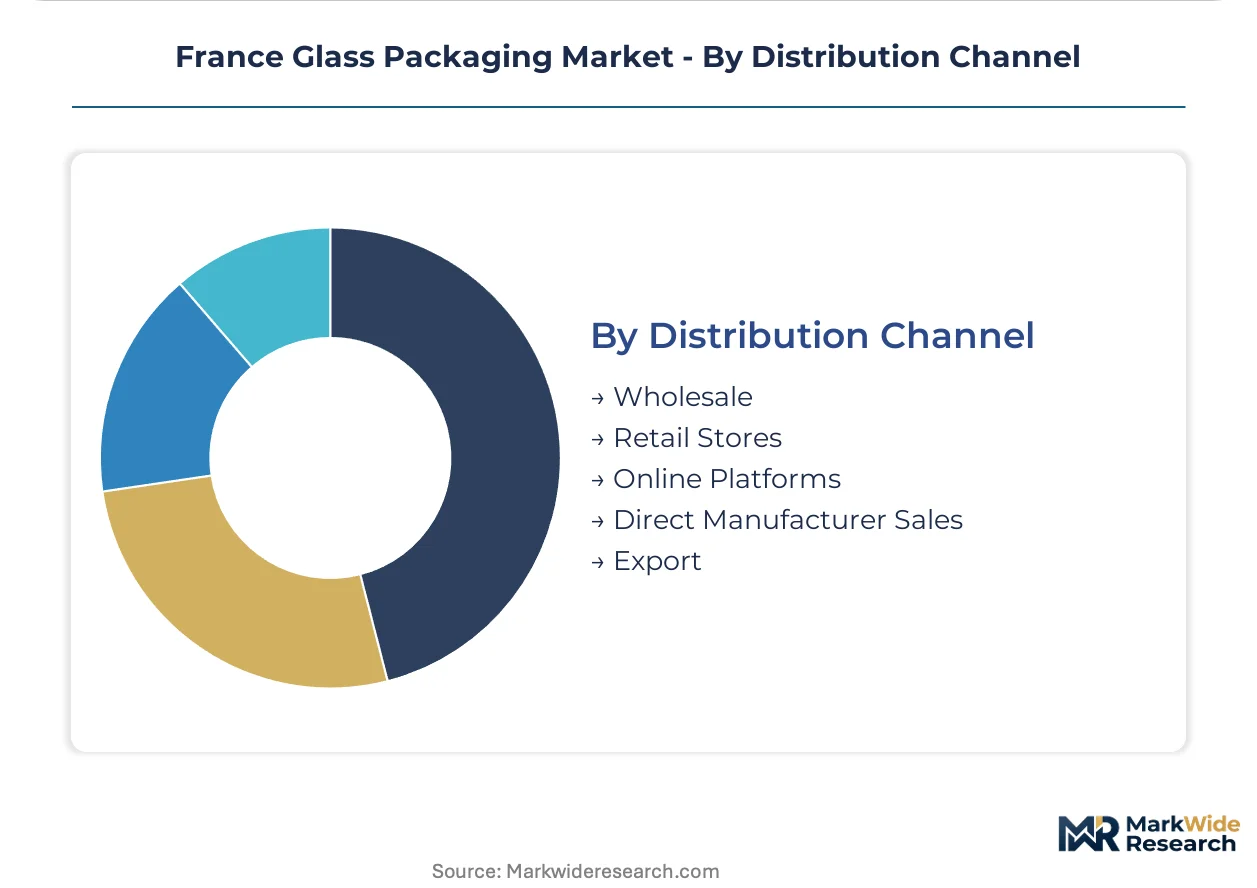
Distribution Channel:
Channel selection reflects order scale, customization depth, and geographic proximity to glassmaking basins.
- Wholesale:Aggregated procurement through beverage and food processing distributors. Volume-rebate structures favor O-I and Verallia national accounts.
- Retail Stores:Direct-to-shelf packaging for private label and regional brands. Limited penetration in glass due to breakage logistics.
- Online Platforms:Digital procurement interfaces for small-batch and standardized formats. Cooperative wineries in Languedoc-Roussillon are fragmenting procurement across mid-cap glassmakers via these channels.
- Direct Manufacturer Sales:Long-term contracts with dedicated furnace allocation. Mass-market brewers and Champagne houses anchor volume through direct relationships.
- Export:Cross-border supply to European and North African markets. Calvados AOC cider producers leverage heritage-format bottles for regional embossing differentiation in export channels.
Direct Manufacturer Sales commands the largest volume commitments. Online Platforms are gaining share fastest as procurement fragmentation displaces historical consolidation patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's glass packaging production concentrates in northern furnace corridors while consumption spreads across wine cooperatives in Languedoc-Roussillon and Champagne-Ardenne bottling houses. This geographic mismatch shapes logistics costs and proximity sourcing strategies for mid-sized beverage brands.
Champagne-Ardenne
Heavy-wall bottle demand from protected designation of origin Champagne houses sustains specialized furnace campaigns resistant to lightweighting pressures. ANSM enforces pharmaceutical-grade purity standards at facilities serving dual-use cosmetic-pharma clients. Reims and Epernay anchor production clusters where hybrid electrification pilots are testing oxy-fuel combustion viability.
Hauts-de-France
Proximity to Belgian border glassmaking infrastructure enables cross-border cullet beneficiation networks under Citeo's extended producer responsibility mandates. The region's logistics corridors absorb natural gas cost volatility through diversified TTF-linked contract structures. Lille metropolitan zone hosts distribution hubs consolidating procurement for mass-market beverage accounts.
Normandy
AOC cider producers in Calvados represent underpenetrated demand for heritage-format bottles with regional embossing specifications. Local cooperatives are fragmenting procurement across mid-cap glassmakers rather than consolidating with national volume contracts. Caen and surrounding zones leverage export channel access for North African market penetration.
Auvergne-Rhône-Alpes
Cosmetic packaging specialists cluster around Lyon-forming corridors serving fragrance and skincare brands with decoration-intensive specifications. ANSM's evolving dermal-contact glass standards are elevating surface treatment documentation requirements for local facilities. Saint-Étienne sub-region concentrates small-batch furnace flexibility for craft spirits launches.
Occitanie
Organic and biodynamic wine verticals in Languedoc-Roussillon are displacing historical volume-rebate procurement structures through online platform fragmentation. Montpellier and Perpignan zones prioritize provenance storytelling that extends to packaging origin verification. Citeo's digital traceability mandates are accelerating batch-level serialization deployment across cooperative winery supply chains.
France Glass Packaging Market Competitive Landscape
The competitive structure tilts toward integrated furnace operators with multi-site proximity networks. National-scale players anchor volume through long-standing beverage relationships while mid-cap specialists capture fragmentation in premium and small-batch segments. Two archetypes dominate: diversified multinational furnace networks and decoration-focused prestige format specialists. Capacity reconfiguration around cullet beneficiation and hybrid electrification trials represent the primary competitive moves reshaping asset deployment.
Among integrated furnace operators, Verallia France and O-I France exemplify scale-driven archetypes with multi-site proximity supply capabilities. Saverglass occupies a position within the prestige-decoration specialist tier, serving premium spirits and cosmetic clients requiring small-batch flexibility. These three anchors demonstrate how competitive positioning splits between volume efficiency and customization depth across France's glassmaking basins.
| Leading Market Players |
|---|
| Verallia France |
| O-I France |
| Ardagh Glass Packaging Europe |
| Saverglass |
| Stoelzle Glass Group |
| Gerresheimer |
| SGD Pharma |
| BA Glass |
| Vetropack |
| Others |
Supply & Pricing Matrix
Natural gas cost volatility propagates through TTF-linked furnace contracts into three-tier pricing structures across premium, standard, and economy levels, with Champagne-Ardenne heavy-wall bottles absorbing margin compression while mass-market flint grades face aluminum substitution pressure.
Pricing Analysis
Margin tightening in standard beverage grades traces to natural gas cost spikes and aluminum can migration, while premium decorated formats maintain pricing power through small-batch scarcity. Three-tier pricing structure across premium, standard, and economy levels stratifies by decoration complexity and volume scale. Mass-market brewers exhibit highest price sensitivity, whereas prestige spirits houses prioritize provenance verification over unit cost.
Supply Chain Analysis
ANSM pharmaceutical-grade certification gates access to injectable and dermal-contact glass segments, extending qualification timelines for imported colorants under REACH documentation. Supply concentrates in France, Belgium, and Germany for furnace operations, with high-purity silica sand extraction tethered to Loire Valley deposits. Single-source vulnerability sits with natural gas procurement through TTF-linked contracts. Distribution runs through direct manufacturer sales for volume accounts and online platforms for fragmented cooperative procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's glass packaging sector is executing a furnace technology transition, with hybrid electrification pilots displacing legacy oxy-fuel combustion ahead of EU ETS phase-in.
For Market Incumbents: Deploy cullet beneficiation infrastructure across northern glassmaking basins to defend margin position against Citeo's escalating recycled content mandates. Anchor volume relationships through proximity supply networks while aluminum substitution erodes mass-market beer offtake. Prioritize furnace crown maintenance knowledge transfer before retiring cohorts exit. For New Entrants and Emerging Players: Online platform procurement routes open access to cooperative wineries in Languedoc-Roussillon that are fragmenting away from national volume contracts. Target heritage-format AOC cider bottling in Normandy with regional embossing capabilities. Calvados export channels to North Africa offer underpenetrated demand with lower incumbent saturation. For Investors and Strategic Acquirers: Hybrid furnace commissioning at multiple French sites is the leading indicator that electrification capital deployment is accelerating competitive differentiation. Five-to-ten-year viability favors mid-cap decorated glass specialists with small-batch flexibility over commodity volume players. Watch for Citeo threshold revisions triggering consolidation pressure on sub-scale furnace operators.| Strategic Initiative | Industry Significance |
|---|---|
| Cullet Beneficiation Infrastructure | Enables Citeo compliance without compromising thermal performance at Champagne-Ardenne furnaces. |
| Hybrid Electrification Pilot | Demonstrates oxy-fuel combustion viability for carbon footprint reduction ahead of EU ETS phase-in. |
| Digital Decoration Integration | Direct-to-glass inkjet systems converge with small-batch logistics for craft spirits launches. |
| Proximity Supply Network Expansion | Multi-site furnace configuration sustains cooperative winery relationships against national contract consolidation. |
| Pharmaceutical-Grade Certification Investment | ANSM purity standards elevate barriers between pharmaceutical and premium cosmetic packaging segments. |
Research Methodology
Multi-period observation of furnace utilization rates, cullet integration ratios, and Citeo compliance filings anchored the trend analysis, supplemented by interviews with plant managers at northern glassmaking basins, procurement leads at Champagne houses, regulatory affairs specialists at ANSM, and category buyers at beverage cooperatives. Secondary validation drew from Citeo annual reports, ANSM pharmaceutical glass purity guidelines, EU REACH substance databases, and SEC filings of listed packaging multinationals. Bottom-up volume modeling triangulated against top-down sector expenditure analysis.
Input-output matrix framing connected silica sand extraction volumes through furnace batch formulations to end-use segment offtake across the projection horizon. Segmentation dimensions modeled include product type, material grade, end-use industry, and geographic glassmaking basin. CAGRs derived from slope analysis of period-to-period value progression, with natural gas cost curves and recycled content mandate trajectories as primary forecast inputs.
The model holds under stable EU ETS implementation timelines and Citeo threshold escalation patterns; deviation in natural gas price volatility or aluminum substitution acceleration would shift volume trajectories. A model refresh is warranted upon material change in France's national packaging waste prevention plan revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
North America Amber Glass Packaging Market
Glass Packaging
United States Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
Dosing Bottles Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Glass Veil Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Germany Container Glass Market