
 Kraft Paper Bags Market | 2026-2036
Kraft Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Paper Bags Market Outlook
E-commerce shippers is redrawing demand patterns across the kraft paper bags landscape as fulfillment centers prioritize branded, durable shipping sacks over plain grocery formats. Mondi Group leverages integrated pulp-to-bag production across Central European mills to capture this shift. Smurfit Kappa Group anchors its position through corrugated-adjacent kraft sack operations serving industrial bulk buyers. WestRock Company differentiates via coated kraft solutions that extend moisture resistance for frozen food applications.
Kraft paper bags are unbleached sulfate pulp containers typically manufactured from 40–120 gsm virgin or recycled fiber, formed on multiwall tubers with pinch-bottom or open-mouth closures for dry goods, fresh produce, and parcel transport. Patch handle bags command premium positioning in boutique retail channels where tear resistance and printability drive replacement of polyethylene carriers. Food and beverage applications lead volume absorption, while industrial-grade flat bags sustain margin pools through custom sizing and anti-slip coatings for cement and chemical loading.
The EU F-Gas Regulation and REACH chemical compliance frameworks elevate barrier specifications for food-contact kraft grades, while FDA food-contact substance notifications govern U.S. import eligibility for printed sacks. Germany's national packaging ordinance, enforced by the Central Agency Packaging Register, mandates minimum recycled content thresholds that reshape raw material sourcing across European converters. Stakeholders must monitor evolving extended producer responsibility fee structures to calibrate regional manufacturing footprints against compliance cost curves.
Market Dynamics
The EU Single-Use Plastics Directive is compressing polyethylene carrier demand and redirecting foodservice procurement toward fiber-based alternatives, while e-commerce fulfillment centers are re-specifying bag constructions for parcel durability over single-use grocery formats.
Growth Catalysts
- EU Single-Use Plastics Directive:The ban on conventional plastic carriers across member states is mandating substitution toward unbleached sulfate pulp alternatives in quick-service restaurant takeout packaging.
- Quick-service restaurant expansion:Chains are standardizing branded kraft bags for curbside pickup and delivery, driving volume procurement of pinch-bottom constructions with reinforced handles.
- German packaging ordinance enforcement:The Central Agency Packaging Register is elevating minimum recycled content thresholds, compelling converters to secure certified post-consumer fiber streams.
Market Restraints
- Virgin pulp cost volatility:Softwood sulfate pricing swings in Nordic supply basins compress margin predictability for converters lacking long-term fiber contracts.
- Barrier performance limitations:Uncoated kraft's moisture susceptibility restricts penetration into frozen food and wet produce segments where polyethylene-coated alternatives retain functional dominance.
- REACH compliance friction:ECHA chemical substance restrictions on certain anti-slip coatings and print inks extend product qualification timelines for industrial-grade flat bags.
Strategic Opportunities
- Coated kraft innovation:Bio-based moisture barriers are opening frozen food applications previously closed to fiber-based packaging, with Germany's discount grocery chains piloting program adoption.
- Industrial bulk automation:Open-mouth sack formats with anti-slip coatings are capturing cement and chemical loading demand as FIBC bulk bags face workplace handling restrictions.
- Extended producer responsibility fee optimization:Producers calibrating manufacturing footprints against Germany's dual-system participation costs can arbitrage compliance burdens across Central European production nodes.
Industry Challenges
- Multiwall tuber technician scarcity:Specialized operators capable of calibrating pinch-bottom seal integrity on high-speed lines are concentrated among aging workforces in traditional paper converting regions.
- Food-contact certification timelines:FDA substance notification reviews for printed kraft grades extend go-to-market schedules, compressing first-mover advantage windows for format innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Paper Bags Market |
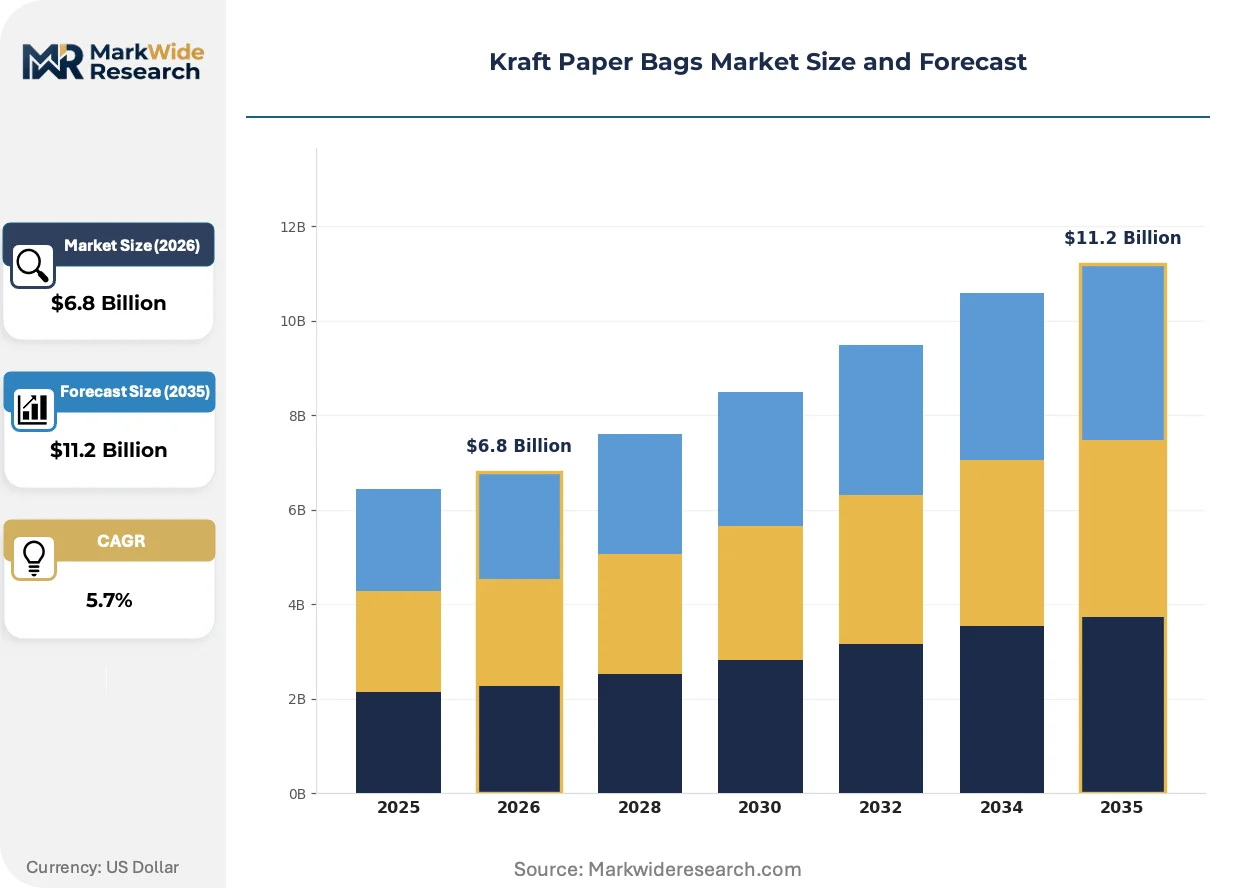
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Patch Handle Bags, Satchel Bags, Retail Bags Application: Food & Beverage, Retail, Grocery, Industrial End User: Restaurants, Supermarkets, E-Commerce, Wholesalers Distribution Channel: Online Stores, Brick-and-Mortar, Wholesale, Direct Sales |
| Companies Covered | Mondi Group, International Paper Company, WestRock Company, Smurfit Kappa Group, Georgia-Pacific LLC, Seaman Paper Company, BillerudKorsnäs, SHAMROCK, Nordic Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Paper Bags Market Strategic Shifts
Digital printing integration and bio-based barrier coatings are redefining performance specifications across food-contact and industrial kraft segments, while regulatory compliance automation is becoming a competitive differentiator.
Water-based flexographic printing with UV-curable inks is fragmenting the dominance of rotogravure for short-run branded orders. Boutique retailers and regional foodservice chains are adopting digitally printed patch handle bags for seasonal campaigns and private-label launches. This capability compression is enabling smaller converters to compete for orders previously captured by gravure-equipped majors with minimum volume thresholds.
The EU F-Gas Regulation is tightening specifications for fluorinated barrier treatments in food-contact kraft grades. Industrial converters are reformulating grease-resistant coatings to eliminate per- and polyfluoroalkyl substances ahead of enforcement deadlines. German frozen food distributors are qualifying alternative bio-wax barriers to maintain shelf-life performance without regulatory exposure.
Direct-to-restaurant procurement platforms are compressing traditional distributor intermediation in kraft bag supply chains. Foodservice operators in urban clusters are sourcing custom-printed carriers through consolidated digital portals that aggregate specification templates and streamline artwork approval. This channel displacement is most advanced in Germany's metropolitan foodservice markets, where procurement centralization is reducing supplier relationship fragmentation.
Kraft Paper Bags Market Segmentation
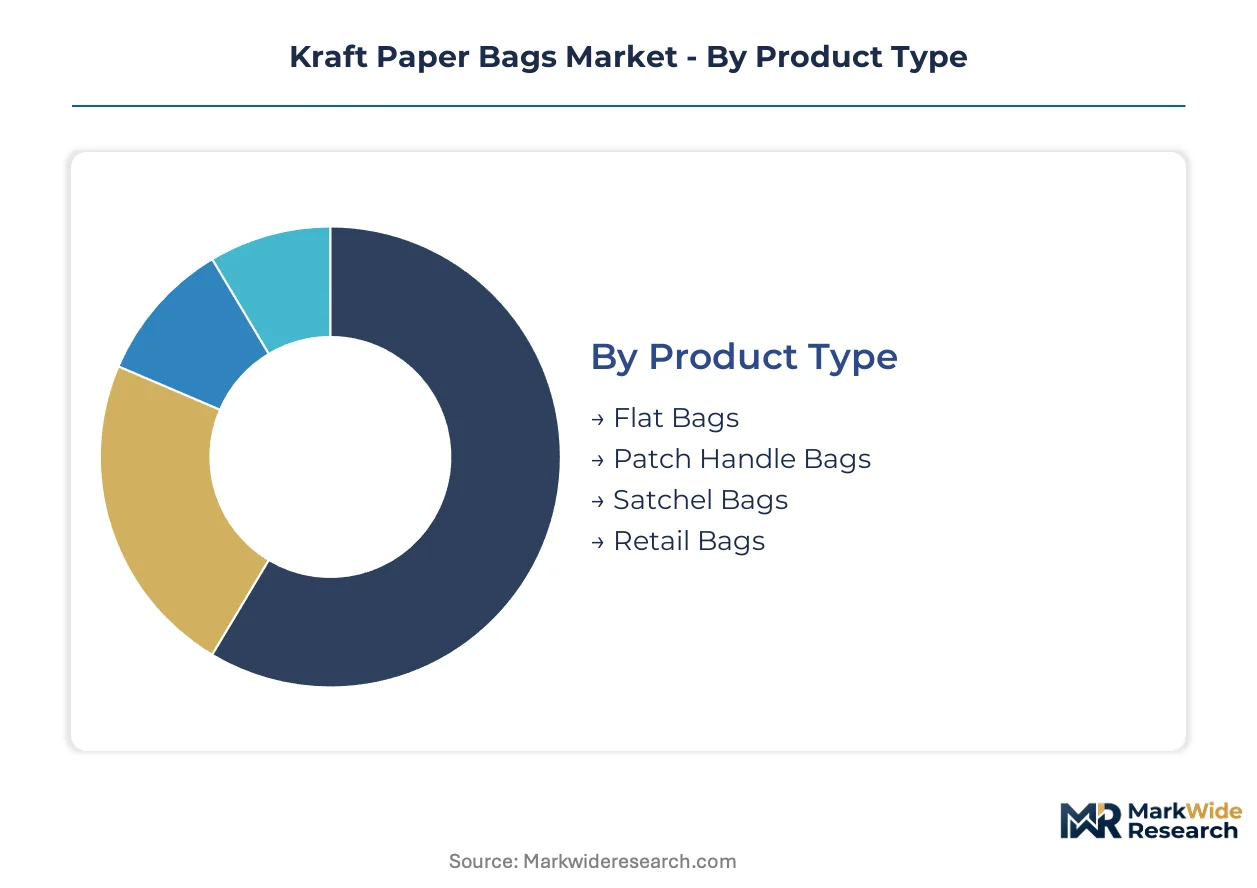
Segmentation in the kraft paper bags market reveals how substitution pressures from plastic bans and e-commerce durability requirements reshape procurement priorities across format types and customer channels. Understanding these divides exposes where fiber-based packaging captures volume versus where polyethylene alternatives retain functional dominance.
Product Type:
Substitution pressure from plastic carrier bans falls unevenly across bag constructions, with handle-integrated formats facing the strongest regulatory tailwinds while open-mouth industrial sacks confront entrenched polypropylene competition.
- Patch Handle Bags:Reinforced die-cut or twisted-paper handles bonded to 70–120 gsm kraft bodies deliver tear resistance for boutique retail and foodservice takeout. German quick-service chains and urban food halls in France are standardizing these for branded curbside pickup, driving specification of pinch-bottom seals with reinforced handle attachments.
- Flat Bags:Unhandled open-mouth or valve constructions from 40–80 gsm fiber serve industrial bulk loading of cement, chemicals, and agricultural products. Demand concentrates in Central European manufacturing corridors where anti-slip coatings and custom sizing sustain margin pools against FIBC bulk bag alternatives.
- Satchel Bags:Self-opening gusseted designs with block bottoms suit pharmacy and specialty retail applications requiring upright shelf display.
- Retail Bags:Lightweight twisted-handle carriers for general merchandise face the steepest competition from reusable non-woven totes in discount retail channels.
Patch Handle Bags retain volume leadership among consumer-facing formats; Flat Bags hold the steepest expansion curve in industrial automation corridors.
Application:
Cost tier differentiation separates commodity grocery formats from performance-specified food-contact and industrial grades, with barrier investments determining margin capture.
- Food & Beverage:Grease-resistant and freezer-grade kraft specifications with bio-wax or clay coatings capture quick-service restaurant and frozen food distributor procurement. EFSA compliance for direct food contact elevates qualification barriers against uncoated alternatives.
- Industrial:Multiwall constructions with polyethylene liners or anti-slip treatments handle cement, lime, and chemical loading where moisture protection and pallet stability outweigh fiber purity.
- Retail:Short-run digitally printed patch handle bags serve seasonal campaigns and private-label launches for boutique chains seeking brand differentiation.
- Grocery:Plain unbleached sulfate pulp sacks face margin compression from centralized supermarket procurement and minimum recycled content mandates under Germany's packaging ordinance.
Food & Beverage commands premium pricing tiers; Industrial applications scale through automated filling line integration.
End User:
Customer type fragmentation concentrates procurement leverage among e-commerce fulfillment networks and consolidated foodservice operators, displacing traditional distributor intermediation.
- E-Commerce:Fulfillment centers specify 90–120 gsm double-wall constructions with burst strength ratings for parcel durability, prioritizing branded print surfaces over plain grocery formats. Amazon and Zalando logistics hubs in Germany and Poland drive volume for pinch-bottom mailer sacks.
- Restaurants:Chain operators standardize custom-printed kraft for delivery and takeout, with urban clusters sourcing through direct-to-restaurant digital portals that compress traditional distribution.
- Supermarkets:Discounters Aldi and Lidl in Germany enforce recycled content thresholds and dual-system participation cost optimization across private-label bag procurement.
- Wholesalers:Cash-and-carry operators aggregate fragmented demand from independent foodservice, constraining specification customization and print complexity.
E-Commerce expands most quickly through fulfillment network densification; Supermarkets retain volume concentration through private-label standardization.
Distribution Channel:
Supply concentration among integrated pulp-to-bag producers favors direct sales and wholesale consolidation, while online channels fragment for standardized specifications.
- Direct Sales:Mondi Group and Smurfit Kappa anchor major accounts through captive mill supply and technical service integration for custom barrier formulations.
- Wholesale:Regional converters aggregate small-to-mid volume orders through distributor networks serving independent retail and foodservice.
- Online Stores:Template-based procurement portals enable standardized specification orders with compressed artwork approval for seasonal campaigns.
- Brick-and-Mortar:Traditional paper merchant channels face displacement as procurement centralization reduces relationship fragmentation.
Direct Sales capture margin through technical integration; Online Stores climb fastest among mid-volume customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated pulp-to-bag production concentrates in Central European mill networks, while demand fragmentation pulls procurement toward regional fulfillment hubs and national packaging ordinances reshape converter economics.
Germany
Quick-service restaurant chains standardize branded kraft bags for curbside pickup, driving pinch-bottom construction demand. The Central Agency Packaging Register enforces minimum recycled content thresholds under the national packaging ordinance. Berlin and Hamburg foodservice clusters source through direct-to-restaurant digital portals that compress traditional distribution.
United States
E-commerce fulfillment centers specify double-wall constructions with burst strength ratings for parcel durability. FDA food-contact substance notifications govern import eligibility for printed sacks. Amazon logistics hubs in Texas and California anchor procurement volumes for branded mailer formats.
China
Industrial-grade flat bag production serves cement and chemical loading applications with anti-slip coatings. The Ministry of Ecology and Environment enforces dual carbon goals that elevate recycled fiber sourcing requirements. Yangtze River Delta converters supply automated filling lines for bulk material handling.
France
Urban food halls adopt patch handle bags for boutique retail and takeaway service. ECHA chemical restrictions under REACH extend qualification timelines for industrial coatings. Paris metropolitan procurement centralization reduces supplier relationship fragmentation through consolidated digital portals.
India
Grocery and foodservice channels absorb unbleached sulfate pulp sacks as plastic carrier bans expand across states. FSSAI compliance frameworks elevate barrier specifications for direct food-contact grades. Maharashtra and Gujarat converter clusters serve quick-service restaurant expansion in Mumbai and Ahmedabad.
Kraft Paper Bags Market Competitive Environment
Concentration sits with integrated pulp-to-bag producers possessing captive fiber supply and multiwall tuber capacity. Three tiers structure competitive positioning: multinational paperboard conglomerates with mill networks, regional converters serving national foodservice accounts, and specialized boutique producers for short-run digital print orders. Dominant competitive moves include backward integration into recycled fiber collection streams and capacity expansion for coated kraft barrier formulations.
Within the integrated multinational tier, Mondi Group and Smurfit Kappa Group exemplify archetypes with captive Central European mill supply. WestRock Company occupies a position among North American paperboard specialists with coated kraft capabilities. These three anchors represent the scale-driven end where technical service integration and custom barrier development separate procurement winners from commodity converters.
| Leading Market Players |
|---|
| Mondi Group |
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group |
| Georgia-Pacific LLC |
| Seaman Paper Company |
| BillerudKorsnäs |
| SHAMROCK |
| Nordic Paper |
| Others |
Value Chain & Pricing Dynamics
Germany's national packaging ordinance enforced by the Central Agency Packaging Register gates both supply qualification and price differentiation simultaneously, as converters must secure certified post-consumer fiber streams to meet minimum recycled content thresholds while buyers pay premiums for compliant documentation. This regulatory anchor compresses margin pools for uncertified competitors and elevates pricing power for integrated producers with captive recycled fiber collection.
Pricing Analysis
Germany's packaging ordinance dictates the pricing tier structure across the kraft paper bags landscape, separating premium food-contact grades with EFSA compliance from standard industrial formats and economy grocery sacks. Price differentiation rests on certification level and volume scale, with quick-service restaurant chains absorbing higher per-unit costs for custom-printed patch handle bags while discount supermarkets drive cost compression through centralized procurement of plain unbleached sulfate pulp formats. Pricing pressure stems from virgin pulp cost volatility in Nordic supply basins, squeezing converters lacking long-term fiber contracts. Supermarket buyers exhibit highest price sensitivity, whereas e-commerce fulfillment centers prioritize burst strength ratings over unit cost.
Supply Chain Analysis
Softwood sulfate pulp availability from Nordic mills constitutes a chokepoint that underwrites converter economics across Central European production networks. Geographic supply concentrates in Germany, Poland, and Sweden, where integrated pulp-to-bag producers operate captive mill supply. Raw material dependencies draw from post-consumer recycled fiber streams, unbleached sulfate pulp, and bio-based barrier coatings. Single-source vulnerability runs through certified recycled fiber collection networks constrained by Germany's dual-system participation requirements. Distribution runs through direct sales channels for major accounts and wholesale consolidation for fragmented independent foodservice demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kraft paper bags market sits in cyclical recovery as EU Single-Use Plastics Directive enforcement accelerates polyethylene substitution toward fiber-based alternatives, creating sustained demand tailwinds for compliant producers.
For Market Incumbents: Compound defensive positioning through backward integration into recycled fiber collection streams and capacity expansion for coated kraft barrier formulations in Poland and Germany. The threat of bio-based plastic alternatives from chemical majors demands preemptive investment in moisture-resistant food-contact grades. Certification investment in EFSA-compliant production lines anchors margin capture against commodity converters. For New Entrants and Emerging Players: Differentiate on digital printing integration for short-run seasonal campaigns targeting boutique retail chains and urban food halls in France and Germany. The most penetrable white space sits in direct-to-restaurant procurement platforms that displace traditional distributor intermediation. A focused go-to-market angle combines template-based specification portals with compressed artwork approval workflows for mid-volume foodservice operators. For Investors and Strategic Acquirers: EU F-Gas Regulation enforcement deadlines reshape the acquisition landscape toward converters with fluorine-free barrier coating capabilities and REACH-compliant ink formulation expertise. Long-term viability over the next decade favors targets with integrated pulp supply and multiwall tuber technician training pipelines. The signal to watch is pilot program adoption of bio-wax barriers by German frozen food distributors as inflection indicator for coated kraft scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Captive post-consumer fiber supply secures compliance with Germany's packaging ordinance thresholds. |
| Coated Kraft Barrier Capacity Expansion | Bio-wax and clay coating lines penetrate frozen food segments previously closed to fiber packaging. |
| Digital Printing Platform Deployment | Short-run capabilities capture boutique retail seasonal campaigns from gravure-equipped majors. |
| Direct-to-Restaurant Procurement Portal | Channel displacement in Berlin and Hamburg foodservice clusters reduces distributor fragmentation. |
| Multiwall Tuber Technician Training Pipeline | Specialized operator scarcity in aging workforces threatens pinch-bottom seal integrity on high-speed lines. |
Study Parameters
A standing panel of paper converting plant managers, quick-service restaurant procurement directors, e-commerce fulfillment center operations leads, and Central Agency Packaging Register compliance officers provided ongoing calibration across the study period. Primary interview data combined with secondary validation from EU F-Gas Regulation enforcement notices, ECHA REACH substance restriction updates, German packaging ordinance filings, and customs trade records for kraft pulp imports. Bottom-up volume aggregation across product type and application segments triangulated against top-down macroeconomic demand indicators.
Consistency checks validated volume and value outputs against external benchmarks including paper industry production statistics and foodservice packaging procurement surveys. The analytical framework modeled segmentation across product construction, barrier specification tier, end-use industry, and regional regulatory cluster throughout the projection horizon. CAGRs derived from trend extrapolation of substitution rates from polyethylene carriers and e-commerce fulfillment network densification patterns, with specific inputs for virgin pulp price elasticity and recycled fiber availability constraints.
The analysis sits within stated boundaries; outcomes outside sustained EU Single-Use Plastics Directive enforcement or accelerated bio-based plastic commercialization would require recalibration. Forecasts reflect documented assumptions around regulatory compliance timelines and fiber supply contract structures. Practitioners should keep alternative scenarios live as ECHA chemical restriction expansions and Nordic pulp capacity investments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Middle East and Africa Coated Paper Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Cushioned Mailer Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market