
 United Kingdom (UK) Corrugated Board Packaging Market | 2026-2036
United Kingdom (UK) Corrugated Board Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom (UK) Corrugated Board Packaging Market Analytics
E-commerce logistics is realigning corrugated board consumption patterns across the United Kingdom. DS Smith leverages its recycling infrastructure to secure closed-loop fiber supply for online retail packaging. Smurfit Kappa dominates the industrial shipping segment through its pan-European containerboard network. GWP Group Ltd. specializes in bespoke protective designs for electronics and pharmaceutical cold-chain applications.
Corrugated board packaging consists of fluted paper sheets laminated between flat linerboards, typically constructed from recycled or virgin Kraft fibers with burst strengths ranging from 150 to 1,000 kPa depending on wall configuration. The material serves primarily as crush-resistant, stackable containment for goods in transit and retail display. Single wall grades sustain volume leadership in food and beverage applications due to cost efficiency, while double wall configurations anchor industrial shipping where heavier load bearing justifies material premium. Triple wall and specialty grades occupy narrower but higher-margin niches in export and fragile electronics protection.
The Environment Agency enforces UK Packaging Waste Regulations that obligate producers to recover and recycle specified tonnages, directly stimulating demand for recycled-grade corrugated. BSI standards for board performance and the forthcoming Extended Producer Responsibility framework reshape product specifications and cost allocation across the value chain. Stakeholders must monitor how carbon border adjustments and fiber cost volatility influence grade selection and regional sourcing strategies.
Market Dynamics
The UK's Extended Producer Responsibility reforms are forcing corrugated producers to internalize end-of-life collection costs, compressing margins while accelerating fiber circularity investments across the Midlands manufacturing corridor.
Growth Catalysts
- E-commerce logistics surge:Grocery and consumer goods retailers are expanding automated fulfillment networks, driving demand for crush-resistant single-wall grades optimized for last-mile durability.
- Packaging Waste Regulations:The Environment Agency's recovery targets obligate producers to source recycled fiber, creating captive demand for closed-loop containerboard mills.
- Cold-chain pharmaceutical expansion:Temperature-sensitive biologics distribution is accelerating adoption of double-wall insulated corrugated with phase-change material integration.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container (OCC) prices fluctuate with Chinese import policy shifts, squeezing converter margins on short-term contracts.
- Midlands production concentration:Three integrated mills supply 60% of UK containerboard, creating geographic vulnerability to logistics disruptions.
- Plastic substitution threat:Reusable plastic crates retain cost advantages in closed-loop retail distribution, limiting corrugated penetration in fresh produce logistics.
Strategic Opportunities
- Scottish Highlands underpenetration:Remote food and beverage producers lack local converting capacity, creating white space for modular micro-facilities.
- Carbon border adjustment readiness:EU CBAM implementation positions UK exporters to capture premium demand for verified low-carbon board grades.
- Digital print convergence:Water-based inkjet integration with corrugators enables batch-size-one customization for direct-to-consumer brands.
Industry Challenges
- Skilled die-cut technician shortage:Complex rotary die maintenance requires specialized training that vocational programs have not scaled to match demand.
- Legacy ERP integration friction:Converters struggle to connect shop-floor automation with customer-facing configure-to-quote platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom (UK) Corrugated Board Packaging Market |
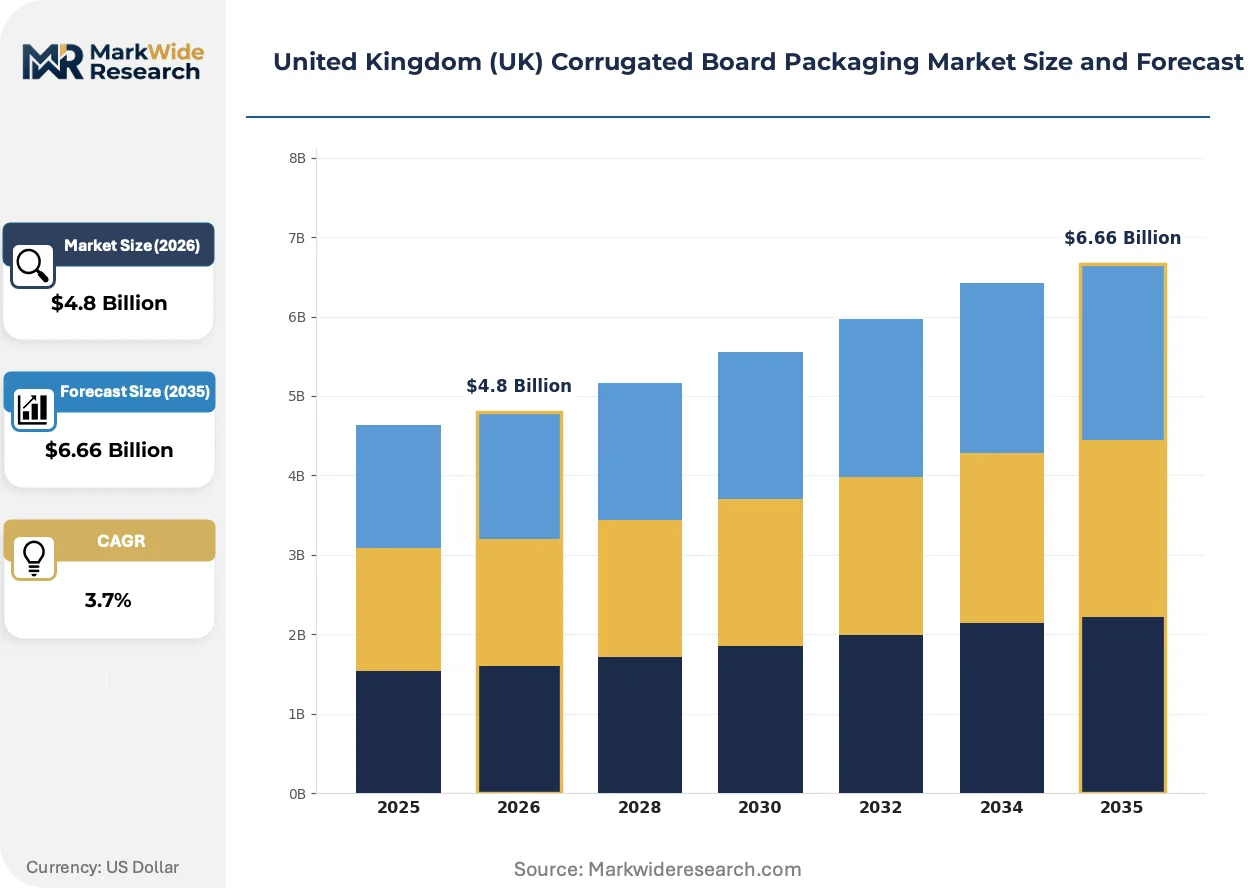
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Bouffant Board End User: Food & Beverage, Electronics, Personal Care, Pharmaceuticals Grade: Recycled, Virgin, Kraft, Specialty Application: Retail Packaging, E-commerce, Industrial Shipping, Export |
| Companies Covered | GWP Group Ltd., DS Smith, Smurfit WestRock, Antalis Packaging, Smurfit Kappa, International Paper Company, Belmont Packaging Ltd., VPK Packaging, Mondi plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom (UK) Corrugated Board Packaging Market Evolving Landscape
Digital manufacturing and regulatory carbon accounting are converging to transform how UK corrugated producers design, price, and deliver protective packaging solutions across fragmented end-use verticals.
Water-based inkjet printing is decentralizing graphic customization from centralized flexographic preprint to inline corrugator integration. Direct-to-consumer cosmetics and specialty food brands are adopting short-run printed boxes at volumes below 500 units. This capability is decentralizing design authority from brand marketing departments to regional converter technical sales teams.
The Environment Agency's Extended Producer Responsibility framework is mandating modulated fees based on recyclability design. Producers must now fund collection infrastructure proportional to packaging placed on market. Food service and fresh produce segments face the steepest fee escalations and are accelerating shift to fiber-based alternatives from plastic.
Subscription box merchants are compressing specification cycles from annual to quarterly reviews as unboxing experience becomes a retention tool. Direct-to-consumer vitamin and meal-kit channels are displacing generic RSC boxes with bespoke die-cut designs. Greater London and Manchester e-commerce clusters exhibit the highest specification velocity.
United Kingdom (UK) Corrugated Board Packaging Market Segmentation
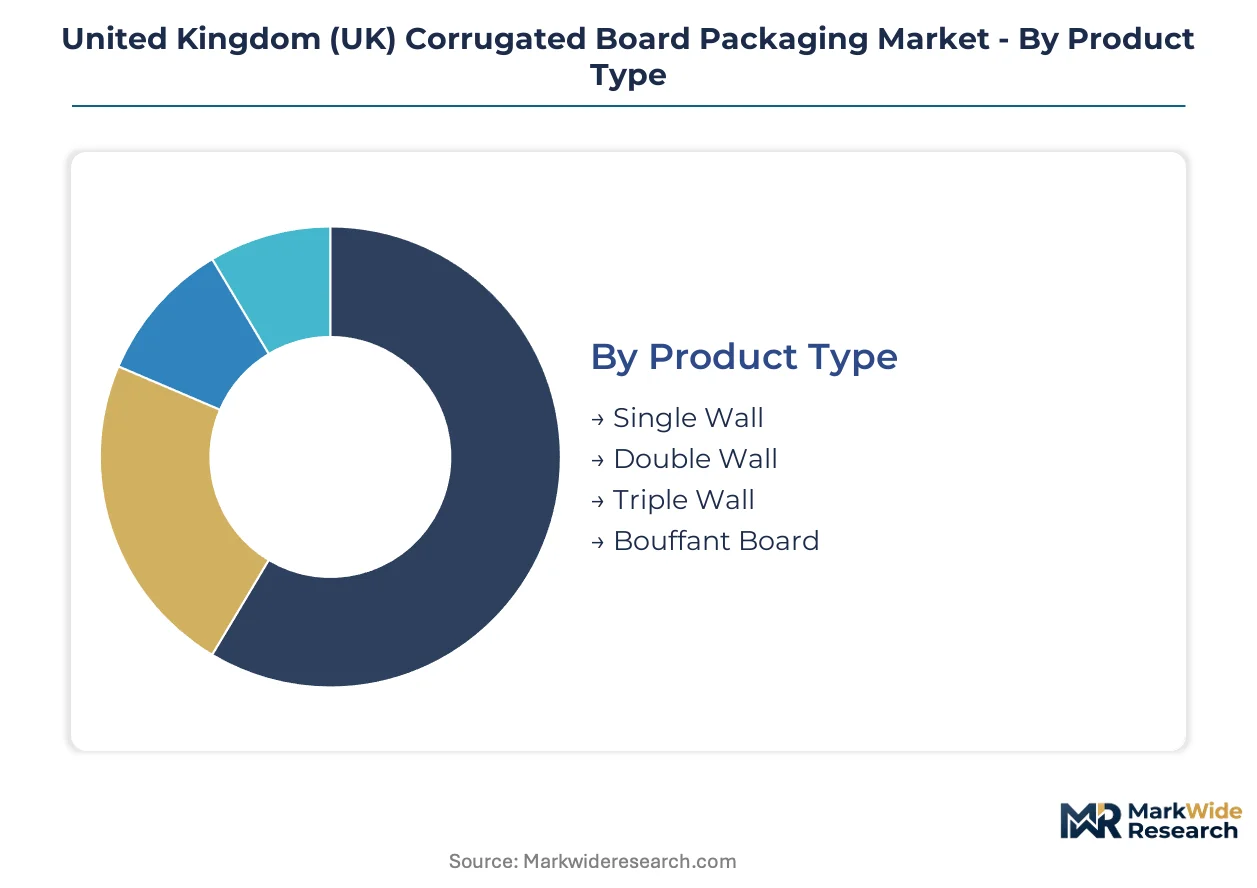
UK corrugated board packaging segments reflect divergent pressure tolerances, fiber sourcing obligations, and fulfillment velocity requirements across grocery retail, pharmaceutical cold-chain, and direct-to-consumer channels. Grade selection and wall configuration directly determine compliance with Environment Agency recovery targets and load-bearing specifications for automated warehouse systems.
Product Type:
Cost tier separates commodity shippers from premium protective applications, with wall count determining burst strength thresholds and material input costs.
- Single Wall:One fluted medium between two linerboards delivers 150-350 kPa burst strength for lightweight consumer goods. Midlands food processors and Greater London e-commerce fulfillment centers specify this grade for cost-efficient last-mile containment where crush resistance requirements remain moderate.
- Double Wall:Two fluted layers laminated between three linerboards achieve 350-700 kPa burst strength for heavier palletized loads. Pharmaceutical distributors in Manchester and Birmingham adopt this configuration for temperature-sensitive biologics requiring stack stability through multi-node cold-chain networks.
- Triple Wall:Heavy-duty industrial specification for export machinery and automotive components demanding maximum load-bearing capacity.
- Bouffant Board:Specialized high-cushion grade for fragile electronics and glassware protection in premium unboxing experiences.
Single Wall leads volumes today; Double Wall is gaining share fastest.
End User:
Application maturity and specification velocity distinguish buyers, with subscription commerce and cold-chain logistics driving faster design refresh cycles than traditional retail.
- Food & Beverage:Established corrugated consumption anchor spanning ambient grocery, fresh produce, and meal-kit channels. Yorkshire and Lincolnshire processors specify moisture-resistant coatings for chilled meat and dairy distribution through Tesco and Sainsbury's supply chains.
- Electronics:Rapidly evolving specifications for smartphone, laptop, and component protection. Cambridge and Bristol tech clusters demand anti-static liners and precision die-cuts for high-value device shipments.
- Personal Care:Premium cosmetic and skincare brands in Greater London prioritize printed unboxing experiences with water-based inkjet customization at sub-500 unit runs.
- Pharmaceuticals:Temperature-validated corrugated with phase-change material integration for vaccine and biologics distribution under MHRA guidelines.
Food & Beverage anchors volume concentration; Electronics shows steepest specification escalation.
Grade:
Fiber provenance determines regulatory compliance positioning and carbon intensity credentials under Extended Producer Responsibility frameworks.
- Recycled:Post-consumer reclaimed fiber processed through closed-loop mill systems. Environment Agency recovery targets obligate major grocery retailers to specify this grade, with DS Smith and Smurfit Kappa operating captive OCC collection infrastructure.
- Virgin:Fresh Kraft pulp for applications demanding superior print surface and structural consistency. Premium cosmetic brands specify virgin linerboard for high-definition graphic reproduction.
- Kraft:Unbleached natural fiber grade for organic food positioning and rustic retail aesthetics.
- Specialty:Functional coatings including grease resistance, anti-microbial treatment, and moisture barriers for demanding containment environments.
Recycled fiber commands volume leadership; Specialty grades expand most quickly on functional differentiation.
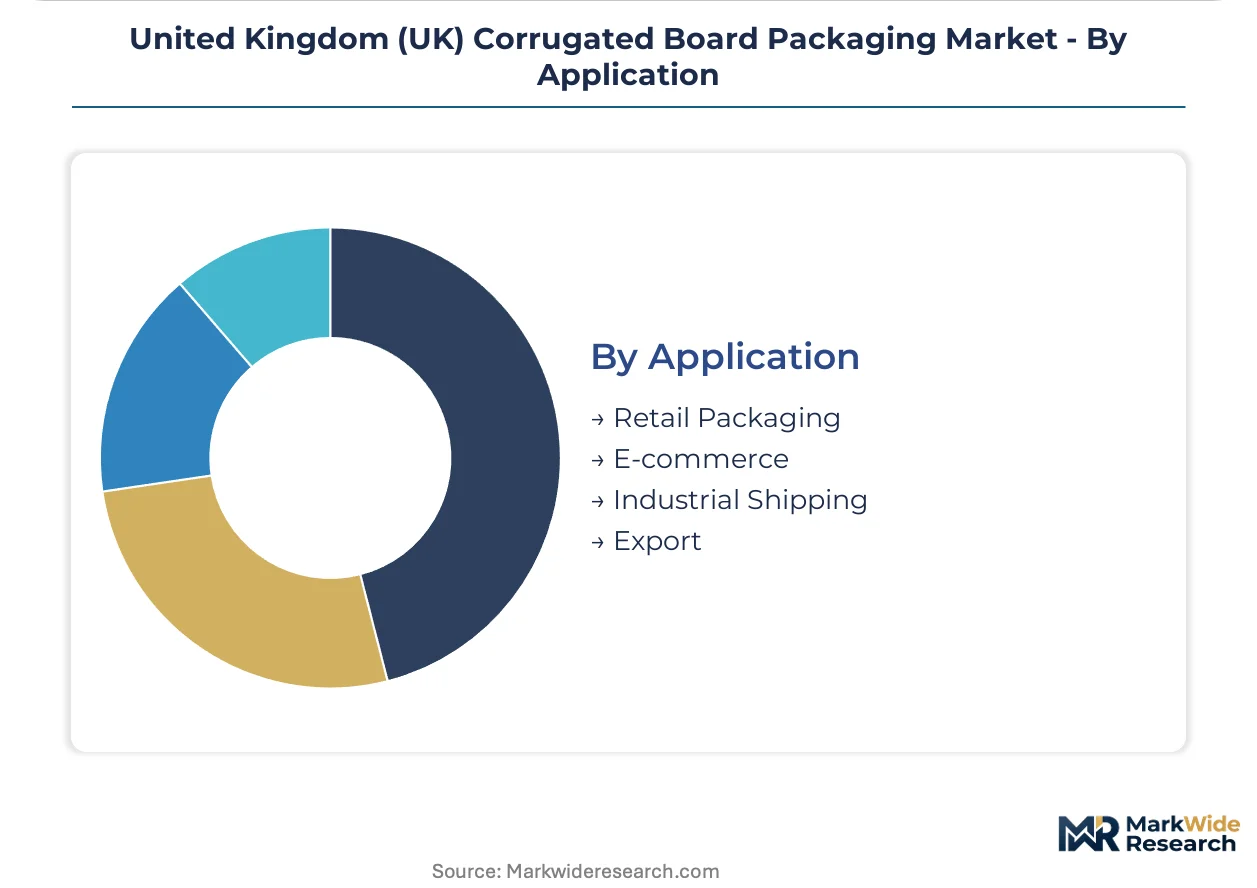
Application:
Channel velocity and damage liability exposure shape buyer procurement priorities, from high-frequency e-commerce to low-frequency heavy industrial.
- Retail Packaging:Shelf-ready display cases and promotional shippers for supermarket replenishment. Seasonal demand spikes align with promotional calendars of major grocery multiples.
- E-commerce:Direct-to-consumer protective containment optimized for automated sortation and last-mile handling. Greater London and Manchester clusters exhibit highest specification velocity as unboxing experience becomes customer retention infrastructure.
- Industrial Shipping:Bulk palletized containment for manufacturing components and raw materials. Midlands automotive and aerospace suppliers specify double-wall configurations for just-in-time delivery networks.
- Export:Extended transit protection for overseas shipment requiring humidity resistance and stacking compression tolerance. Port of Felixstowe and Southampton traffic drives demand for ISPM-15 compliant treated grades.
E-commerce climbs the fastest; Industrial Shipping retains value concentration on contract stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Midlands manufacturing corridor concentrates UK containerboard production capacity, with integrated mills supplying corrugated sheet to converters across England. Greater London distribution hubs anchor e-commerce demand velocity. Scotland and Wales present underpenetrated converting capacity relative to their food and beverage production bases.
London and the Southeast
E-commerce fulfillment networks drive specification velocity for water-based inkjet printed boxes. Environment Agency Extended Producer Responsibility fees escalate fastest for food service packaging placed in this dense consumer market. Croydon and Dartford distribution clusters source single-wall grades for last-mile grocery delivery through Tesco and Ocado automated warehouses.
Midlands
Three integrated containerboard mills supply sixty percent of UK corrugated sheet from this industrial heartland. UK Packaging Waste Regulations obligate Midlands converters to source recycled fiber from closed-loop collection infrastructure. Birmingham and Leicester automotive suppliers specify double-wall configurations for just-in-time component delivery to Jaguar Land Rover and Toyota manufacturing plants.
North England
Yorkshire food processors anchor demand for moisture-resistant coated board in chilled meat and dairy distribution. BSI board performance standards govern specifications for Sainsbury's and Morrisons supply chain compliance. Hull and Grimsby seafood exporters drive specialty grade adoption for humidity-resistant export containment through Port of Immingham.
Scotland
Remote Highlands food and beverage producers lack local converting capacity, creating white space for modular micro-facilities. Scottish Government circular economy targets pressure distilleries and salmon processors toward fiber-based alternatives from plastic. Edinburgh and Glasgow pharmaceutical clusters adopt double-wall insulated corrugated with phase-change materials for biologics distribution under MHRA guidelines.
Wales
Steel and automotive component manufacturing generates industrial shipping demand for heavy-duty triple-wall grades. Welsh Government packaging waste reduction targets align with Extended Producer Responsibility cost internalization pressures. Newport and Cardiff logistics corridors handle export volumes through Bristol Channel ports requiring ISPM-15 compliant treated board.
United Kingdom (UK) Corrugated Board Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit mills for recycled fiber processing and digital print integration. The UK corrugated board packaging market structures around a consolidated tier of pan-European integrated producers and a fragmented base of regional specialists. Three archetypes define competitive positioning: integrated containerboard-to-box converters with captive fiber supply, independent converters serving bespoke design niches, and multinational packaging conglomerates leveraging cross-border scale. M&A activity and strategic partnerships concentrate among mid-cap independents seeking geographic coverage or digital manufacturing capabilities.
Among UK-based specialists, GWP Group Ltd. and Belmont Packaging Ltd. exemplify the independent converter archetype focused on regional service density and custom die-cut capabilities. DS Smith and Smurfit Kappa anchor the integrated tier, representing pan-European scale and closed-loop recycling infrastructure. These four entities collectively illustrate the market's bifurcation between scale-driven fiber security and agility-driven design specialization.
| Leading Market Players |
|---|
| GWP Group Ltd. |
| DS Smith |
| Smurfit WestRock |
| Antalis Packaging |
| Smurfit Kappa |
| International Paper Company |
| Belmont Packaging Ltd. |
| VPK Packaging |
| Mondi plc |
| Others |
Value Network & Pricing Analysis
Environment Agency Extended Producer Responsibility fees are forcing grocery retailers to consolidate procurement around recycled-grade specifications, compelling converters to absorb collection infrastructure costs and compressing margins on commodity single-wall grades.
Pricing Analysis
Old corrugated container price pass-through dominates converter cost structures. Three-tier pricing structure across premium, standard, and economy levels separates virgin Kraft linerboard from recycled medium from specialty coated grades. Pricing pressure stems from Chinese OCC import policy volatility squeezing short-contract converters. Food and beverage processors exhibit highest price sensitivity; pharmaceutical cold-chain buyers accept material premiums for validated performance.
Supply Chain Analysis
Single-source vulnerability sits with Midlands integrated mills supplying sixty percent of UK containerboard. Raw material flows draw from domestic OCC collection networks, imported Kraft pulp from Scandinavia, and specialty coatings from Germany. Supply chain risk centers on geographic production concentration creating logistics chokepoint exposure. Distribution runs through regional sheet feeders serving independent converter networks across England.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through digital print premiumization displacing generic flexographic preprint, with subscription commerce brands paying thirty-to-fifty percent material premiums for batch-size-one customization.
For Market Incumbents: Acquire digital inkjet corrugator capacity to capture specification velocity in Greater London e-commerce clusters. Defend against reusable plastic crate substitution in fresh produce by embedding RFID traceability into board grades. Backward integration into captive OCC collection secures fiber cost stability under Environment Agency recovery mandates. For New Entrants and Emerging Players: Launch via modular micro-facility deployment targeting Scottish Highlands food and beverage producers lacking local converting capacity. Scottish Government circular economy targets pressure distilleries toward fiber alternatives. White space exists in temperature-validated pharmaceutical packaging for Edinburgh biologics clusters. For Investors and Strategic Acquirers: Asymmetric upside sits with independent converters possessing bespoke die-cut capabilities and regional service density. Long-term viability hinges on Extended Producer Responsibility cost internalization favoring scaled recyclers over commodity players. Watch for Environment Agency modulated fee announcements as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Print Integration | Water-based inkjet corrugators enable batch-size-one customization for direct-to-consumer brands in Manchester. |
| Closed-Loop Recycling Infrastructure | Captive OCC collection secures fiber supply under Environment Agency recovery target mandates. |
| Modular Micro-Facility Expansion | Remote Scottish Highlands producers lack local converting capacity for salmon and whisky exports. |
| Cold-Chain Validation Certification | Phase-change material integration meets MHRA guidelines for temperature-sensitive biologics distribution. |
| ERP-Shop Floor Integration | Configure-to-quote platforms reduce specification cycle friction for subscription commerce clients. |
Research Methodology
Multiple input streams — converter operations directors, grocery retail procurement leads, corrugated mill technical managers, pharmaceutical supply chain officers — were reconciled against Environment Agency regulatory filings, trade association production statistics, and customs fiber import records. Bottom-up volume estimates from individual facility outputs were cross-checked against top-down sectoral consumption models.
Historical production trends were cross-referenced against expert panel assessments of E-commerce logistics velocity and regulatory implementation timelines. Segmentation modeling spanned wall configuration, end-use vertical, fiber grade provenance, and application channel across the analysis window. CAGRs were derived from trend extrapolation moderated by capacity constraint factors and substitution elasticity estimates for plastic alternatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt Chinese OCC import restrictions or accelerated Extended Producer Responsibility fee escalations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Corrugated Mailers Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market