
 Paper IBC Container Market | 2026-2036
Paper IBC Container Market Size, Share, and Industry Trends Forecast 2026-2036
Paper IBC Container Market Analytics
The capital-intensity divergence between integrated paperboard producers and regional converters is unwinding competitive stability in the paper IBC container space. Mondi leverages captive pulp supply and extrusion coating capacity to control liner barrier performance. Greif sustains North American market presence through its industrial packaging network and steel-to-paper IBC transition programs. DS Smith competes on circular design credentials, embedding recycled fiber content targets into customer procurement frameworks.
A paper IBC container is a fiberboard-based intermediate bulk container with a multiwall corrugated body, laminated moisture barrier, and integrated polyethylene liner, engineered to transport 250 to 1,500 liters of liquid, paste, or granular materials. The container collapses flat after discharge, reducing return freight cost and warehouse footprint versus rigid alternatives. Collapsible IBCs lead volume share due to downstream logistics savings, while customized IBCs capture margin pools through food-grade and chemical-resistant liner configurations. The 1,000-liter capacity segment anchors standard procurement patterns across European chemical distributors.
REACH restricts hazardous substance migration into fiber-based packaging, compelling liner material reformulation by compounders serving this market. FDA food contact regulations and EU Green Deal circularity targets jointly shape product development roadmaps, with EFSA guidance on recycled fiber safety adding compliance layers. Stakeholders must monitor evolving liner adhesive chemistries and regional extended producer responsibility schemes to anticipate cost pass-through structures and qualification timelines.
Market Dynamics
The EU Green Deal's mandatory recycled content thresholds are forcing liner compounders to reformulate barrier chemistries, compressing qualification timelines and redrawing supplier qualification hierarchies across European chemical distributors.
Growth Catalysts
- REACH migration limits:ECHA's tightened hazardous substance thresholds compel food-grade liner redesigns, opening procurement windows for certified fiber-based alternatives.
- Steel-to-paper transition programs:Industrial packaging buyers in Germany and France are retiring metal IBC fleets to meet Scope 3 reduction targets.
- Kraft linerboard innovation:Wet-strength chemistries from Nordic pulp mills now achieve moisture barriers competitive with multi-layer plastic laminates.
Market Restraints
- Pulp cost volatility:Bleached kraft pulp pricing swings tied to Brazilian supply disruptions compress converter margins unpredictably.
- Extrusion coating concentration:Barrier film supply clusters in Germany and Austria create single-source vulnerability for regional IBC assemblers.
- Performance ceiling in solvents:Aromatic hydrocarbon resistance remains inferior to steel alternatives, blocking chemical sector penetration.
Strategic Opportunities
- Indian food processing corridors:FSSAI's plastic reduction mandates in Maharashtra and Gujarat create first-mover openings for fiber-based liquid transport.
- Pharmaceutical aseptic filling:Gamma-sterilizable liner configurations address biologics bulk shipment needs in Swiss and Belgian manufacturing clusters.
- Digital print integration:QR-coded IBCs enable batch traceability for EU CSRD supply chain disclosure requirements.
Industry Challenges
- Adhesive qualification timelines:EFSA's evolving recycled fiber safety assessments delay food-contact certifications by 8-14 months.
- Corrugator retrofit requirements:Multiwall board production for 1,500-liter capacities demands press upgrades that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper IBC Container Market |
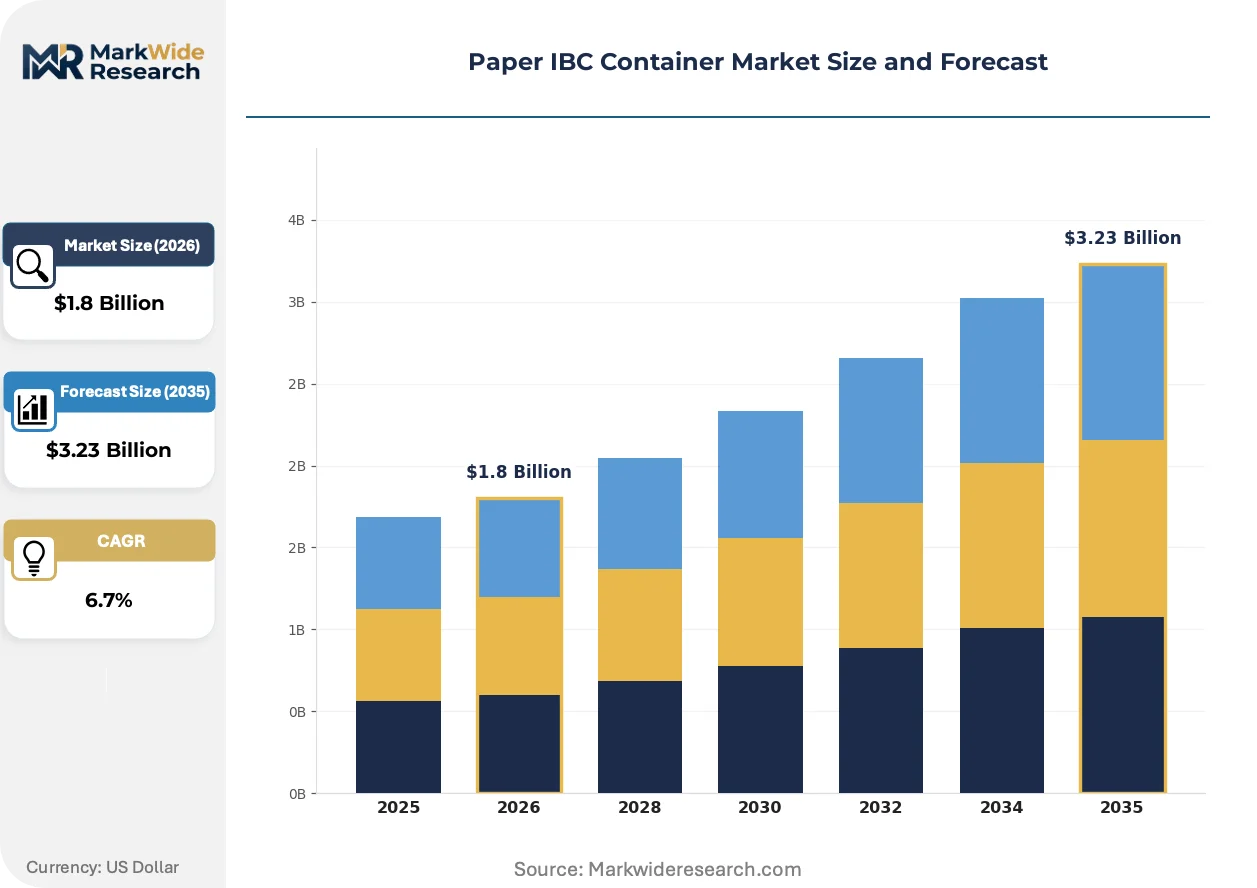
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard IBCs, Customized IBCs, Collapsible IBCs, Rigid IBCs End User: Food Industry, Chemical Industry, Pharmaceutical Sector, Agricultural Sector Capacity: 250 Liters, 500 Liters, 1000 Liters, 1500 Liters Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Retailers |
| Companies Covered | Mondi, LC Packaging, Paper Systems, Global-Pak, Conitex Sonoco, International Paper Company, Greif, Berry Global, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper IBC Container Market Evolving Landscape
Barrier chemistry innovation and regulatory disclosure mandates are converging to redefine competitive advantage around material traceability rather than unit economics alone.
Biopolymer liner formulations derived from fermented cellulose are fragmenting the incumbent polyethylene-dominated barrier market. Food processors in Denmark and the Netherlands are piloting these liners for dairy and edible oil transport. The technology is fragmenting established supplier relationships as compounders without biopolymer capabilities lose shelf space in sustainability-driven procurement frameworks.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from food-contact liners. German chemical distributors now require fluorine-free barrier declarations in RFP documentation. The regulation is compressing formulation development cycles as compounders race to qualify silicone and clay-based alternatives before 2026 enforcement deadlines.
Consolidated buying cooperatives among French and Belgian beverage exporters are displacing spot-market IBC procurement with multi-year framework agreements tied to circularity metrics. These contracts bundle container supply with reverse logistics and fiber recovery services. The model is most visible in wine and spirits bulk shipping, where cooperative members pool volume to secure dedicated production lines from converter networks.
Paper IBC Container Market Segmentation
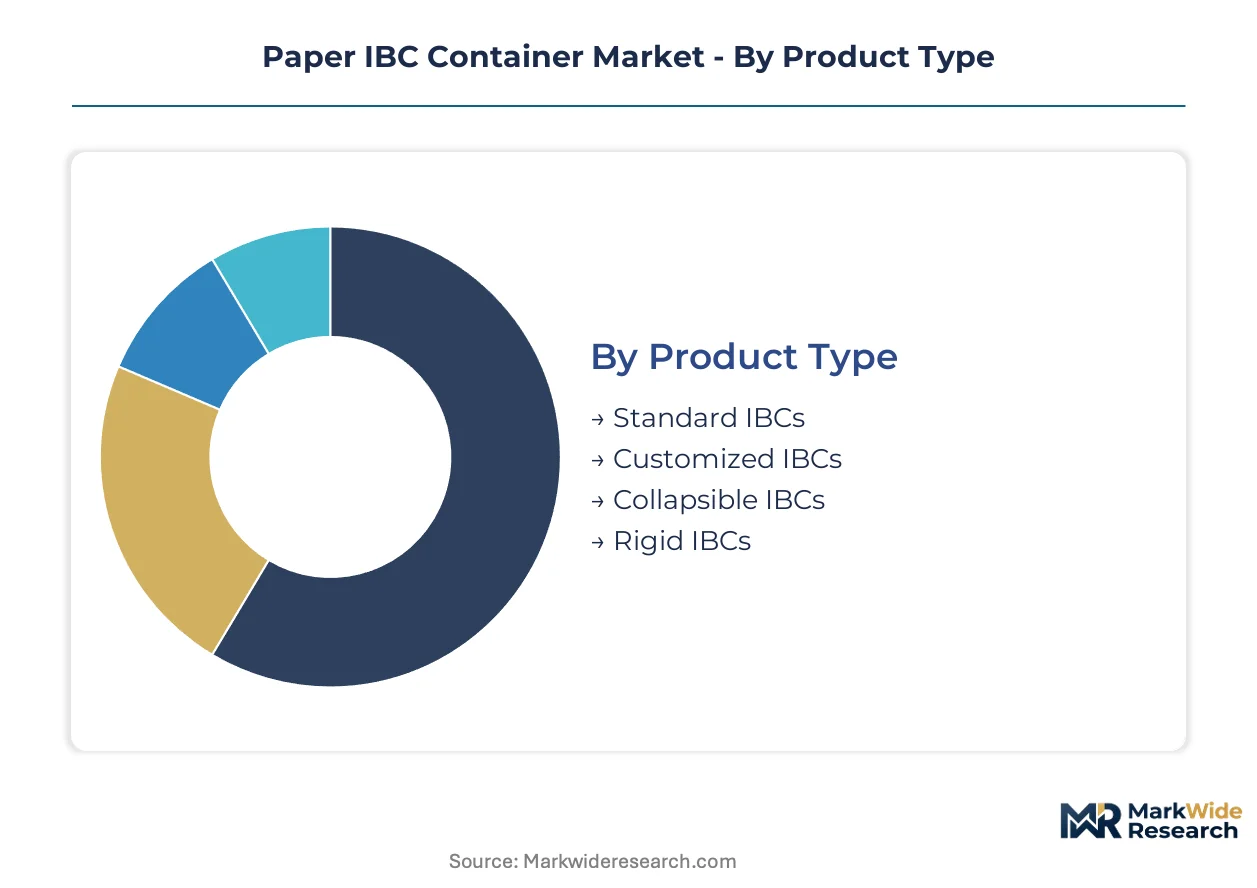
Paper IBC container procurement patterns diverge sharply by channel and end-use, with chemical distributors favoring standardized volumes while food processors demand customized liner configurations. Segment boundaries are blurring as integrated converters bundle design services with logistics contracts.
Product Type:
Channel mix varies by structural format, with collapsible IBCs flowing through distributor networks and rigid variants commanding direct sales relationships with chemical processors.
- Collapsible IBCs:These containers fold flat after discharge, cutting return freight costs by roughly two-thirds versus rigid alternatives. German chemical distributors are standardizing on 1,000-liter collapsible formats to optimize reverse logistics under EU Green Deal circularity mandates.
- Customized IBCs:Engineered with food-grade or chemical-resistant liner specifications, these command margin premiums through tailored barrier chemistries. Danish dairy processors and Dutch edible oil refiners are driving specification intensity as they retire plastic IBC fleets.
- Standard IBCs:Off-the-shelf corrugated bodies with generic polyethylene liners serve cost-sensitive agricultural chemical blending operations.
- Rigid IBCs:Reinforced multiwall construction targets solvent transport where dimensional stability under stacking load is non-negotiable.
Collapsible IBCs dominate installed base. Customized IBCs are where expansion concentrates.
End User:
Application-driven cost tiers separate premium liner investments from commodity procurement, with pharmaceutical aseptic requirements sitting atop the value pyramid.
- Chemical Industry:REACH migration limits and fluorine-free barrier mandates are forcing liner reformulation across German and French industrial packaging buyers. Steel-to-paper transition programs here concentrate volume demand.
- Food Industry:EFSA recycled fiber safety assessments and FSSAI plastic reduction mandates in Maharashtra and Gujarat are opening procurement windows for certified fiber-based liquid transport. Wet-strength kraft innovations from Nordic pulp mills now match multi-layer plastic laminate performance.
- Pharmaceutical Sector:Gamma-sterilizable liner configurations address biologics bulk shipment needs in Swiss and Belgian manufacturing clusters.
- Agricultural Sector:Fertilizer and pesticide blending operations prioritize unit cost over barrier sophistication, accepting standard liner specifications.
Chemical Industry anchors procurement volume. Food Industry represents the steepest expansion trajectory.
Capacity:
Volume scale determines corrugator press requirements and converter capital intensity, with 1,500-liter formats demanding equipment upgrades that strain mid-tier balance sheets.
- 1000 Liters:The standard procurement anchor across European chemical distributors, this capacity optimizes pallet footprint and truck cube utilization. REACH-compliant liner configurations are qualifying fastest at this scale due to concentrated buyer demand.
- 1500 Liters:Multiwall board production demands corrugator press upgrades, creating supply concentration among integrated producers with captive pulp supply. German beverage exporters in consolidated buying cooperatives are pooling volume to secure dedicated production lines.
- 500 Liters:Mid-scale format serves specialty chemical sampling and pilot-batch pharmaceutical production.
- 250 Liters:Compact footprint targets laboratory and small-batch food processing applications where handling ergonomics outweigh unit economics.
1000 Liters commands procurement standardization. 1500 Liters is gaining share fastest among sustainability-driven volume consolidators.
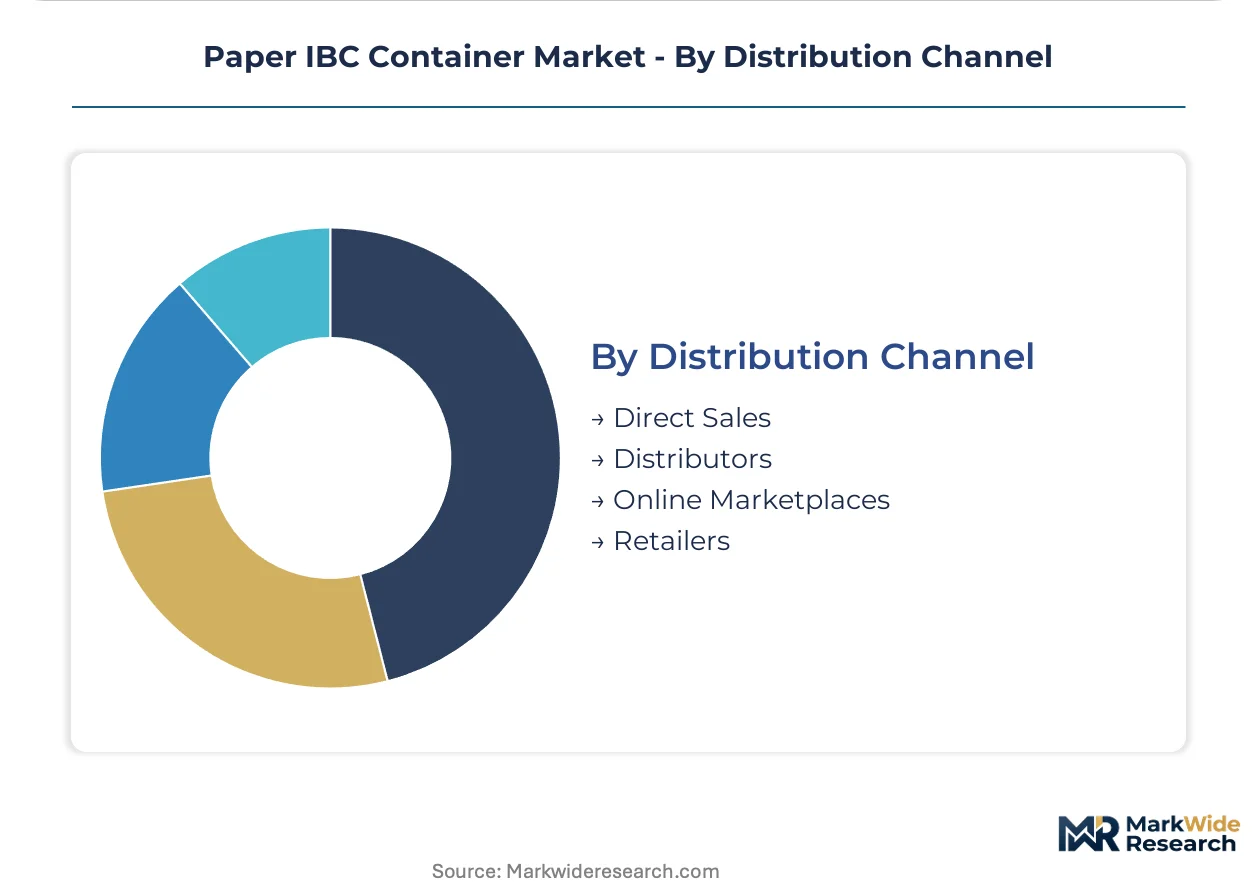
Distribution Channel:
Customer type and geography shape channel selection, with framework agreements displacing spot procurement among organized buyer cooperatives.
- Distributors:Industrial packaging networks sustain market presence through steel-to-paper transition programs and technical specification support. French and Belgian beverage exporter cooperatives are bundling container supply with reverse logistics through these channels.
- Direct Sales:Large chemical processors and food manufacturers negotiate multi-year agreements tied to circularity metrics and dedicated production lines. CSRD supply chain disclosure requirements are accelerating QR-coded IBC traceability integration here.
- Online Marketplaces:Spot procurement for emergency replenishment and small-batch agricultural chemical buyers.
- Retailers:Limited presence confined to consumer-scale container formats and hobbyist agricultural applications.
Distributors hold channel share leadership. Direct Sales is where contract value and margin expansion concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical distributors deploy paper IBCs primarily for bulk solvent transport, whereas Indian food processors adopt them for liquid ingredient handling under plastic-reduction mandates. This consumption-mix differential shapes divergent liner specification requirements across procurement clusters.
Germany
Steel-to-paper transition programs among industrial packaging buyers concentrate demand in the Rhine-Ruhr and Bavarian chemical corridors. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances compel fluorine-free barrier declarations in RFP documentation. Hamburg-based beverage exporters participate in consolidated buying cooperatives bundling container supply with reverse logistics services.
India
FSSAI plastic reduction mandates in Maharashtra and Gujarat food processing corridors create first-mover procurement windows for fiber-based liquid transport. The country's national food safety regulator enforces compliance timelines accelerating fleet retirement decisions. Pune and Ahmedabad edible oil refiners pilot wet-strength kraft configurations matching multi-layer plastic laminate performance.
United States
Industrial packaging networks sustain market presence through technical specification support for chemical sector buyers. FDA food contact regulations shape liner material qualification pathways for domestic food processors. Houston and Gulf Coast petrochemical clusters evaluate paper IBC adoption for non-aromatic hydrocarbon applications.
France
Beverage exporter cooperatives in Champagne and Bordeaux displace spot-market procurement with multi-year framework agreements tied to circularity metrics. EU Green Deal mandatory recycled content thresholds compress supplier qualification timelines. Lyon-based chemical distributors participate in steel-to-paper transition programs targeting Scope 3 reduction targets.
Switzerland
Gamma-sterilizable liner configurations address biologics bulk shipment needs in Basel and Zurich manufacturing clusters. Swissmedic pharmaceutical regulations intersect with EFSA recycled fiber safety assessments shaping certification requirements. Geneva-area biotech processors demand dedicated production lines from converter networks.
Paper IBC Container Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the paper IBC container space. Integrated paperboard producers control captive pulp supply and extrusion coating capacity, while regional converters compete on customization velocity and logistics bundling. Three archetypes dominate: pulp-integrated multinationals, liner-specialist compounders, and logistics-integrated converters. Capacity expansion and backward integration into barrier film production represent the dominant competitive moves reshaping supplier hierarchies.
Within the integrated tier, Mondi exemplifies pulp-captive positioning through Nordic supply chain control. LC Packaging and Greif occupy positions bridging industrial packaging networks with steel-to-paper transition program execution. These three anchors represent distinct geographic and capability vectors—Austrian pulp integration, Dutch logistics bundling, and North American industrial packaging density—without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Mondi |
| LC Packaging |
| Paper Systems |
| Global-Pak |
| Conitex Sonoco |
| International Paper Company |
| Greif |
| Berry Global |
| DS Smith |
| Others |
Value Network & Pricing Analysis
Steel-to-paper fleet substitution among German chemical distributors simultaneously redraws procurement geography toward Nordic pulp supply zones and compresses pricing premiums previously commanded by metal IBC incumbents. This material transition forces liner compounders to absorb reformulation costs while converters capture margin through bundled reverse logistics contracts.
Pricing Analysis
Reverse logistics service bundling drives lifetime value differentiation as beverage exporter cooperatives in France and Belgium shift from spot procurement to multi-year framework agreements. Three-tier pricing structure across premium, standard, and economy levels separates gamma-sterilizable pharmaceutical configurations from generic agricultural chemical formats. Cost compression in standard-grade agricultural segments intensifies because Brazilian pulp supply disruptions transmit unpredictably through converter cost structures. Food processors in Denmark and the Netherlands exhibit lowest price sensitivity due to sustainability-driven procurement mandates, while fertilizer blending operations in India anchor the economy tier.
Supply Chain Analysis
Extended lead times for fluorine-free barrier qualification are compressing effective supplier capacity as compounders race ECHA enforcement deadlines. Pulp supply concentrates in Sweden, Finland, and Brazil, while extrusion coating capacity clusters in Germany and Austria create single-source vulnerability for regional IBC assemblers. Barrier film production rests on polyethylene resin, wet-strength kraft, and biopolymer cellulose feedstocks. Tariff exposure on Nordic pulp imports threatens margin stability for non-integrated converters. Distribution runs through industrial packaging networks bundling technical specification support with steel-to-paper transition program execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paper IBC adoption sits in early-cycle expansion as EU Green Deal recycled content mandates force accelerated fleet retirement decisions across European chemical distributors. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances open procurement windows for certified fiber-based alternatives ahead of 2026 enforcement.
For Market Incumbents: Shield market position through captive pulp supply consolidation and extrusion coating capacity expansion in Germany and Austria. Biopolymer liner fragmentation from fermented cellulose compounders threatens established supplier relationships. Backward integration into barrier film production represents the priority defensive lever against margin compression. For New Entrants and Emerging Players: Differentiate on gamma-sterilizable liner configurations for Swiss and Belgian biologics manufacturing clusters. Indian food processing corridors in Maharashtra and Gujarat offer the most penetrable geography under FSSAI plastic reduction mandates. Direct sales relationships with consolidated buying cooperatives provide the strongest go-to-market angle for volume anchoring. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional converters possessing logistics bundling capabilities but lacking pulp integration. Five-to-ten year viability hinges on circular design credential monetization through customer procurement frameworks. Watch EFSA recycled fiber safety assessment timelines as the inflection signal for food-contact certification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Film Production | Captive extrusion coating capacity insulates German converters from single-source vulnerability in Austria. |
| Fluorine-Free Liner Qualification Program | Silicone and clay-based barrier formulations secure REACH Annex XVII compliance ahead of ECHA deadlines. |
| Consolidated Buying Cooperative Partnership | Multi-year framework agreements with French beverage exporters bundle container supply with fiber recovery services. |
| Gamma-Sterilizable Configuration Development | Swissmedic-compliant liners address biologics bulk shipment needs in Basel manufacturing clusters. |
| Digital Print Traceability Integration | QR-coded IBCs enable batch disclosure for EU CSRD supply chain reporting requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chemical procurement managers, food processing plant engineers, liner compounder R&D directors, and industrial packaging distribution heads. Secondary validation drew from ECHA regulatory filings, EU Green Deal implementation documents, FSSAI mandate notifications, customs trade data for pulp and container movements, and SEC disclosures from integrated paperboard producers. Bottom-up volume estimates from corrugator capacity and top-down demand triangulation from end-use procurement patterns were cross-referenced for convergence.
Across the analysis window, the forecast framework models product type segmentation by structural format, end-use industry by regulatory exposure tier, capacity scale by corrugator press requirements, and distribution channel by contract structure. CAGRs were derived from trend extrapolation of fleet substitution rates and qualification timeline compression. Industry-specific inputs include REACH migration limit enforcement schedules and wet-strength kraft innovation adoption curves from Nordic pulp mills.
Material uncertainties — pulp cost volatility from Brazilian supply disruptions, EFSA recycled fiber safety assessment delays, and extrusion coating capacity concentration risks — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement timing and substitution elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Kraft Paper Mailer Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market