
 Egypt Plastic Packaging Films Market | 2026-2036
Egypt Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Plastic Packaging Films Market Insights
Domestic distributor networks for plastic packaging films is fragmenting as regional converters bypass traditional Cairo-based wholesalers to secure direct supply contracts with Delta manufacturers. Misr Elhegaz Group leverages its integrated resin-to-film operations to control pricing across Upper Egypt governorates. UFlex Limited competes through specialized multilayer co-extrusion capabilities serving pharmaceutical blister packs. Pack House Egypt anchors its position in agricultural stretch films for export-oriented produce handlers in Kafr El-Sheikh and Damietta.
Egypt plastic packaging films comprise flexible polymer substrates manufactured through blown or cast extrusion processes, typically ranging from 12 to 150 microns in thickness, engineered to provide moisture barrier, optical clarity, and seal integrity for perishable and durable goods. The primary commercial purpose centers on extending shelf life while enabling high-speed form-fill-seal automation across food processing and pharmaceutical operations. Stretch films lead volume throughput due to palletization demand from Alexandria Port logistics operators, while barrier films command premium positioning as local dairy and processed meat processors upgrade to ethylene vinyl alcohol structures. Polyethylene dominates material consumption given its cost position and compatibility with existing extrusion infrastructure along the 10th of Ramadan industrial corridor.
Egypt's Ministry of Environment enforces extended producer responsibility frameworks that mandate recycled content thresholds in single-use packaging, while the Egyptian Organization for Standardization and Quality (EOS) administers compliance testing for food-contact migration limits under harmonized Gulf standards. These regulations compel domestic extruders to reformulate virgin-heavy recipes and certify mono-material streams for mechanical recycling compatibility. Stakeholders must monitor enforcement intensity in free zone versus domestic market channels and calibrate capital allocation between compliance-ready co-extrusion upgrades and conventional asset bases.
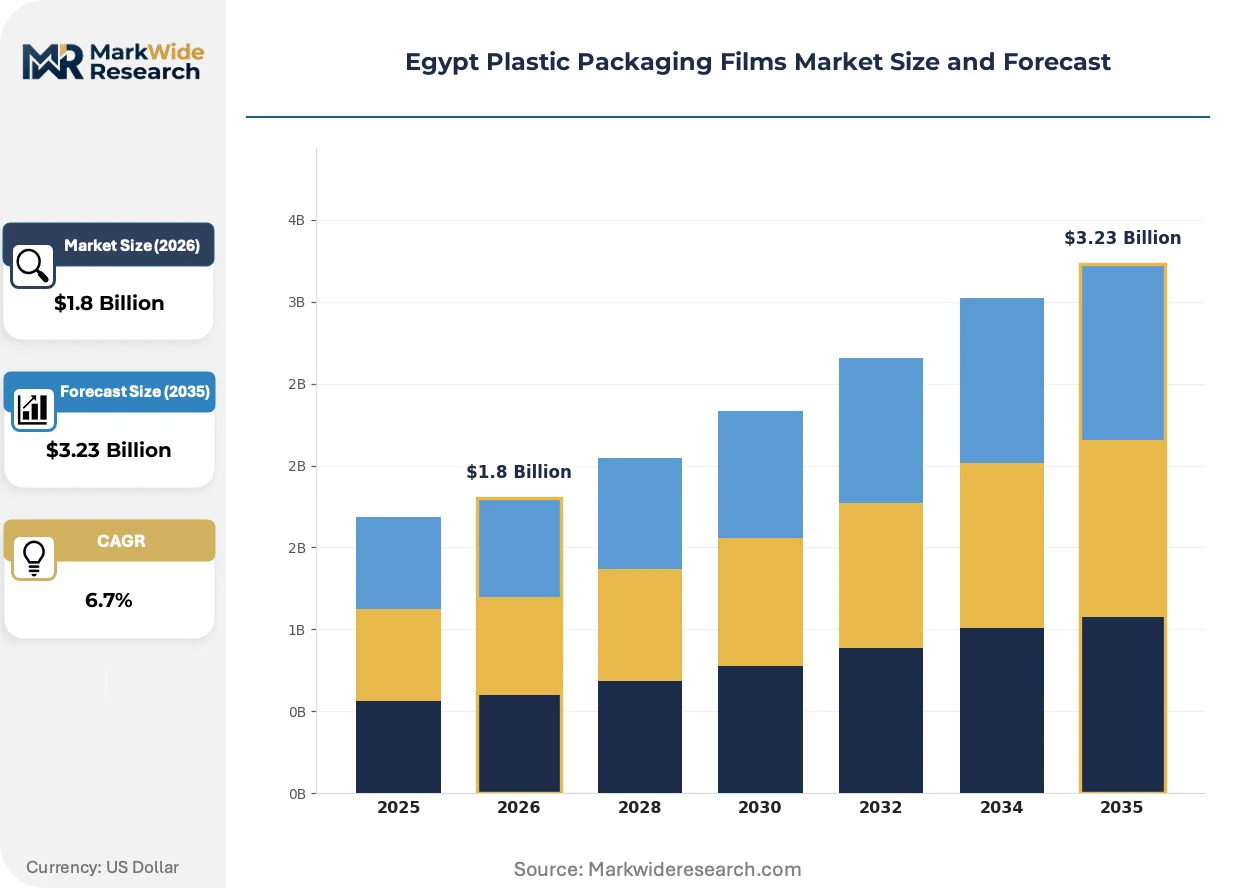
Market Dynamics
Egypt's Ministry of Environment has tightened extended producer responsibility rules, forcing converters to abandon multi-material laminates and adopt mono-material recyclable structures. This regulatory pivot is compressing margins for legacy extruders while rewarding early movers with certified recycling streams.
Growth Catalysts
- Extended Producer Responsibility Mandates:Egypt's Ministry of Environment enforces recycled content thresholds in single-use packaging, compelling dairy and processed meat processors to upgrade to ethylene vinyl alcohol barrier structures.
- Suez Canal Logistics Expansion:Alexandria Port operators are scaling palletization throughput, driving stretch film demand from export-oriented produce handlers in Kafr El-Sheikh and Damietta.
- High-Clarity Film Adoption:Packaged food producers in Greater Cairo and Alexandria are expanding orders for barrier films that enable high-speed form-fill-seal automation.
Market Restraints
- Resin Price Volatility:Polyethylene feedstock costs fluctuate with naphtha-linked import pricing, squeezing margin predictability for extruders along the 10th of Ramadan industrial corridor.
- Mechanical Recycling Limitations:Local collection infrastructure for post-consumer film waste remains underdeveloped, constraining the volume of certified recycled content available for compliance.
- Import Dependency for EVOH:Ethylene vinyl alcohol barrier layers rely on foreign suppliers, creating supply concentration risk for converters serving pharmaceutical blister pack specifications.
Strategic Opportunities
- Upper Egypt Distribution Gap:Misr Elhegaz Group's integrated resin-to-film operations demonstrate pricing control potential in governorates underserved by Delta-based manufacturers.
- Agricultural Export Packaging:European Union destination markets for Egyptian produce are tightening packaging sustainability requirements, creating demand for certified recyclable stretch films.
- Mono-Material Co-Extrusion Convergence:Combining blown extrusion with digital thickness gauging enables food-contact compliance while maintaining optical clarity standards.
Industry Challenges
- Co-Extrusion Technical Talent Scarcity:The shift to seven-layer and nine-layer barrier structures requires process engineers with specialized rheology expertise that domestic technical institutes rarely produce.
- Migration Testing Certification Delays:Egyptian Organization for Standardization and Quality food-contact compliance timelines stretch 12-18 months, slowing new product introductions for converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Plastic Packaging Films Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Shrink Films, Rigid Films, Barrier Films Material: Polyethylene, Polypropylene, PVC, PET End User: Food & Beverages, Pharmaceuticals, Consumer Goods, Electronics Technology: Blown Film Extrusion, Cast Film Extrusion, Co-extrusion, Lamination |
| Companies Covered | International Pack For Packaging Industry (IPPI), Pack House Egypt, Misr Elhegaz Group, UFlex Limited, Amcor Group GmbH, Hyma Plastic, Taghleef Industries Group, Huhtamaki Egypt Flexible Packaging, COPACK Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Plastic Packaging Films Market Trends and Innovations
Film formulation and manufacturing processes are undergoing rapid transformation as regulatory deadlines compress adoption timelines. Three convergent developments are reconfiguring competitive advantage among Nile Delta extruders.
Multilayer co-extrusion technology is migrating from conventional five-layer configurations to sophisticated nine-layer systems capable of embedding barrier properties within mono-material polyethylene streams. Pharmaceutical blister pack manufacturers in Alexandria are adopting these structures fastest, driven by European export compliance requirements. This migration is compressing demand for legacy adhesive-laminated films that fail mechanical recycling compatibility tests.
Egypt's Ministry of Environment enforces extended producer responsibility frameworks that mandate recycled content thresholds in single-use packaging. The Egyptian Organization for Standardization and Quality administers compliance testing for food-contact migration limits under harmonized Gulf standards. Domestic extruders are responding by reformulating virgin-heavy recipes and certifying mono-material streams for mechanical recycling compatibility.
Regional converters are bypassing traditional Cairo-based wholesalers to secure direct supply contracts with Delta manufacturers. This disintermediation concentrates procurement power among large FMCG clusters operating near Suez Canal logistics hubs. The pattern is most visible in agricultural stretch film purchasing, where export-oriented produce handlers in Kafr El-Sheikh negotiate volume-based pricing directly with extrusion plants.
Egypt Plastic Packaging Films Market Segmentation

Egypt's plastic packaging films market exhibits distinct performance profiles across product, material, and end-use dimensions. Segment-level dynamics reveal where technical capability investments concentrate and which application clusters drive margin expansion for Nile Delta extruders.
Product Type:
Mature palletization films dominate volume throughput while emerging barrier structures capture premium positioning.
- Stretch Films:Linear low-density polyethylene formulations engineered for puncture resistance and load containment. Alexandria Port logistics operators and Kafr El-Sheikh produce exporters drive concentrated demand as palletization throughput scales. Egyptian Ministry of Environment EPR mandates are accelerating shifts toward mono-material recyclable grades.
- Barrier Films:Multilayer structures incorporating ethylene vinyl alcohol or metallized layers for oxygen and moisture exclusion. Dairy and processed meat processors in Greater Cairo and Alexandria are expanding orders for high-clarity variants that enable high-speed form-fill-seal automation.
- Shrink Films:Biaxially oriented polyethylene terephthalate or polyolefin formulations for retail display bundling.
- Rigid Films:Calendered or extruded sheets for thermoformed trays and blister packs serving pharmaceutical specifications.
Stretch films retain volume leadership; barrier films hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity resins from specialty barrier polymers with divergent margin profiles.
- Polyethylene:Dominates consumption across blown and cast extrusion infrastructure along the 10th of Ramadan industrial corridor. Compatibility with existing equipment and mechanical recycling streams reinforces its position despite naphtha-linked import price volatility squeezing converter margins.
- Polypropylene:Cast film grades command premium positioning in clarified food-contact applications. Biaxially oriented variants serve cigarette overwrap and snack packaging for FMCG clusters operating near Suez Canal logistics hubs.
- PVC:Rigid calendered sheets for pharmaceutical blister packs and consumer goods thermoforming.
- PET:Biaxially oriented films for high-barrier lidding and metallized snack packaging structures.
Polyethylene anchors volume throughput; polypropylene captures the widest margin spread.
End User:
Application intensity varies sharply between perishable goods requiring barrier performance and durable goods prioritizing cost efficiency.
- Food & Beverages:Largest demand cluster spanning dairy, processed meat, bakery, and fresh produce packaging. Extended producer responsibility rules from Egypt's Ministry of Environment are compelling processors to upgrade from multi-material laminates to mono-material recyclable structures.
- Pharmaceuticals:Blister pack and sachet specifications demand ethylene vinyl alcohol barrier layers and migration-tested food-contact compliance. European export requirements are accelerating adoption of nine-layer co-extrusion systems among Alexandria manufacturers.
- Consumer Goods:Personal care and household product wrapping with moderate barrier requirements.
- Electronics:Anti-static films for component protection and retail display packaging.
Food & Beverages commands absolute volume; Pharmaceuticals delivers the highest specification premiums.
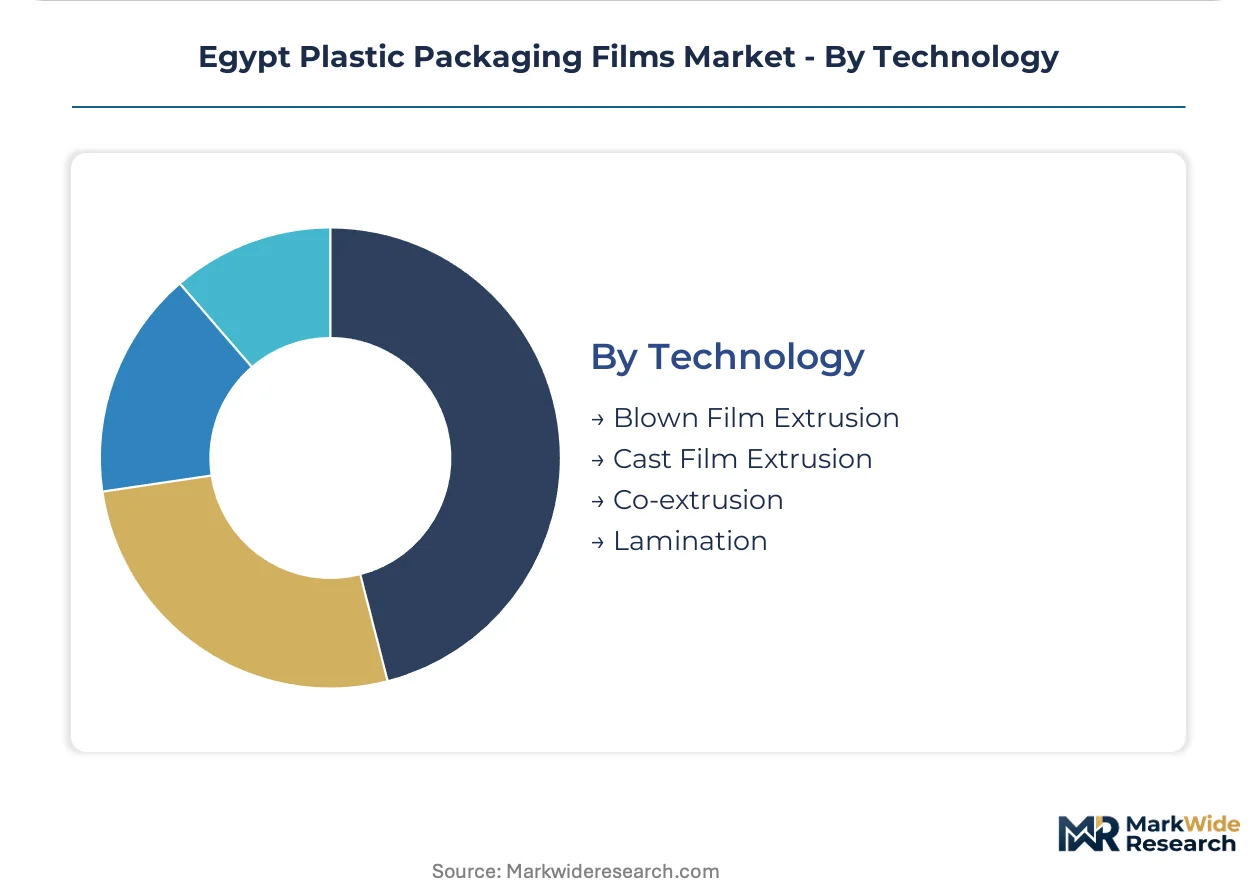
Technology:
Process sophistication determines compliance readiness as regulatory deadlines compress adoption timelines.
- Blown Film Extrusion:Dominant process for stretch films and agricultural mulching applications. Tubular bubble quenching produces balanced orientation properties suited to palletization demand from export-oriented produce handlers.
- Co-extrusion:Five-layer to nine-layer systems enabling barrier properties within mono-material polyethylene streams. Pharmaceutical blister pack manufacturers are adopting these structures fastest to meet mechanical recycling compatibility tests.
- Cast Film Extrusion:Chill-roll quenching for high-clarity food-contact films with superior optical properties.
- Lamination:Adhesive and extrusion lamination for multi-material structures now facing displacement from EPR-mandated recyclable alternatives.
Blown film extrusion retains installed base dominance; co-extrusion is climbing the fastest as compliance requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's Ministry of Environment anchors regulatory frameworks across the Nile Delta industrial corridor, where FMCG manufacturing clusters and Suez Canal logistics hubs concentrate film demand. Sub-regional dynamics vary sharply between Greater Cairo's barrier film specifications and Alexandria Port's palletization throughput.
Greater Cairo
Dairy and processed meat processors in 10th of Ramadan City drive high-clarity barrier film orders for form-fill-seal automation. The Ministry of Environment enforces recycled content thresholds through extended producer responsibility mandates. Industrial extruders along the corridor are reformulating virgin-heavy recipes to certify mono-material polyethylene streams.
Alexandria
Pharmaceutical blister pack manufacturers demand nine-layer co-extrusion systems for European export compliance. The Egyptian Organization for Standardization and Quality administers migration testing certification timelines stretching 12-18 months. Alexandria Port logistics operators scale stretch film palletization throughput for export-oriented produce handlers.
Kafr El-Sheikh and Damietta
Agricultural stretch film procurement concentrates among export-oriented produce handlers negotiating direct supply contracts with Delta extruders. European Union destination markets tighten packaging sustainability requirements for certified recyclable grades. Pack House Egypt anchors regional supply for produce handlers bypassing traditional Cairo-based wholesalers.
Upper Egypt Governorates
Distribution networks fragment as regional converters seek direct supply relationships outside Delta manufacturing clusters. Misr Elhegaz Group leverages integrated resin-to-film operations to control pricing across underserved governorates. Local demand for polyethylene-based packaging remains tethered to agricultural commodity processing and consumer goods distribution.
Egypt Plastic Packaging Films Market Competitive Landscape
Integrated resin-to-film operators and specialized multilayer co-extrusion houses split the market into distinct capability tiers. Domestic converters dominate stretch film volumes through proximity to Alexandria Port logistics, while barrier film premiums accrue to players with certified recycling streams and pharmaceutical-grade migration testing. Three archetypes define competitive positioning: backward-integrated petrochemical players, co-extrusion technology specialists, and agricultural film pure-plays. Capacity expansion in mono-material recyclable structures and direct supply contract negotiations with FMCG clusters represent the dominant competitive moves compressing traditional distributor margins.
Among Egypt-based integrated operators, Misr Elhegaz Group exemplifies backward-integrated pricing control across Upper Egypt governorates. Pack House Egypt occupies a position within the agricultural stretch film tier, anchoring supply relationships with export-oriented produce handlers. UFlex Limited represents the specialized co-extrusion archetype, with multilayer capability positioning for pharmaceutical blister pack specifications requiring European compliance alignment.
| Leading Market Players |
|---|
| International Pack For Packaging Industry (IPPI) |
| Pack House Egypt |
| Misr Elhegaz Group |
| UFlex Limited |
| Amcor Group GmbH |
| Hyma Plastic |
| Taghleef Industries Group |
| Huhtamaki Egypt Flexible Packaging |
| COPACK Co |
| Others |
Pricing and Supply Chain Analysis
Naphtha-linked import price volatility for polyethylene feedstock compresses margin predictability across Egyptian extrusion corridors while simultaneously widening spreads between virgin-heavy commodity grades and certified mono-material recyclable structures. This input-cost instability forces converters to absorb fluctuations in standard film tiers while capturing premiums in EVOH-barrier and pharmaceutical-grade specifications that pass through resin escalation clauses.
Pricing Analysis
The customization-premium spread separates configured-to-order multilayer co-extrusion from standard blown film grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification status under Egyptian Organization for Standardization and Quality migration testing and Ministry of Environment extended producer responsibility compliance. Pricing pressure stems from naphtha-linked polyethylene import costs squeezing converter margins along the 10th of Ramadan industrial corridor. Export-oriented produce handlers in Kafr El-Sheikh and Damietta exhibit highest price sensitivity due to direct volume negotiations, while pharmaceutical blister pack manufacturers in Alexandria accept premium positioning for European compliance alignment.
Supply Chain Analysis
Export-control regimes on ethylene vinyl alcohol barrier layer technology limit supply diversification for pharmaceutical-grade specifications. Geographic supply concentration centers on Saudi Arabia and UAE for polyethylene resin, with specialty EVOH and metallized substrates drawing from South Korea and Germany. Raw material dependencies rest on naphtha derivatives, imported barrier polymers, and certified recycled flake for compliance-grade formulations. Single-source vulnerability concentrates in EVOH supply for nine-layer co-extrusion systems serving European export requirements. Distribution runs through direct supply contracts between Delta extruders and FMCG clusters near Suez Canal logistics hubs, bypassing traditional Cairo-based wholesale networks.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's plastic packaging films market sits at a regulatory inflection where extended producer responsibility mandates are compressing legacy multi-material laminate demand while accelerating mono-material recyclable structure adoption. This technological pivot rewards early compliance investment and punishes stranded conventional extrusion capacity.
For Market Incumbents: Pre-empt margin erosion by accelerating co-extrusion capability upgrades to seven-layer and nine-layer systems before Egyptian Organization for Standardization and Quality certification queues lengthen. Secure backward integration into resin compounding or captive recycling streams to control input cost volatility from naphtha-linked import pricing. Defend position against regional converters disintermediating Cairo wholesalers by locking direct supply contracts with FMCG clusters near Suez Canal logistics hubs.
For New Entrants and Emerging Players: Upper Egypt governorates present distribution whitespace where Misr Elhegaz Group's integrated operations have established pricing benchmarks but specialized barrier film capability remains scarce. Target agricultural stretch film segments in Kafr El-Sheikh and Damietta where European Union sustainability requirements are tightening demand for certified recyclable grades. Enter through co-extrusion technology partnerships that shortcut the 12-18 month Egyptian Organization for Standardization and Quality food-contact migration testing timelines.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors co-extrusion technology specialists with certified recycling streams over commodity blown film operators facing stranded asset risk. Long-term viability over a multi-year window hinges on regulatory compliance readiness rather than scale economics alone. Monitor enforcement intensity divergence between free zone and domestic market channels as the inflection signal for capital allocation toward compliance-ready assets versus conventional extrusion bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Co-Extrusion Capacity Expansion | Enables Egyptian converters to meet Ministry of Environment extended producer responsibility recycled content thresholds. |
| Backward Integration into Resin Compounding | Insulates margin predictability from naphtha-linked polyethylene import price volatility. |
| Direct Supply Contract Negotiation | Concentrates procurement power with FMCG clusters near Suez Canal logistics hubs bypassing wholesalers. |
| Pharmaceutical-Grade Migration Testing Certification | Unlocks premium positioning for Alexandria blister pack manufacturers serving European export markets. |
| Agricultural Stretch Film Sustainability Repositioning | Aligns Kafr El-Sheikh and Damietta produce handlers with tightening European Union packaging requirements. |
Research Methodology
A spread of perspectives from extrusion plant managers, procurement leads at dairy and processed meat processors, distribution channel partners in Upper Egypt governorates, and technical R&D directors at co-extrusion specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from Egyptian Organization for Standardization and Quality compliance filings, Ministry of Environment regulatory circulars, Suez Canal Authority throughput statistics, and customs records for polyethylene resin imports. Bottom-up capacity assessments at Nile Delta extrusion facilities were triangulated against top-down demand estimates from FMCG manufacturing clusters.
Demand-supply balance dynamics across the analysis window were modeled through segmentation across product type, material grade, end-use application, and technology process. The forecast framework incorporated stretch film palletization throughput scaling at Alexandria Port, barrier film adoption curves among pharmaceutical blister pack manufacturers, and co-extrusion technology migration timelines. CAGRs were derived from regression analysis of historical capacity utilization and forward projection of regulatory compliance deadlines. Industry-specific inputs included Egyptian Ministry of Environment enforcement intensity scenarios and European Union packaging sustainability requirement trajectories for Egyptian produce exports.
The forecast holds incumbent behavior within observed patterns; aggressive moves by backward-integrated petrochemical players or Gulf-based multinationals entering through acquisition would shift outcomes beyond modeled ranges. Material shifts in Ministry of Environment extended producer responsibility enforcement intensity, naphtha price volatility spikes, or European Union packaging regulation acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Poly Coated Paper Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
Embossed Film Market
Poly film
Twist Wrap Film Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Soft Touch Film Market
Poly film
PET Lidding Films Market
Poly film
Isotropic Film Market
Poly film
PCR Bubble Films Market
Poly film
Polystyrene Films Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Packaging Film Market
Poly film
Japan Polypropylene Packaging Films Market
Poly film
MOPP Packaging Films Market
Poly film
Australia and New Zealand Plastic Packaging Film Market