
 Kitchen Roll Market | 2026-2036
Kitchen Roll Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Roll Market Analytics
Asset-light contract manufacturing and third-party tolling arrangements is rewriting competitive entry dynamics in kitchen roll production. Procter & Gamble Co. leverages its North American pulp supply agreements to sustain margin structures against private-label encroachment. Kimberly-Clark Corporation anchors its position through integrated tissue mills that control fiber sourcing from timberland to finished roll. Essity AB differentiates via concentrated R&D spending on air-laid technology for premium absorbency tiers.
Kitchen roll denotes a perforated, absorbent paper towel product manufactured from virgin or recycled wood pulp through creping or through-air-drying processes, designed for surface cleaning, grease absorption, and hand drying in domestic and professional settings. Creping imparts bulk and softness by scraping dried paper from Yankee dryer cylinders with a doctor blade, yielding the loft critical to liquid retention. The material segment shows recycled paper and bamboo grades gaining shelf space as retailers respond to Ecolabel and FSC certification requirements, while the end-use dimension tilts toward food service and hospitality as away-from-home consumption recovers post-pandemic. The size category sees mega rolls and bulk packs commanding disproportionate volume in club and e-commerce channels where shipping economics favor lower replenishment frequency.
The EU Ecolabel and the US EPA's Comprehensive Procurement Guidelines shape fiber sourcing and recycled-content thresholds for products sold in their respective jurisdictions. FSC chain-of-custody certification functions as a de facto market-access requirement for premium positioning in German and UK retail. Stakeholders must monitor pulp futures volatility and evolving extended-producer-responsibility frameworks to calibrate sourcing strategies and product mix decisions.
Market Dynamics
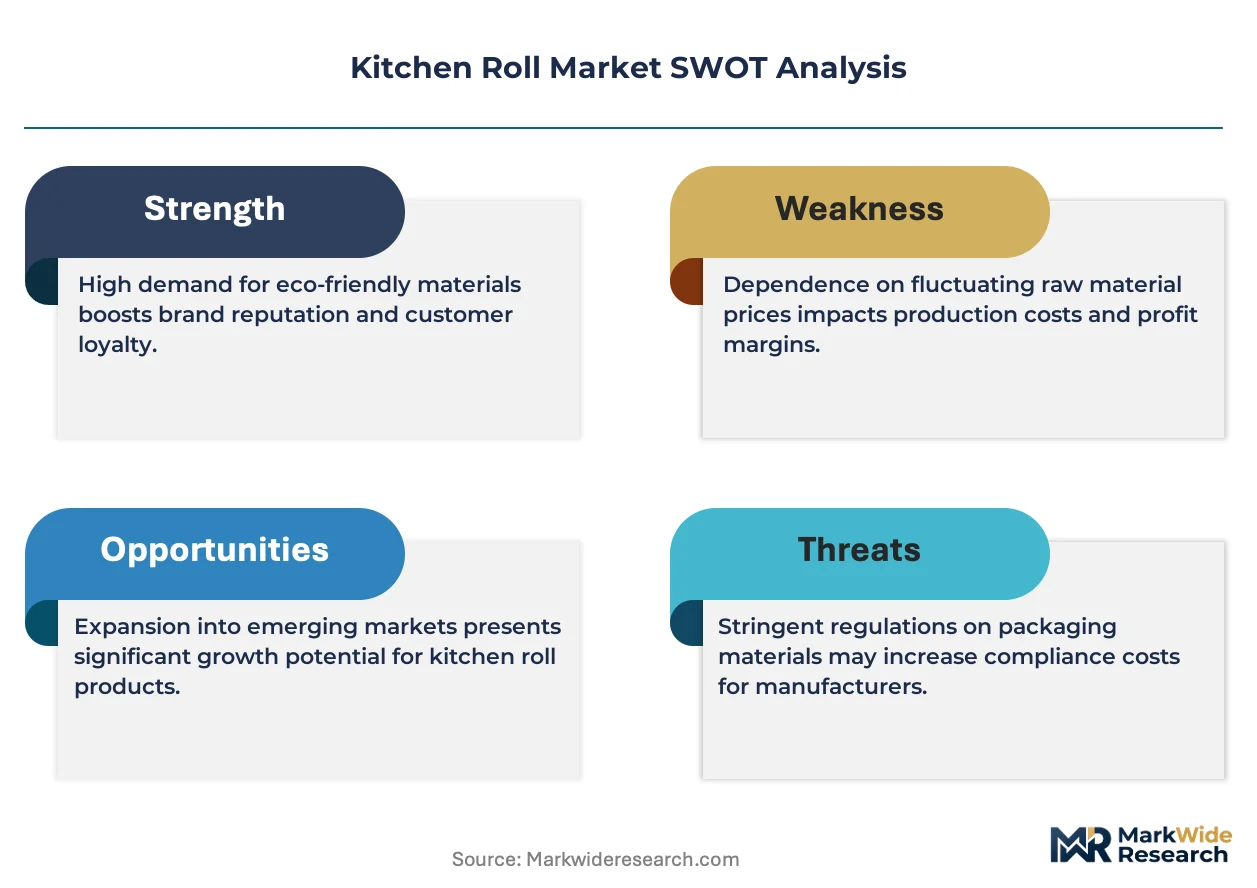
Fiber sourcing economics and extended-producer-responsibility mandates are compressing legacy virgin-pulp supply chains while accelerating certified recycled-content and alternative-fiber qualification programs across manufacturing footprints.
Growth Catalysts
- EU Single-Use Plastics Directive:This framework accelerates material transitions away from plastic-coated grades toward fiber-based alternatives in food service applications.
- Quick-service restaurant hygiene protocols:Labor cost pressures and tightening sanitation standards expand procurement of disposable absorbent products for back-of-house operations.
- Air-laid technology maturation:Advanced through-air-drying processes enable premium absorbency tiers that command shelf space in club and e-commerce channels.
Market Restraints
- Pulp futures volatility:Northern softwood and eucalyptus pulp price swings compress margin structures for non-integrated manufacturers lacking captive timberland supply.
- German retail concentration:Private-label penetration and sustainability labeling requirements create asymmetric negotiating leverage for Aldi, Lidl, and Rewe purchasing consortiums.
- Biodegradable substrate performance gaps:Bamboo and agricultural-residue fibers exhibit lower wet-strength retention versus virgin kraft, limiting substitution rates in professional cleaning segments.
Strategic Opportunities
- Certified circular-economy product lines:EU Ecolabel and FSC chain-of-custody certification unlock premium positioning in German and UK retail channels.
- Mega-roll bulk formats:Lower replenishment-frequency packs align with shipping economics in Amazon and Costco fulfillment networks.
- Tolling arrangement expansion:Asset-light contract manufacturing lowers capital barriers for regional entrants seeking access to integrated tissue mill technology.
Industry Challenges
- FSC certification timeline compression:Chain-of-custody audits and recycled-content verification create six-to-twelve-month product launch delays for new market entrants.
- Legacy creping equipment retrofit costs:Converting Yankee dryer configurations for through-air-drying compatibility demands capital outlays that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Roll Market |
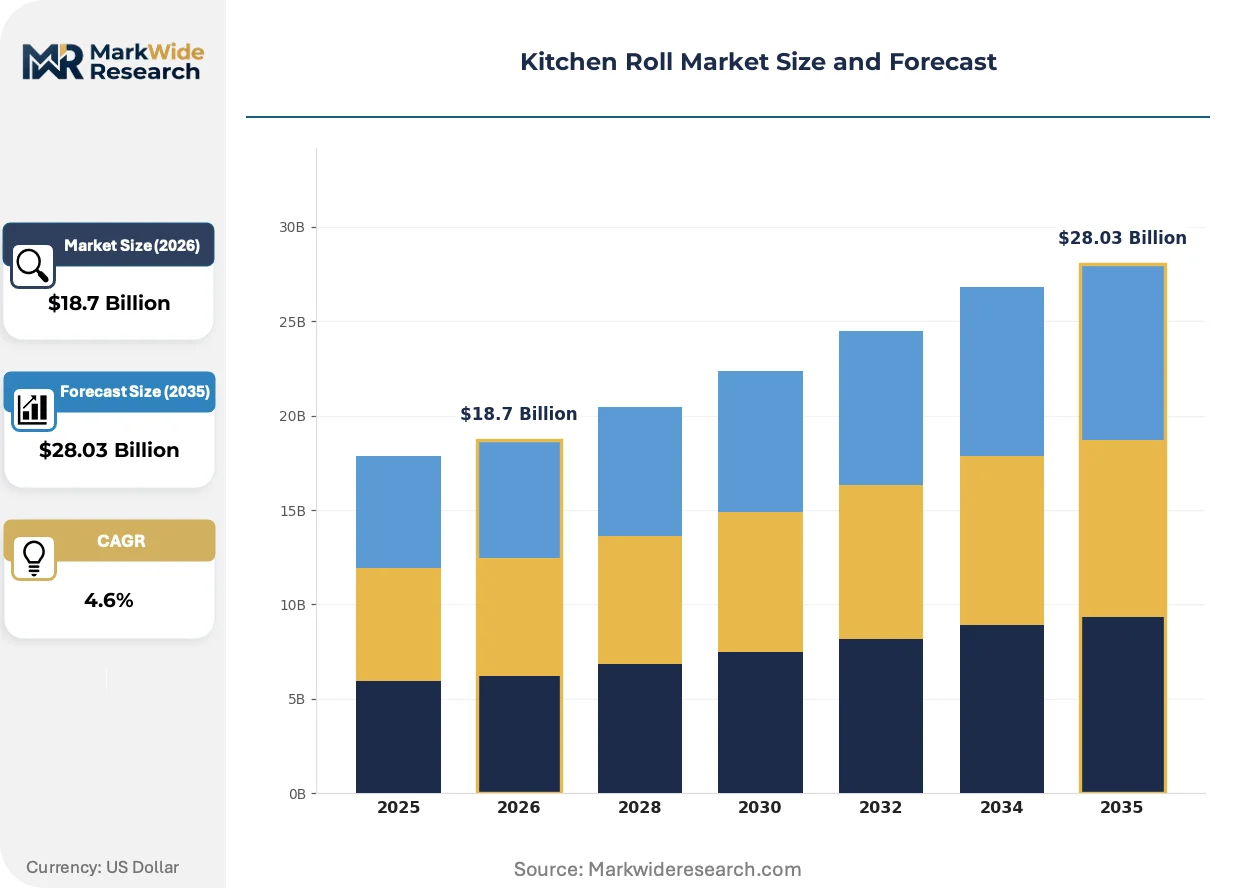
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Premium, Eco-Friendly, Patterned End Use: Household, Commercial, Hospitality, Food Service Material: Pulp, Recycled Paper, Bamboo, Cloth Size: Single Roll, Double Roll, Mega Roll, Bulk Pack |
| Companies Covered | Procter & Gamble Co., Kimberly-Clark Corporation, Essity AB, Georgia-Pacific, Sofidel Group SPA, WEPA Professional GmbH, Oji Holdings Corporation, Hengan International Group Company Limited, Metsä Tissue Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Roll Market Evolving Landscape
Material science convergence and regulatory material-bans are collapsing traditional grade boundaries while reshaping procurement criteria across food service, hospitality, and retail channels.
Through-air-drying (TAD) technology is hybridizing conventional creping methods to produce structured sheets with engineered void volume for superior liquid retention. Quick-service chains and institutional food service operators are adopting TAD-reinforced grades for grease-handling tasks previously requiring cloth or multiple-ply alternatives. This hybridization is compressing the performance gap between premium and standard tiers, forcing price realignment across private-label and branded portfolios.
REACH chemical registration requirements and EU Ecolabel fiber-sourcing criteria are tightening allowable coatings and brightening agents in products sold across European Economic Area member states. Manufacturers must reformulate wet-strength resins and de-inked pulp streams to maintain market access. German retail chains are responding by mandating FSC-certified supply chains as a listing prerequisite, effectively filtering non-compliant suppliers from shelf sets.
Food service procurement teams are consolidating spend through group purchasing organizations that negotiate multi-year supply agreements with sustainability-linked volume commitments. Distributor disintermediation is accelerating as large QSR chains establish direct relationships with integrated tissue mills to secure certified fiber provenance and price stability. This consolidation is most visible in the United States, where Aramark, Compass Group, and Sodexo purchasing cooperatives are qualifying single-source suppliers for national rollouts.
Kitchen Roll Market Segmentation
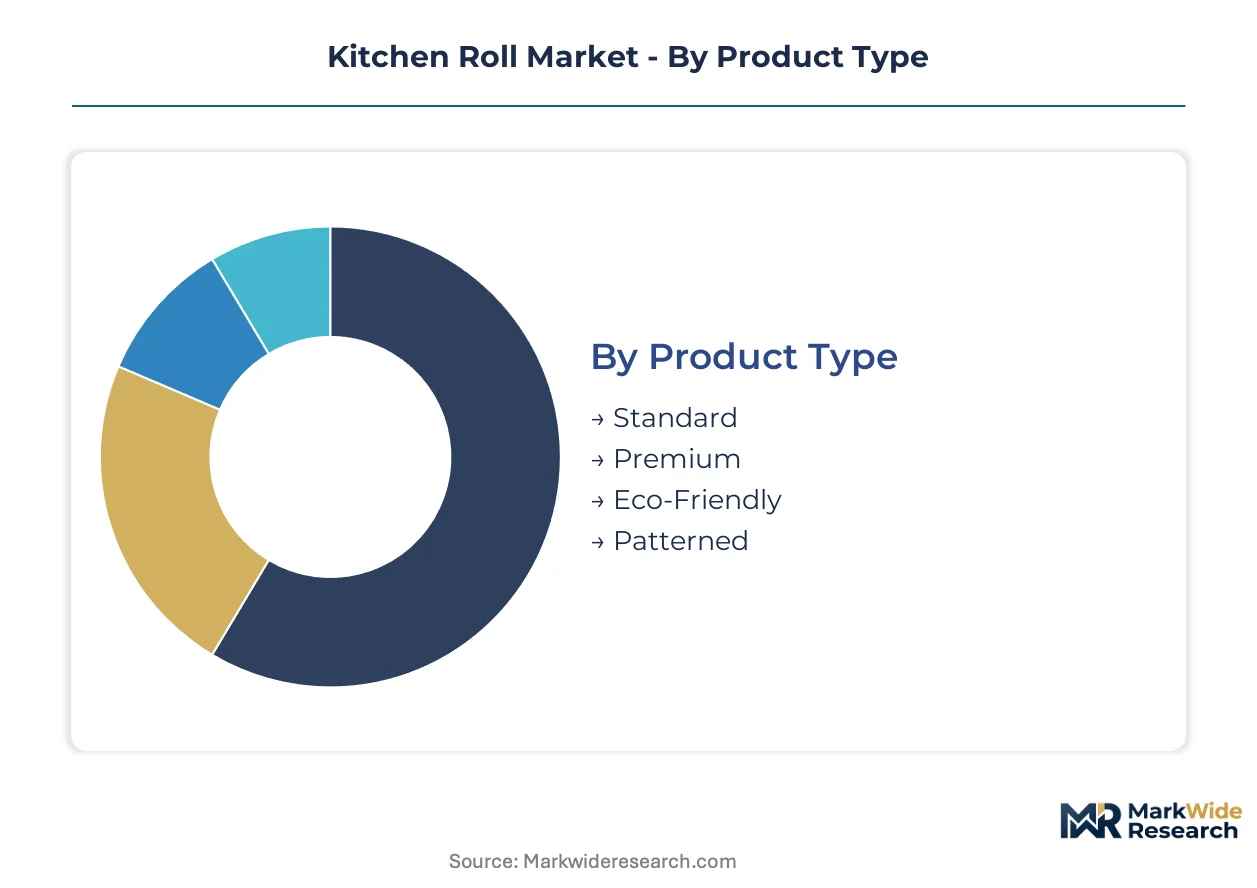
Kitchen roll manufacturers calibrate product portfolios across four intersecting dimensions where absorbency specifications, sustainability credentials, and format economics determine channel access. Segmentation discipline separates integrated mills serving national QSR contracts from regional converters targeting club-store shelf sets.
Product Type:
After-sales service intensity varies sharply across product tiers, with premium and eco-friendly grades demanding technical support for dispenser compatibility and sustainability certification documentation that standard grades rarely require.
- Premium:Manufactured through through-air-drying or hybrid TAD-creping processes that engineer void volume for superior liquid retention. German and UK retail chains concentrate procurement here as FSC-certified supply chains become listing prerequisites. EU Ecolabel compliance adds documentation overhead that raises supplier switching costs.
- Eco-Friendly:Composed of bamboo fibers, agricultural residues, or de-inked pulp streams with wet-strength resin reformulations. Food service operators in Aldi and Lidl supply bases drive fastest adoption despite performance gaps in grease-handling tasks versus virgin kraft grades.
- Standard:Conventional creped virgin pulp meeting baseline absorbency metrics for price-sensitive household replenishment cycles.
- Patterned:Embossed or printed surface treatments targeting gift and specialty retail channels with aesthetic differentiation over functional performance.
By volume, Standard leads. By growth pace, Eco-Friendly is climbing the fastest.
End Use:
Cost tier stratification separates capital-intensive integrated mills from asset-light tolling arrangements as contract values and certification requirements diverge across customer types.
- Food Service:Quick-service restaurant back-of-house operations specify disposable absorbent products for grease handling and surface sanitation. Aramark, Compass Group, and Sodexo purchasing cooperatives negotiate multi-year supply agreements with sustainability-linked volume commitments, consolidating spend through group purchasing organizations.
- Hospitality:Hotels and institutional facilities balance guest-facing quality impressions with operational cost controls, driving demand for mid-tier embossed grades with reliable dispenser fit.
- Commercial:Office buildings and industrial facilities prioritize cost-per-use economics and janitorial supply chain simplicity over performance specifications.
- Household:Replenishment-driven consumption through supermarket and e-commerce channels where private-label penetration concentrates negotiating leverage.
Food Service commands the highest per-unit margins. Hospitality shows the steepest expansion trajectory as away-from-home consumption normalizes.
Material:
Supply concentration in Northern softwood and eucalyptus pulp regions shapes sourcing strategies as manufacturers qualify alternative fibers to hedge futures volatility.
- Pulp:Virgin northern softwood and eucalyptus grades deliver superior wet-strength retention for professional cleaning segments. Procter & Gamble leverages North American pulp supply agreements to sustain margin structures against private-label encroachment.
- Recycled Paper:De-inked pulp streams require wet-strength resin reformulation to meet EU Ecolabel and US EPA Comprehensive Procurement Guidelines thresholds.
- Bamboo:Rapid-renewal grass fibers gaining shelf space as retailers respond to Ecolabel certification requirements, though lower wet-strength limits substitution rates in food service applications.
- Cloth:Reusable textile alternatives competing on total-cost-of-ownership calculations in institutional settings with laundering infrastructure.
Pulp retains volume dominance. Bamboo is gaining share fastest among sustainability-mandated procurement categories.
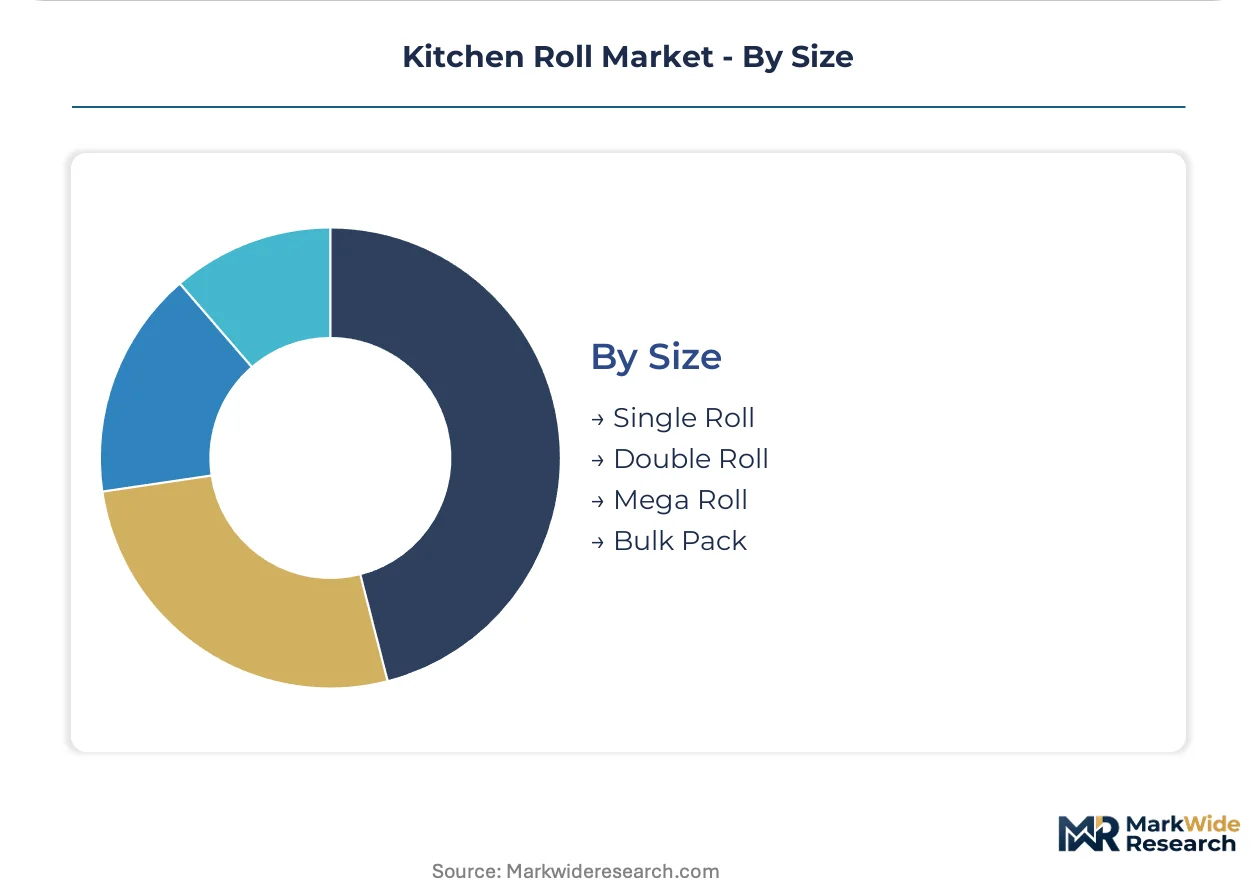
Size:
Shipping economics and replenishment frequency preferences reshape format mix as e-commerce and club channels capture channel growth.
- Mega Roll:Extended-sheet formats engineered for lower replenishment frequency align with Amazon and Costco fulfillment network economics where package dimensional weight determines profitability.
- Bulk Pack:Multi-roll configurations targeting commercial and hospitality accounts with centralized storage capacity and predictable consumption patterns.
- Double Roll:Mid-format option balancing shelf presence with household storage constraints in mainstream retail.
- Single Roll:Entry-price-point format for convenience retail and trial-size marketing programs.
Mega Roll leads by volume in club and e-commerce. Bulk Pack shows the fastest growth pace in food service contract procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Ecolabel fiber-sourcing criteria and extended-producer-responsibility mandates are reshaping procurement patterns across the major consuming economies. National retail consolidation and food service hygiene protocols create divergent competitive entry conditions.
United States
Quick-service restaurant chains expand back-of-house absorbent product procurement as labor costs rise and sanitation standards tighten. The EPA's Comprehensive Procurement Guidelines set recycled-content thresholds for federal and institutional purchasing. Integrated tissue mills in Wisconsin and Georgia control fiber sourcing from timberland through finished roll production.
Germany
Private-label penetration at Aldi, Lidl, and Rewe purchasing consortiums creates asymmetric negotiating leverage demanding FSC chain-of-custody certification. The EU Single-Use Plastics Directive accelerates transitions away from plastic-coated grades toward fiber-based alternatives. Manufacturing clusters in North Rhine-Westphalia and Baden-Württemberg specialize in certified recycled-content and bamboo-based product lines.
United Kingdom
Food service group purchasing organizations consolidate spend through multi-year supply agreements with sustainability-linked volume commitments. REACH chemical registration requirements tighten allowable coatings and brightening agents in products sold across the European Economic Area. Distribution networks in the Midlands and Greater London prioritize mega-roll formats aligned with e-commerce fulfillment economics.
China
Dual carbon goals and provincial environmental compliance inspections accelerate alternative-fiber qualification programs across manufacturing footprints. The national standardization administration issues GB standards for tissue product quality and labeling. Production capacity concentrates in Guangdong and Zhejiang provinces where integrated mills serve both domestic food service and export contract manufacturing.
Japan
METI guidelines on sustainable procurement push hospitality and commercial sectors toward certified supply chains. JIS standards govern absorbency metrics and hygiene specifications for professional cleaning segments. Industrial clusters in the Kanto region around Tokyo specialize in premium air-laid technology for institutional accounts.
Kitchen Roll Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into integrated tissue mills with captive timberland supply, asset-light tolling arrangements leveraging third-party capacity, and regional converters targeting club-store shelf sets. Two dominant competitive moves define current positioning: backward integration into pulp supply agreements to hedge futures volatility, and certification-driven portfolio diversification to unlock premium retail channels.
Within the integrated mill tier, Procter & Gamble Co. and Kimberly-Clark Corporation exemplify scale-driven archetypes with North American pulp supply structures. Essity AB occupies a position emphasizing concentrated R&D spending on advanced manufacturing processes. Among European specialists, WEPA Professional GmbH and Metsä Tissue Group represent regional production concentration aligned with Ecolabel compliance requirements. Sofidel Group SPA and Georgia-Pacific anchor mid-cap positions through geographic diversification across Atlantic basin markets.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| Kimberly-Clark Corporation |
| Essity AB |
| Georgia-Pacific |
| Sofidel Group SPA |
| WEPA Professional GmbH |
| Oji Holdings Corporation |
| Hengan International Group Company Limited |
| Metsä Tissue Group |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Guangdong and Zhejiang provinces to Long Beach and Rotterdam determine landed cost spreads between integrated mills and tolling-dependent converters, compressing margin structures for non-captive supply chains while amplifying price differentiation between FSC-certified premium tiers and unverified standard grades.
Pricing Analysis
Certification level creates the primary spread across the kitchen roll market, with FSC chain-of-custody and EU Ecolabel compliance commanding shelf-space premiums in German and UK retail against uncertified private-label alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by absorbency technology and fiber provenance, with TAD-processed grades capturing margin uplift over conventional creped products. Cost compression in the standard tier is intensifying because pulp futures volatility and private-label concentration at Aldi and Lidl purchasing consortiums squeeze converter margins. Food service operators under Sodexo and Compass Group purchasing cooperatives show lowest price sensitivity due to sustainability-linked contract requirements, while household replenishment cycles through supermarket channels exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning as manufacturers qualify alternative fiber sources to hedge regulatory friction. Production gravity centers on China, the United States, and Germany, with integrated mills in Wisconsin and North Rhine-Westphalia controlling captive timberland supply while Chinese converters in Guangdong and Zhejiang serve export contract manufacturing. Fiber sourcing draws from northern softwood pulp, eucalyptus plantations, and emerging bamboo cultivation zones across Sichuan and Anhui provinces. Single-source vulnerability concentrates in bleached kraft pulp supply from Scandinavian and Brazilian producers. Distribution runs through food service group purchasing organizations, club-store fulfillment networks, and e-commerce platform logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kitchen roll market sits in early-cycle expansion as EU Single-Use Plastics Directive enforcement accelerates material transitions away from plastic-coated alternatives toward fiber-based absorbent products.
For Market Incumbents: Insulate margin structures by deepening backward integration into North American pulp supply agreements and accelerating FSC certification coverage across product portfolios to defend against private-label encroachment at German retail consortiums. Prioritize capacity utilization in integrated tissue mills serving national QSR contracts rather than competing for spot market tolling arrangements. For New Entrants and Emerging Players: Pursue asset-light tolling arrangements with underutilized air-laid capacity in European manufacturing clusters to bypass capital barriers for premium absorbency tier entry. Target hospitality sector procurement in Japan and the United Kingdom where METI guidelines and REACH compliance create certification-based switching costs that favor agile specialists over legacy integrated mills. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate parent companies with non-core tissue operations lacking Ecolabel compliance infrastructure or integrated fiber supply. Mid-cap regional converters with established FSC chain-of-custody and existing Aldi or Lidl supply relationships present viable acquisition profiles over a five-to-ten year consolidation horizon. Watch for pulp futures volatility spikes as inflection indicators that would accelerate distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Acceleration | EU Ecolabel compliance unlocks premium positioning in German and UK retail channels. |
| Air-Laid Technology Investment | Advanced TAD processes enable superior absorbency tiers commanding club-store shelf space. |
| Backward Integration into Pulp Supply | Captive timberland agreements hedge futures volatility against private-label price pressure. |
| Mega-Roll Format Expansion | Lower replenishment-frequency packs align with Amazon and Costco fulfillment economics. |
| Food Service Direct Contracting | QSR chain relationships bypass distributor markups and secure volume commitments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tissue mill operations directors, retail category buyers at Aldi and Lidl, food service procurement leads at Aramark and Sodexo, and sustainability certification auditors; alongside secondary validation through EU Ecolabel registry databases, FSC chain-of-custody disclosure records, pulp futures exchange data, and SEC filings from publicly traded manufacturers. Bottom-up volume estimates from production capacity utilization rates and top-down demand calibration from retail scan data were triangulated to reconcile segment-level figures.
Forecast inputs include modeled trajectories across product type, material composition, end-use sector, and geographic regulatory cluster throughout the projection horizon. CAGRs were derived from regression analysis against macroeconomic indicators and pulp price indices, with cross-segment elasticity effects incorporated for substitution between virgin pulp, recycled fiber, and bamboo grades.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese integrated mills or accelerated EU regulatory tightening would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
Corrugated Mailers Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Paper Packaging Materials Market