
 Coated White Board Paper Market | 2026-2036
Coated White Board Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Coated White Board Paper Market Outlook
Finland is rewriting the competitive map of coated white board paper through sustained mill modernization and pulp integration. Stora Enso leverages its Oulu bioproduct mill complex to anchor high-volume supply of coated grades into continental Europe. UPM-Kymmene Corporation differentiates through proprietary coating formulations that tighten surface smoothness tolerances for high-resolution commercial printing. International Paper sustains its position across North American folding carton demand through integrated containerboard-to-coated board conversion lines.
Coated white board paper consists of multi-ply paperboard with mineral pigment and binder layers applied to one or both surfaces, typically achieving gloss levels above 60 GU at 75 degrees for premium commercial reproduction. The coating layer, composed of kaolin clay and calcium carbonate in a latex binder matrix, creates a receptive surface for offset lithography and digital toner adhesion in luxury packaging and display applications. Double-sided coated grades command the thickest margin pools where cosmetic and pharmaceutical brands specify uniform print fidelity on exterior and interior carton faces. Specialty coated variants, including anti-scratch and moisture-resistant formulations, represent the fastest-expanding product type as e-commerce fulfillment demands tougher board performance through distribution chains. By end user, the packaging industry absorbs the dominant volume share as consumer goods manufacturers convert from plastic rigid boxes to fiber-based alternatives.
EMA and REACH frameworks in Europe enforce migration limits for mineral oils and heavy metals in food-contact coated board, compelling mills to certify coating chemistries through third-party laboratories. The EU Green Deal's packaging and packaging waste regulation revision tightens recycled content thresholds and restricts fluorinated treatments that historically imparted grease resistance. Stakeholders must monitor how FDA food-contact notification requirements for new coating substances interact with state-level extended producer responsibility laws in California and Maine, as divergence between jurisdictions multiplies compliance architecture for multinational suppliers.
Market Dynamics
REACH migration limits on mineral oils in food-contact packaging are forcing mills to re-engineer coating chemistries and certify through third-party laboratories, compressing margins while creating competitive separation between certified and uncertified suppliers.
Growth Catalysts
- E-commerce fulfillment standards:Anti-scratch and moisture-resistant coated grades absorb surging order volumes as distribution chains demand tougher board performance through multiple handling touchpoints.
- EU Green Deal packaging waste revision:Recycled content thresholds and fluorinated treatment restrictions redirect brand procurement toward certified fiber-sourced coated board with verifiable carbon intensity credentials.
- Rhine-Ruhr folding carton clustering:German converters concentrate demand around integrated mill-to-converter logistics corridors, reducing inbound freight costs for high-volume premium retail box orders.
Market Restraints
- Kaolin clay supply concentration:Brazilian and UK deposit dominance creates input cost volatility when currency fluctuations or shipping disruptions affect pigment availability for coating formulations.
- Calcium carbonate energy intensity:Precipitated calcium carbonate production requires substantial natural gas input, exposing coating layer costs to European energy price spikes.
- Plastic rigid box substitution limits:Moisture barrier performance gaps in standard coated grades prevent full displacement of plastic in certain pharmaceutical and cosmetic packaging specifications.
Strategic Opportunities
- India folding carton underpenetration:Domestic coated board capacity lags behind fast-moving consumer goods packaging demand growth, creating import substitution potential for integrated pulp-to-board operators.
- Digital toner adhesion chemistry:Proprietary coating formulations enabling high-resolution variable data printing open premium pricing tiers for personalized packaging campaigns in cosmetics and luxury spirits.
- California extended producer responsibility:State-level packaging waste laws mandate recycled fiber minimums that favor suppliers with pre-certified circular supply chains over uncertified competitors.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise combining mineral pigment dispersion with latex binder optimization commands premium compensation, constraining mill R&D expansion timelines.
- Food-contact notification timelines:FDA review periods for novel coating substances extend 18-24 months, delaying product launches for mills pursuing performance differentiation through chemistry innovation.
- Double-sided grade quality consistency:Achieving uniform gloss and smoothness tolerances across both surfaces requires capital-intensive multi-station coating lines that smaller mills struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated White Board Paper Market |
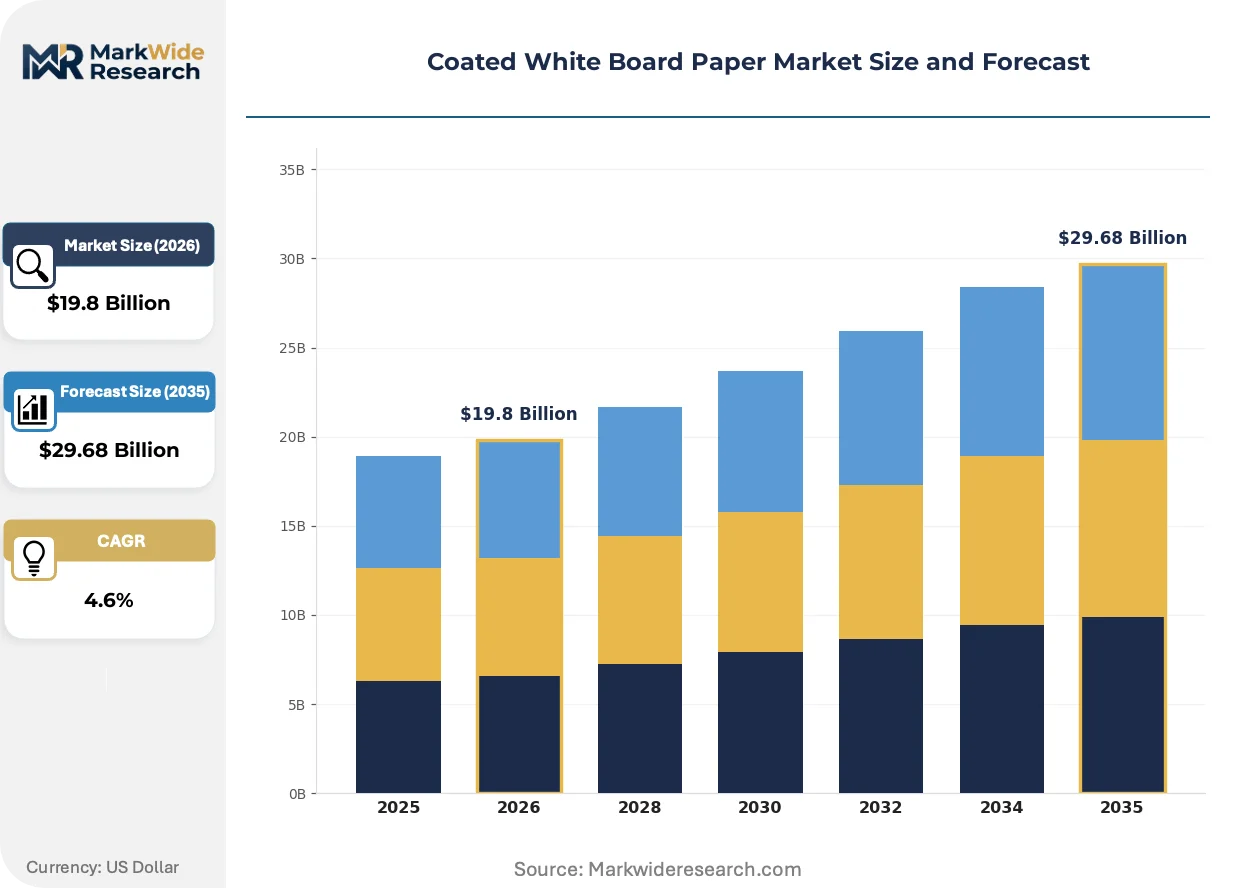
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $29.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Specialty Coated, Machine Finished End User: Printing Industry, Packaging Industry, Office Supplies, Educational Institutions Thickness: Lightweight, Medium Weight, Heavyweight, Ultra Heavyweight Coating Type: Matte, Glossy, Satin, Anti-Glare |
| Companies Covered | International Paper, Stora Enso, UPM-Kymmene Corporation, Oji Holdings Corporation, Sappi Limited, Nippon Paper Industries, Smurfit Kappa Group, Mondi Group, Graphic Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated White Board Paper Market Strategic Shifts
Water-based barrier coatings are displacing conventional polyethylene extrusion layers in food-contact applications, while digital print compatibility requirements are rewriting coating formulation specifications across premium packaging segments.
Advanced water-based barrier technologies incorporating plant-derived polymers are rendering obsolete conventional polyethylene-laminated board in chilled and frozen food carton applications. Major European dairy and ready-meal brands have accelerated qualification timelines for these substrates. The structural consequence is compression of incumbent extrusion coating equipment valuations as mills redirect capital toward aqueous dispersion lines.
EU Green Deal packaging waste regulation revision tightens recycled content mandates and restricts per- and polyfluoroalkyl substance treatments historically used for grease resistance. Mills must reformulate coating layers to achieve equivalent barrier performance without fluorinated chemistries. Premium food-service carton segments in Germany and France face the steepest compliance timelines and are consolidating supplier relationships around early-certified mills.
Brand procurement teams now specify digital print readiness as a standard coating performance metric rather than a premium option, compressing qualification cycles for analog-only board grades. Folding carton converters in North America and continental Europe are retiring offset-dedicated inventory positions. This behavioral shift concentrates volume with mills offering coating formulations optimized for both toner adhesion and inkjet receptor properties.
Coated White Board Paper Market Segmentation
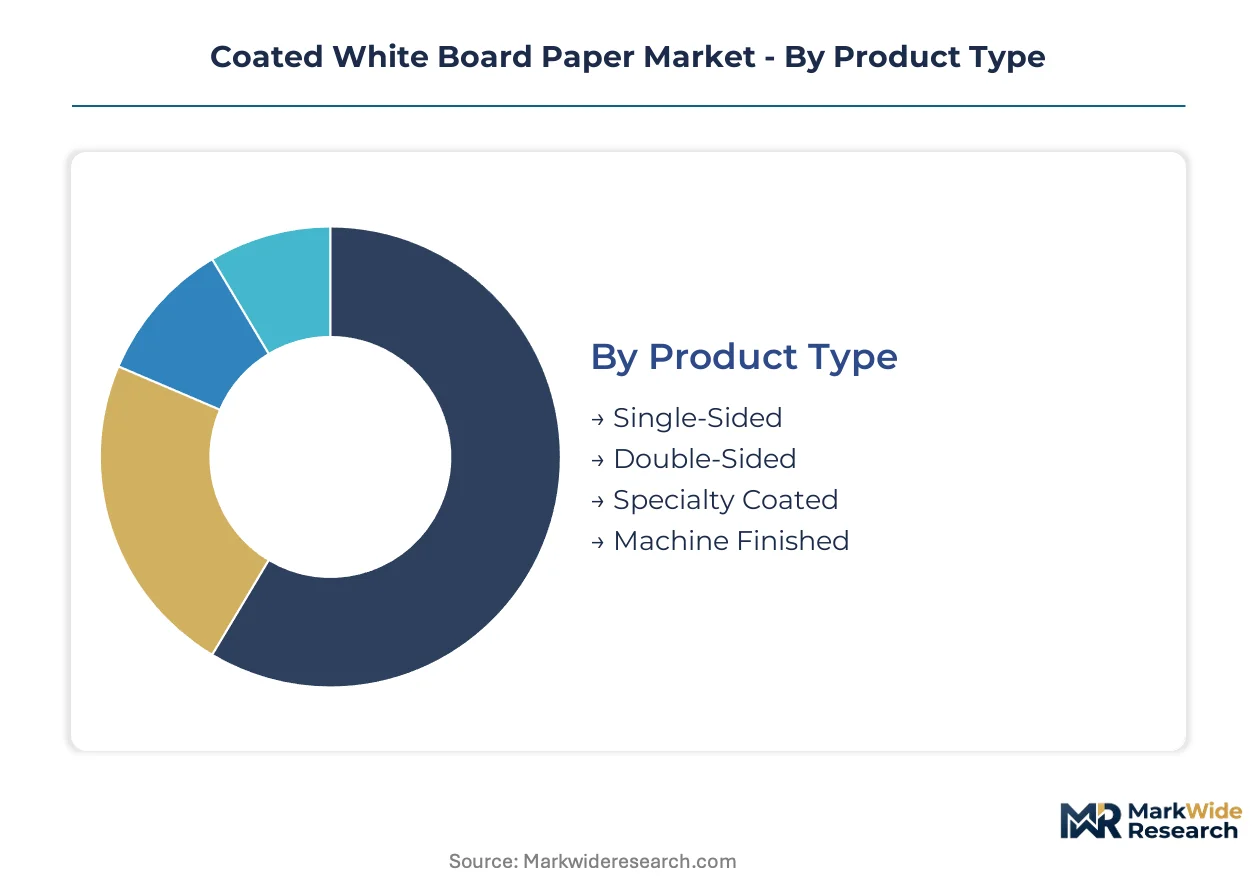
Segmentation in coated white board paper reveals how coating architecture, end-use performance requirements, and caliper specifications create distinct margin pools and capital allocation priorities for mills. Understanding these divides exposes where formulation R&D investments concentrate versus where volume commoditization pressures dominate.
Product Type:
Mature commodity grades anchor baseline capacity utilization while emerging specialty formulations capture expanding premium pricing tiers.
- Double-Sided:Mineral pigment and latex binder layers applied to both surfaces achieve uniform gloss levels exceeding 60 GU for luxury cosmetic and pharmaceutical cartons requiring identical print fidelity on exterior and interior faces. German folding carton converters around the Rhine-Ruhr corridor concentrate procurement of these grades for premium retail box orders.
- Specialty Coated:Anti-scratch and moisture-resistant formulations incorporate modified latex matrices and cross-linked polymers to withstand e-commerce distribution chain handling. Demand is climbing fastest as fulfillment networks specify tougher board performance through multiple touchpoints.
- Single-Sided:One-surface coating reduces material input for cost-sensitive applications where reverse-side print quality is non-critical.
- Machine Finished:Uncoated calendered surface provides base stock for downstream converter coating operations.
Double-Sided retains volume leadership; Specialty Coated holds the steepest expansion curve.
End User:
Application-driven performance specifications split procurement between precision reproduction requirements and protective packaging functionality.
- Packaging Industry:Folding carton converters specify coated board for food cartons, premium retail boxes, and pharmaceutical blister packs where surface smoothness directly determines print registration accuracy. REACH migration limits on mineral oils in food-contact applications are forcing mills to re-engineer coating chemistries and certify through third-party laboratories.
- Printing Industry:Commercial lithography and digital print shops demand tight surface smoothness tolerances for high-resolution reproduction in catalogs and display graphics.
- Office Supplies:Standard presentation and report covers utilize lighter coated grades where cost efficiency outweighs premium surface characteristics.
- Educational Institutions:Workbook and instructional material publishers specify mid-tier coated board for durability at institutional budget constraints.
Packaging Industry commands the dominant procurement volume; Specialty formulations for e-commerce fulfillment are gaining share fastest.
Thickness:
Caliper selection maps directly to structural rigidity requirements and postal weight optimization in distribution economics.
- Heavyweight:Substantial board construction provides structural integrity for rigid luxury packaging and display applications where dimensional stability under load is essential.
- Medium Weight:Balanced stiffness-to-weight ratio serves standard folding carton applications across consumer goods segments.
- Lightweight:Reduced caliper meets postal optimization targets for direct mail and catalog distribution where per-unit shipping cost sensitivity dominates.
- Ultra Heavyweight:Maximum rigidity specifications support point-of-purchase displays and premium gift packaging requiring substantial hand-feel perception.
Medium Weight maintains baseline volume; Heavyweight is climbing fastest as brand owners upgrade packaging perceived value.
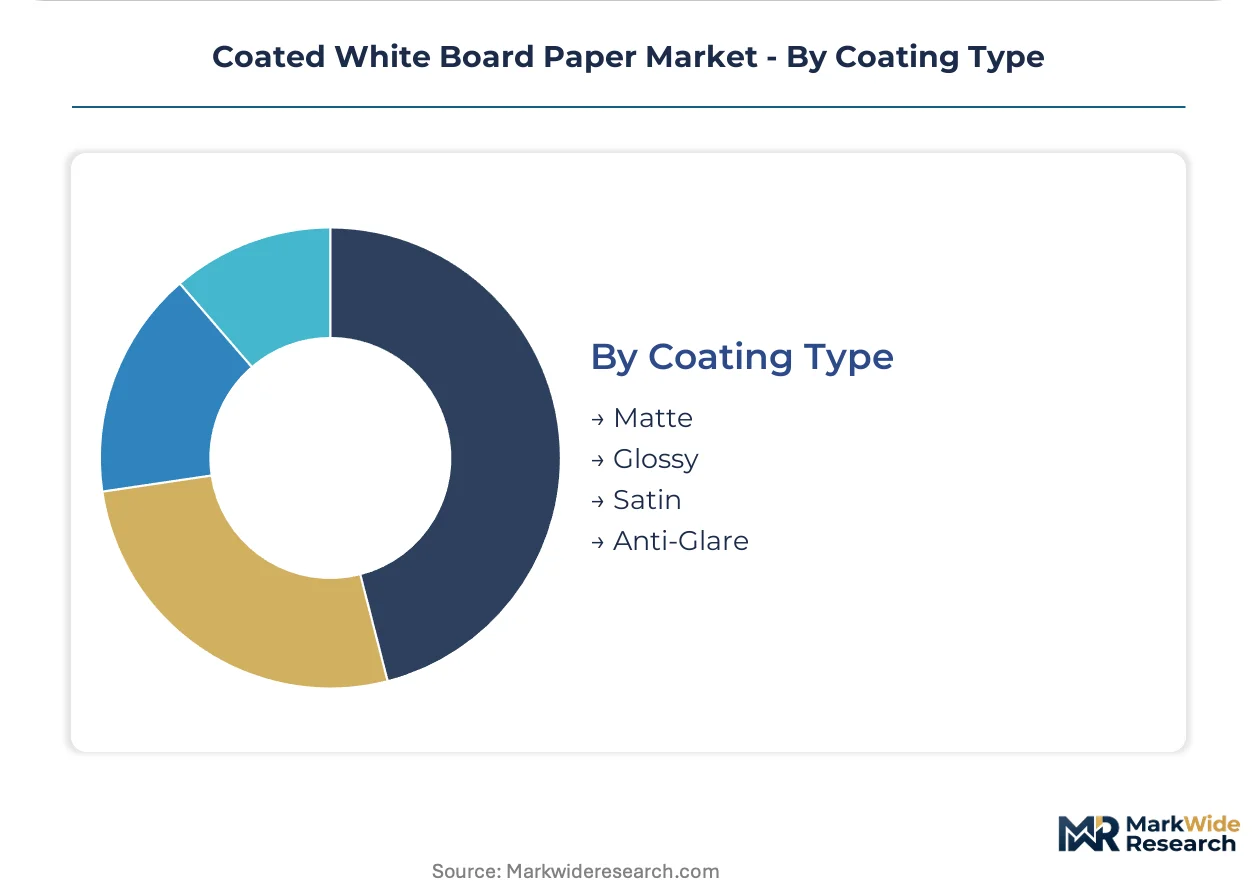
Coating Type:
Surface finish specifications divide between aesthetic differentiation and functional readability requirements under varied lighting conditions.
- Glossy:High-specular finish maximizes color saturation and visual impact for cosmetic and luxury spirits packaging where shelf presence determines purchase conversion.
- Matte:Diffuse surface reflection reduces glare for instructional materials and premium publications where prolonged reading comfort matters.
- Satin:Intermediate sheen level balances aesthetic appeal with fingerprint resistance in handling-intensive applications.
- Anti-Glare:Engineered micro-surface texture scatters incident light for digital display backing and architectural presentation boards.
Glossy retains premium positioning; Matte is expanding most quickly as digital content consumption shifts tactile expectations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mill capacity clusters along the Baltic Sea and Rhine-Ruhr corridor, with integrated pulp-to-board operations anchoring supply into continental Europe. German folding carton converters absorb the dominant volume share for premium retail applications.
Germany
Rhine-Ruhr industrial corridor hosts the densest concentration of folding carton converters in Europe, driving procurement of double-sided coated grades for cosmetic and pharmaceutical packaging. REACH migration limits on mineral oils in food-contact applications compel mills to certify coating chemistries through ECHA-recognized laboratories. Düsseldorf and Cologne logistics hubs enable just-in-time delivery from integrated mills in Lower Saxony.
Finland
Stora Enso's Oulu bioproduct mill complex supplies high-volume coated board into German and French markets through Baltic Sea shipping routes. EU Green Deal packaging waste regulations redirect capital toward certified fiber sourcing and carbon intensity reduction. Kotka and Helsinki ports serve as export gateways for specialty coated grades targeting Nordic premium packaging demand.
United States
Integrated containerboard-to-coated board conversion lines sustain supply for North American folding carton demand, particularly in food service and retail box segments. FDA food-contact notification requirements for novel coating substances interact with state-level extended producer responsibility laws in California and Maine. Wisconsin and Georgia mill clusters concentrate production capacity near major corrugated converter networks.
China
Domestic coated board capacity expansion lags behind fast-moving consumer goods packaging demand growth, creating import dependency for premium grades. GB standards for food-contact paperboard enforce heavy metal and fluorescent whitening agent limits that mills must verify through SAMR-recognized testing. Yangtze River Delta converters in Shanghai and Jiangsu province concentrate demand for high-gloss cosmetic packaging substrates.
India
FMCG sector expansion outpaces domestic coated white board paper capacity, generating import substitution opportunities for integrated pulp-to-board operators. FSSAI food safety standards mandate coating compliance for direct food-contact cartons in dairy and ready-meal segments. Maharashtra and Gujarat industrial corridors cluster folding carton converters serving Mumbai and Ahmedabad consumer goods markets.
Coated White Board Paper Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The market structure consolidates around vertically integrated forest products conglomerates with captive pulp supply, while regional converters occupy fragmented downstream positions. Three archetypes dominate: Nordic pulp-integrated mills with bioproduct diversification, North American containerboard converters extending into coated grades, and Asian packaging conglomerates with scale-driven cost positions. Competitive moves concentrate on capacity expansion in water-based barrier coating lines and strategic partnerships with folding carton converters for qualification acceleration.
Among Nordic pulp-integrated operators, Stora Enso and UPM-Kymmene Corporation exemplify the bioproduct mill archetype combining certified fiber sourcing with proprietary coating formulation capabilities. International Paper anchors the North American integrated converter tier, representing scale-driven positions in containerboard-to-coated board transition lines. These three companies sit within distinct geographic supply orbits—Baltic Sea, North American Great Lakes, and Southeastern US mill networks—each commanding regional procurement relationships with major folding carton converters.
| Leading Market Players |
|---|
| International Paper |
| Stora Enso |
| UPM-Kymmene Corporation |
| Oji Holdings Corporation |
| Sappi Limited |
| Nippon Paper Industries |
| Smurfit Kappa Group |
| Mondi Group |
| Graphic Packaging International |
| Others |
Value Chain & Pricing Dynamics
Baltic Sea shipping corridors linking Finnish mills to German Rhine-Ruhr converters compress freight differentials between integrated and non-integrated suppliers, amplifying pricing power for backward-linked operators while forcing merchant market participants to absorb logistics volatility or concede volume.
Pricing Analysis
REACH migration limits on mineral oils dictate the pricing tier structure across food-contact and non-food segments. Three-tier pricing structure across premium, standard, and economy levels separates certified fiber-sourced grades with ECHA-recognized laboratory validation from uncertified merchant supply. Price differentiation hinges on coating formulation complexity and carbon intensity credentialing. Cost compression in standard grades is intensifying because precipitated calcium carbonate production exposes coating layers to European natural gas price spikes. Small folding carton converters in Southern Europe exhibit highest price sensitivity; cosmetic and pharmaceutical brand owners in Germany show lowest sensitivity due to print fidelity requirements.
Supply Chain Analysis
Tariff exposure between Brazil and European coating mills dominates input cost volatility for kaolin clay-dependent formulations. Supply concentrates in Finland, Germany, and the United States for integrated pulp-to-board capacity, with merchant market dependence rising in India and China. Raw material dependencies center on Brazilian kaolin deposits, precipitated calcium carbonate from regional chemical suppliers, and latex binders from petrochemical streams. Single-source vulnerability in specialty coating chemist talent constrains mill R&D expansion timelines. Distribution runs through converter-proximate logistics hubs in Düsseldorf, Cologne, and Kotka for just-in-time premium retail box fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around REACH certification and EU Green Deal compliance creates structural barriers that compound over qualification cycles.
For Market Incumbents: Insulate margin position through captive pulp integration and accelerated water-based barrier coating line deployment before fluorinated treatment restrictions tighten. Threat from Asian packaging conglomerates with scale-driven cost positions intensifies in India import substitution segments. Certification investment in ECHA-recognized laboratory partnerships secures food-contact procurement relationships against uncertified competitors. For New Entrants and Emerging Players: Build out specialty coated capacity targeting anti-scratch and moisture-resistant formulations for e-commerce fulfillment networks. India folding carton underpenetration offers the most penetrable geography where domestic capacity lags FMCG packaging demand growth. Go-to-market angle should emphasize digital print readiness as standard performance metric rather than premium option. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified forest products conglomerates seeking to monetize non-core coated board assets. Long-term viability over a multi-year horizon rests on water-based barrier technology positioning and circular supply chain certification. Signal to watch: acceleration of California extended producer responsibility enforcement shifting procurement toward pre-certified circular suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Coating Line Expansion | Displacement of polyethylene-laminated board accelerates as European dairy brands compress qualification timelines. |
| Digital Print Compatibility Certification | Folding carton converters in North America retire offset-dedicated inventory, concentrating volume with qualified mills. |
| Integrated Pulp-to-Board Capacity Addition | Rhine-Ruhr logistics corridors reduce inbound freight costs for high-volume premium retail box orders. |
| Specialty Coating Formulation Partnership | Proprietary anti-scratch matrices open premium pricing tiers for e-commerce fulfillment applications. |
| Circular Supply Chain Certification Program | EU Green Deal recycled content mandates redirect brand procurement toward verified carbon intensity credentials. |
Study Parameters
Operator-level perspectives from mill coating chemists, folding carton converter procurement directors, and brand sustainability officers anchored the qualitative base. Primary interviews combined with secondary validation through ECHA regulatory filings, EU packaging waste regulation drafts, and customs trade data for kaolin and calcium carbonate flows. SEC 10-K disclosures from integrated forest products conglomerates and Baltic Sea shipping manifests provided capacity and logistics benchmarks. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Scenario-bracketing around regulatory implementation timelines and energy price volatility shaped the analytical framework. Segmentation dimensions modeled include coating architecture, end-use performance requirements, caliper specifications, and regional regulatory cluster. CAGRs derived from volume trajectory analysis against capacity expansion announcements and substitution elasticity assumptions. Industry-specific forecast inputs incorporated folding carton converter clustering patterns and e-commerce fulfillment network expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian packaging conglomerates with scale-driven cost positions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
United States Paper Packaging Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
Tea Filter Paper Market