
 Tracing Paper Market | 2026-2036
Tracing Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Tracing Paper Market Analytics
Architectural drafting is broadening its share of tracing paper consumption as hybrid digital-manual workflows expand in design studios. Clairefontaine leverages its European manufacturing base to sustain premium positioning across specialty grades. Nippon Paper Industries anchors supply reliability through integrated pulp-to-paper operations in East Asia. Hahnemühle FineArt GmbH differentiates via artisanal production methods targeting conservation-grade applications.
Tracing paper is a cellulose-based substrate engineered to achieve controlled translucency, typically manufactured through extended beating of fibers to reduce opacity while maintaining tensile strength above 3.5 kN/m for ink stability. Its primary purpose is to enable precise overlay reproduction in technical and creative workflows where dimensional accuracy and light transmission are critical. Transparent tracing paper leads volume due to universal applicability across drafting disciplines, while specialty tracing paper commands concentrated margin pools from archival and conservation markets. Architectural drafting drives structural growth as building information modeling workflows still require physical markup layers, and pigment printed paper occupies a niche serving pre-printed template demand from educational institutions.
EPA guidelines govern chemical discharge from pulp bleaching operations affecting North American supply chains, while REACH mandates in Europe restrict formaldehyde-based resin coatings used to enhance dimensional stability. ISO 9706 permanence standards shape product differentiation for archival-grade segments by defining pH thresholds and tear resistance minimums. Stakeholders must monitor evolving chemical disclosure requirements across multiple jurisdictions to determine which product lines warrant reformulation investment versus phase-out.
Market Dynamics
Hybrid architectural workflows are compressing the boundary between digital and manual drafting, forcing mills to recalibrate production runs for smaller-batch specialty grades alongside commodity transparent stock.
Growth Catalysts
- Building Information Modeling integration:Architectural firms in Germany and Japan maintain physical markup layers for regulatory submission, sustaining demand for dimensionally stable translucent substrates.
- REACH chemical disclosure mandates:European coating reformulation is accelerating transparency into resin compositions, creating competitive separation for compliant producers.
- Conservation-grade applications:Museums and archives in Switzerland and Australia are expanding ISO 9706-certified inventory for long-term document preservation.
Market Restraints
- Pulp cost volatility:Hardwood fiber prices fluctuate with Nordic supply disruptions, squeezing margin on standard-grade transparent tracing paper.
- East Asian supply concentration:Integrated pulp-to-paper operations in Japan and South Korea limit alternative sourcing for Western converters during logistics disruptions.
- Digital tablet substitution:Wacom and Apple stylus systems are capturing preliminary sketch phases previously executed on translucent substrates.
Strategic Opportunities
- Indian technical education expansion:Engineering institutes under the country's PLI scheme are equipping drafting labs with pre-printed template stocks for standardized coursework.
- Carbon-neutral coating chemistry:Bio-based resin alternatives align with EU Green Deal procurement preferences for public infrastructure documentation.
- Direct-to-studio distribution:Bypassing traditional paper merchants through specialized e-commerce portals serving freelance illustrators and independent architects.
Industry Challenges
- Beating technician scarcity:Extended fiber processing for controlled translucency requires skills concentrated in aging European and Japanese workforces.
- ISO 9706 certification timelines:Laboratory permanence testing extends product development cycles by 18-24 months for archival-grade launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tracing Paper Market |
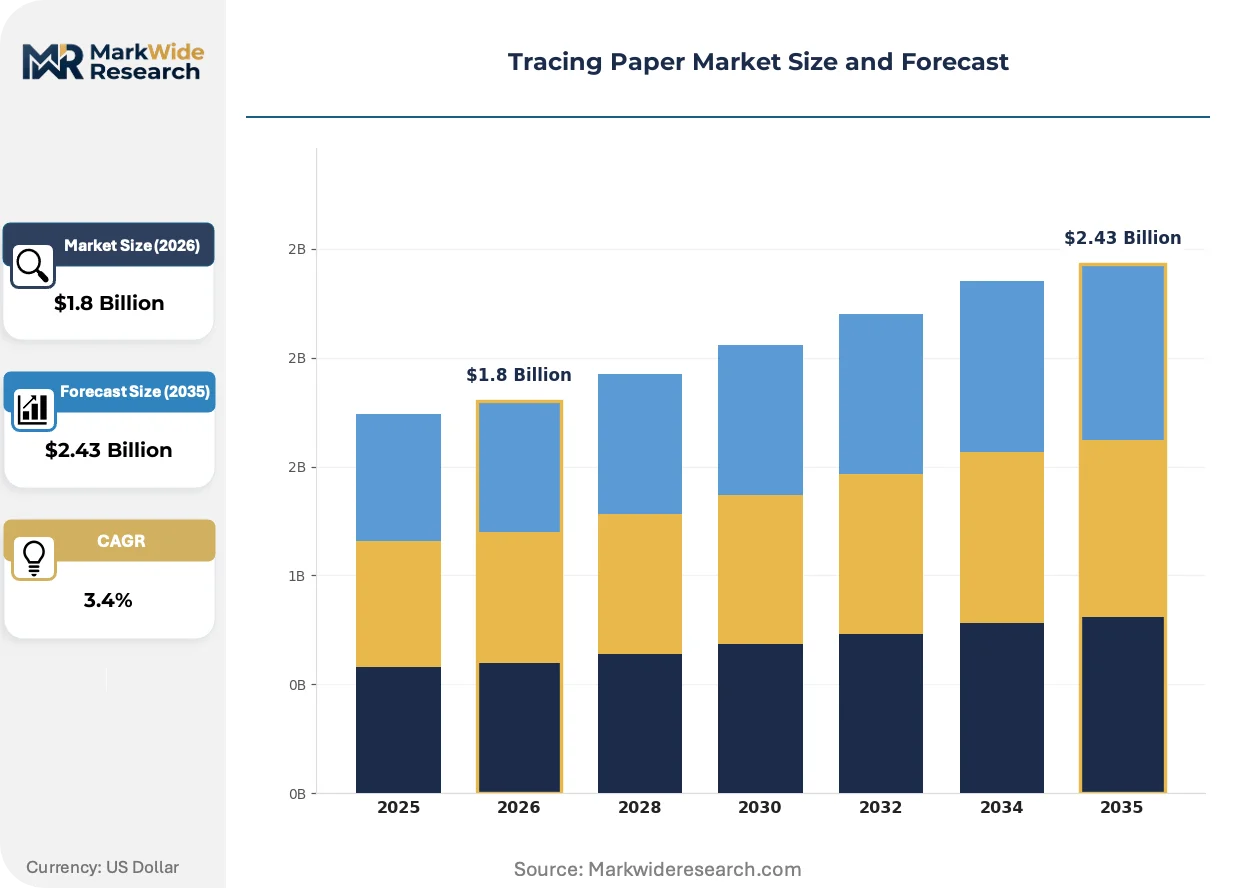
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Tracing Paper, Translucent Tracing Paper, Pigment Printed Paper, Specialty Tracing Paper Application: Graphic Design, Art Projects, Technical Drawings, Architectural Drafting End User: Artists, Architects, Designers, Students Distribution Channel: Online Stores, Retail Shops, Wholesale Distributors, Specialty Stationery |
| Companies Covered | Borden & Riley Paper Co., Clairefontaine, Alvin & Company, Inc., Nippon Paper Industries Co., Ltd., Daler-Rowney Ltd., Bee Paper Company, Canson Inc., Hahnemühle FineArt GmbH, Bienfang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tracing Paper Market Evolving Landscape
Material science advances and regulatory chemistry shifts are redefining performance benchmarks for translucent substrates, with sustainability credentials now filtering procurement decisions alongside traditional mechanical specifications.
Cellulose nanofibril reinforcement is absorbing mechanical stress in ultra-thin tracing grades below 40 gsm, enabling Japanese architectural offices to reduce shipping weight for international competition submissions without sacrificing ink stability. The technology is compressing the performance gap between synthetic polyester alternatives and premium cellulose stocks.
REACH Annex XVII restrictions on formaldehyde-based resins are forcing coating reformulation across European mills, with ECHA compliance deadlines in 2027 driving accelerated R&D into bio-aldehyde crosslinkers. Archival-grade producers in Germany and France are most exposed, with product lines requiring full requalification against ISO 9706 permanence standards.
Consolidated procurement by multi-office architectural networks is fragmenting historical merchant relationships, with design conglomerates in London and New York negotiating master supply agreements directly with mills. Independent studios are responding through cooperative purchasing platforms that aggregate volume for freight efficiency without surrendering grade customization.
Tracing Paper Market Segmentation
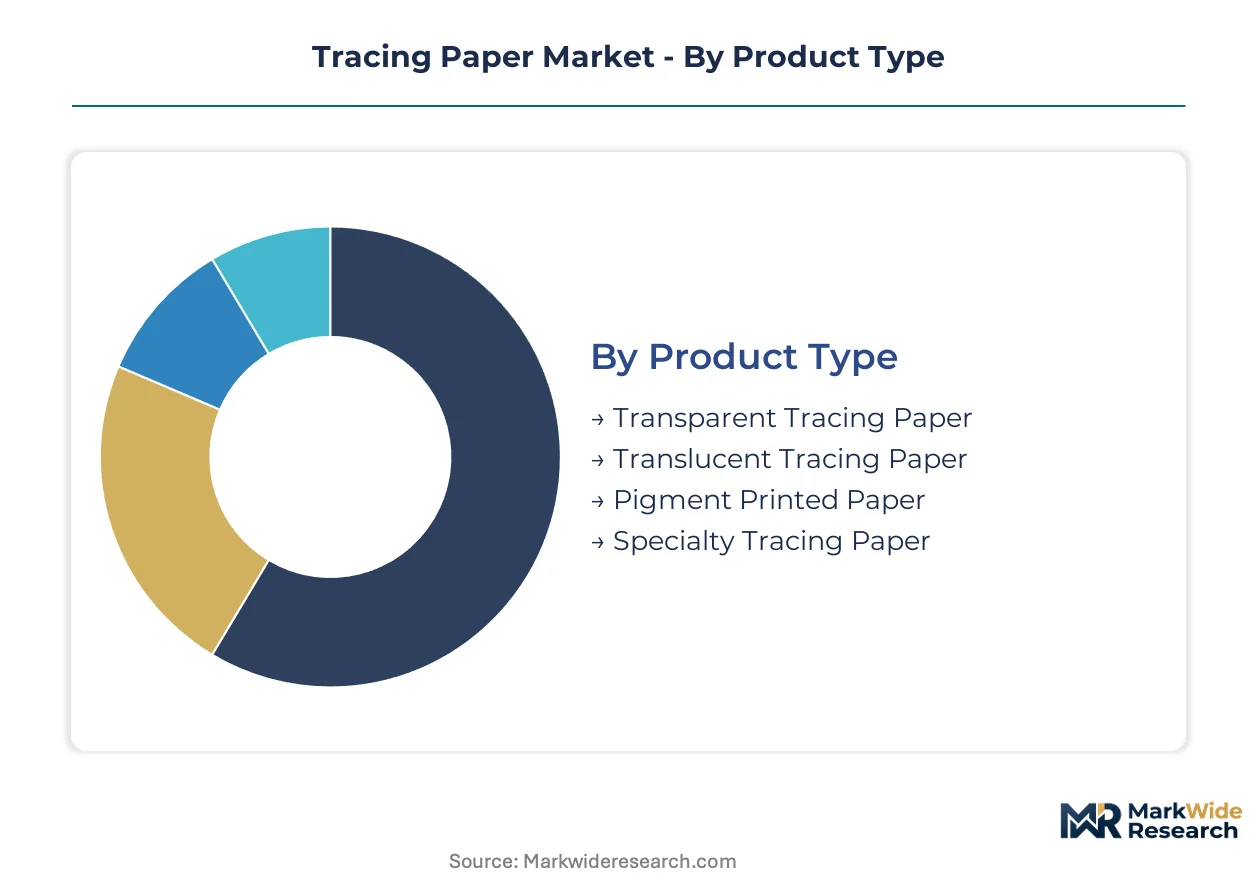
Tracing paper demand fragments across four distinct dimensions, each responding to different procurement rhythms and performance specifications. Product type determines margin structure and coating chemistry investment, while application and end-user categories govern volume concentration and channel strategy.
Product Type:
Upgrade cycles in drafting workflows are compressing replacement timelines for premium grades while extending commodity stock lifespans.
- Transparent Tracing Paper:Manufactured through extended fiber beating to achieve controlled translucency above 60% light transmission while maintaining tensile strength thresholds for ink stability. Demand concentrates in German and Japanese architectural studios where Building Information Modeling workflows still require physical markup layers for regulatory submission.
- Specialty Tracing Paper:Engineered with cellulose nanofibril reinforcement and conservation-grade chemistry meeting ISO 9706 permanence standards. Swiss and Australian museums are expanding certified inventory for long-term document preservation, driving margin concentration despite smaller batch volumes.
- Translucent Tracing Paper:Intermediate opacity grades serving educational institutions and amateur illustrators with balanced cost-performance profiles.
- Pigment Printed Paper:Pre-printed template stocks standardized under India's PLI scheme for technical education expansion in engineering institutes.
Volume placements concentrate in transparent tracing paper; the faster expansion belongs to specialty tracing paper.
Application:
Cost tier stratification separates capital-intensive professional workflows from budget-constrained educational and hobbyist use cases.
- Architectural Drafting:Hybrid digital-manual workflows in London and New York design conglomerates sustain demand for dimensionally stable translucent substrates. Consolidated procurement through master supply agreements is fragmenting historical merchant relationships.
- Technical Drawings:Precision overlay reproduction in engineering documentation requires controlled dimensional stability under humidity variation.
- Graphic Design:Freelance illustrators in cooperative purchasing platforms aggregate volume for freight efficiency without surrendering grade customization.
- Art Projects:Conservation-grade applications in museum and gallery contexts demand archival chemistry compliance.
Architectural drafting commands the dominant revenue share; graphic design is climbing the fastest as independent studio formation accelerates.
End User:
Customer type determines sensitivity to certification premiums versus price elasticity, with professional segments absorbing reformulation costs that students resist.
- Architects:Regulatory submission requirements in Germany and Japan mandate physical markup layers, sustaining premium-grade procurement despite digital tablet substitution pressure from Wacom and Apple stylus systems.
- Designers:Specialized e-commerce portals are enabling direct-to-studio distribution, bypassing traditional paper merchants for customized specifications.
- Artists:Conservation-grade chemistry awareness drives ISO 9706-certified purchases for portfolio longevity.
- Students:Indian engineering institutes under PLI scheme procurement standardize on pre-printed template stocks for coursework uniformity.
Architects generate the highest per-unit margins; students represent the steepest volume expansion trajectory through institutional procurement scaling.
Distribution Channel:
Supply concentration in East Asian integrated pulp-to-paper operations shapes channel reliability and geographic reach constraints.
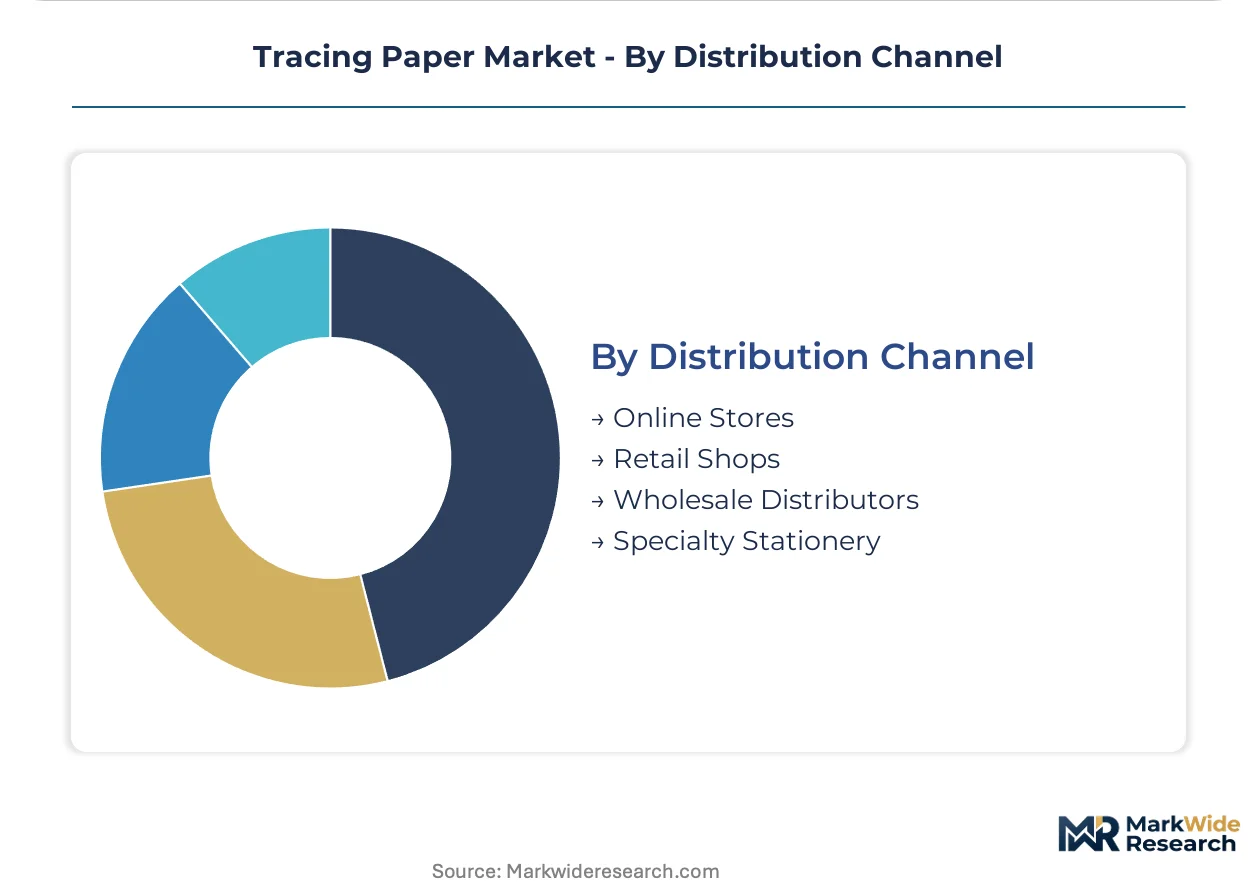
- Wholesale Distributors:Traditional merchant relationships face compression as multi-office architectural networks negotiate direct mill agreements, though they retain relevance for fragmented independent studio access.
- Online Stores:Specialized e-commerce portals serving freelance illustrators enable grade customization without volume minimums, aggregating dispersed demand for freight efficiency.
- Specialty Stationery:Curated conservation-grade and archival product lines for museum and gallery procurement with technical consultation services.
- Retail Shops:Immediate-need fulfillment for students and amateur practitioners with limited brand differentiation.
Wholesale distributors retain the largest transaction volume; online stores are gaining share fastest through independent professional aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Tamil Nadu are concentrating technical education procurement under India's PLI scheme, redirecting institutional demand toward standardized drafting supplies.
Germany
REACH Annex XVII mandates are forcing coating reformulation across Baden-Württemberg mills by 2027. ECHA compliance deadlines accelerate R&D into bio-aldehyde crosslinkers for dimensional stability. Stuttgart's engineering design clusters sustain premium-grade demand through hybrid BIM workflows requiring physical markup layers.
Japan
METI industrial standards govern cellulose nanofibril reinforcement adoption in ultra-thin grades below 40 gsm. Tokyo architectural offices reduce international shipping weights through advanced fiber processing. Kanto region studios anchor East Asian demand for competition-ready translucent substrates.
United States
EPA discharge guidelines from pulp bleaching operations affect supply chain reliability for North American converters. California technical illustration markets fragment procurement through cooperative purchasing platforms. Pacific Northwest distributors face compression as multi-office networks negotiate direct mill agreements.
India
PLI scheme incentives standardize pre-printed template procurement across Maharashtra engineering institutes. BIS certification requirements shape import substitution strategies for educational-grade stocks. Mumbai-Pune corridor drafting labs scale institutional volumes under centralized government procurement.
Switzerland
Swissmedic-adjacent conservation standards exceed ISO 9706 baselines for museum-grade chemistry. Federal archival regulations mandate permanence testing for long-term document preservation. Basel and Zurich museum clusters expand certified inventory for heritage documentation.
Tracing Paper Market Competitive Landscape
Top-tier vendors anchor premium specialty grades, while mid-scale European and East Asian producers compete on coating chemistry compliance. The vendor base stratifies across integrated pulp-to-paper operators, artisanal mills, and regional converters serving educational markets. Three archetypes dominate: conservation-grade specialists, mass-market transparent stock producers, and hybrid digital-manual workflow suppliers. Capacity consolidation and REACH-driven reformulation partnerships represent the dominant competitive vectors.
Among European heritage mills, Clairefontaine and Hahnemühle FineArt GmbH occupy positions within the conservation-grade archetype, leveraging artisanal production credentials for archival market penetration. Nippon Paper Industries Co., Ltd. anchors the integrated operator segment through captive pulp supply chains. These three exemplify how geographic concentration of beating technician skills creates defensive moats against digital substitution pressures.
| Leading Market Players |
|---|
| Borden & Riley Paper Co. |
| Clairefontaine |
| Alvin & Company, Inc. |
| Nippon Paper Industries Co., Ltd. |
| Daler-Rowney Ltd. |
| Bee Paper Company |
| Canson Inc. |
| Hahnemühle FineArt GmbH |
| Bienfang |
| Others |
Value Network & Pricing Analysis
Hardwood fiber price indices in Nordic markets cascade through tracing paper supply chains, compressing margins on standard transparent grades while amplifying premium capture for ISO 9706-certified specialty stocks. Mills in Germany and Japan translate pulp volatility into three-tier pricing structures across premium, standard, and economy levels, with architectural studios absorbing reformulation costs that educational buyers resist.
Pricing Analysis
Short lead-time premiums command measurable markups as Stuttgart engineering clusters and Tokyo architectural offices pay expedited rates for competition-ready translucent substrates. Price differentiation rests on certification grade and volume scale, with conservation-grade chemistry sustaining margin pools despite smaller batch sizes. Cost compression in commodity transparent stock is intensifying because Nordic supply disruptions feed directly into converter pricing. Students and amateur illustrators exhibit highest price sensitivity, while museums and archives absorb permanence-testing premiums without volume negotiation.
Supply Chain Analysis
Regional distribution centers in Hamburg and Yokohama anchor hub-and-spoke patterns serving European and East Asian architectural networks. Supply concentrates in Japan, South Korea, and Germany through integrated pulp-to-paper operations that limit alternative sourcing during logistics disruptions. Raw material dependencies draw from Nordic hardwood fiber, bio-aldehyde coating chemistry, and cellulose nanofibril additives. Single-source vulnerability in beating technician skills concentrated in aging European and Japanese workforces threatens specialty grade continuity. Distribution runs through wholesale merchants facing compression as multi-office networks negotiate direct mill agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
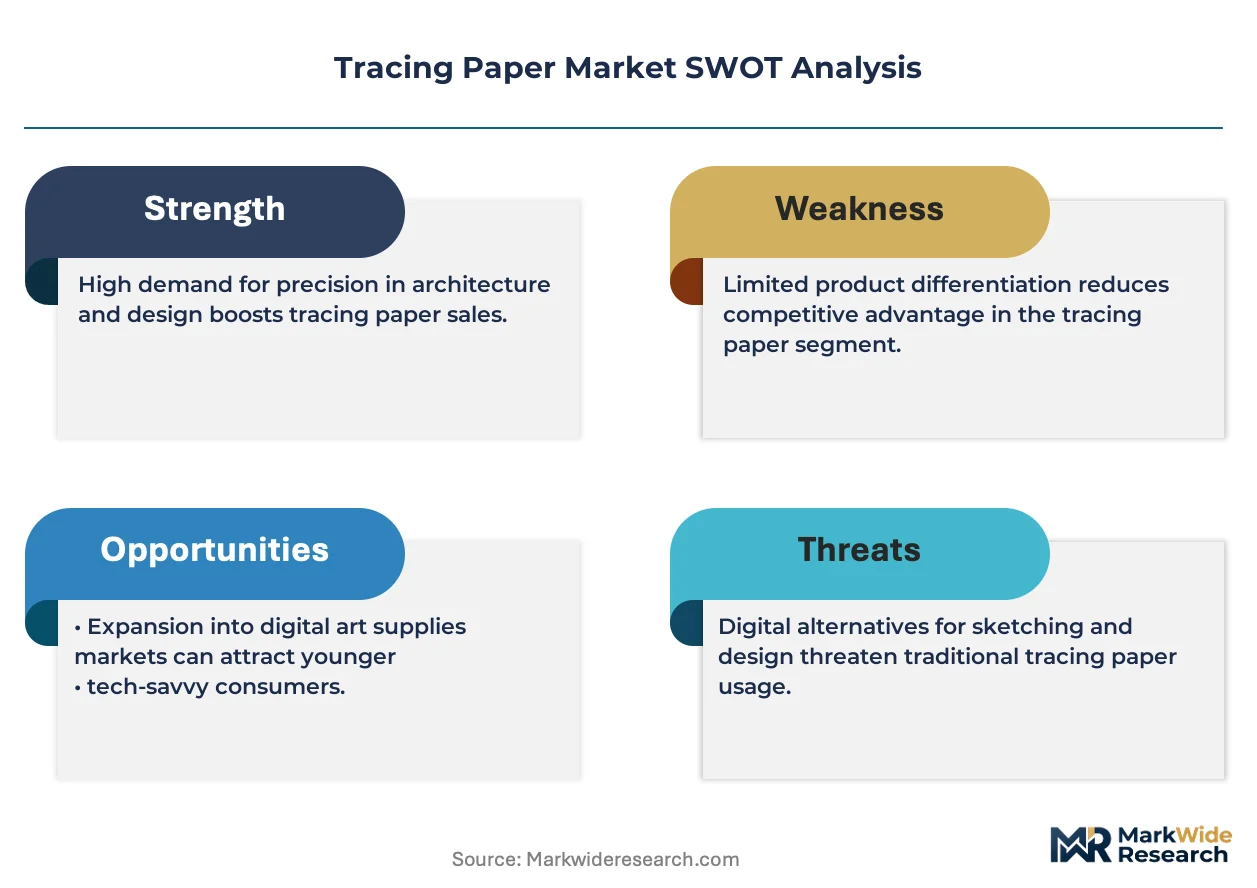
Tracing paper sits in a technology-transition phase as Wacom and Apple stylus systems displace preliminary sketch phases previously executed on translucent substrates. This substitution pressure forces strategic recalibration across incumbent mills, new entrants, and capital allocators.
For Market Incumbents: Anticipate coating reformulation deadlines by accelerating bio-aldehyde crosslinker R&D ahead of ECHA compliance timelines. Defensive consolidation through captive pulp supply agreements in Nordic regions mitigates hardwood fiber volatility exposure. Certification investment in ISO 9706 permanence testing extends product development cycles but locks in archival-grade margin pools against digital tablet substitution.
For New Entrants and Emerging Players: Launch via specialized e-commerce portals aggregating dispersed freelance illustrator demand without volume minimums. India's PLI scheme technical education procurement represents the most penetrable white-space target, with standardized pre-printed template demand scaling through institutional channels. Direct-to-studio distribution bypassing traditional paper merchants offers the clearest go-to-market angle for independent professional aggregation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor conservation-grade specialists in Germany and Switzerland with established ISO 9706 certification infrastructure and museum network relationships. Long-term viability across the five-to-ten year window hinges on hybrid digital-manual workflow persistence in regulatory submission contexts. Watch cellulose nanofibril reinforcement adoption rates in Japanese architectural offices as the inflection indicator for premium grade substitution resistance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Supply | Captive hardwood fiber sourcing insulates margin from Baltic supply disruption volatility. |
| Bio-Aldehyde Coating Reformulation | ECHA REACH Annex XVII compliance secures European market access ahead of 2027 deadlines. |
| ISO 9706 Permanence Certification Investment | Archival-grade chemistry qualification opens Swiss and Australian museum procurement channels. |
| Direct-to-Studio E-Commerce Launch | Specialized portals aggregate freelance illustrator demand without traditional merchant markup. |
| Cellulose Nanofibril Reinforcement Scale-Up | Ultra-thin grade capability below 40 gsm captures Japanese architectural competition submissions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this tracing paper market analysis. Primary interviews with mill operations directors, architectural procurement managers, museum conservation officers, and paper merchant category buyers combined with bottom-up and top-down triangulation against ECHA chemical disclosure databases, Japanese METI industrial standards filings, and Indian PLI scheme procurement disclosures. Secondary validation drew from pulp price indices, ISO certification registries, and technical education equipment tender records.
Granularity-level modeling operated at product type, application, end user, and distribution channel dimensions with geographic disaggregation to country-level for Germany, Japan, United States, India, and Switzerland. CAGRs were derived through trend extrapolation of historical volume trajectories adjusted for regulatory phase-in schedules and technology substitution curves. Forecast inputs incorporated Building Information Modeling workflow persistence rates, REACH compliance cost pass-through elasticity, and cellulose nanofibril adoption diffusion patterns across the projection horizon.
Pulp cost volatility, ECHA enforcement intensity, and digital tablet substitution acceleration are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect documented assumptions regarding hybrid workflow persistence and regulatory submission requirements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
China Paper Packaging Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Paperboard Tray Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
GCC Paper Bags Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Paper Based Consumer Bags Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market