
 Customized E-Commerce Packaging Market | 2026-2036
Customized E-Commerce Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Customized E-Commerce Packaging Market Analysis
Direct-to-consumer fulfillment channels are reshaping how packaging is specified, procured, and branded at scale. Smurfit Kappa Group leverages its European recycled fiber network to dominate corrugated customization for fashion and electronics subscriptions. Sealed Air Corporation sustains technology leadership in automated void-fill systems that reduce dimensional weight penalties. Mondi Group anchors its position through integrated kraft paper production and on-demand print capabilities across Central European logistics hubs.
Customized e-commerce packaging comprises engineered containment and presentation systems—typically corrugated fiberboard, polyethylene mailers, or hybrid laminates between 150–400 gsm—designed to protect goods during parcel transit while delivering brand-mediated opening experiences. Cardboard segments lead in absolute volume across apparel and electronics fulfillment, though poly mailers compete aggressively on last-mile freight efficiency for soft goods. Branded and eco-friendly design complexity tiers command margin premiums as unboxing content drives customer lifetime value metrics for direct-to-consumer merchants.
The EU Green Deal, REACH chemical frameworks, and FDA food-contact standards collectively elevate material traceability and recyclability thresholds for cross-border e-commerce shipments. ECHA restrictions on per- and polyfluoroalkyl substances are forcing substrate transitions in grease-resistant food packaging applications. Stakeholders must monitor how extended producer responsibility schemes in Germany and France alter total cost of ownership calculations for plastic-intensive formats.
Market Dynamics
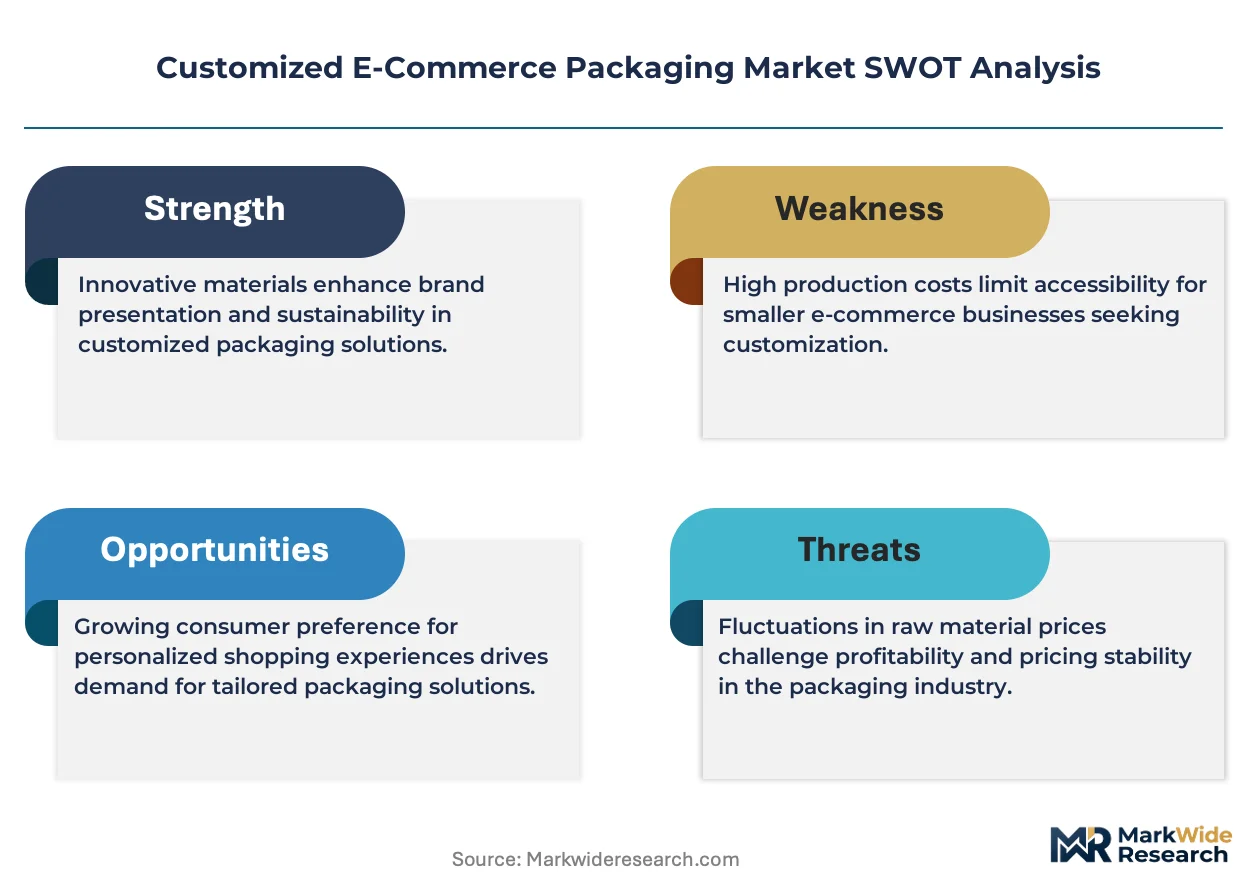
The unboxing economy is restructuring packaging procurement, with direct-to-consumer brands now specifying protective and presentational performance simultaneously rather than treating them as separate cost centers.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility schemes in Germany and France now require e-commerce merchants to finance end-of-life collection, accelerating fiber-based substrate adoption.
- Dimensional weight optimization:Parcel carriers across North America and Europe have tightened volumetric pricing thresholds, forcing merchants to specify void-fill systems that minimize shipping cube.
- Apparel unboxing content:Fashion subscription services generate social media engagement through tactile opening experiences, converting packaging from cost item to customer acquisition tool.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container prices fluctuate with municipal collection economics, compressing margin for corrugated converters serving high-volume fulfillment centers.
- Barrier coating technical limits:Current water-based grease resistance formulations fail shelf-life requirements for chilled meal kits, constraining fiber substitution in food-contact e-commerce.
- Polyethylene film substitution threat:Lightweight poly mailers retain freight cost advantages for soft goods under 500 grams, limiting cardboard penetration in fast fashion last-mile delivery.
Strategic Opportunities
- India BIS packaging standards evolution:Draft regulations for e-commerce shipment integrity create first-mover positioning for fiber-based protective systems in a plastic-dominant market.
- On-demand digital print convergence:Integration of inkjet decoration with corrugated converting lines enables lot-size-one branding without plate changeover downtime.
- Pharmaceutical cold-chain expansion:Temperature-assured subscription medications require insulated containment systems with embedded phase-change materials and brand differentiation.
Industry Challenges
- Structural design engineering scarcity:Few packaging engineers possess simultaneous expertise in finite-element crush analysis and print color management for unboxing aesthetics.
- Multi-substrate certification timelines:FDA food-contact and REACH chemical compliance testing for novel barrier coatings extends qualification cycles beyond seasonal product launch windows.
- Legacy warehouse management integration:Automated pack stations require real-time dimensional data feeds that conflict with existing ERP inventory modules in mid-market fulfillment operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customized E-Commerce Packaging Market |
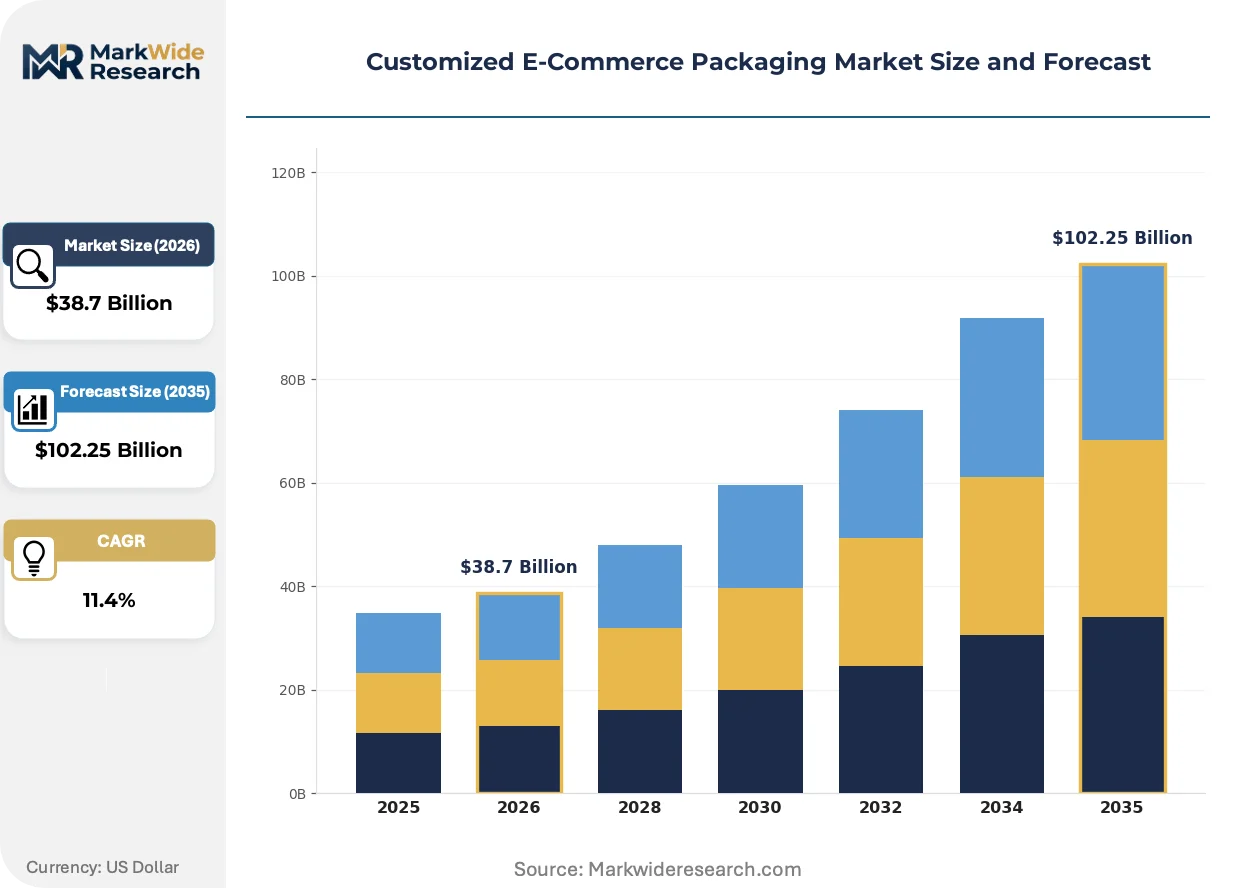
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Plastic, Poly Mailers, Bubble Wrap Packaging Style: Flat Pack, Boxed, Padded Mailers, Custom Shapes End Use: Apparel, Electronics, Beauty Products, Food Items Design Complexity: Simple, Branded, Eco-Friendly, Luxury |
| Companies Covered | Smurfit Kappa Group, Sealed Air Corporation, International Paper Company, Packaging Corporation of America, Sonoco Products Company, Amcor plc, DS Smith plc, WestRock Company, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customized E-Commerce Packaging Market Emerging Trajectories
Packaging specification is bifurcating between commodity protective performance and premium experiential layers, with technology investments concentrating at this interface.
Curbside-recyclable flexible films are migrating from multi-material laminates to mono-polyethylene structures with compatible adhesive and print chemistries. Soft goods merchants in Germany and the Netherlands are specifying these substrates to preempt EPR fee penalties. The shift is compressing demand for conventional foil-barrier pouches in non-food e-commerce applications.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from pizza box and meal kit formats. ECHA enforcement timelines have forced substrate transitions toward clay-coated or PLA-lined fiber alternatives. Food-contact e-commerce verticals in France face the most compressed compliance deadlines.
Subscription merchants are consolidating packaging specification authority from logistics procurement to brand marketing functions. This organizational shift elevates unboxing experience metrics above unit cost in supplier selection criteria. Direct-to-consumer beauty and electronics categories in the United States exhibit the most pronounced internal reorganization.
Customized E-Commerce Packaging Market Segmentation
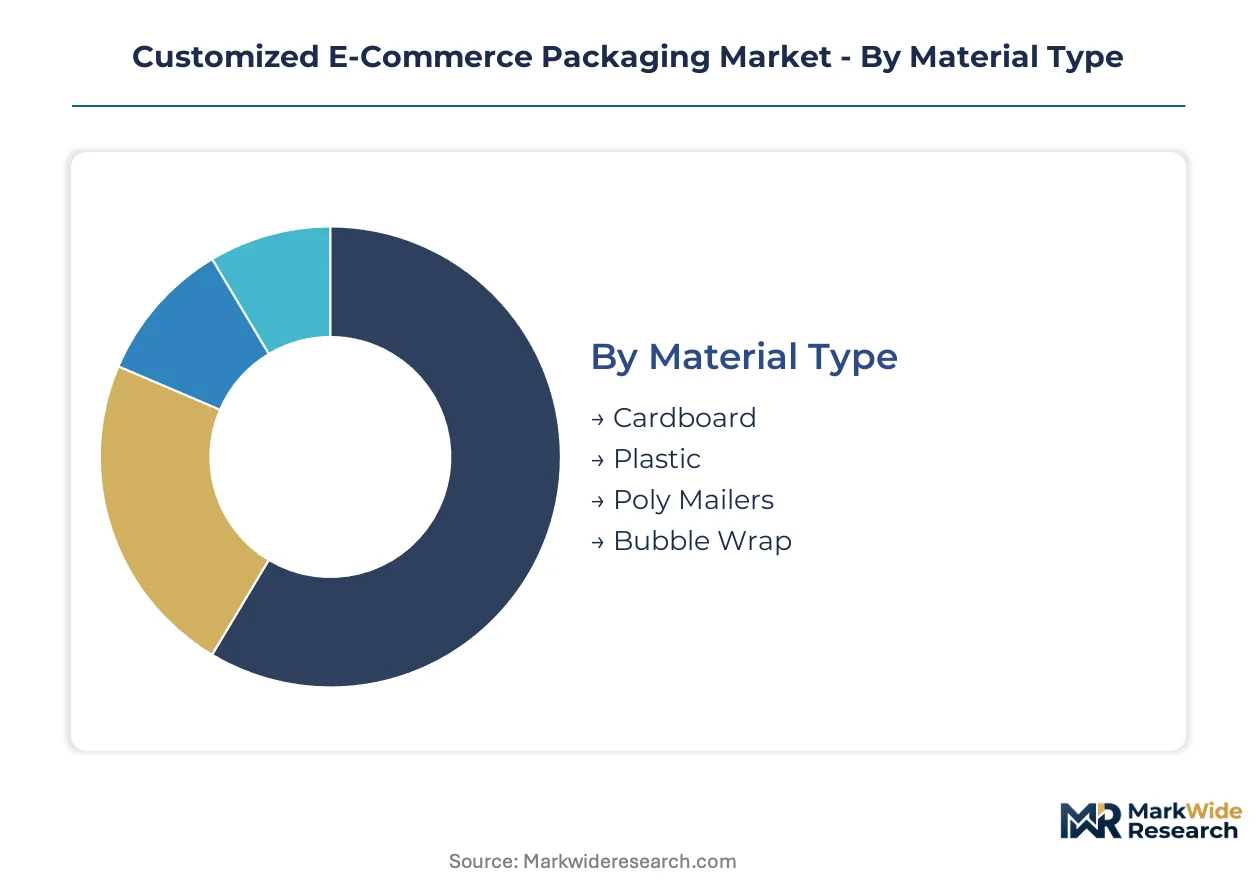
Packaging procurement decisions in customized e-commerce channels now split across material performance, brand expression, and regulatory compliance dimensions. Merchants configure specifications differently depending on whether fulfillment prioritizes freight cost, unboxing content, or circular economy mandates.
Material Type:
Corrugated fiberboard cycles through specification fastest due to volatile old corrugated container pricing and seasonal demand surges from subscription box merchants. Polyethylene formats turn over slowest, locked in by multi-year freight optimization contracts with major soft goods retailers.
- Cardboard:Engineered corrugated fiberboard between 150–400 gsm dominates protective containment for electronics and apparel subscriptions. German fulfillment centers specify this substrate most intensively under EU Green Deal extended producer responsibility financing requirements.
- Plastic:Rigid polyethylene and polypropylene formats serve reusable return systems and premium electronics unboxing. Demand concentrates in France where ANSM cosmetic packaging regulations favor pharmaceutical-grade barrier performance.
- Poly Mailers:Lightweight polyethylene film envelopes under 100 gsm optimize dimensional weight pricing for soft goods under 500 grams. Fast fashion merchants in the Netherlands specify these for cross-border EU deliveries.
- Bubble Wrap:Air-retention cushioning films and pouches protect fragile electronics and glass cosmetics during parcel transit. Demand is compressing as paper-based void-fill systems gain specification share.
Cardboard anchors the volume base while Poly Mailers gain share at the steepest rate in fast fashion last-mile channels.
Packaging Style:
Flat pack configurations concentrate procurement spend among furniture and home goods merchants seeking container utilization efficiency. Custom shaped formats command the widest margin spreads between premium beauty subscriptions and commodity protective applications.
- Flat Pack:Collapsible corrugated designs minimize shipping cube for assembled furniture and bulky home goods. IKEA-scale merchants in Sweden and Poland specify these formats for direct-to-consumer delivery.
- Boxed:Rigid six-corner containment systems protect electronics and glass cosmetics through multi-node parcel networks. German electronics subscriptions specify crush-tested double-wall constructions.
- Padded Mailers:Fiber or film envelopes with integrated bubble or foam lining protect soft goods and small electronics. US beauty merchants favor these for sample subscription programs.
- Custom Shapes:Die-cut and scored fiberboard engineered to product dimensions eliminates void-fill requirements. Premium watch and jewelry merchants in Switzerland specify these for experiential unboxing.
Boxed formats dominate absolute procurement value while Custom Shapes expand most quickly in premium direct-to-consumer verticals.
End Use:
Apparel fulfillment drives the highest specification velocity as seasonal collections force quarterly packaging redesigns. Food e-commerce faces the slowest turnover due to FDA and EFSA compliance testing timelines for novel barrier substrates.
- Apparel:Soft goods fulfillment requires tear-resistant containment with tactile surface finishes for unboxing content generation. Fashion subscription services in Germany and France specify branded poly mailers and rigid mailers simultaneously.
- Electronics:Fragile device protection demands engineered crush resistance combined with anti-static and moisture barrier properties. Smartphone and laptop merchants specify molded pulp and corrugated hybrid systems.
- Beauty Products:Cosmetic and skincare fulfillment requires contamination-resistant containment with premium surface decoration. French regulatory frameworks through ANSM elevate pharmaceutical-grade packaging specifications.
- Food Items:Meal kit and specialty food e-commerce requires grease-resistant and temperature-assured barrier performance. ECHA PFAS restrictions are forcing substrate transitions toward clay-coated fiber alternatives.
Apparel anchors procurement volume while Food Items climb the fastest as chilled subscription meal kits expand across European markets.
Design Complexity:
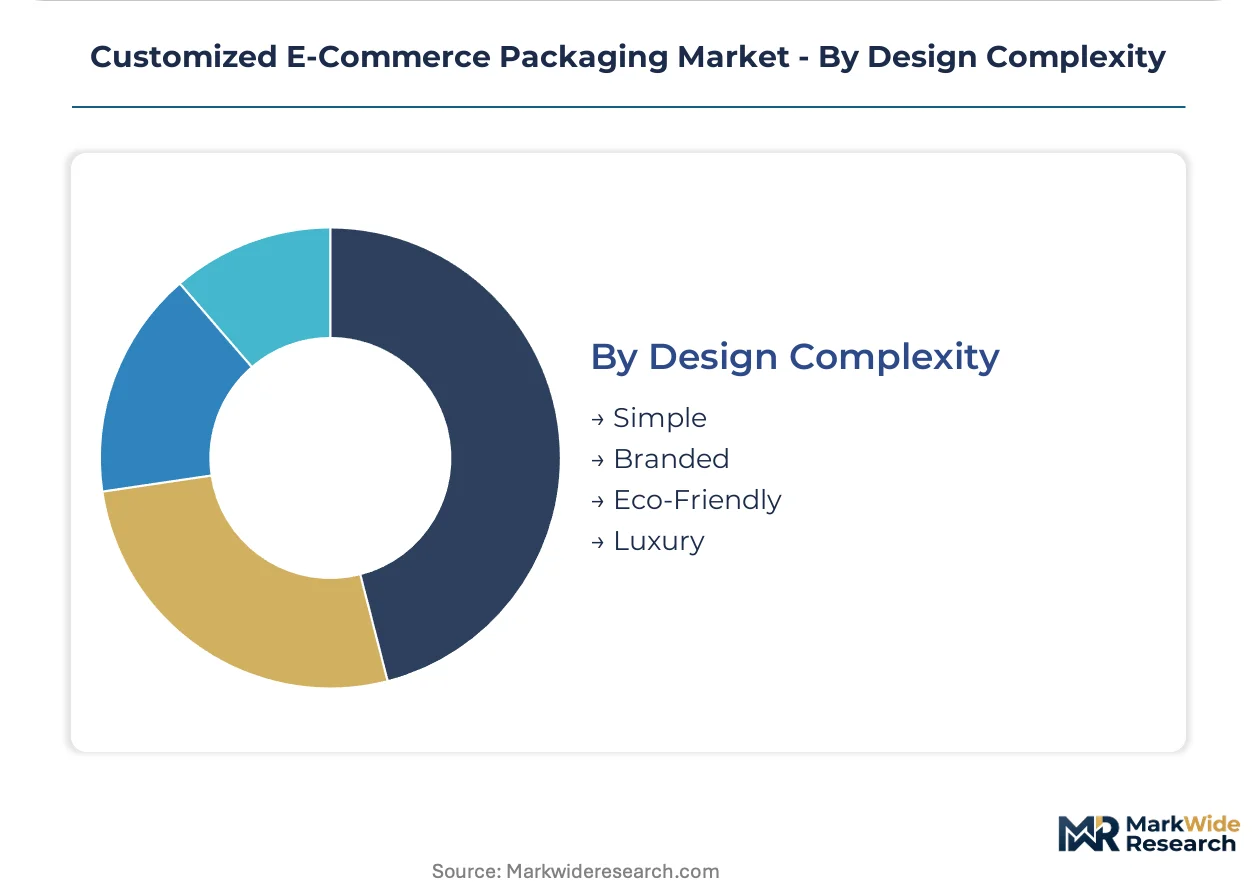
Simple protective specifications concentrate among cost-optimized marketplace sellers. Luxury tier packaging commands the steepest engineering and print technology investments for experiential differentiation.
- Simple:Unprinted kraft or standard white corrugated optimized purely for protective performance at lowest unit cost. Marketplace merchants and clearance retailers specify these formats exclusively.
- Branded:Flexographic or digital print decoration integrating logos, color fields, and opening instructions. Direct-to-consumer merchants in the United States specify these for customer acquisition metrics.
- Eco-Friendly:Curbside-recyclable mono-material designs with water-based inks and adhesive systems. German and Dutch merchants specify these to preempt EPR fee penalties under EU Green Deal frameworks.
- Luxury:Multi-layer presentation systems combining rigid boxes, tissue, ribbon, and printed collateral for experiential unboxing. Premium beauty and jewelry subscriptions command these specifications.
Branded designs anchor current procurement volume while Eco-Friendly specifications gain share fastest under tightening extended producer responsibility schemes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA regulations on per- and polyfluoroalkyl substances and extended producer responsibility frameworks are concentrating packaging specification authority in European fulfillment centers. Supply-side investment clusters around recycled fiber networks and digital print conversion infrastructure.
Germany
Apparel subscription services and electronics direct-to-consumer brands drive fiber-based packaging procurement. The EU Green Deal extended producer responsibility scheme requires merchants to finance end-of-life collection, accelerating corrugated substitution. The Ruhr logistics corridor hosts automated pack stations integrating real-time dimensional optimization.
United States
FDA food-contact compliance timelines and beauty subscription unboxing content generation elevate specification complexity. Dimensional weight pricing reforms by parcel carriers force void-fill system upgrades. The Chicago-Memphis freight corridor concentrates corrugated converting capacity for mid-market fulfillment operations.
France
ANSM cosmetic packaging regulations and ECHA PFAS enforcement deadlines compress substrate qualification cycles. Meal kit merchants transition toward clay-coated fiber alternatives for grease resistance. The Lyon logistics cluster specializes in pharmaceutical-grade cold-chain packaging with embedded phase-change materials.
India
Draft BIS e-commerce shipment integrity standards create positioning opportunities for fiber-based protective systems. Plastic-dominant fast fashion last-mile channels face regulatory pressure. The Mumbai-Pune industrial corridor attracts investment in on-demand digital print integration with corrugated converting lines.
Netherlands
Cross-border EU delivery optimization and curbside-recyclable mono-polyethylene film adoption preempt EPR fee penalties. Soft goods merchants specify lightweight mailers for dimensional weight efficiency. The Rotterdam-Antwerp port cluster handles imported substrate volumes for Central European fulfillment networks.
Customized E-Commerce Packaging Market Vendor Landscape
Integrated fiber producers and specialized protective systems providers split the market along substrate expertise lines. Concentration is moderate, with top-tier players controlling recycled fiber networks and automated converting infrastructure while mid-tier converters compete on lot-size flexibility. European corrugated specialists and North American containerboard giants represent the dominant archetypes, with Asian flexible film manufacturers emerging at the cost-optimized fringe. Competitive dynamics center on backward integration into recycled pulp supply and geographic expansion of on-demand digital print capabilities.
Among European-based integrated producers, Smurfit Kappa Group, DS Smith plc, and Mondi Group exemplify the fiber-network archetype, leveraging captive recycled containerboard supply and regional logistics hub proximity to serve fashion and electronics subscription merchants. These entities occupy positions where EU Green Deal compliance requirements and extended producer responsibility financing create structural advantages for curbside-recyclable substrate formats. Their geographic concentration in Central European industrial corridors aligns with the most stringent regulatory enforcement timelines.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Sealed Air Corporation |
| International Paper Company |
| Packaging Corporation of America |
| Sonoco Products Company |
| Amcor plc |
| DS Smith plc |
| WestRock Company |
| Mondi Group |
| Others |
Supply Flow & Price Mechanics
Old corrugated container supply concentration in Germany and France funnels margin pools toward integrated fiber producers with captive pulp networks, while fragmented converters downstream absorb recycled fiber cost volatility without pricing power.
Pricing Analysis
German fulfillment centers command 15-20% premiums over Southern European equivalents for identical corrugated specifications due to EPR compliance bundling and logistics proximity. Three-tier pricing structure across luxury unboxing, branded mid-tier, and unprinted protective levels stratifies procurement decisions, with certification grade under EU Green Deal frameworks serving as the primary wedge. Cost compression in commodity corrugated runs through volatile OCC index movements and seasonal subscription box demand spikes. Marketplace merchants exhibit extreme price sensitivity, whereas premium beauty subscriptions absorb 40-50% unit cost premiums for experiential layers.
Supply Chain Analysis
Recycled pulp feedstock draws from municipal collection networks concentrated in Germany, France, and the Netherlands, with quality variation forcing blend optimization at the mill level. Kraft linerboard, clay-coated recycled board, and water-based barrier coatings constitute critical input dependencies. Single-source vulnerability sits with German OCC collection cooperatives that supply the Ruhr corridor converting cluster. Distribution runs through automated pack stations at fulfillment hubs, with real-time dimensional data integration determining downstream logistics efficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural advantage in this market accrues to players commanding both structural design engineering talent and digital print conversion infrastructure, yet fewer than twelve European facilities possess integrated capability across both domains.
For Market Incumbents: Pre-empt poly mailer substitution in fast fashion channels by acquiring on-demand digital print capabilities in the Mumbai-Pune corridor, where BIS regulatory evolution favors fiber-based positioning. Defend margin pools through backward integration into OCC collection networks, locking supply security against municipal pricing volatility. Capacity addition in Central European logistics hubs reinforces proximity advantages under tightening EPR enforcement timelines. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical cold-chain packaging, where temperature-assured subscription medications demand insulated containment systems with embedded phase-change materials and limited incumbent expertise. Target the Lyon logistics cluster for pharmaceutical-grade barrier coating qualification under ANSM frameworks. Go-to-market leverage rests on phase-change material sourcing partnerships with specialty chemical suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed corrugated converters in Poland and the Czech Republic lacking digital print integration but holding established fashion subscription relationships. Long-term viability hinges on fiber substitution momentum outlasting poly mailer freight optimization in cross-border EU channels. Watch ECHA PFAS enforcement acceleration in France as the signal indicating substrate transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | Captive pulp supply secures margin against German municipal pricing volatility. |
| On-Demand Digital Print Convergence | Inkjet decoration integration enables lot-size-one branding without plate downtime. |
| Pharmaceutical Cold-Chain Expansion | Temperature-assured systems with phase-change materials address ANSM compliance. |
| Curbside-Recyclable Mono-Material Transition | Mono-polyethylene structures preempt EPR fee penalties in Dutch fulfillment. |
| Barrier Coating R&D Investment | Water-based grease resistance R&D unlocks fiber substitution in French meal kits. |
Methodological Framework
Desk research of trade association filings, customs records, and EU regulatory databases preceded structured interviews with corrugated plant managers, fashion subscription procurement leads, and logistics hub operators. Primary fieldwork with fulfillment center engineers and digital print conversion specialists was cross-validated against secondary sources including ECHA restriction timelines and BIS draft standard consultations. Bottom-up volume modeling triangulated against top-down packaging spend estimates across the analysis window.
Assumptions held EU Green Deal EPR enforcement timelines and parcel carrier dimensional weight pricing structures fixed, while OCC index volatility and fast fashion penetration rates were stress-tested across scenarios. Segmentation dimensions spanned material type, packaging style, end-use vertical, and design complexity tier. CAGRs were derived from segment-level volume trajectories and value-per-unit escalation patterns, with pharmaceutical cold-chain and meal kit subscription expansion serving as industry-specific demand inputs.
Stress conditions across recycled fiber input costs, ECHA PFAS enforcement acceleration, and India BIS regulatory finalization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding substitution elasticity between fiber and polyethylene formats. Cross-checking against customs trade data for containerboard and flexible film import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Holographic Foils Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market