
 Kraft Paper Shopping Bag Market | 2026-2036
Kraft Paper Shopping Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Paper Shopping Bag Market Foresight
Custom print-on-demand services is recalibrating how bag producers monetize relationships beyond unit sales. WestRock Company leverages its North American mill network to anchor virgin and recycled fiber supply for retail clients. Mondi Group competes through integrated pulp-to-bag operations across European packaging corridors. Smurfit Kappa specializes in high-volume merchandise formats with in-line flexographic printing capacity.
Kraft paper shopping bags are unbleached paper containers manufactured from sulfate pulp, typically ranging from 40 to 120 grams per square meter in basis weight, designed for consumer goods transport and brand display. The bags derive structural integrity from cross-direction fiber orientation and reinforced bottom paste adhesion, permitting load-bearing capacity from two to twenty kilograms depending on ply configuration. Die-cut handle variants now lead volume share in grocery and retail channels where ergonomic carrying overrides premium aesthetics. E-commerce end-use represents the fastest-expanding segment as corrugated insert compatibility and tear-resistant grammages become fulfillment prerequisites. Merchandise bags with fold-over closures command margin concentration in gift and specialty retail where brand embellishment justifies unit price premiums.
The EU F-Gas Regulation and REACH chemical compliance frameworks govern adhesive and ink formulations used in European kraft bag production, while FDA food-contact substance notifications apply to US grocery-facing formats. Germany's national packaging ordinance, implementing extended producer responsibility, directly shapes demand for certified recyclable kraft constructions. Stakeholders must monitor evolving state-level plastic bans in India and Brazil as these jurisdictions accelerate paper substitution timelines without harmonized testing protocols.
Market Dynamics
The EU single-use plastics directive is compressing substitution timelines across European retail supply chains, forcing grocery and fashion sectors to convert carrier bag specifications from polymer to unbleached kraft constructions ahead of phased enforcement deadlines.
Growth Catalysts
- E-commerce fulfillment mandates:Corrugated insert compatibility requirements from Amazon, Zalando, and Otto Group are pulling tear-resistant kraft grammages into warehouse logistics specifications.
- REACH chemical compliance:Adhesive and ink reformulation under ECHA guidelines is certifying European-produced bags for food-contact and retail applications, unlocking grocery channel access.
- German packaging ordinance implementation:Extended producer responsibility frameworks are mandating certified recyclable constructions, concentrating demand for FSC-chain-of-custody verified supply.
Market Restraints
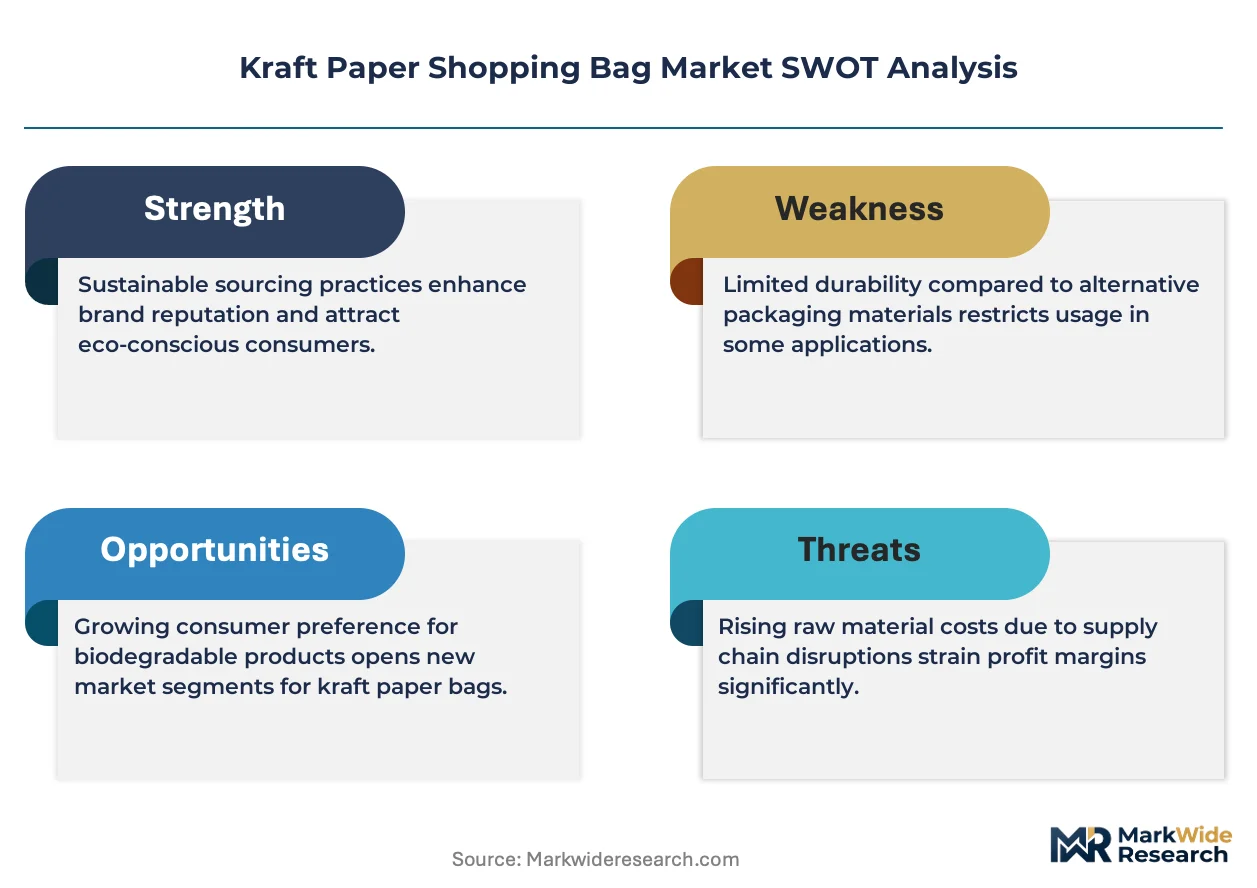
- Pulp cost volatility:Softwood fiber pricing swings in Nordic and Baltic supply basins compress margin predictability for converters operating on fixed retail contracts.
- Mill concentration risk:European kraftliner capacity clusters in Sweden and Finland, creating single-source vulnerability for bag producers without multi-continent fiber agreements.
- Polypropylene woven substitution:Reusable plastic carriers with 50+ use cycles are capturing price-sensitive grocery segments in Eastern European markets with deferred plastics enforcement.
Strategic Opportunities
- Indian state-level plastic bans:Maharashtra, Tamil Nadu, and Karnataka are accelerating paper substitution without harmonized testing protocols, creating first-mover certification advantages for compliant exporters.
- Smart packaging convergence:NFC-enabled kraft bags integrating traceability chips with QR-printed flexography are opening premium brand authentication channels in cosmetics and spirits.
- Direct-to-consumer brand packaging:Subscription box services are specifying custom die-cut handle formats with interior tissue lining, displacing generic wholesale merchandise bags.
Industry Challenges
- Flexographic color-matching expertise:Short-run custom print orders require prepress technicians capable of Pantone-accurate water-based ink formulation, a skill scarce outside established European packaging corridors.
- FSC chain-of-custody audit timelines:Certification body backlogs are extending compliance verification from 12 to 18 months, delaying market access for new mill entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Paper Shopping Bag Market |
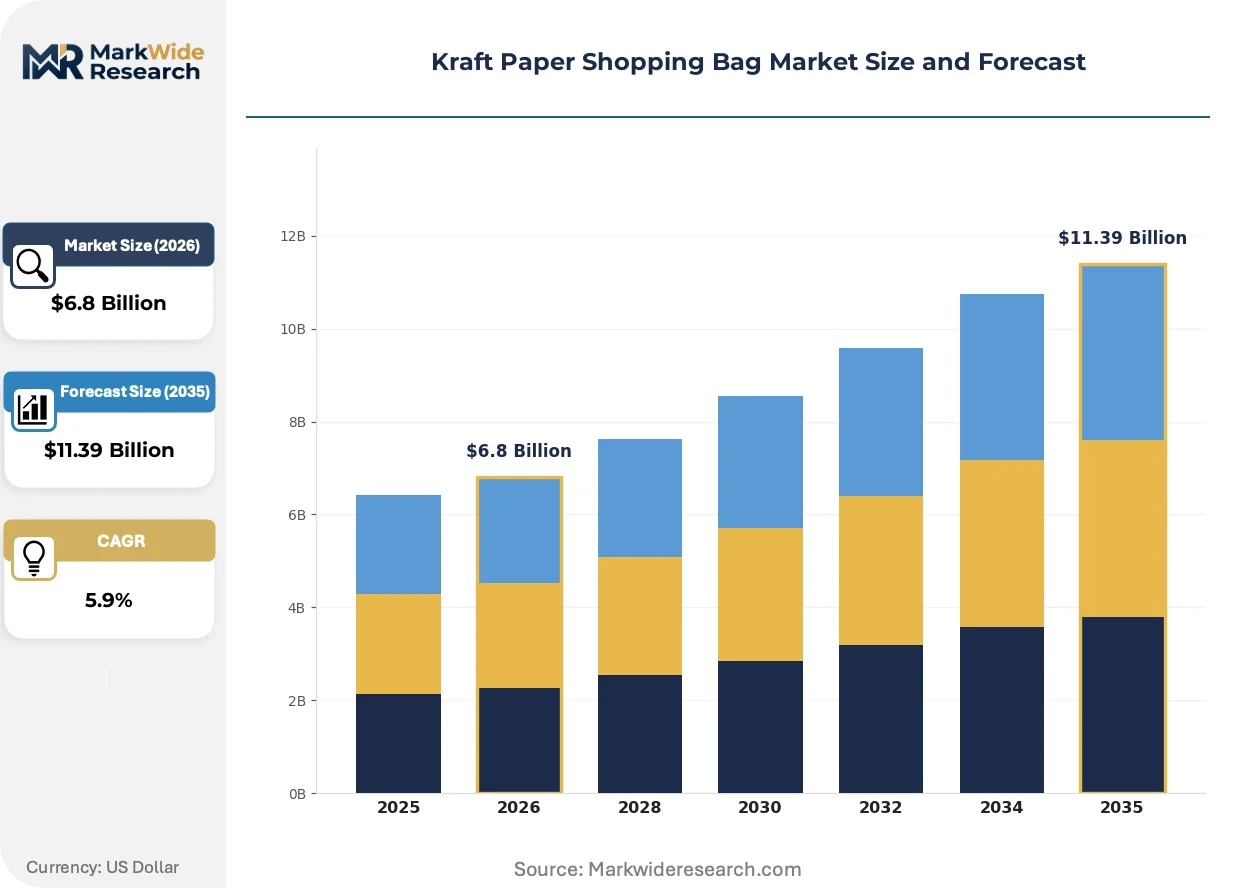
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bag Type: Flat, Stand-Up, Die-Cut, Merchandise Closure Type: Tie, Tape, Twist Tie, Fold-Over End User: Retail Stores, Grocery Outlets, Gift Shops, E-commerce Weight Capacity: Lightweight, Medium, Heavyweight, Bulk |
| Companies Covered | WestRock Company, HEMCBags, Mondi Group, Shamrock Kraft Bags, Georgia-Pacific LLC, Smurfit Kappa, Novolex, Bagitan Packaging, International Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Paper Shopping Bag Market Shifts & Advancements
Active material science breakthroughs and regulatory enforcement mechanics are compressing specification cycles for kraft bag producers, collapsing the traditional multi-year design-to-shelf timeline into quarterly refresh mandates.
Water-based barrier coatings derived from chitosan and alginate biopolymers are rewriting moisture-resistance standards for frozen food and chilled grocery applications. German discount chains Aldi and Lidl are piloting these formulations in private-label carrier programs. The technology is rewriting competitive positioning by eliminating polyethylene laminate layers previously required for wet-strength performance.
EU F-Gas Regulation phase-down schedules are restricting fluorinated greenhouse gas use in pulp mill processes, indirectly tightening kraftliner supply availability. This industrial consequence is accelerating capital deployment into sulfur-free pulping alternatives. Nordic producers are most affected, with Stora Enso and BillerudKorsnäs restructuring energy recovery systems to maintain output under tightened emission budgets.
Brand procurement teams are consolidating carrier bag specifications across continental retail footprints, collapsing previously fragmented national buying into centralized category management. Pan-European fashion retailers are replacing country-specific suppliers with single-source partners capable of multi-language print versioning. This consolidation is most visible in Germany, where Zara, H&M, and Primark have unified bag specifications across DACH-region operations under shared sustainability scorecards.
Kraft Paper Shopping Bag Market Segmentation
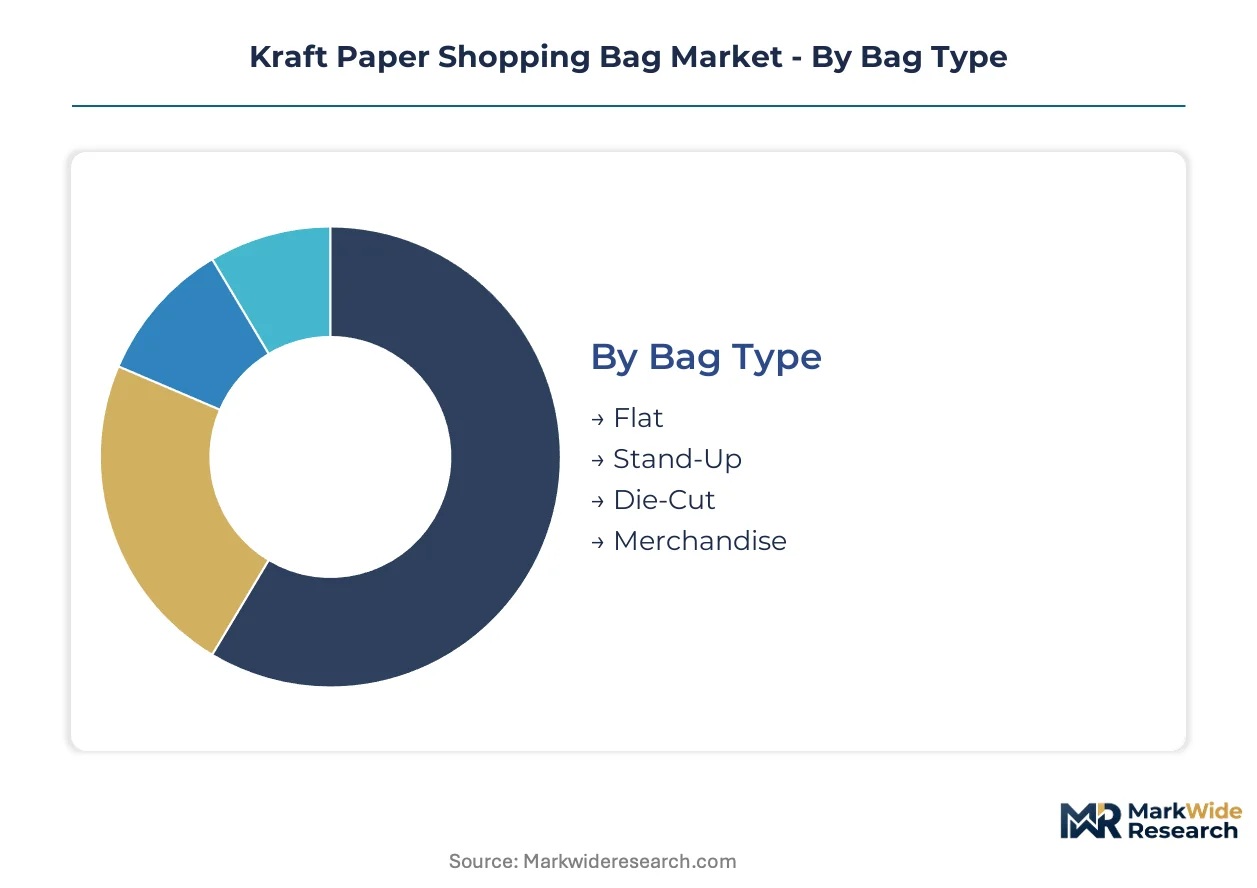
Bag specification diversity in the Kraft Paper Shopping Bag Market reflects divergent capital requirements across converting equipment, fiber sourcing, and print finishing capabilities. Segment selection directly determines mill scale, die-cutting investment thresholds, and compliance certification scope.
Bag Type:
Capital intensity peaks with stand-up formats requiring specialized bottom-forming machinery and multi-ply adhesion systems, while flat bags demand minimal converting infrastructure.
- Flat:Single-ply constructions with gusseted or non-gusseted sidewalls dominate high-volume grocery and fast-food takeaway channels. German discount chains Aldi and Lidl specify flat formats with reinforced bottom paste for cost-optimized carrier programs under national packaging ordinance compliance.
- Stand-Up:Box-bottom constructions with integrated base panels require rotary die-cutting and automatic bottom-folder equipment. Demand concentrates in premium cosmetics and spirits retail where shelf-display functionality justifies higher unit costs; French luxury houses specify these for boutique packaging.
- Die-Cut:Ergonomic handle apertures punched directly into bag bodies. Swedish pulp-to-bag converters deploy in-line flexographic printing for fashion retail clients across the DACH region.
- Merchandise:Rope or ribbon handle variants with reinforced header cards. Gift shops in Bavaria and North Rhine-Westphalia favor these for seasonal packaging programs.
Most installed capacity flows through flat formats. Expansion is steepest in die-cut configurations.
Closure Type:
Closure specification drives adhesive chemistry investment and food-contact certification pathways, with tape and fold-over formats requiring the most sophisticated barrier coating R&D.
- Tie:Pre-attached paper or fabric ribbons knotted by consumers. Italian specialty food retailers specify tie closures for gourmet gift packaging under EFSA food-contact guidelines.
- Tape:Pressure-sensitive adhesive strips with release liners. E-commerce fulfillment centers in the Netherlands require tape closures for automated packing line compatibility; REACH-compliant acrylic formulations dominate.
- Twist Tie:Metallic or paper-wrapped wire fasteners. Bakery and fresh produce applications in Belgium favor these for resealable functionality.
- Fold-Over:Extended top flaps with tuck-in or adhesive seals. Cosmetics subscription services in Hamburg and Munich specify fold-over formats with interior tissue lining for unboxing experience differentiation.
Fold-over formats command margin premiums. Tape closures are gaining share fastest in warehouse logistics.
End User:
Customer type determines volume predictability, print customization depth, and sustainability audit intensity, with e-commerce presenting the most demanding corrugated-insert compatibility requirements.
- Retail Stores:Fashion and department stores specifying multi-language print versioning across pan-European footprints. Zara and H&M have unified bag specifications across DACH-region operations under shared sustainability scorecards.
- Grocery Outlets:High-frequency, low-margin procurement with extended producer responsibility compliance mandatory under German packaging ordinance. Unbleached kraft with FSC chain-of-custody verification dominates.
- Gift Shops:Short-run custom print orders with Pantone-accurate water-based ink requirements. Prepress technician scarcity outside established European packaging corridors constrains supplier selection.
- E-commerce:Tear-resistant grammages with corrugated insert compatibility. Amazon, Zalando, and Otto Group warehouse specifications are pulling 90-120 gsm constructions into fulfillment logistics.
Grocery outlets absorb the highest absolute tonnage. E-commerce represents the fastest-expanding demand channel.
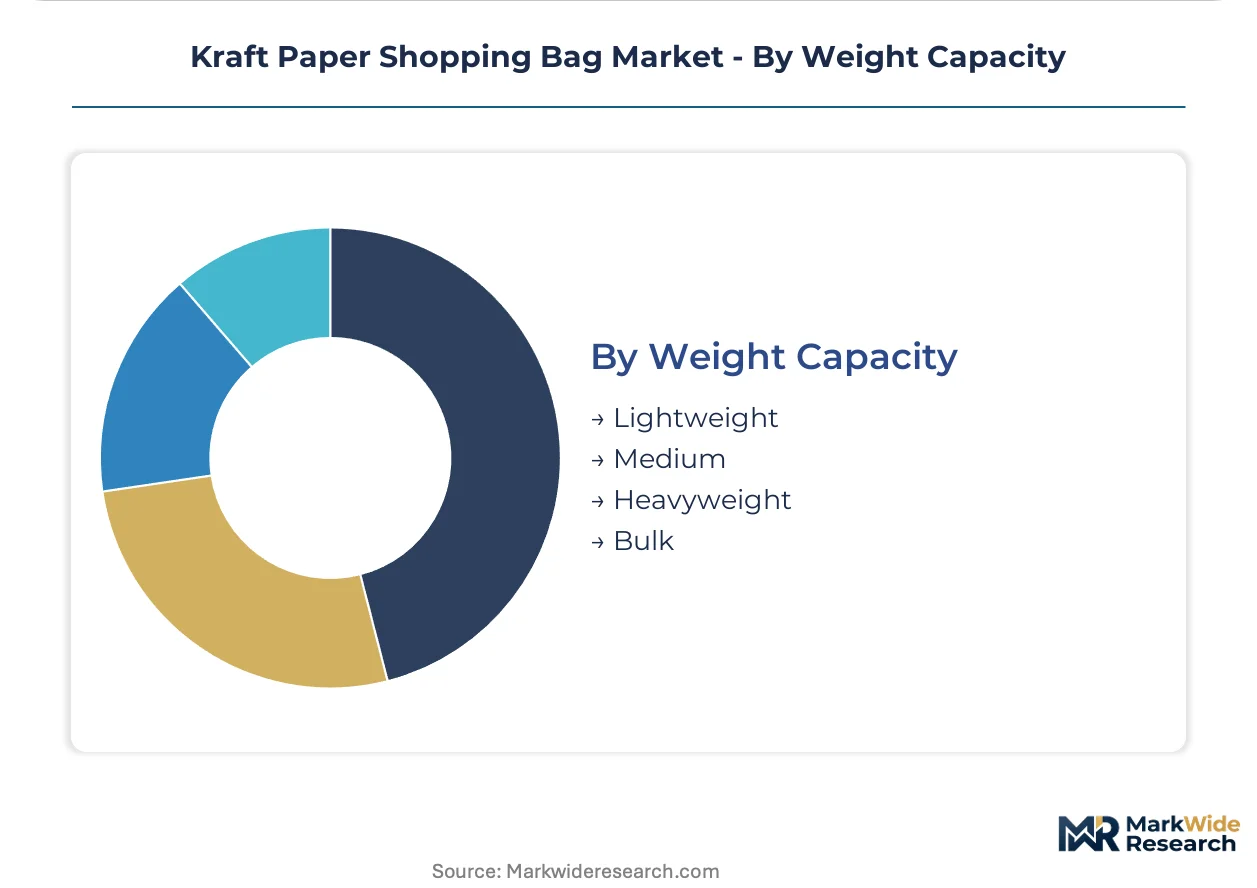
Weight Capacity:
Load-bearing specification dictates ply count, fiber blend ratios, and bottom reinforcement chemistry, with heavyweight and bulk formats requiring the most capital-intensive multi-ply laminating equipment.
- Lightweight:Single-ply 40-60 gsm constructions for apparel and accessories. Fast-fashion retailers in Poland and Czech Republic specify these for price-sensitive carrier programs.
- Medium:70-90 gsm with reinforced bottom paste for standard retail merchandise. Supermarket chains across Austria and Switzerland standardize on medium capacity for checkout lane distribution.
- Heavyweight:100-120 gsm multi-ply configurations with cross-direction fiber orientation. DIY and home improvement retailers in Germany require these for paint and hardware transport.
- Bulk:120+ gsm with die-cut handles and bottom board inserts. Industrial supply distributors in the Nordic region specify bulk formats for catalog order fulfillment.
Medium capacity accounts for the largest installed equipment base. Heavyweight specifications are climbing the fastest as e-commerce load requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in kraft bag consumption intensity per retail square meter, while India accelerates faster than any European market on the back of state-level plastic prohibitions. National regulatory frameworks now determine substitution velocity more than consumer preference.
Germany
Aldi and Lidl mandate unbleached kraft carriers across private-label programs, displacing polymer alternatives ahead of EU enforcement deadlines. The national packaging ordinance imposes extended producer responsibility on all retail bag formats. Düsseldorf and Hamburg host the densest converter clusters, where FSC chain-of-custody certification has become a baseline procurement requirement.
United States
Amazon fulfillment centers specify tear-resistant grammages for corrugated insert compatibility, pulling heavyweight constructions into warehouse logistics. FDA food-contact substance notifications govern grocery-facing formats. Wisconsin and Georgia mill networks anchor virgin and recycled fiber supply for retail clients operating under state-level plastic ban variability.
India
Maharashtra, Tamil Nadu, and Karnataka enforce paper substitution without harmonized testing protocols, creating certification arbitrage for compliant exporters. The Bureau of Indian Standards (BIS) develops packaging material guidelines amid regulatory fragmentation. Mumbai and Chennai industrial corridors attract first-mover capacity for FSC-verified supply.
Netherlands
Zalando and Otto Group warehouse specifications standardize tape-closure formats for automated packing line compatibility. REACH-compliant adhesive formulations dominate procurement criteria under ECHA guidelines. Rotterdam logistics hubs concentrate converter capacity serving pan-European e-commerce distribution.
Sweden
Stora Enso and BillerudKorsnäs restructure energy recovery systems to maintain kraftliner output under EU F-Gas Regulation phase-down schedules. Nordic softwood fiber pricing volatility compresses margin predictability for dependent converters. Gothenburg and Stockholm mill complexes face emission budget constraints tightening supply availability.
Kraft Paper Shopping Bag Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pulp-to-bag operators commanding premium positioning against regional converters. The vendor base concentrates around three strategic archetypes: captive fiber owners with mill networks, standalone converters with flexographic specialization, and private-label contractors serving retail procurement consolidation. Dominant competitive moves include backward integration into pulp supply and geographic expansion through distribution partnerships.
Among North American integrated producers, WestRock Company and Georgia-Pacific LLC exemplify captive fiber strategies, while Mondi Group anchors European pulp-to-bag operations across packaging corridors. Smurfit Kappa occupies a position within high-volume merchandise formats, representing the flexographic specialization archetype.
| Leading Market Players |
|---|
| WestRock Company |
| HEMCBags |
| Mondi Group |
| Shamrock Kraft Bags |
| Georgia-Pacific LLC |
| Smurfit Kappa |
| Novolex |
| Bagitan Packaging |
| International Paper |
| Others |
Supply & Pricing Matrix
Pan-European fashion retailers and German grocery chains command pricing power through consolidated procurement volumes, compressing margin structures for converters without FSC-certified fiber access or multi-country print versioning capabilities. Contract-based long-term offtake agreements dominate, with price floors indexed to Nordic softwood fiber futures.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade kraft bags as Maharashtra and Tamil Nadu state bans accelerate local production scale-up. Three-tier pricing structure across premium, standard, and economy levels separates FSC-chain-of-custody verified supply from generic recycled fiber and virgin pulp alternatives. Pricing pressure stems from polypropylene woven substitution in Eastern European markets with deferred plastics enforcement. Price-sensitive grocery outlets in Poland and Czech Republic drive volume, while gift shops and cosmetics subscription services show least sensitivity due to unboxing experience premiums.
Supply Chain Analysis
Returns and refurbishment flows are minimal in kraft bag logistics, with end-of-life pathways centering on municipal recycling streams rather than closed-loop recovery. Supply concentrates in Sweden, Finland, and Germany, with Nordic softwood fiber pricing volatility creating margin unpredictability. Raw material dependencies rest on sulfate pulp, water-based barrier coatings, and REACH-compliant adhesive formulations. Single-source vulnerability runs through Baltic mill concentration, with Stora Enso and BillerudKorsnäs output constrained under EU F-Gas Regulation emission budgets. Distribution runs through Rotterdam and Hamburg logistics hubs serving pan-European retail footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory premium capture and Indian state-ban acceleration, with certification compliance costs in Europe running substantially higher than unharmonized testing requirements in Maharashtra and Karnataka.
For Market Incumbents: Cement pulp-to-bag integration advantages by securing multi-continent fiber agreements that insulate against Nordic supply concentration risk. Extend FSC chain-of-custody certification depth to preempt audit timeline backlogs that delay new entrant market access. Channel control through direct relationships with Zalando and Otto Group warehouse specifications protects against price erosion from Asian converters. For New Entrants and Emerging Players: Begin with tape-closure format specialization for automated e-commerce packing lines in the Netherlands, where REACH-compliant adhesive expertise creates qualification barriers for unseasoned suppliers. Target Indian state-level plastic ban enforcement in Tamil Nadu and Karnataka, where BIS guideline fragmentation allows first-mover certification advantages. A private-label contractor model serving pan-European retail procurement consolidation offers the cleanest go-to-market path. For Investors and Strategic Acquirers: Integrated pulp-to-bag operators with captive Nordic fiber supply are the most active acquirer in this space, consolidating distressed converters facing fixed-contract margin compression. Long-term viability hinges on sulfur-free pulping technology deployment and water-based barrier coating R&D pipelines. Watch EU F-Gas Regulation phase-down schedules as the inflection signal for kraftliner supply tightening and price floor elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive Nordic fiber access insulates WestRock and Mondi Group from Baltic pricing volatility. |
| Water-Based Barrier Coating R&D | Aldi and Lidl pilot programs for chitosan formulations eliminate polyethylene laminate dependencies. |
| FSC Chain-of-Custody Certification | German packaging ordinance mandates unlock grocery channel access under extended producer responsibility. |
| Multi-Language Print Versioning Capability | Zara and H&M pan-European consolidation favors single-source partners with DACH-region coverage. |
| NFC-Enabled Smart Packaging Convergence | QR-printed flexography with traceability chips opens premium authentication in cosmetics and spirits. |
Research Methodology
Multiple input streams — mill production data, retail procurement specifications, and regulatory filing analysis — were reconciled across primary interviews with pulp procurement directors, flexographic prepress technicians, and extended producer responsibility compliance officers. Secondary validation drew from EU F-Gas Regulation submissions, ECHA REACH dossiers, German packaging ordinance implementation reports, and Bureau of Indian Standards draft guidelines. Bottom-up volume modeling by bag type, closure format, and end-use channel was cross-checked against top-down kraftliner consumption estimates from Nordic producer disclosures.
Historical capacity utilization patterns were cross-referenced against panel input from converter operations managers across DACH-region industrial corridors. Segmentation dimensions modeled included bag construction type, grammage tier, closure chemistry compliance, and geographic regulatory cluster. CAGRs were derived through regression analysis of substitution velocity against enforcement timelines. Forecast inputs incorporated e-commerce fulfillment specification evolution from Amazon and Zalando logistics teams, plus water-based coating pilot scale-up timelines from German discount chain technical departments.
Several conditions sit outside the modeled scope, including potential harmonization of Indian state-level testing protocols, acceleration of EU single-use plastics directive enforcement beyond published schedules, and breakthrough scale-up of alternative fiber sources such as agricultural residue pulp. Forecasts reflect base-case assumptions regarding Nordic mill emission budget compliance and REACH adhesive reformulation adoption curves. Periodic stress-testing of base assumptions is recommended against pulp futures volatility and polypropylene woven substitution elasticity in price-sensitive segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
GCC Paper Bags Market
Paper & Paperboard Packaging
North America Corrugated Board Packaging Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Air Fryer Paper Liners Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Disposable Paper Plates Market