
 Corrugated Pharmaceutical Packaging Market | 2026-2036
Corrugated Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Pharmaceutical Packaging Market Outlook
REACH compliance is restructuring the cost-of-entry calculus for European suppliers of pharmaceutical-grade corrugated materials. WestRock leverages its North American containerboard network to sustain high-volume output of validated pharma packaging. DS Smith competes through specialized temperature-control designs for cold-chain distribution. Mondi Group anchors its position with integrated kraft paper and converting operations across Central Europe.
Corrugated pharmaceutical packaging denotes multi-layered fiberboard structures engineered with precise burst strength, moisture resistance, and dimensional tolerances to protect drug products through distribution. Single wall and double wall configurations dominate structural specifications, with recycled fiber content rising as converters respond to sustainability mandates. Boxes and trays capture the largest volume share across the product type dimension, while inserts command premium positioning due to custom die-cutting requirements for vial and syringe protection. The vaccines application segment exhibits the fastest structural expansion, driven by stringent cold-chain integrity requirements that favor engineered corrugated with phase-change liner compatibility.
FDA validation protocols and EU Good Distribution Practice guidelines jointly shape material traceability and sterility assurance standards for pharmaceutical corrugated packaging. The EPA's evolving recycled content benchmarks and ISO 15378 quality management requirements for medicinal products further constrain supplier qualification pathways. Stakeholders must monitor regulatory divergence between US and European pharmacopeial standards as a decisive factor in regional manufacturing location strategy.
Market Dynamics
The EU F-Gas Regulation is forcing converters to abandon synthetic insulation in favor of fiber-based thermal protection, compressing margins for traditional cold-chain packaging while opening qualification pathways for engineered corrugated solutions.
Growth Catalysts
- Cold-chain biologics expansion:Vaccine manufacturers are scaling temperature-stable distribution networks that demand validated corrugated shippers with phase-change liner compatibility.
- REACH compliance restructuring:Chemical safety mandates in Europe are disqualifying incumbent coating suppliers and redirecting procurement toward fiber-based barrier technologies.
- Rhine-Main cluster concentration:Germany's integrated packaging corridor is consolidating converter capacity, creating density advantages for pharmaceutical-grade production.
Market Restraints
- Recycled fiber input volatility:OCC pricing swings and collection contamination rates are destabilizing cost structures for converters dependent on post-consumer feedstock.
- Validation timeline friction:FDA protocol requirements and EU Good Distribution Practice sterility assurance standards extend supplier qualification cycles to 18-24 months.
- Rigid plastic substitution threat:Reusable thermal containers from specialized cold-chain logistics providers are capturing high-value recurring shipments in biologics distribution.
Strategic Opportunities
- Cell and gene therapy packaging:Ultra-low temperature requirements for CAR-T therapies are creating demand for corrugated structures integrating cryogenic-rated insulation layers.
- Indian pharmaceutical export corridor:CDSCO-aligned converters in Gujarat and Maharashtra are positioning to supply temperature-controlled packaging for generic drug shipments to regulated markets.
- ISO 15378 certification acceleration:Quality management mandates for medicinal products are creating first-mover advantages for converters investing in dedicated cleanroom converting lines.
Industry Challenges
- Die-cutting precision talent scarcity:Custom vial and syringe insert production requires skilled tooling engineers that converters struggle to recruit in competitive labor markets.
- Legacy ERP integration complexity:Batch-level traceability requirements for pharmaceutical customers are forcing expensive middleware deployments to connect shop-floor systems with customer portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Pharmaceutical Packaging Market |
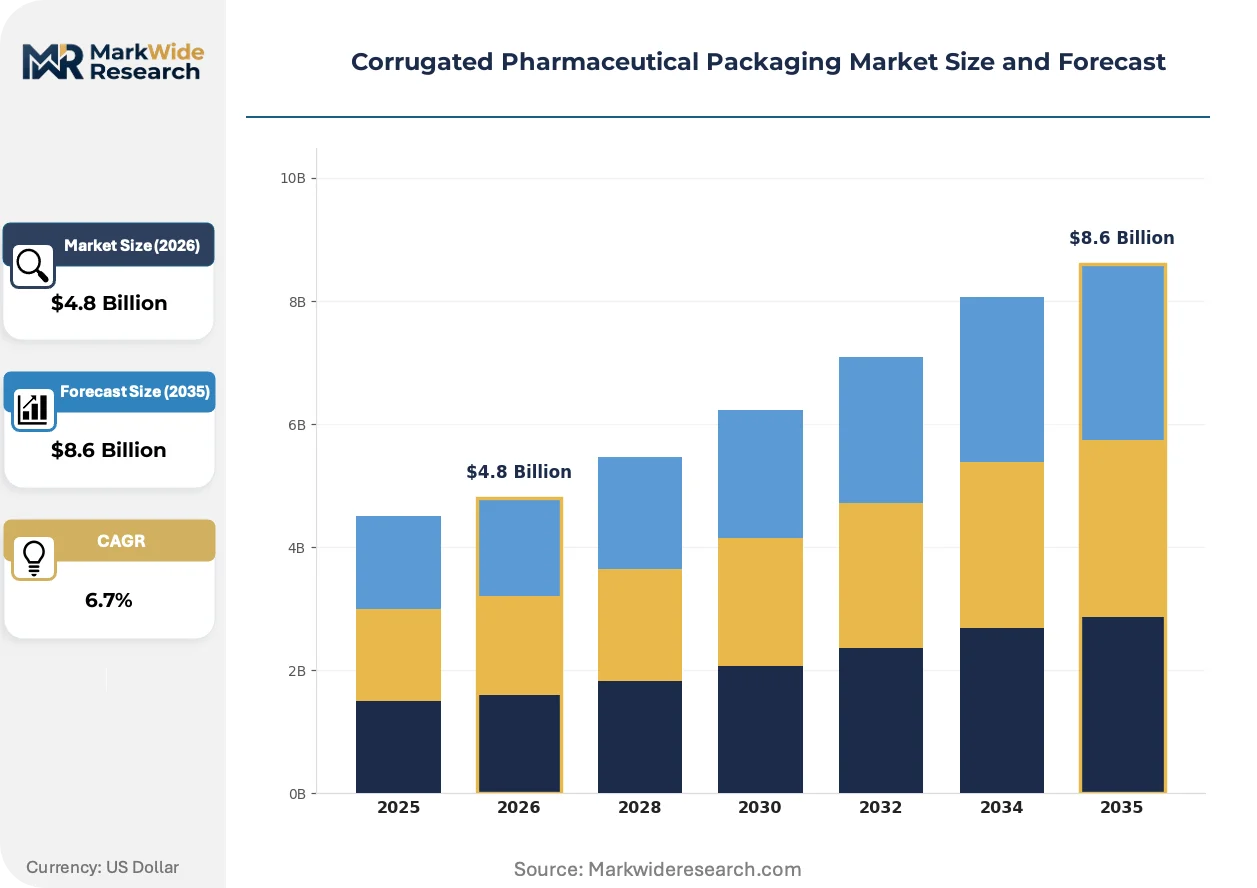
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Trays, Inserts, Pallets End User: Pharmacies, Hospitals, Clinics, Distribution Centers Material: Single Wall, Double Wall, Recycled, Virgin Fiber Application: Medicines, Vaccines, Medical Devices, Nutraceuticals |
| Companies Covered | WestRock, International Paper, DS Smith, Mondi Group, Packaging Corporation of America, Smurfit Kappa, Sonoco Products, Graphic Packaging International, Rengo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Pharmaceutical Packaging Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to reshape how corrugated packaging protects temperature-sensitive pharmaceuticals through distribution networks.
Phase-change material integration is absorbing thermal load variability in engineered corrugated shippers. Biologics distributors are specifying PCM-lined boxes for 48-96 hour ambient protection. This technology is absorbing market share from expanded polystyrene in European cold-chain lanes.
REACH Annex XVII restrictions on fluorinated substances are eliminating greaseproofing options for direct food-contact and pharmaceutical applications. Converters are responding with bio-based barrier coatings derived from plant waxes and nanocellulose. The vaccines segment is most affected, with manufacturers demanding documentation of coating chemistry for regulatory filing packages.
Consolidated buying by large pharmaceutical distributors is compressing supplier margins and accelerating qualification requirements. Regional converter networks are losing share to integrated containerboard producers with captive linerboard supply and in-house testing laboratories. This concentration is most visible in Germany, where three buying groups now control over half of corrugated pharma packaging procurement.
Corrugated Pharmaceutical Packaging Market Segmentation
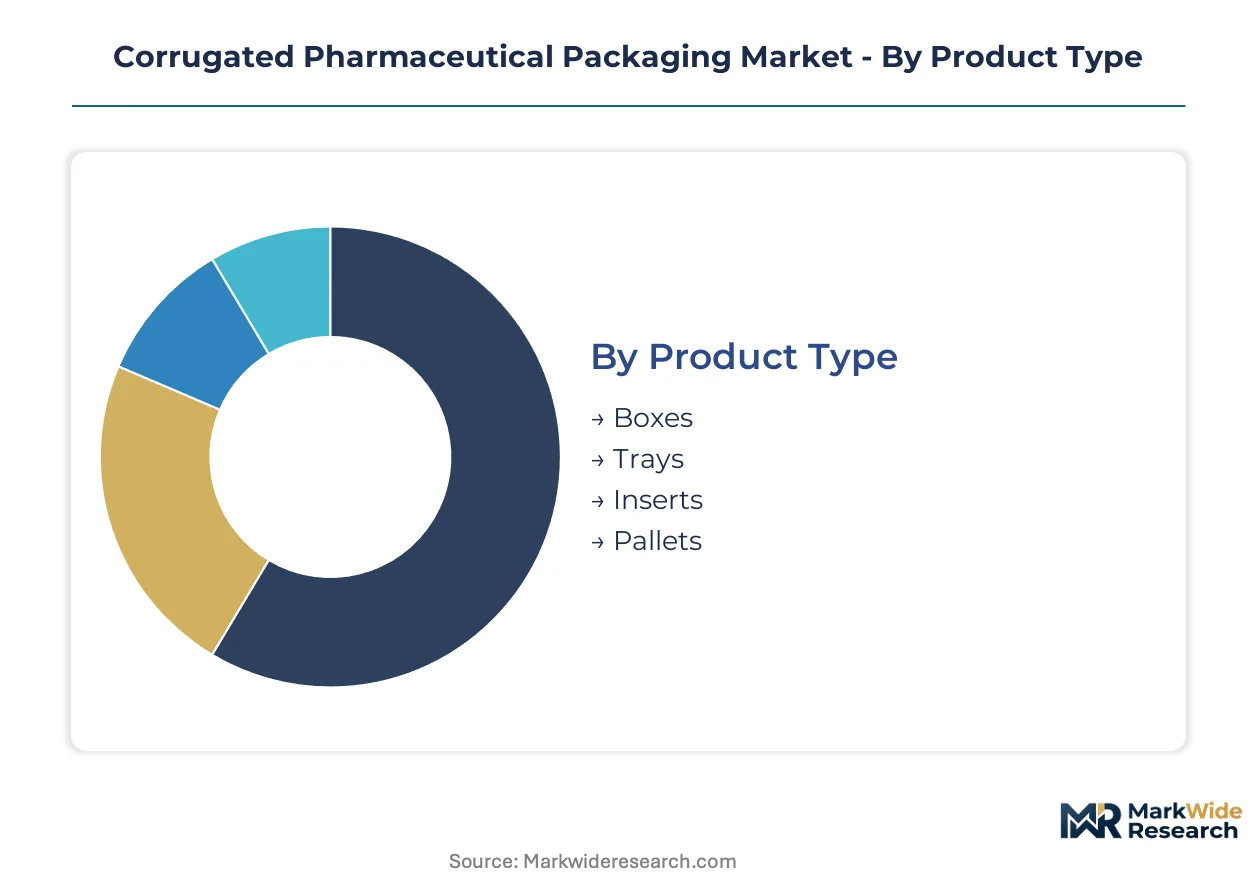
Segmentation in corrugated pharmaceutical packaging determines qualification pathways, margin structures, and regulatory exposure. Structural configuration, material composition, and end-use sterility requirements each create distinct supplier-customer matching patterns across the value chain.
Product Type:
Pharmaceutical buyers prioritize structural integrity against distribution stress and die-cutting precision for vial protection.
- Boxes:Multi-layered fiberboard enclosures with specified burst strength and moisture resistance ratings. Demand concentrates in high-volume generic drug distribution from Germany's Rhine-Main cluster, where converters integrate phase-change liner compatibility for cold-chain validation.
- Trays:Formed fiberboard platforms engineered for unit-dose organization and automated dispensing compatibility. Hospital and clinic procurement in regulated European markets drives specifications, with REACH-compliant barrier coatings now mandatory for direct product contact.
- Inserts:Custom die-cut components securing vials, syringes, and ampoules against shock and vibration.
- Pallets:Heavy-duty corrugated platforms for bulk shipment consolidation and warehouse automation.
Volume sits with Boxes; growth tilts toward Inserts.
End User:
Customer type dictates sterility assurance depth, traceability granularity, and order frequency patterns.
- Pharmacies:Retail dispensaries requiring patient-ready unit packaging with tamper-evident closures and clear dosing instructions. Community pharmacy chains in France and Italy are consolidating procurement through buying groups, compressing supplier margins while accelerating ISO 15378 certification requirements.
- Hospitals:Acute care facilities demanding bulk formats compatible with automated dispensing cabinets and inventory management systems. Central European hospital networks specify validated corrugated for high-value biologics, with temperature monitoring integration becoming standard.
- Clinics:Outpatient and specialty care sites with smaller lot sizes and flexible delivery schedules.
- Distribution Centers:Wholesale and logistics hubs consolidating multi-manufacturer shipments for downstream allocation.
Procurement scale peaks at Distribution Centers; regulatory stringency tightens fastest for Hospitals.
Material:
Fiber sourcing and wall construction determine thermal performance, sustainability credentials, and qualification cost.
- Single Wall:Three-ply construction combining linerboard and corrugated medium for standard protection requirements. Cost-sensitive generic drug packaging in India relies heavily on this grade, though CDSCO-aligned converters face pressure to upgrade barrier properties for export to regulated markets.
- Double Wall:Five-ply structures with enhanced stacking strength and insulation value for temperature-sensitive shipments. Vaccine manufacturers specify this configuration for 48-96 hour ambient protection, with EU F-Gas Regulation accelerating displacement of synthetic insulation alternatives.
- Recycled:Post-consumer fiber content meeting EPA benchmarks and converter sustainability mandates.
- Virgin Fiber:Primary kraft pulp delivering consistent mechanical properties and regulatory documentation clarity.
Recycled fiber dominates tonnage; virgin fiber retains premium positioning for biologics.
Application:
Product protection requirements vary sharply by contents' temperature sensitivity, regulatory classification, and value density.
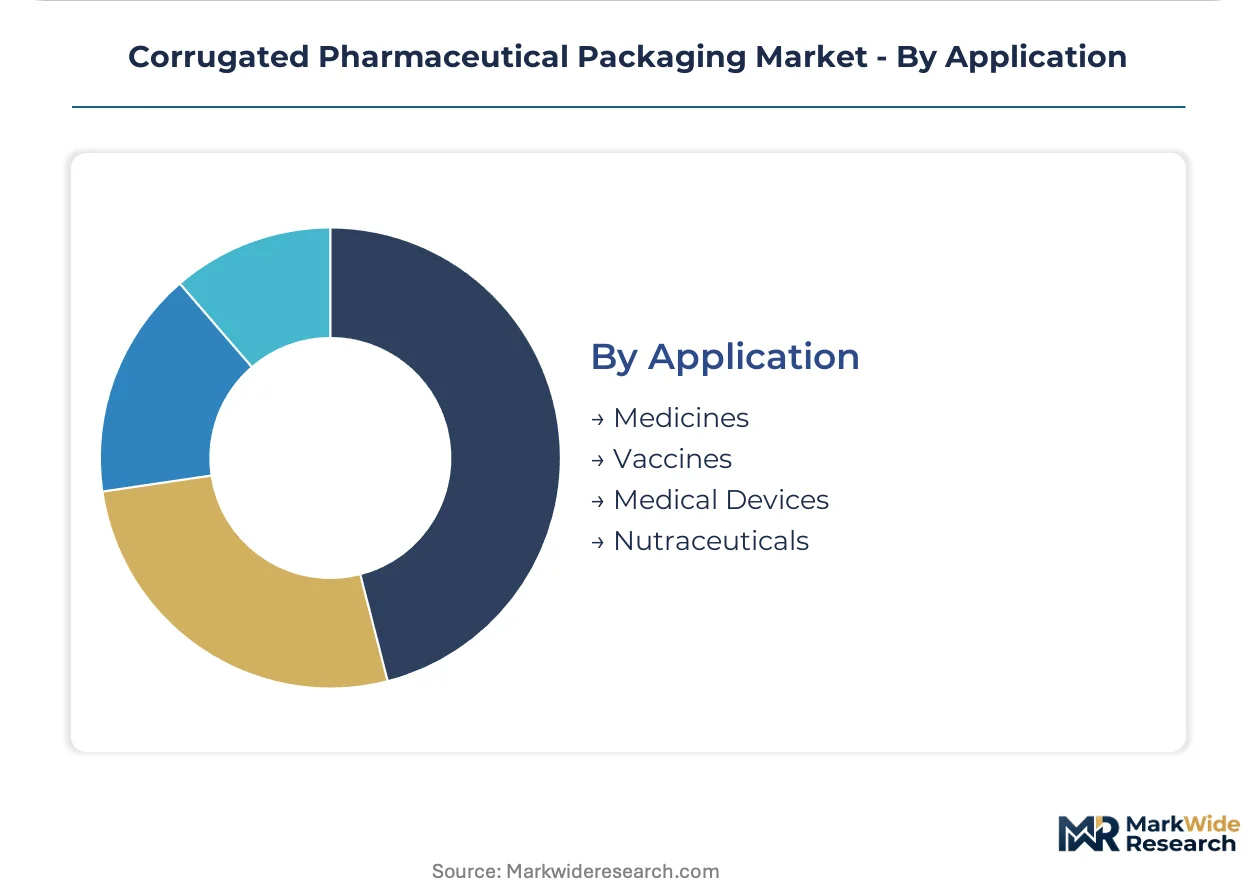
- Medicines:Solid oral dosage and liquid formulations requiring moisture and light protection through standard distribution. High-volume shipments of chronic disease therapies from Central European manufacturing sites sustain demand for validated boxes with child-resistant closure compatibility.
- Vaccines:Temperature-critical biological products demanding engineered cold-chain integrity. This segment absorbs phase-change material integration fastest, with manufacturers specifying PCM-lined corrugated for last-mile distribution in emerging markets.
- Medical Devices:Sterile instruments and diagnostic equipment with dimensional stability and particulate contamination requirements.
- Nutraceuticals:Dietary supplements and functional foods with packaging requirements bridging pharmaceutical and food-contact regulations.
Medicines anchor current volume; vaccines are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical export processing zones concentrate corrugated packaging demand around temperature-controlled logistics corridors serving regulated markets. Tax incentives in Gujarat's Special Economic Zones attract integrated converters seeking CDSCO-aligned qualification pathways for generic drug shipments.
Germany
The Rhine-Main packaging cluster anchors European pharmaceutical-grade corrugated production, with converters integrating phase-change liner compatibility for vaccine distribution. EU F-Gas Regulation compliance mandates fiber-based thermal protection, disqualifying synthetic insulation alternatives. Frankfurt's logistics hub consolidates procurement for Central European biologics manufacturers.
United States
FDA validation protocols drive qualification timelines for corrugated shippers serving domestic vaccine manufacturers and cold-chain distributors. EPA recycled content benchmarks pressure converters toward post-consumer fiber integration without compromising burst strength specifications. The Mid-Atlantic containerboard corridor supplies validated pharma packaging to Northeast pharmaceutical manufacturing zones.
India
CDSCO-aligned converters in Gujarat and Maharashtra scale temperature-controlled packaging capacity for generic drug exports to regulated European and North American markets. PLI scheme incentives support cleanroom converting line investments. The Ahmedabad-Vadodara industrial corridor concentrates specialist die-cutting capacity for vial and syringe insert production.
China
NMPA quality management requirements for medicinal products reshape supplier qualification for corrugated packaging serving domestic biologics manufacturers. Dual carbon goals accelerate fiber-based insulation adoption in cold-chain distribution. The Yangtze River Delta pharmaceutical manufacturing belt generates concentrated demand for validated shippers with traceability documentation.
Japan
PMDA sterility assurance standards extend supplier validation cycles for corrugated packaging serving domestic vaccine and cell therapy manufacturers. METI sustainability mandates drive recycled fiber content targets without sacrificing dimensional tolerance requirements. The Kanto region's pharmaceutical manufacturing concentration sustains premium-grade corrugated demand.
Corrugated Pharmaceutical Packaging Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered qualification requirements. The market structure consolidates around integrated containerboard producers with captive linerboard supply and in-house testing laboratories. Three archetypes dominate: North American scale players with continent-wide distribution networks, European specialists in temperature-control engineering, and Asian converters leveraging cost-advantaged fiber sourcing. Competitive moves center on backward integration into linerboard production and strategic partnerships with cold-chain logistics providers.
Among North American scale players, WestRock and International Paper occupy positions anchored by extensive containerboard networks. DS Smith and Mondi Group exemplify the European specialist archetype with integrated kraft paper operations. Smurfit Kappa represents the cross-regional integrated model with converting presence across multiple pharmaceutical manufacturing corridors.
| Leading Market Players |
|---|
| WestRock |
| International Paper |
| DS Smith |
| Mondi Group |
| Packaging Corporation of America |
| Smurfit Kappa |
| Sonoco Products |
| Graphic Packaging International |
| Rengo |
| Others |
Value Chain & Pricing Dynamics
Consolidated buying by German pharmaceutical distributors is compressing supplier margins and forcing converters toward captive linerboard production to defend cost positions. This procurement concentration rewards integrated containerboard producers with in-house testing laboratories while squeezing regional converter networks.
Pricing Analysis
Short lead-time premiums dominate pricing structures for validated corrugated shippers serving vaccine manufacturers with urgent cold-chain requirements. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified cleanroom production from standard converting and commodity-grade fiberboard. Cost compression in standard-grade boxes is intensifying because recycled fiber input volatility destabilizes converter margins. Generic drug distributors in India exhibit highest price sensitivity, while European biologics manufacturers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Linerboard supply rests on integrated kraft pulp operations in the United States, Germany, and Brazil, with specialty phase-change liner production concentrated in German and Austrian chemical processing corridors. Raw material dependencies include OCC recovered fiber, unbleached kraft pulp, and bio-based barrier coatings derived from plant waxes and nanocellulose. Single-source vulnerability sits with European specialty chemical producers facing REACH Annex XVII fluorinated substance restrictions. Distribution runs through pharmaceutical manufacturing clusters with validated logistics partnerships, notably Germany's Rhine-Main corridor and India's Gujarat Special Economic Zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated containerboard producers with captive supply chains, as FDA and EU validation timelines disqualify undercapitalized regional converters from pharmaceutical qualification pathways.
For Market Incumbents: Deploy backward integration into linerboard production to secure fiber cost stability against OCC pricing volatility. Incumbents should accelerate ISO 15378 cleanroom line investments to capture qualification advantages as EU F-Gas Regulation eliminates synthetic insulation competitors. Rigid plastic substitution from specialized cold-chain logistics providers threatens high-value recurring shipments, demanding defensive partnerships with phase-change material suppliers. For New Entrants and Emerging Players: Cold-chain logistics providers represent the most accessible channel partner type for corrugated converters lacking direct pharmaceutical relationships. White-space targets include CAR-T therapy packaging requiring cryogenic-rated insulation layers and CDSCO-aligned export corridors serving Indian generic drug manufacturers. A qualification-first go-to-market angle emphasizing documented coating chemistry for regulatory filing packages penetrates vaccine manufacturer procurement faster than price competition. For Investors and Strategic Acquirers: Re-rating potential sits with European temperature-control engineering specialists given EU F-Gas Regulation catalysts accelerating fiber-based thermal protection adoption. Long-term viability favors converters with integrated kraft paper operations and established cleanroom converting infrastructure across Central Europe. Watch for CDSCO alignment completion in Gujarat and Maharashtra as inflection indicators for Indian export corridor expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linerboard Production | Captive kraft pulp supply insulates margins from OCC volatility and secures FDA traceability documentation. |
| ISO 15378 Cleanroom Line Investment | Dedicated pharmaceutical converting capacity creates qualification barriers against commodity competitors. |
| Phase-Change Material Partnership | PCM liner integration captures vaccine cold-chain share from displaced expanded polystyrene insulation. |
| CDSCO Alignment for Indian Exports | Regulatory qualification opens generic drug packaging demand from Gujarat Special Economic Zones. |
| Die-Cutting Precision Talent Acquisition | Skilled tooling engineers for vial and syringe inserts command premium positioning in biologics segments. |
Study Parameters
Document review covered FDA validation protocols, EU Good Distribution Practice guidelines, and REACH Annex XVII regulatory filings, complemented by interviews with converter operations directors, pharmaceutical procurement managers, cold-chain logistics specialists, and barrier coating R&D leads. Secondary sources included EPA recycled content benchmarks, ISO 15378 quality management documentation, CDSCO export processing zone records, and customs trade data for containerboard movements. Bottom-up capacity assessments triangulated against top-down demand modeling from pharmaceutical manufacturing cluster analysis.
Market size outputs reflect segment-level modeling across structural configuration, material composition, end-use sterility requirements, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation of biologics cold-chain expansion, EU F-Gas compliance timelines, and Indian pharmaceutical export growth patterns. Industry-specific forecast inputs incorporated phase-change material adoption curves and REACH-compliant coating technology substitution rates.
Several conditions sit outside the modeled scope, including unforeseen regulatory divergence between US and European pharmacopeial standards, abrupt shifts in OCC collection contamination rates, and breakthrough rigid plastic thermal container technologies. Forecasts reflect documented assumptions about validation timeline stability and fiber-based insulation performance parity. A small set of named triggers warrants ongoing watch: CDSCO enforcement alignment completion, EPA recycled content benchmark revisions, and major pharmaceutical distributor buying group consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market