
 Italy Honeycomb Paper Market | 2026-2036
Italy Honeycomb Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Honeycomb Paper Market Insights
High-density structural-grade honeycomb is unwinding legacy demand for lower-specification cores in Italian industrial applications. Smurfit Kappa Group leverages its integrated containerboard network to secure recycled fiber supply for honeycomb cell production. Mondi Group anchors Central European distribution corridors with specialty kraftliner grades optimized for laminated honeycomb facings. DS Smith competes through design-led packaging solutions that specify honeycomb substitution for expanded polystyrene protective formats.
Honeycomb paper comprises a cellular core structure formed from kraft paper ribbons bonded in continuous hexagonal cell configurations, with typical cell diameters ranging from 6 mm to 50 mm and basis weights of 80–200 gsm, engineered to deliver high strength-to-weight ratios for load-bearing and cushioning functions. Recycled-content honeycomb dominates Italian volume given mature collection infrastructure and pulp mill proximity, while bio-based variants incorporating unbleached or agricultural residue fibers are capturing premium positioning in furniture and decorative segments where end-of-life compostability commands specification priority. Laminated honeycomb, faced with solid board or decorative papers, occupies the margin-rich tier in protective materials for precision equipment and luxury goods export packaging.
Italy's Ministry of Environment enforces EU Packaging and Packaging Waste Directive targets that mandate recyclability and recycled content thresholds, directly shaping honeycomb specification against non-paper alternatives. CE marking under harmonized construction product standards governs structural honeycomb panel performance claims in furniture and building applications, creating compliance barriers for imported substitutes. Stakeholders must monitor evolving Ecodesign for Sustainable Products Regulation requirements and assess whether bio-based honeycomb certification schemes from BIS-equivalent Italian standards bodies will become mandatory procurement filters in public infrastructure and institutional furniture tenders.
Market Dynamics
Italy's National Recovery and Resilience Plan (PNRR) green building incentives are compressing demand timelines for cellulose-based core materials, forcing synthetic core substitution decisions in furniture and construction procurement cycles.
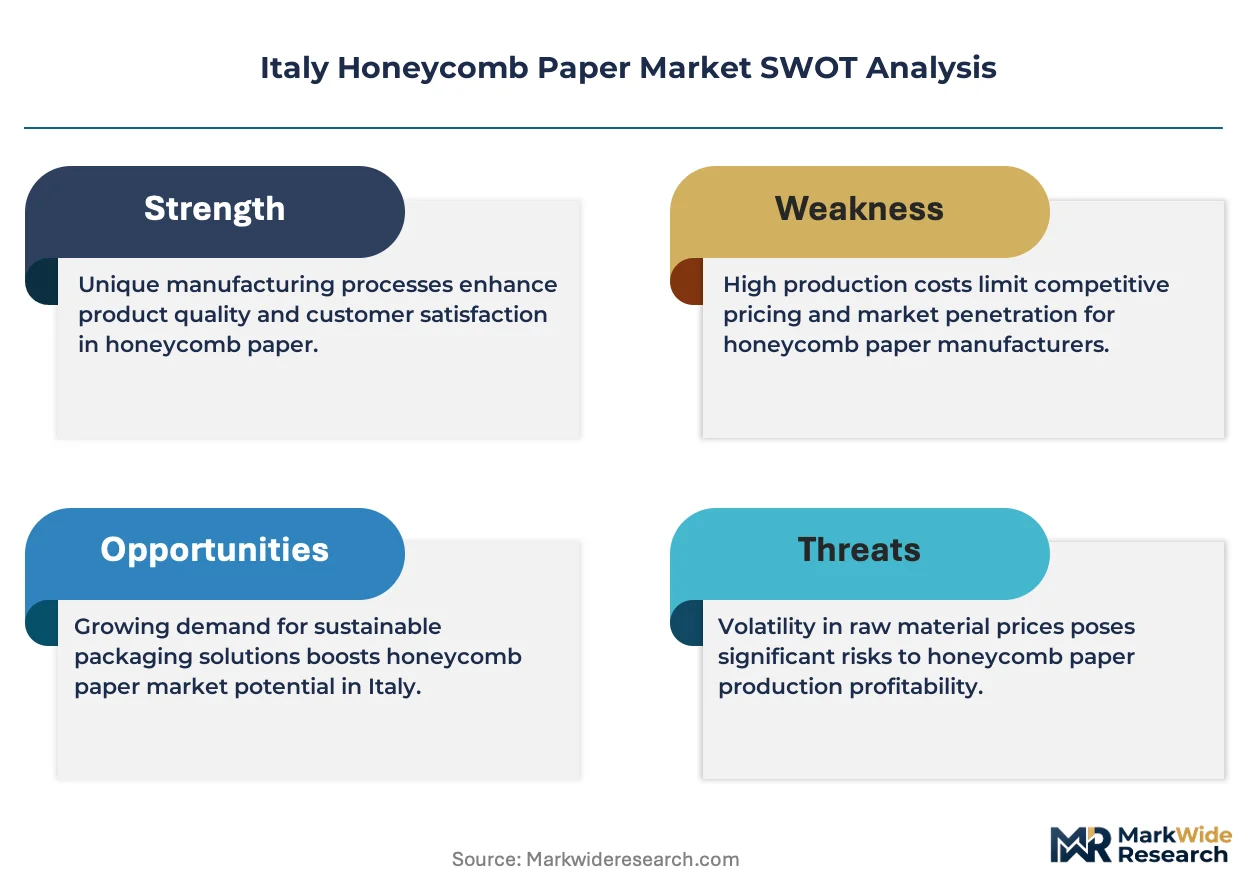
Growth Catalysts
- PNRR Green Building Incentives:Italy's recovery framework mandates recycled-content thresholds in public infrastructure tenders, accelerating honeycomb specification for structural panels.
- Milan-Turin Furniture Cluster:Northern Italian manufacturers are consolidating lightweight panel production around honeycomb cores to reduce shipping weights for export markets.
- EU Packaging and Packaging Waste Directive:Recyclability mandates are eliminating expanded polystyrene from protective packaging specifications for luxury goods exports.
Market Restraints
- Kraft Pulp Price Volatility:Recycled fiber supply constraints in Lombardy are compressing margins for honeycomb producers dependent on containerboard mill proximity.
- CE Marking Compliance Burden:Harmonized construction product standards create certification barriers for imported honeycomb substitutes seeking structural panel applications.
- Synthetic Core Cost Competition:Polypropylene honeycomb from Central European producers retains price advantage in non-structural cushioning applications.
Strategic Opportunities
- Emilia-Romagna Agricultural Residue Integration:Unbleached fiber variants from regional wheat straw pulping are capturing premium positioning in compostable furniture segments.
- Ecodesign for Sustainable Products Regulation:Pending EU mandatory digital product passports will favor honeycomb with verified bio-based content in institutional tenders.
- Veneto Precision Equipment Channel:Laminated honeycomb facing technology is penetrating high-value export packaging for medical device manufacturers.
Industry Challenges
- Hexagonal Cell Geometry Expertise Gap:Northern Italian converters face recruitment constraints for adhesive patterning technicians capable of high-density structural-grade production.
- Bio-Based Certification Timeline Uncertainty:Italian standards bodies have not finalized equivalence protocols for BIS-aligned compostability claims, delaying premium pricing realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Honeycomb Paper Market |
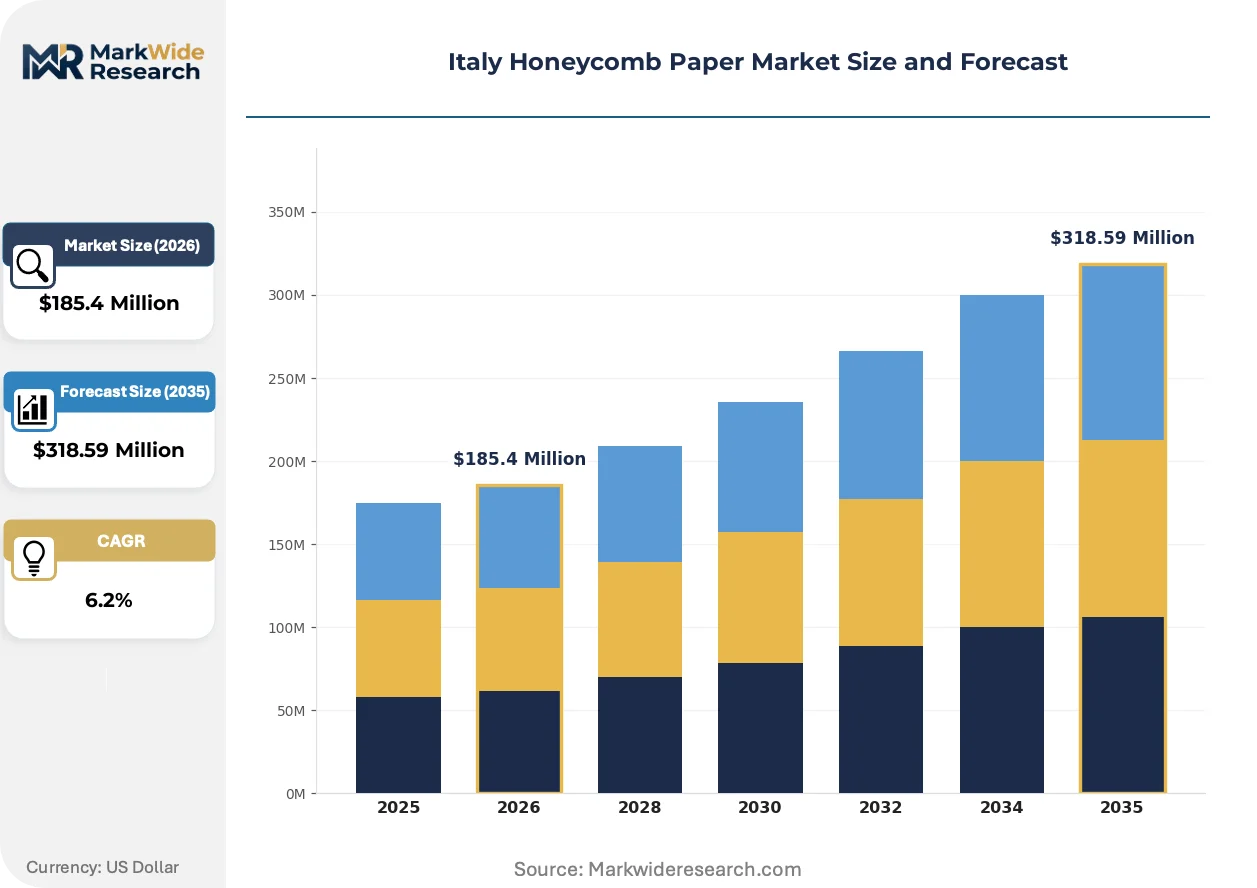
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $318.59 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recycled, Bio-Based, Laminated, Plain End User: Packing Industry, Advertising, Crafting, Furniture Application: Packaging Solutions, Decorative Purposes, Industrial Use, Protective Materials Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | Smurfit Kappa Group, DS Smith, Mondi Group, International Paper, WestRock Company, Stora Enso, Cascades Inc., Sappi Lanaken, Papeteries de Genval, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Honeycomb Paper Market Trends and Innovations
Digital manufacturing integration and bio-material science are converging to reshape honeycomb specification criteria across Italian industrial buyer segments. Three developments are compressing traditional competitive boundaries.
Continuous ribbon expansion technology is decomposing legacy die-cut production methods in high-volume honeycomb manufacturing. Turin-based panel producers are adopting servo-controlled adhesive deposition systems that enable variable cell density within single production runs. This flexibility is decomposing the historical trade-off between structural performance and material efficiency that constrained honeycomb penetration in weight-critical furniture applications.
Italy's Ministry of Environment enforcement of EU Packaging and Packaging Waste Directive recyclability targets is eliminating non-paper alternatives from public procurement specifications. Industrial buyers in Lombardy must now document end-of-life collection pathways for protective materials used in precision equipment shipping. The directive's recycled content thresholds are most acutely affecting luxury goods exporters in Milan who previously relied on expanded polystyrene for shock protection.
Consolidated buying by Emilia-Romagna furniture OEMs is compressing supplier negotiation cycles from annual to quarterly terms. Tier-one panel manufacturers are unbundling design services from material supply, forcing honeycomb converters to demonstrate finite element analysis capability for load-bearing applications. This behavioral shift is most visible in Veneto's medical device packaging cluster, where procurement teams now require structural simulation data prior to vendor qualification.
Italy Honeycomb Paper Market Segmentation
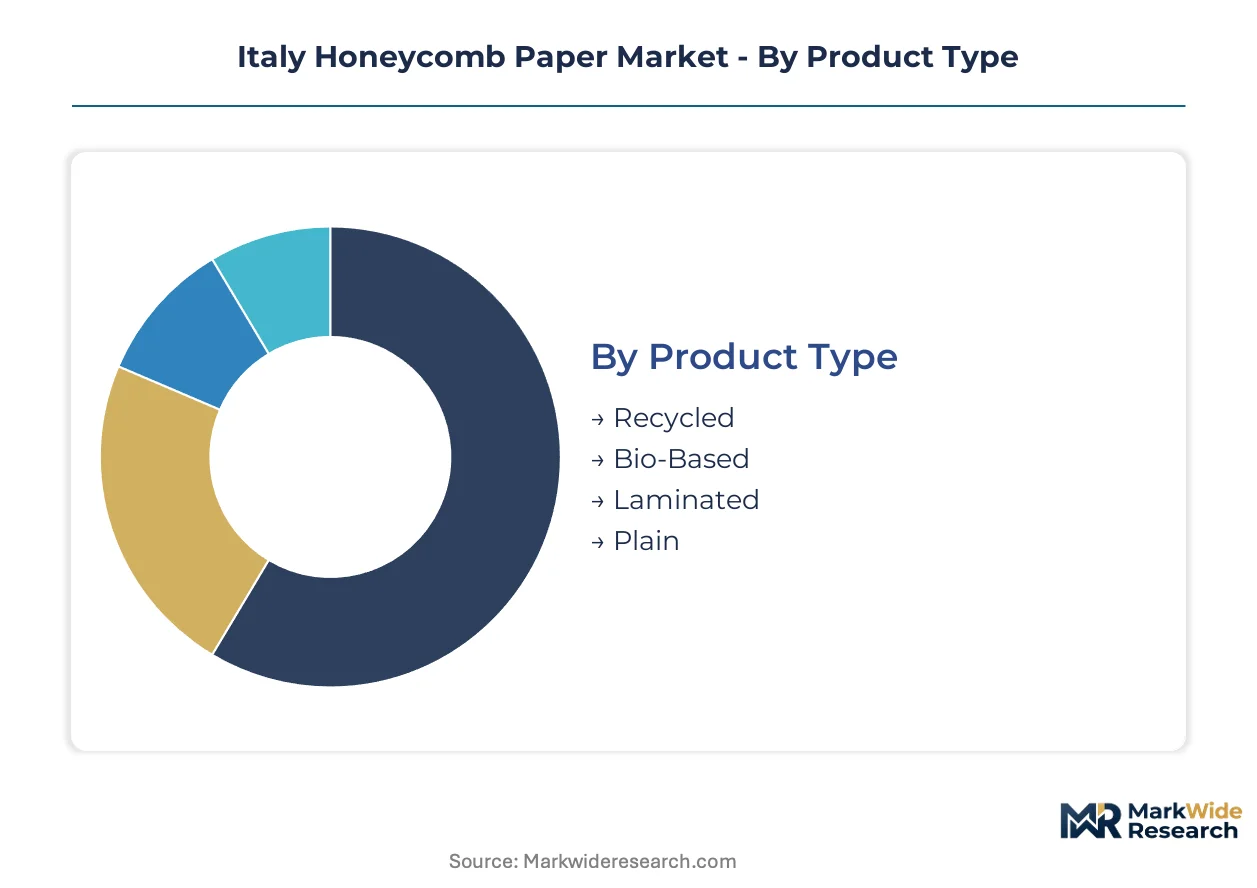
Segmentation in the Italy Honeycomb Paper Market reveals how substitution pressures from synthetic cores and regulatory mandates reshape procurement priorities across material grades and end-use channels. Understanding these divisions exposes where cellulose-based alternatives command specification authority versus where cost competition from polypropylene honeycomb persists.
Product Type:
Recycled-content honeycomb faces the most acute substitution threat from polypropylene alternatives in non-structural cushioning, while bio-based variants defend premium positioning through compostability certification.
- Recycled:Manufactured from post-consumer kraft paper collected through Lombardy's mature containerboard recovery infrastructure, with basis weights of 80–150 gsm optimized for cost-sensitive protective packaging. Demand concentrates in Milan's luxury goods export corridor where EU Packaging and Packaging Waste Directive recyclability mandates eliminate expanded polystyrene alternatives.
- Bio-Based:Incorporates unbleached kraft or agricultural residue fibers from Emilia-Romagna wheat straw pulping, engineered for end-of-life compostability in furniture and decorative applications. Northern Italian OEMs specify these variants for institutional tenders anticipating Ecodesign for Sustainable Products Regulation digital product passport requirements.
- Laminated:Faced with solid board or decorative papers for margin-rich precision equipment packaging.
- Plain:Unfaced cellular core for basic cushioning and void-fill applications in high-volume industrial shipping.
Recycled honeycomb retains volume leadership; bio-based honeycomb holds the steepest expansion curve.
End User:
Customer-type concentration in northern Italy's industrial corridor determines margin structure, with furniture OEMs consolidating procurement power while advertising agencies fragment demand across small-batch decorative applications.
- Packing Industry:Protective packaging converters serving Veneto's medical device manufacturers and Milan's precision equipment exporters specify laminated honeycomb for shock-absorbing performance in high-value international shipments.
- Furniture:Milan-Turin panel manufacturers drive structural-grade honeycomb adoption for lightweight bed frames, cabinet cores, and shelving systems where shipping weight reduction directly impacts export competitiveness.
- Advertising:Display and point-of-sale material producers utilize honeycomb for temporary exhibition structures and retail fixtures.
- Crafting:Hobbyist and educational supply channels consume small-diameter cell honeycomb for model construction and artistic applications.
Furniture commands the highest per-kilogram pricing tier; advertising applications expand most quickly through experiential marketing demand.
Application:
Application-level segmentation tracks how CE marking requirements under harmonized construction product standards partition structural from non-structural demand, creating compliance barriers that reshape competitive boundaries.
- Packaging Solutions:Protective shipping formats for luxury goods, medical devices, and precision instrumentation where Italy's Ministry of Environment enforcement of EU recyclability targets mandates paper-based alternatives.
- Industrial Use:Load-bearing panel cores for furniture and temporary building systems subject to CE marking performance verification.
- Protective Materials:Cushioning and void-fill applications competing directly with polypropylene honeycomb on cost.
- Decorative Purposes:Faced honeycomb for interior design and exhibition applications where visual finish and compostability drive specification.
Packaging Solutions retains volume leadership; Industrial Use climbs the fastest as PNRR green building incentives accelerate structural panel adoption.
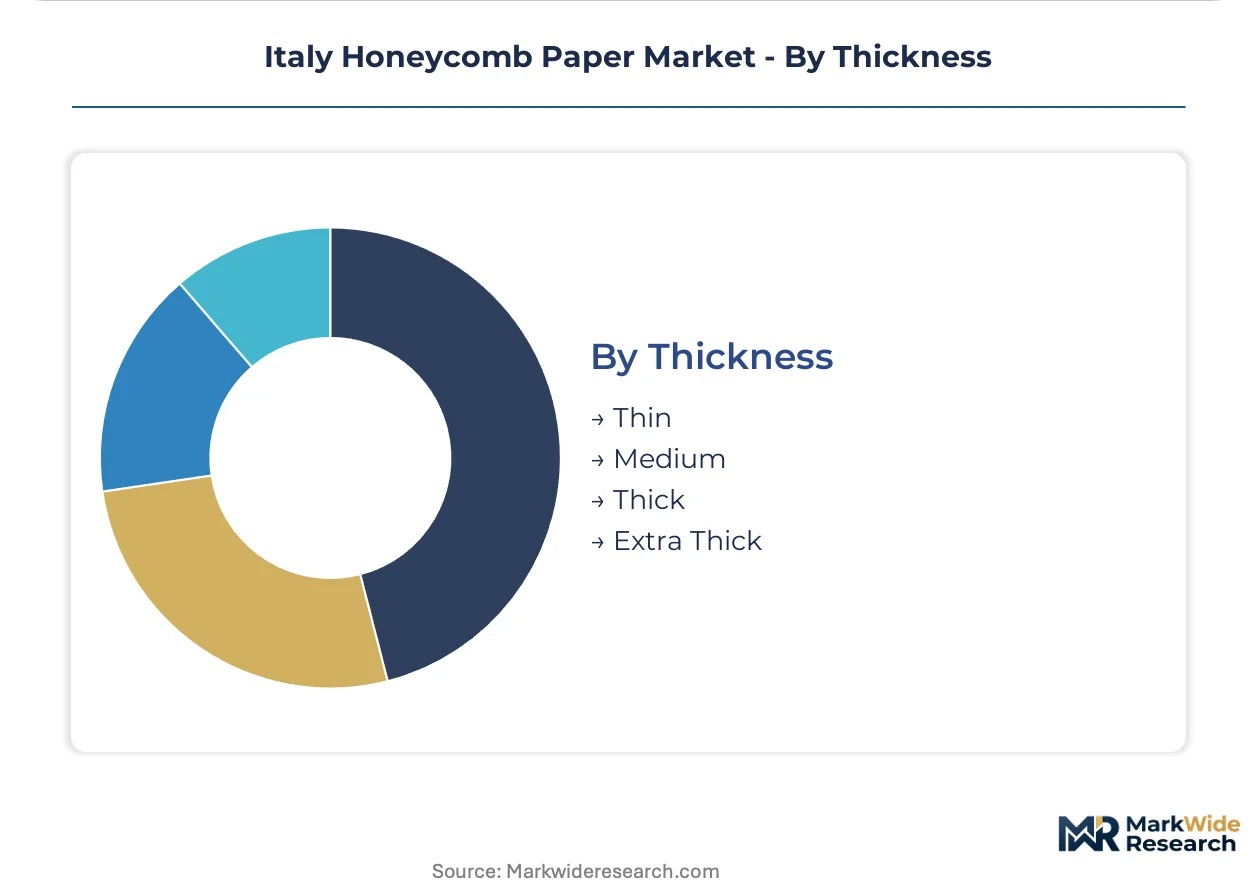
Thickness:
Thickness stratification correlates with cell geometry complexity and adhesive patterning precision, concentrating high-value production among Turin-based converters with servo-controlled deposition capabilities.
- Thick:Cell depths exceeding 50 mm for heavy-duty industrial cushioning and architectural panel applications requiring maximum compressive strength.
- Medium:20–50 mm cell depth serving furniture core and protective packaging markets with balanced strength-to-weight performance.
- Thin:6–20 mm configurations for lightweight display materials and precision-fit protective formats.
- Extra Thick:Custom-engineered depths above 75 mm for specialized load-bearing and impact-absorption requirements.
Medium thickness dominates current procurement volumes; Thick honeycomb gains share fastest through structural furniture panel demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Veneto's precision equipment corridor exhibit the highest price elasticity, squeezing converter margins on standard-grade honeycomb, while Milan-Turin furniture OEMs absorb premium pricing for structural certification. This demand-elasticity contrast concentrates investment in high-specification production capacity across the northern industrial corridor.
Lombardy
Milan's luxury goods exporters drive laminated honeycomb specification for shock-sensitive international shipments. Italy's Ministry of Environment enforces EU Packaging and Packaging Waste Directive recyclability thresholds that eliminate expanded polystyrene alternatives. The metropolitan logistics hub concentrates procurement power among consolidated buying groups that compress supplier payment terms to quarterly cycles.
Piedmont
Turin-based panel manufacturers anchor structural-grade honeycomb adoption for lightweight furniture cores targeting export markets. CE marking under harmonized construction product standards governs performance claims for load-bearing applications. The city's servo-controlled adhesive deposition specialists enable variable cell density production that decomposes legacy trade-offs between strength and material efficiency.
Veneto
Medical device manufacturers in the precision equipment cluster specify laminated honeycomb facing technology for high-value export packaging. The EU Ecodesign for Sustainable Products Regulation positions bio-based variants for institutional tender advantages through pending digital product passport requirements. Procurement teams now mandate finite element analysis data prior to vendor qualification, elevating technical barriers for converters.
Emilia-Romagna
Furniture OEMs consolidate procurement around unbleached fiber honeycomb incorporating regional wheat straw pulping residues. Italy's National Recovery and Resilience Plan green building incentives accelerate substitution of synthetic cores in public infrastructure tenders. Agricultural residue integration captures premium positioning where end-of-life compostability commands specification priority.
Lazio
Rome's institutional furniture procurement channels absorb bio-based honeycomb volumes anticipating mandatory certification schemes from Italian standards bodies. Regulatory timeline uncertainty delays premium pricing realization as equivalence protocols for BIS-aligned compostability claims remain unfinalized. Central government green procurement mandates concentrate demand for verified sustainable content in public building projects.
Italy Honeycomb Paper Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Italian honeycomb paper market. Integrated containerboard producers leverage captive fiber supply and mill proximity to defend cost positions in high-volume recycled segments. Specialized converters with servo-controlled deposition capabilities occupy the premium tier for structural-grade applications requiring variable cell geometry. Independent honeycomb specialists compete through design services unbundled from material supply. Dominant competitive moves include backward integration into containerboard networks and capacity expansion in laminated facing technology.
Among integrated paper-honeycomb groups, Smurfit Kappa Group exemplifies the containerboard-backed archetype with Lombardy mill proximity securing recycled fiber supply. DS Smith represents the design-led packaging specialist positioning, while Mondi Group anchors Central European distribution corridors with specialty kraftliner grades. These three companies collectively illustrate how fiber integration, design capability, and geographic anchoring define competitive positioning in a market where procurement consolidation and regulatory compliance reshape vendor selection criteria.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith |
| Mondi Group |
| International Paper |
| WestRock Company |
| Stora Enso |
| Cascades Inc. |
| Sappi Lanaken |
| Papeteries de Genval |
| Others |
Pricing and Supply Chain Analysis
Sixty-day containerboard mill lead times in Lombardy compress converter pricing power during kraft pulp volatility spikes, while Turin-based panel manufacturers exploit geographic proximity to secure volume discounts on structural-grade honeycomb. This inventory-to-pricing linkage concentrates margin defense among integrated producers with captive fiber supply.
Pricing Analysis
After-sales technical service contracts for load-bearing panel certification drive lifetime value capture in the Italian honeycomb market. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking compliance tier and servo-controlled cell geometry precision. Cost compression in recycled-content grades intensifies because polypropylene honeycomb from Central European producers undercuts paper-based alternatives in non-structural cushioning. Furniture OEMs in Milan-Turin exhibit lowest price sensitivity due to shipping weight reduction premiums, while Veneto medical device exporters squeeze margins on standard protective formats.
Supply Chain Analysis
Strategic stockpile preferences dominate kraft paper procurement as Lombardy converters buffer against containerboard mill scheduling volatility. Supply concentrates in Italy, Germany, and Austria for specialty kraftliner grades, with raw material dependencies centering on post-consumer recycled fiber, unbleached agricultural residue pulp, and hot-melt adhesive formulations. Single-source vulnerability runs through Smurfit Kappa's Lombardy mill network for high-volume recycled grades. Distribution feeds from northern Italian production clusters through consolidated buying groups serving Milan luxury goods exporters and Turin furniture panel manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's honeycomb paper market operates as a substitution defense against polypropylene core erosion, where cellulose-based incumbents must navigate synthetic cost competition while extracting premium from regulatory-mandated sustainable packaging transitions.
For Market Incumbents: Shield structural-grade positioning by deepening servo-controlled deposition capabilities in Turin production corridors, and secure backward integration into Emilia-Romagna agricultural residue pulping to defend bio-based premium tiers against imported kraftliner volatility. CE marking compliance investment creates switching costs that synthetic core substitutes cannot replicate. For New Entrants and Emerging Players: CE marking fast-track specialization opens procurement channels among Veneto medical device packaging clusters where finite element analysis capability gaps delay vendor qualification. Target laminated honeycomb facing technology for precision equipment exporters, and unbundle design services from material supply to penetrate consolidated furniture OEM buying groups. For Investors and Strategic Acquirers: Carve-out targets emerge from containerboard majors seeking to monetize non-core honeycomb conversion assets, particularly Lombardy-based facilities with stranded recycled fiber access. Long-term viability hinges on bio-based certification scheme adoption trajectories. Watch for BIS-equivalence protocol finalization from Italian standards bodies as inflection signal for premium pricing realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Pulping | Captures wheat straw fiber supply from Emilia-Romagna for compostable furniture-grade honeycomb. |
| Servo-Controlled Adhesion Capacity Expansion | Enables variable cell density production for Turin structural panel manufacturers. |
| CE Marking Certification Investment | Creates compliance barriers against Central European polypropylene honeycomb imports. |
| Laminated Facing Technology Partnership | Penetrates Veneto medical device export packaging with shock-absorbing precision formats. |
| Bio-Based Certification Scheme Alignment | Positions for Ecodesign for Sustainable Products Regulation digital product passport requirements. |
Research Methodology
A standing panel of honeycomb conversion plant managers, furniture OEM procurement directors, kraftliner mill supply planners, and Italy's Ministry of Environment regulatory officers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Packaging and Packaging Waste Directive enforcement records, CE marking harmonized standard databases, Lombardy containerboard trade flow statistics, and PNRR green building tender documentation. Bottom-up segment sizing triangulated against top-down macroeconomic anchors across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs through cross-referencing with customs data on kraft paper ribbon imports and protective packaging sector production indices. The analytical framework modeled product type, end user, application, and thickness segmentation alongside regional industrial corridor concentration throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating PNRR incentive phase-in assumptions and synthetic core substitution elasticities.
Underlying assumptions cover kraft pulp price stability, CE marking enforcement continuity, and polypropylene honeycomb cost trajectories, with deviation risk concentrated in recycled fiber supply disruptions and bio-based certification timeline delays. Revision becomes warranted when BIS-equivalence protocol finalization crosses institutional procurement mandate thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Air Fryer Paper Liners Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Paperboard Protectors Market