
 Asia-Pacific Paper Bags Market | 2026-2036
Asia-Pacific Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Paper Bags Market Outlook
Supermarket private-label supply chains is tilting toward domestic paper-bag converters across Southeast Asia and Oceania. Oji Holdings Corporation leverages integrated pulp-to-bag operations across Japan and Australia to secure long-term retail contracts. SCG Packaging anchors its position through captive kraft-paper supply from Thai forestry assets and regional converting plants. Mondi Group competes on food-grade barrier coatings that extend paper-bag utility into chilled and greasy product segments.
Asia-Pacific paper bags are multi-ply containers manufactured from kraft, recycled, or bleached paper stock through tube forming, bottom pasting, and optional flexographic or digital printing, designed to carry retail goods, prepared food, or e-commerce parcels with load-bearing capacity typically ranging from two to twenty kilograms. Kraft paper dominates material selection for its tensile strength and compostability, though recycled-paper grades gain share where post-consumer waste collection infrastructure matures. Block bottom bags lead in grocery and food service applications due to stable shelf-standing geometry, while e-commerce demand pushes growth in gusseted satchel formats with reinforced handles.
Japan's Ministry of Economy, Trade and Industry enforces container and packaging recycling targets that mandate minimum recycled content thresholds, while Australia's National Packaging Covenant sets design-for-recovery standards affecting import eligibility. India's BIS standards for food-contact paper materials restrict certain optical brighteners and mandate migration testing, shaping supplier qualification protocols. Stakeholders must monitor how China's SAMR implements stricter labeling and traceability rules for single-use paper products, as compliance costs will reshape competitive rankings among regional converters.
Market Dynamics
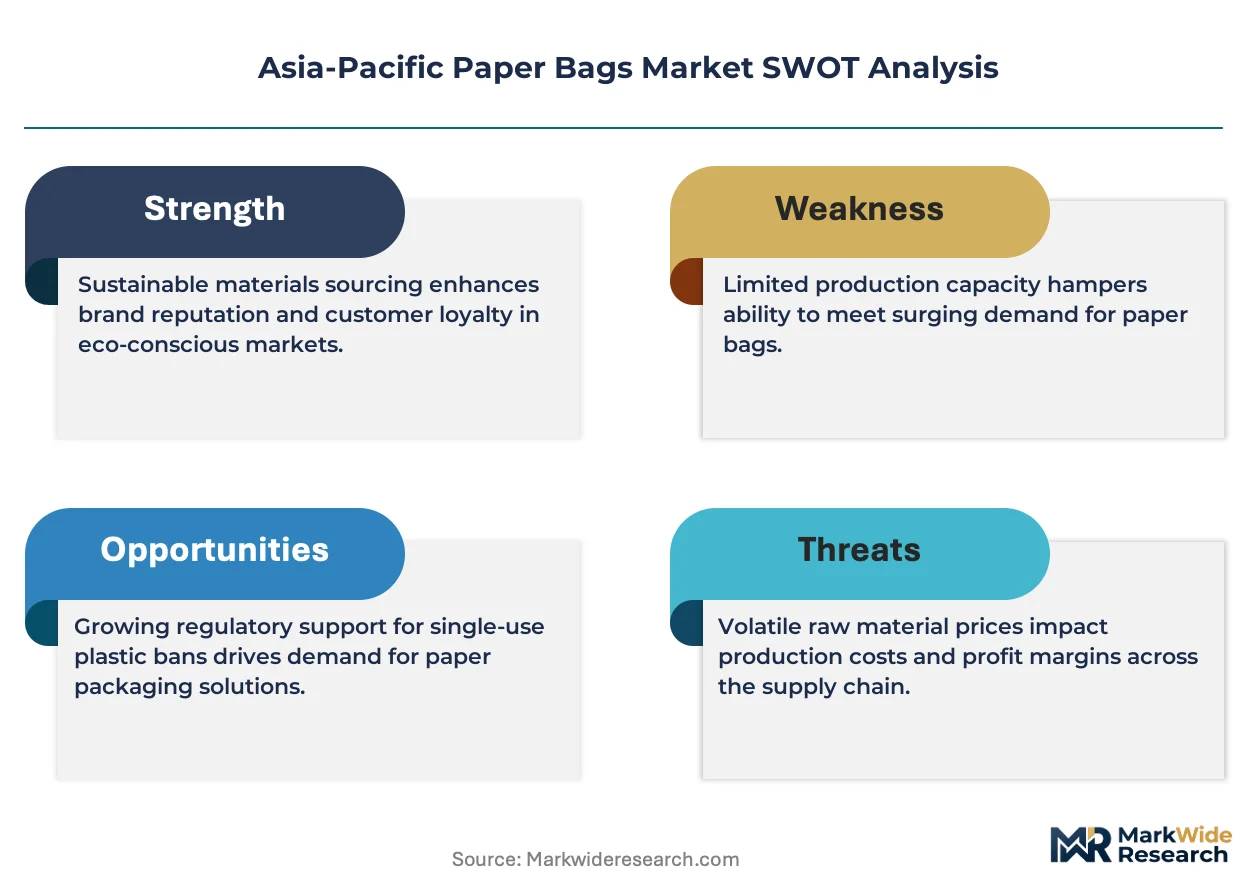
Municipal plastic bans across Southeast Asia are compressing substitution timelines for food service packaging, forcing converters to absorb kraft-paper price volatility while scaling barrier-coating capabilities.
Growth Catalysts
- Thailand's National Plastic Waste Management Roadmap:Mandatory phase-outs of single-use plastics in food service channels are redirecting procurement budgets toward certified paper alternatives.
- Barrier coating chemistry:Water-based grease-resistant formulations are extending paper-bag utility into hot and oily food segments previously locked to plastic.
- Vietnam's export manufacturing corridor:Concentrated converting capacity near Ho Chi Minh City is capturing Japanese and Australian retail contract flows.
Market Restraints
- Pulp cost volatility:Kraft fiber prices fluctuate with Indonesian and Malaysian plantation harvest cycles, squeezing converter margins.
- Regional supply concentration:Bleached paper stock for premium retail applications relies heavily on Australian pulp mills, creating single-source exposure.
- India's BIS certification timeline:Migration testing requirements for food-contact materials extend supplier qualification cycles by 8-14 months.
Strategic Opportunities
- Indonesia's archipelago logistics:Underdeveloped cold-chain infrastructure creates demand for insulated paper-based delivery pouches in prepared food.
- E-commerce gusseted satchels:Reinforced-handle formats are displacing poly-mailers in Australian last-mile delivery networks.
- Japan's METI recycling mandates:Minimum recycled-content thresholds favor converters with integrated post-consumer fiber processing.
Industry Challenges
- Flexographic pre-press talent:Shortage of skilled operators for high-definition food-grade printing is constraining quality ramp rates.
- Coextrusion equipment lead times:Barrier-film lamination lines face 18-24 month delivery delays from European and Japanese OEMs.
- Multi-jurisdiction label compliance:Divergent language and traceability rules across ASEAN markets fragment packaging artwork versioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Paper Bags Market |
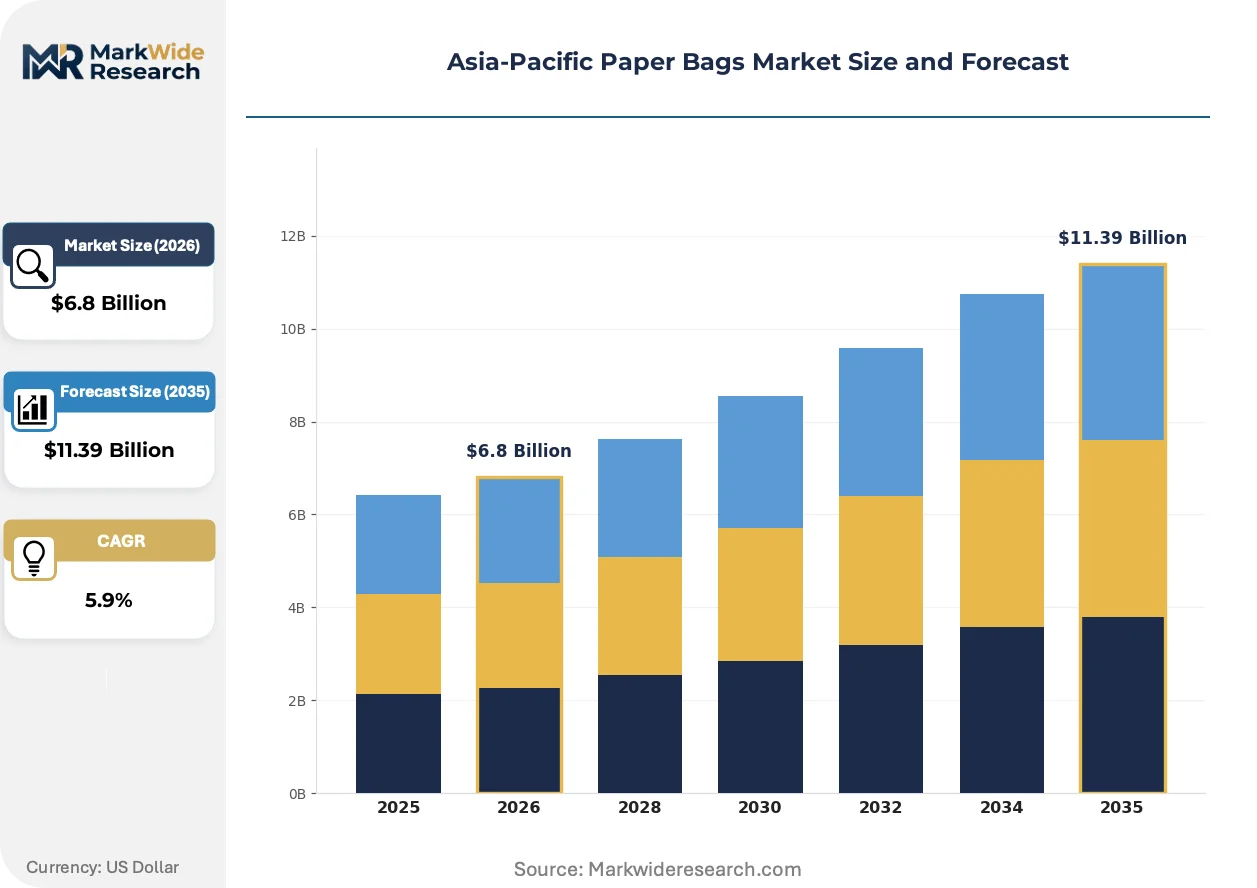
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Paper Bags, Block Bottom Bags, Satchel Bags, T-Shirt Bags End User: Retail, Food Service, Packaging, E-commerce Material: Kraft Paper, Recycled Paper, Virgin Paper, Bleached Paper Printing Technology: Flexographic, Offset, Digital, Gravure |
| Companies Covered | Oji Holdings Corporation, International Paper Company, Smurfit Kappa, Mondi Group, WestRock Company, SCG Packaging, Huhtamaki Group, Amcor plc, Rengo Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Paper Bags Market Strategic Shifts
Active coating technologies and digital print workflows are compressing product development cycles while regulatory pressure on plastic alternatives intensifies specification complexity.
Water-based fluorine-free grease barriers are collapsing the performance gap between paper and plastic in hot-food applications. Fast-casual chains in Singapore and Malaysia are adopting these coatings at scale for fried product lines. The technology is collapsing resistance among franchise operators who previously cited leakage failures as the barrier to paper conversion.
Australia's National Packaging Covenant is mandating design-for-recovery standards that restrict import eligibility for non-compliant bag suppliers. The framework requires recyclability testing against domestic fiber-recovery infrastructure. Japanese retail buyers are now auditing Southeast Asian converters against these Australian protocols to preempt supply chain disruption.
Direct-to-brand digital print contracts are displacing traditional converter-distributor relationships in premium cosmetics and specialty food. Australian and Japanese brands are contracting Vietnamese and Thai printers for short-run customized packaging without intermediary trading houses. This pattern is most visible in Melbourne and Sydney boutique retail segments where seasonal artwork turnover exceeds 12 cycles annually.
Asia-Pacific Paper Bags Market Segmentation
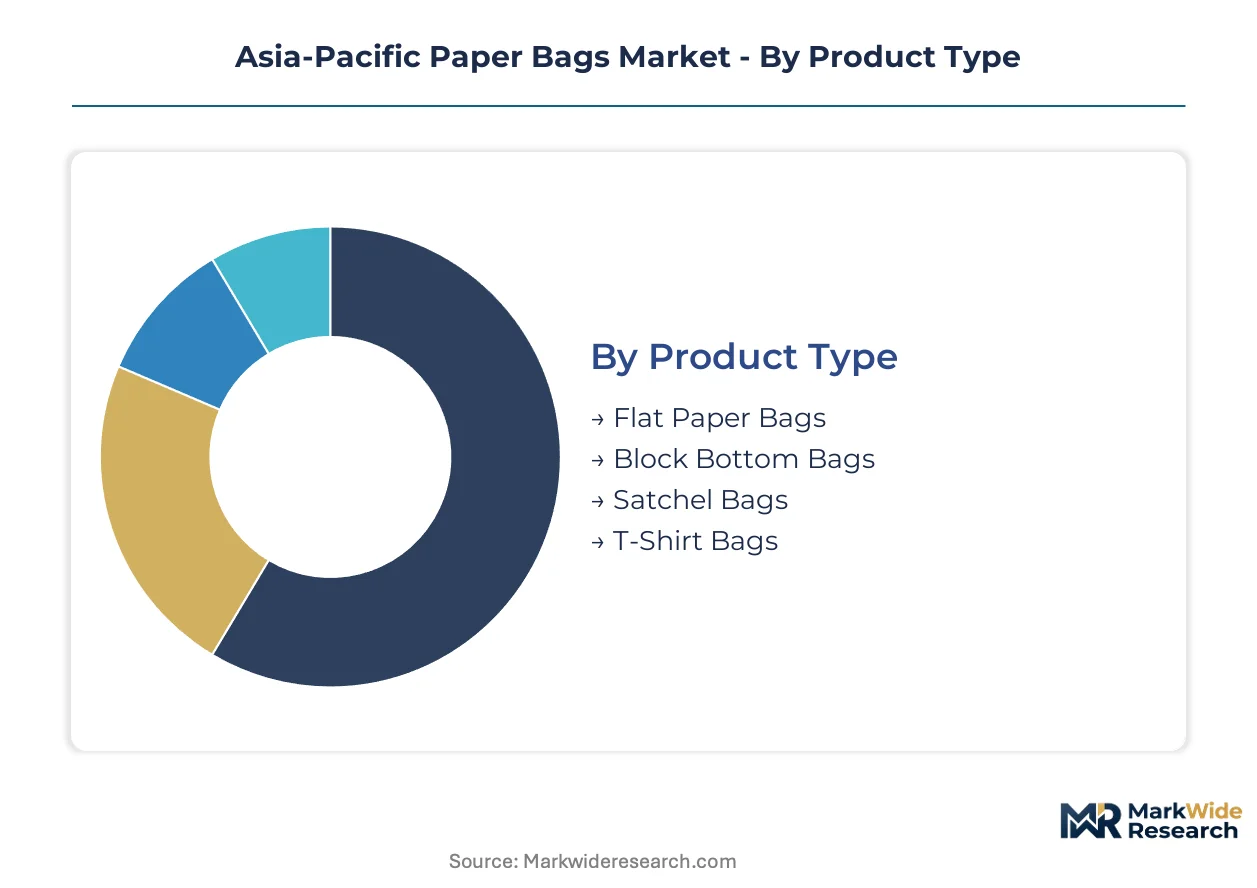
Paper bag specifications diverge sharply across load-bearing requirements, food-contact compliance, and print fidelity demands. Procurement managers in Asia-Pacific trade-offs between kraft fiber durability, barrier coating performance, and artwork versioning complexity when qualifying suppliers.
Product Type:
Mature formats dominate grocery and food service channels while emerging geometries capture e-commerce growth corridors.
- Flat Paper Bags:Single-sheet construction with glued side seams handles lightweight retail merchandise and pharmacy prescriptions. Japanese convenience store chains specify these for non-food items where shelf-standing stability is unnecessary.
- Block Bottom Bags:Cross-bottom pasting creates rectangular bases that stand upright on shelves and resist tipping under load. Australian supermarket private-label programs and Vietnamese export contracts to Japanese retail buyers concentrate demand here, with specifications tightening around moisture resistance for chilled produce applications.
- Satchel Bags:Gusseted side panels expand capacity for irregular e-commerce parcels; reinforced paper handles or woven tape inserts address last-mile durability concerns in Australian delivery networks.
- T-Shirt Bags:Die-cut handle apertures mimic plastic carrier ergonomics for retail checkout transitions; Thai food service chains favor these for quick-service takeaway where one-handed carrying is essential.
Block bottom bags handle the majority of throughput; satchel bags are expanding most quickly on share.
End User:
Application requirements split between regulated food-contact compliance and non-food durability specifications.
- Retail:Supermarket checkout carriers and boutique merchandise packaging demand consistent print registration and handle tensile strength. Australia's National Packaging Covenant recyclability standards filter supplier eligibility for this segment.
- Food Service:Hot and greasy product lines require water-based fluorine-free grease barriers that BIS-certified Indian converters are scaling for quick-service restaurant chains. Singaporean and Malaysian fast-casual operators are converting fried product packaging at pace.
- Packaging:Industrial void-fill and protective wrapping applications prioritize cost minimization over print quality; recycled fiber content thresholds vary by destination market recycling infrastructure.
- E-commerce:Gusseted satchel formats with tamper-evident closures displace poly-mailers in Australian last-mile networks; Vietnamese converters near Ho Chi Minh City capture Japanese and Australian contract flows.
Retail commands the largest procurement volumes; e-commerce is climbing the fastest on share.
Material:
Fiber sourcing strategies balance tensile performance against post-consumer waste integration mandates.
- Kraft Paper:Unbleached sulfate pulp delivers superior tear resistance and compostability; dominates load-bearing applications across Southeast Asian food service channels. Price volatility tracks Indonesian and Malaysian plantation harvest cycles.
- Recycled Paper:Post-consumer fiber integration satisfies Japan's METI minimum recycled-content thresholds; converters with in-house deinking and pulping operations capture long-term retail contracts.
- Virgin Paper:Consistent fiber length and cleanliness suit high-definition flexographic printing for premium cosmetics and specialty food segments.
- Bleached Paper:Optical brightness and surface smoothness target luxury retail applications; Australian pulp mills supply concentrated capacity creating single-source exposure for premium specifications.
Kraft paper anchors volume procurement; recycled grades are gaining share fastest as collection infrastructure matures.
Printing Technology:
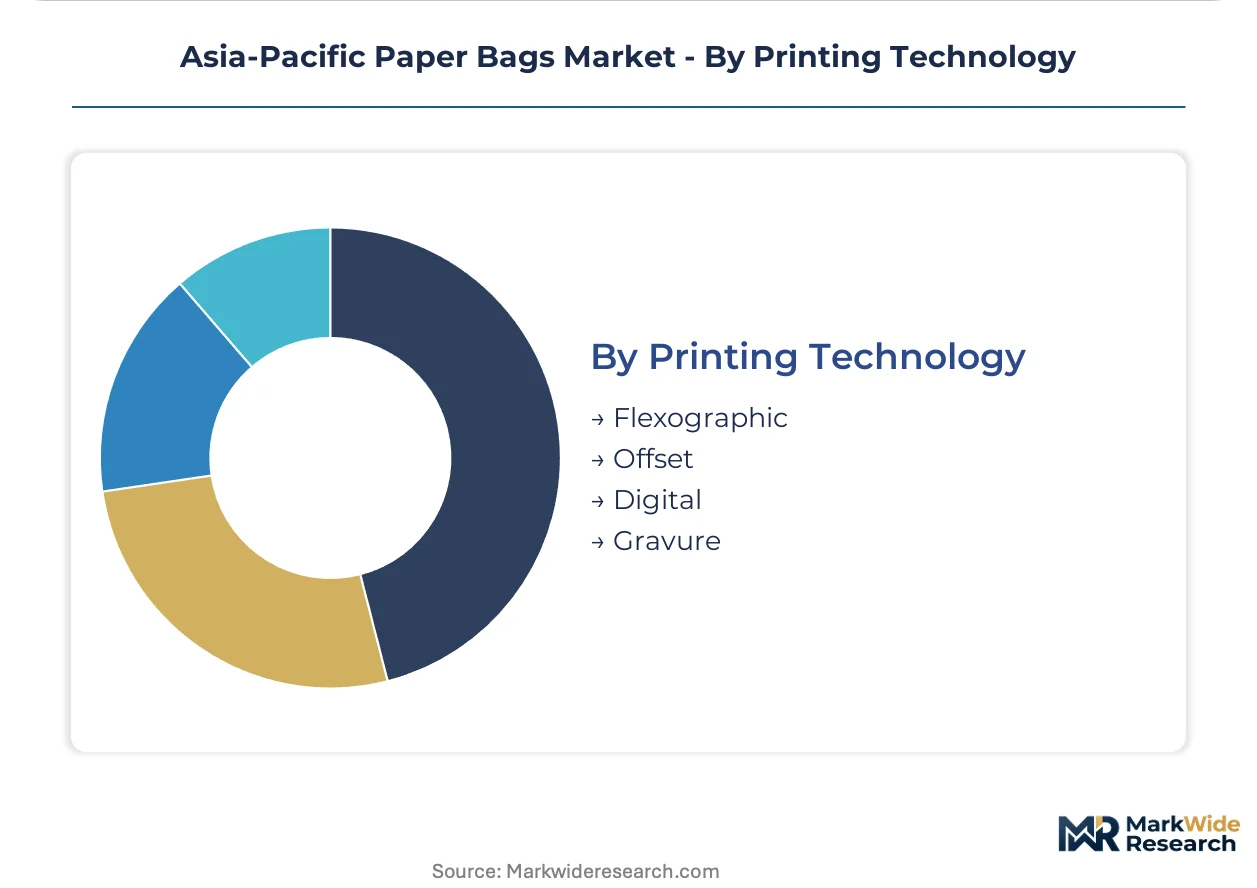
Print method selection trades setup cost, run length flexibility, and food-contact compliance complexity.
- Flexographic:Rotary relief printing on continuous rolls dominates long-run grocery and food service production; skilled pre-press operator scarcity constrains quality ramp rates across Southeast Asian converter bases.
- Offset:Planographic lithography delivers fine detail for premium retail and cosmetics packaging where artwork complexity justifies plate costs.
- Digital:Inkjet and toner systems enable short-run customization without plate changeover; Australian and Japanese boutique brands contract Vietnamese and Thai printers directly for seasonal artwork turnover exceeding twelve cycles annually.
- Gravure:Intaglio cylinder engraving supports ultra-long runs with consistent ink deposition; limited adoption in paper bags due to cylinder cost and lead time disadvantages versus flexographic alternatives.
Flexographic systems carry the heaviest production load; digital workflows are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI enforces container and packaging recycling targets that mandate minimum recycled content thresholds, anchoring regulatory pressure across the region. Australia's National Packaging Covenant sets design-for-recovery standards affecting import eligibility. India's BIS certification requirements for food-contact paper materials are accelerating investment in compliant kraft-paper conversion lines.
Japan
Retail chains and convenience store operators drive specification demand for lightweight flat and block bottom formats. METI's recycling mandates favor converters with integrated post-consumer fiber processing capabilities. Industrial clusters in the Kanto region around Tokyo concentrate flexographic printing capacity serving domestic and export buyers.
Australia
Supermarket private-label programs and e-commerce last-mile networks absorb gusseted satchel volumes. The National Packaging Covenant's design-for-recovery standards filter supplier eligibility through recyclability testing protocols. Converting capacity concentrates in Victoria and New South Wales, where facilities serve both domestic retail and export qualification requirements.
India
Quick-service restaurant chains and organized retail expansion fuel food-grade bag procurement. BIS migration testing requirements for food-contact materials extend supplier qualification cycles by 8-14 months. Manufacturing corridors in Maharashtra and Gujarat host kraft-paper conversion lines scaling to meet domestic and Middle Eastern export demand.
Vietnam
Export-oriented production for Japanese and Australian retail buyers concentrates procurement activity. Municipal plastic bans across neighboring ASEAN markets redirect regional contract flows toward Ho Chi Minh City-area converters. The manufacturing corridor near the city captures Japanese and Australian retail contract flows through competitive labor costs and port access.
Thailand
Food service chains switching from plastic to paper-based takeaway packaging under the National Plastic Waste Management Roadmap. Mandatory phase-outs of single-use plastics redirect procurement budgets toward certified paper alternatives. SCG Packaging anchors regional supply through captive kraft-paper sourcing from Thai forestry assets and regional converting plants.
Asia-Pacific Paper Bags Market Competitive Environment
Integrated pulp-to-bag operators and specialized regional converters split the market along supply chain control lines. The vendor base clusters around three strategic archetypes: forestry-integrated conglomerates with captive fiber supply, independent converters scaling barrier-coating capabilities, and digital-native printers capturing short-run customization demand. Dominant competitive moves include backward integration into kraft-paper production and geographic expansion through distribution partnerships in ASEAN markets.
Among forestry-integrated operators, Oji Holdings Corporation exemplifies the archetype through Japan and Australia operations. SCG Packaging anchors Southeast Asian supply through Thai-based pulp assets. Mondi Group occupies a position competing on food-grade barrier coatings. These three represent distinct strategic postures: trans-Pacific integrated operations, ASEAN regional captive supply, and specialty coating technology respectively.
| Leading Market Players |
|---|
| Oji Holdings Corporation |
| International Paper Company |
| Smurfit Kappa |
| Mondi Group |
| WestRock Company |
| SCG Packaging |
| Huhtamaki Group |
| Amcor plc |
| Rengo Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Indonesian and Malaysian plantation harvest cycles for kraft fiber concentrate upstream supply, anchoring margin pools with converters who maintain long-term pulp offtake agreements versus spot-market buyers absorbing volatility. Price differentiation across the Asia-Pacific paper bags market hinges on barrier-coating certification tiers and volume scale commitments from retail chains.
Pricing Analysis
Geographic price spreads of 15-25% separate Vietnamese export converters from Australian domestic producers, driven by labor cost arbitrage and port proximity to Japanese buyers. Three-tier pricing structure across premium, standard, and economy levels aligns with BIS food-contact certification status and recycled-content thresholds under Japan's METI mandates. Cost compression in standard-grade kraft bags is intensifying because Indonesian pulp spot markets transmit plantation yield fluctuations directly to converter input costs. Quick-service restaurant chains in Thailand and Malaysia exhibit highest price sensitivity, while Japanese cosmetics brands purchasing short-run digital-print satchels show lowest elasticity.
Supply Chain Analysis
Japan's export-control restrictions on advanced coextrusion barrier-film lamination equipment limit technology transfer to Vietnamese and Thai converters, extending equipment lead times from European and Japanese OEMs. Geographic supply concentration clusters in Vietnam, Thailand, and Australia, with Ho Chi Minh City-area converters capturing Japanese and Australian retail contract flows through competitive labor costs. Raw material dependencies center on Indonesian kraft pulp, Australian bleached fiber for premium grades, and water-based fluorine-free grease-barrier chemistry imports. Single-source vulnerability pervades bleached paper stock for luxury retail applications where Australian pulp mills dominate regional capacity. Distribution runs through supermarket private-label procurement offices in Melbourne and Sydney, fast-casual chain regional headquarters in Singapore, and trading houses serving Japanese department store buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of skilled flexographic pre-press operators for high-definition food-grade printing constrains quality ramp rates across Southeast Asian converter bases, creating acquisition targets and capability-build opportunities for capital deployment.
For Market Incumbents: Insulate margin pools by securing captive kraft-pulp supply from Thai or Indonesian forestry assets before plantation harvest volatility transmits to spot markets. Accelerate BIS certification investment for Indian food-contact material qualification cycles, as 8-14 month migration testing timelines filter out undercapitalized competitors. Barrier-coating chemistry partnerships with Japanese OEMs defend against emerging Vietnamese converters acquiring European lamination technology. For New Entrants and Emerging Players: Mid-tier e-commerce gusseted satchel production for Australian last-mile networks represents the most penetrable entry point, given poly-mailer displacement trends and less stringent barrier-coating requirements versus food-contact segments. Indonesia's archipelago prepared-food delivery pouch demand offers secondary white-space, where underdeveloped cold-chain infrastructure creates insulated paper-based packaging needs. Direct-to-brand digital print contracts with Melbourne and Sydney boutique retailers provide go-to-market traction without intermediary trading house relationships. For Investors and Strategic Acquirers: Capital is best deployed toward Vietnamese and Thai converters with existing Japanese retail buyer relationships and unutilized flexographic capacity, as equipment lead times and pre-press talent scarcity protect installed bases. Long-term viability across the 5-10 year window rests on post-consumer fiber processing integration to satisfy Japan's METI minimum recycled-content thresholds. The signal to watch is BIS certification completion rates among Maharashtra and Gujarat kraft-paper conversion lines, as qualification timeline compression would indicate competitive intensification in Indian food-grade supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft-Pulp Production | Captive fiber supply from Thai forestry assets insulates margin pools from Indonesian plantation harvest volatility. |
| Barrier-Coating Technology Licensing | Water-based fluorine-free grease barriers from Japanese chemistry partners unlock hot-food applications for quick-service chains. |
| Digital Print Capability Expansion | Direct-to-brand short-run contracts with Australian boutique retailers displace traditional converter-distributor relationships. |
| BIS Certification Investment | Food-contact material qualification accelerates access to Indian quick-service restaurant procurement budgets. |
| Regional Distribution Partnership | Ho Chi Minh City port access captures Japanese and Australian retail contract flows through logistics cost arbitrage. |
Study Parameters
A spread of perspectives from kraft-paper mill procurement managers, flexographic converter operations directors, Japanese retail buyer quality auditors, and Indian quick-service restaurant supply chain heads converged on the working assumptions shaping demand trajectories. Primary fieldwork combined structured interviews with secondary validation against customs trade data, BIS certification registries, METI recycling compliance disclosures, and Australian National Packaging Covenant recyclability testing protocols. Bottom-up shipment data from Vietnamese export corridors triangulated against top-down pulp consumption estimates across the analysis window.
Demand-supply-balance framing anchored the analytical framework across product type, material grade, end-use application, and geographic production hub segmentation dimensions. CAGRs derived from regression analysis of historical pulp price elasticity and substitution coefficient modeling for plastic-to-paper conversion rates. Forecast inputs incorporated municipal plastic ban implementation timelines across ASEAN markets and e-commerce parcel volume growth corridors in Australian last-mile networks.
Macroeconomic conditions sit as an overlay; deviation in Indonesian ringgit pulp input costs, Australian dollar export competitiveness, or regional freight rate indices would shift the trajectory. Forecasts reflect documented assumptions on barrier-coating technology adoption curves and BIS certification timeline standardization. Material shifts in Japan's METI recycled-content threshold enforcement or China's SAMR single-use paper product traceability rules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Italy Paper Packaging Market