
 Plastic Toilet Paper Dispenser Market | 2026-2036
Plastic Toilet Paper Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Toilet Paper Dispenser Market Insights
Healthcare and hospitality facility spending is recalibrating procurement priorities toward touchless hygiene infrastructure. Kimberly-Clark leverages its institutional distribution network to sustain shelf presence across North American hospital systems. Essity anchors European demand through direct service contracts with facility management conglomerates. Bobrick competes on specification-grade engineering for high-traffic restroom environments.
Plastic toilet paper dispensers are injection-molded or thermoformed enclosures, typically of ABS, polypropylene, or SAN resin, engineered to house perforated tissue rolls and control dispensing tension while resisting vandalism and moisture ingress. Wall-mounted installation dominates commercial specifications due to space efficiency and cleaning access, while jumbo and high-capacity product types command margin pools through reduced maintenance intervals and bulk purchasing agreements. Online retail channels are gaining traction among mid-size facility operators seeking transparent pricing and rapid replenishment.
EPA guidelines on water-efficient restroom design and FDA Food Code sanitation standards shape product specifications in the United States, while REACH compliance and RoHS substance restrictions govern resin selection across European supply chains. Stakeholders must monitor evolving antimicrobial additive regulations and polymer recycling mandates that will determine material substitution timelines and supplier qualification requirements.
Market Dynamics
Touchless dispensing mechanisms are displacing mechanical lever systems across commercial restroom specifications, driven by post-pandemic hygiene mandates and facility management outsourcing contracts that prioritize reduced maintenance touchpoints.
Growth Catalysts
- EPA WaterSense guidelines:Federal efficiency standards for restroom fixtures are accelerating specification of sensor-activated dispensers that integrate with low-flow infrastructure in US federal buildings and healthcare facilities.
- Antimicrobial resin additives:Silver-ion and copper-based polymer treatments are gaining traction in hospital procurement tenders, particularly for ICU and surgical ward installations where surface bioburden reduction is critical.
- Facility management consolidation:Third-party service providers like ISS and Sodexo are standardizing dispenser fleets across multi-site contracts, creating volume pull for interoperable, high-capacity housing designs.
Market Restraints
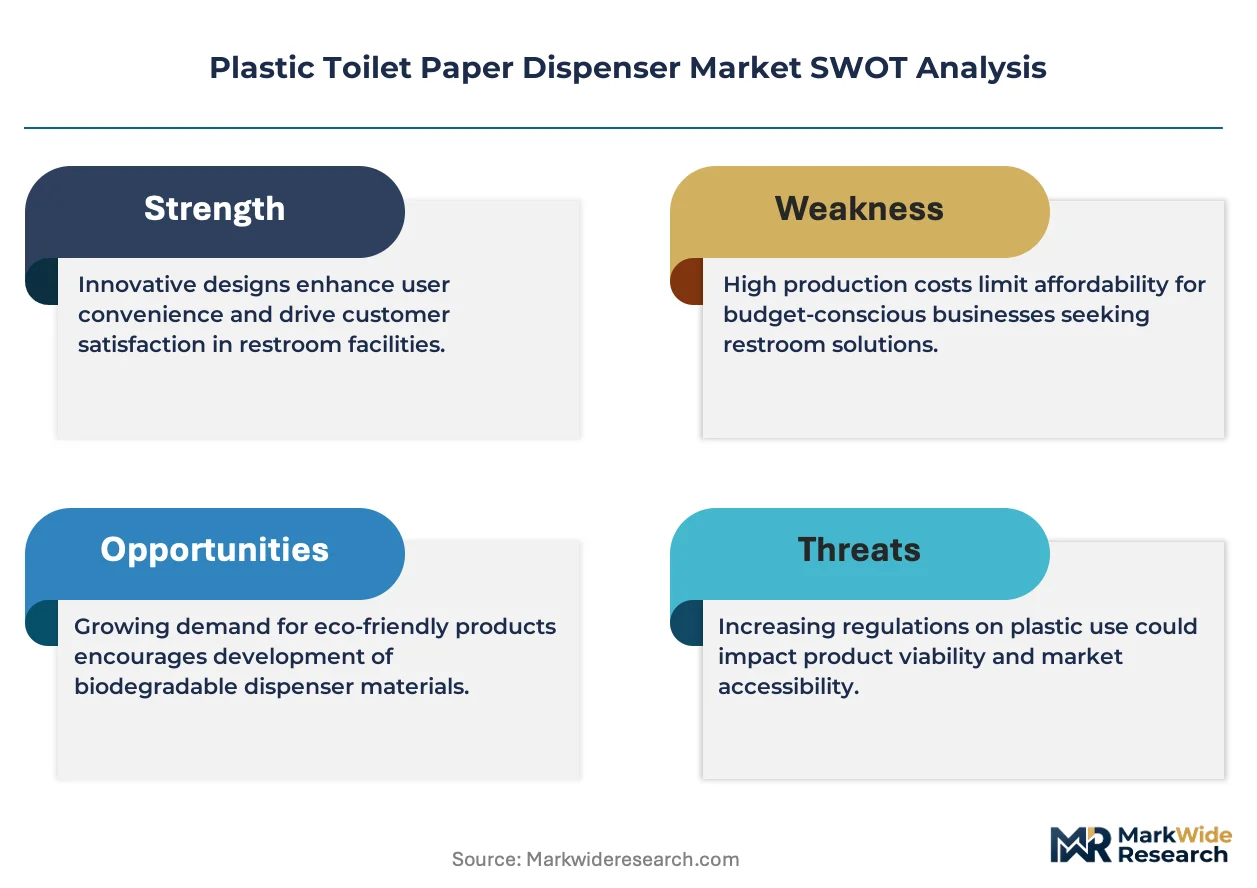
- ABS resin price volatility:Acrylonitrile feedstock costs tied to propylene and ammonia markets create margin compression for injection molders serving price-sensitive municipal segments.
- Single-use plastic directives:EU Single-Use Plastics Directive and emerging state-level bans in California and New York are constraining virgin polymer specifications for non-durable dispenser components.
- Stainless steel substitution:Premium hospitality and high-end commercial segments are migrating toward metal housings for durability and aesthetic differentiation, eroding addressable volume for plastic alternatives.
Strategic Opportunities
- Post-consumer recycled content:rPP and rABS grades certified to UL 2809 are opening specification pathways in LEED-targeted projects where green building points determine vendor selection.
- Smart restroom integration:IoT-enabled dispensers with fill-level sensors are expanding into airport and stadium deployments, enabling predictive restocking and usage analytics for facility operators.
- India commercial real estate:Office stock expansion in Bengaluru and Mumbai is creating first-mover advantage for touch-free infrastructure as Class A developments adopt international hygiene standards.
Industry Challenges
- Antimicrobial additive compliance:EPA FIFRA registration requirements and evolving state-level disclosure mandates for treated articles are extending product development timelines by 8-14 months.
- Legacy mechanical retrofit compatibility:Backward integration with existing wall mounting patterns and spindle dimensions constrains industrial design freedom and slows new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Toilet Paper Dispenser Market |
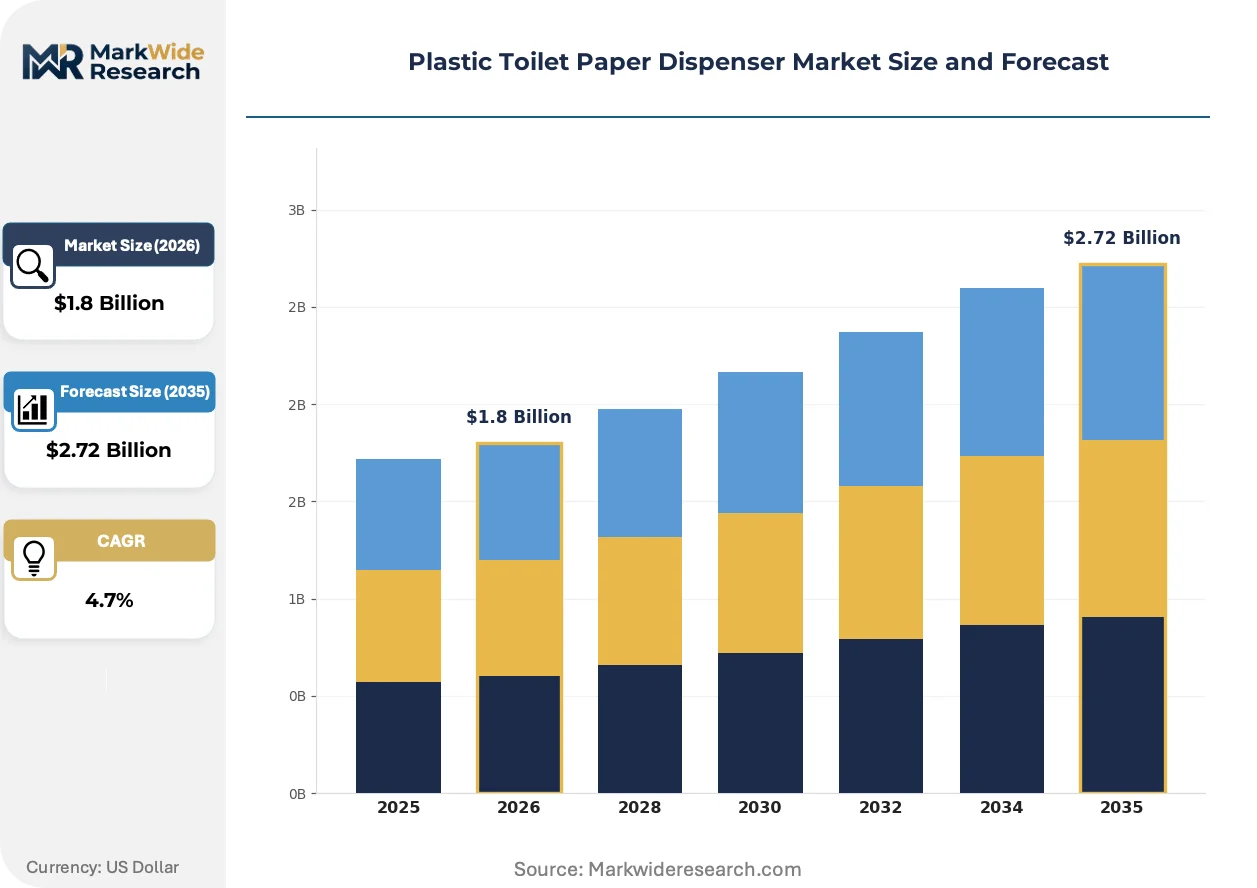
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Mini, Jumbo, High-Capacity End User: Residential, Commercial, Industrial, Institutional Installation Type: Wall-Mounted, Freestanding, Countertop, Recessed Distribution Channel: Online Retail, Wholesale, Direct Sales, Supermarkets |
| Companies Covered | Bobrick, Essity, Kimberly-Clark, Georgia-Pacific, Carlisle (San Jamar), Palmer Fixture, PELLET, Hagleitner Hygiene, Frost, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Toilet Paper Dispenser Market Trends and Innovations
Sensor-activated dispensing architectures are reconfiguring competitive advantage around electronic subsystem reliability rather than purely mechanical durability, compressing traditional supplier qualification criteria.
Thermoformed SAN housings with embedded capacitive proximity sensors are expanding into mid-tier office and educational segments previously served by purely mechanical units. Facility operators in Germany and Japan are specifying these hybrids for 3-5 year replacement cycles that balance capital cost against reduced service labor. The technology is expanding into price-sensitive tiers by enabling modular electronic upgrades without full housing replacement.
REACH Annex XVII restrictions on certain antimicrobial silver compounds are forcing reformulation of treated polymers across European supply chains. Compounders serving dispenser manufacturers are pivoting to zinc-based and organic biocide alternatives that maintain efficacy claims while satisfying ECHA substance evaluations. Nordic hospital systems and Dutch municipal procurement frameworks are most affected, with tender specifications now requiring full material disclosure documentation.
Direct-to-facility e-procurement platforms are fragmenting traditional distribution relationships that relied on janitorial supply intermediaries. Mid-size restaurant chains and regional healthcare networks in the United States are bypassing distributor markups through Amazon Business and specialized B2B marketplaces. This channel compression is most visible among operators managing 10-50 locations where procurement centralization meets minimum order quantity flexibility requirements.
Plastic Toilet Paper Dispenser Market Segmentation
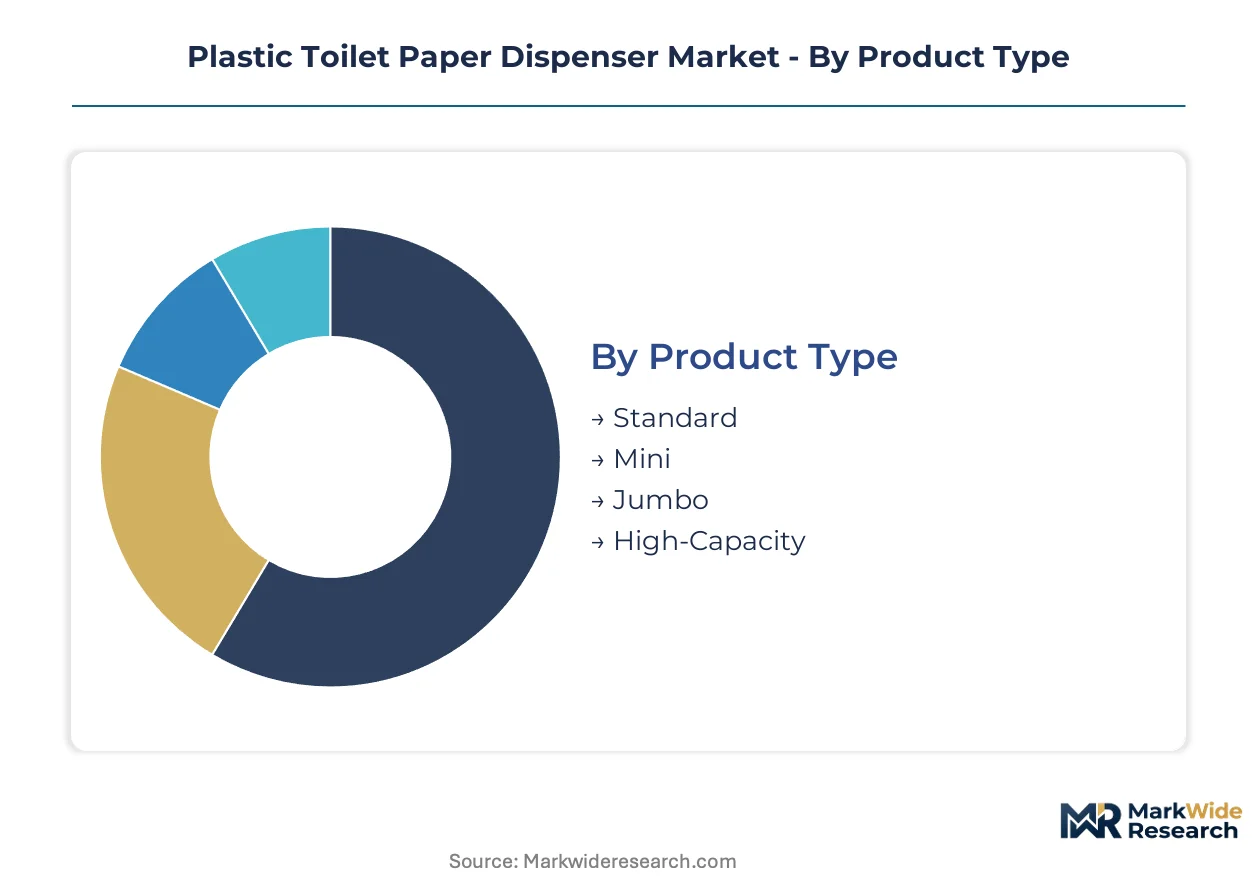
Plastic toilet paper dispenser segmentation reveals how procurement priorities diverge across facility types and operational constraints. Upgrade cycles and specification standards vary dramatically between high-traffic commercial installations and residential replacement markets.
Product Type:
Replacement cycles correlate directly with capacity requirements and maintenance labor economics across facility portfolios.
- Jumbo:These housings accommodate 9-12 inch diameter tissue rolls, reducing service intervals by 60-70% compared to standard formats. Airport terminals and stadium concourses in the United States specify jumbo units under ISS and Sodexo facility management contracts where labor optimization drives procurement decisions.
- High-Capacity:Engineered for 15-20 inch roll diameters with reinforced spindle mechanisms, these units serve extended-stay healthcare and correctional facilities. German hospital systems favor high-capacity ABS housings with antimicrobial additives for psychiatric and long-term care wards where staff access is restricted.
- Standard:Traditional 4-5 inch roll housings dominate residential and small office specifications.
- Mini:Compact units for space-constrained restrooms in older European building stock.
Volume placements concentrate in Jumbo; the faster expansion belongs to High-Capacity.
End User:
Cost tier differentiation separates specification-grade commercial procurement from price-sensitive residential purchasing.
- Commercial:Office complexes, retail chains, and hospitality properties demand vandal-resistant ABS or polypropylene housings with modular electronic upgrade paths. Class A developments in Mumbai and Bengaluru specify touch-free commercial units as hygiene infrastructure benchmarks.
- Institutional:Hospitals, schools, and government facilities prioritize antimicrobial-treated polymers and ADA-compliant mounting heights. EPA WaterSense guidelines shape federal building specifications, while FDA Food Code standards govern healthcare food service installations.
- Residential:Home improvement channels and builder supply contracts drive injection-molded SAN and PP unit sales.
- Industrial:Manufacturing facilities and warehouse operations specify heavy-duty housings for high-abuse environments.
Commercial commands the largest placement volumes; institutional procurement is climbing the fastest.
Installation Type:
Application context determines mounting geometry and cleaning protocol compatibility.
- Wall-Mounted:Space-efficient vertical installation dominates commercial specifications, enabling floor cleaning access and vandalism resistance. Wall-mounted units account for the majority of facility management standardization programs across North American hospital systems.
- Recessed:Flush-mount housings integrated into partition walls serve premium hospitality and executive office segments where aesthetic minimalism commands specification priority.
- Freestanding:Portable units for temporary facilities and event infrastructure.
- Countertop:Compact housings for restroom vanities and powder rooms in residential applications.
Wall-mounted units retain the dominant share; recessed formats are gaining specification traction fastest.
Distribution Channel:
Customer type and order scale fragment traditional supply relationships.
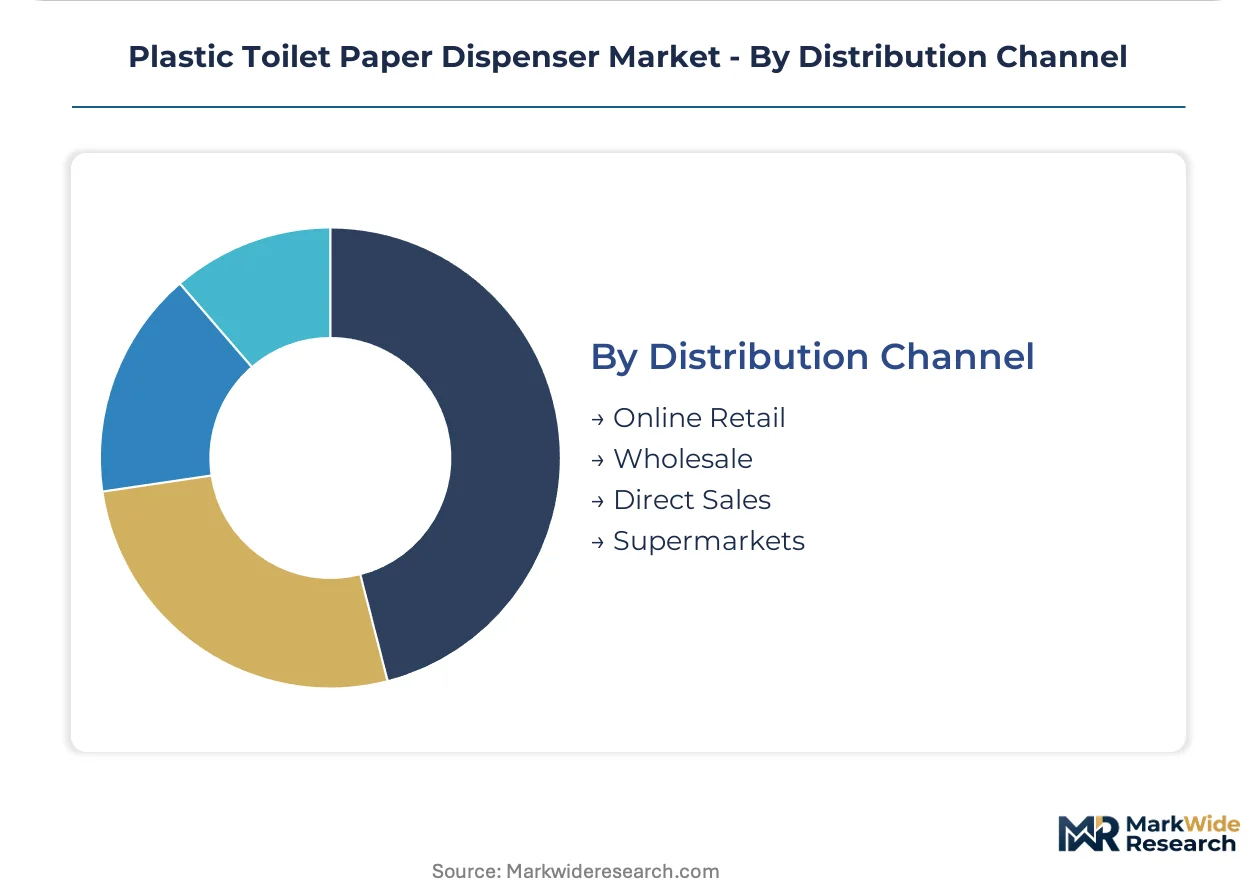
- Online Retail:Amazon Business and specialized B2B marketplaces serve mid-size facility operators managing 10-50 locations. Regional healthcare networks in the United States bypass distributor markups through transparent pricing and rapid replenishment capabilities.
- Wholesale:Janitorial supply intermediaries retain volume relationships with municipal and educational procurement frameworks.
- Direct Sales:Manufacturer contracts with facility management conglomerates like ISS and Sodexo standardize fleet specifications across multi-site portfolios.
- Supermarkets:Mass retail channels serve residential replacement demand and small commercial accounts.
Wholesale maintains the highest transaction volumes; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injection molding capacity clusters in China and Germany, while consumption concentrates across facility-dense corridors in the United States, Japan, and Western Europe. This production-consumption divide shapes trade flows and regional specification standards.
United States
Airport terminals and hospital systems drive specification-grade procurement volumes. EPA WaterSense guidelines and FDA Food Code sanitation standards mandate touch-free infrastructure in federal buildings and healthcare food service zones. Dallas-Fort Worth and Atlanta airport hubs anchor facility management consolidation programs under ISS and Sodexo contracts.
Germany
REACH Annex XVII restrictions on antimicrobial silver compounds force polymer reformulation across dispenser supply chains. ECHA substance evaluations now govern zinc-based biocide alternatives in Nordic hospital tenders. Stuttgart and Munich industrial corridors concentrate injection molding capacity serving European institutional procurement frameworks.
Japan
METI efficiency standards and JIS certification requirements shape product specifications for commercial restroom infrastructure. Tokyo and Osaka facility management markets prioritize 3-5 year replacement cycles balancing capital cost against service labor reduction. Touch-free thermoformed SAN housings penetrate mid-tier office segments previously served by mechanical units.
India
Class A commercial real estate expansion in Bengaluru and Mumbai creates first-mover demand for international hygiene infrastructure standards. BIS certification requirements and green building programs under the CII Indian Green Building Council influence vendor qualification. Maharashtra and Karnataka state procurement frameworks increasingly specify antimicrobial-grade housings for public hospital renovations.
United Kingdom
Facility management outsourcing contracts standardize dispenser fleets across NHS hospital trusts and municipal portfolios. UKCA marking requirements post-Brexit create parallel conformity assessment pathways to CE-marked European products. London and Southeast England commercial property markets specify recessed-mount units for premium hospitality and executive office installations.
Plastic Toilet Paper Dispenser Market Competitive Landscape
Top-tier vendors anchor specification-grade procurement channels, while mid-tier fabricators compete on price-sensitive municipal and residential replacement demand. The vendor base stratifies across three functional tiers: institutional distributors with direct service contracts, engineering specialists serving high-traffic environments, and regional manufacturers supplying price-driven segments. Consolidation pressure intensifies through facility management fleet standardization and antimicrobial additive compliance costs.
Among institutional-grade suppliers, Bobrick and Essity exemplify divergent competitive archetypes. Bobrick occupies a position emphasizing specification-grade engineering for vandal-resistant, high-traffic installations. Essity anchors European demand through direct facility management contracts and polymer formulation expertise. Kimberly-Clark represents the distribution-network archetype, leveraging institutional relationships across North American hospital systems for shelf presence and replenishment scale.
| Leading Market Players |
|---|
| Bobrick |
| Essity |
| Kimberly-Clark |
| Georgia-Pacific |
| Carlisle (San Jamar) |
| Palmer Fixture |
| PELLET |
| Hagleitner Hygiene |
| Frost |
| Others |
Pricing and Supply Chain Analysis
Tool-and-die engineering talent concentration in Stuttgart and Dongguan shapes labor-cost differentials that widen pricing-tier spreads between specification-grade antimicrobial housings and commodity mechanical units. Municipal procurement frameworks in the United States and Germany absorb these spreads through volume aggregation, while fragmented facility operators in emerging markets face steeper premiums for compliant-grade resins.
Pricing Analysis
Margin tightening in economy-tier mechanical dispensers traces to ABS resin feedstock volatility tied to propylene and ammonia markets. Three-tier pricing structure across premium antimicrobial, standard touch-free, and economy mechanical levels separates buyers by certification grade and volume scale. Pricing pressure intensifies in standard tiers as post-consumer recycled content mandates from EPA guidelines and EU directives force material reformulation costs onto molders. Municipal segments exhibit highest price sensitivity; hospital systems and Class A commercial developments show lowest sensitivity due to green building point requirements and infection control budgets.
Supply Chain Analysis
Container freight rate fluctuations between Ningbo and Los Angeles/Long Beach reshape landed cost calculations for injection-molded housings sourced from Chinese manufacturing clusters. Supply concentrates in China, Germany, and the United States, with Guangdong and Zhejiang provinces anchoring mold fabrication and ABS compounding capacity. Raw material dependencies rest on acrylonitrile-butadiene-styrene resin, polypropylene feedstock, and silver-ion antimicrobial masterbatches. Single-source vulnerability concentrates in specialized mold tooling fabricated in Stuttgart and Shanghai industrial corridors. Distribution runs through janitorial supply intermediaries for wholesale volumes, direct manufacturer contracts for facility management conglomerates, and Amazon Business for mid-size operator bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized antimicrobial additive compounding capacity operates as the binding constraint propping pricing power for specification-grade housings. Qualified suppliers face 8-14 month EPA FIFRA registration timelines that throttle new entrant qualification.
For Market Incumbents: Anchor market position through backward integration into antimicrobial masterbatch compounding to capture margin pools eroded by resin price volatility. Defend against stainless steel substitution in premium hospitality by accelerating IoT-enabled dispenser development for predictive restocking contracts. Prioritize capacity addition in India to serve Bengaluru and Mumbai Class A commercial expansion ahead of competitor qualification cycles. For New Entrants and Emerging Players: Enter via post-consumer recycled content certification pathways opening under LEED-targeted projects and CII Indian Green Building Council frameworks where incumbent qualification lags create specification windows. Target mid-size restaurant chains and regional healthcare networks in the United States managing 10-50 locations through Amazon Business and specialized B2B marketplaces. Deploy transparent pricing and rapid replenishment capabilities as the primary go-to-market angle against janitorial supply intermediary markups. For Investors and Strategic Acquirers: Re-rating potential sits with compounders possessing UL 2809 rPP and rABS certification capabilities given accelerating green building procurement mandates across North American and European hospital systems. Long-term viability favors targets with established EPA FIFRA registration dossiers and ECHA substance evaluation compliance for zinc-based biocide alternatives. Monitor antimicrobial additive disclosure mandate progression in California and New York as the signal indicating qualification timeline compression or extension.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Masterbatch Backward Integration | Captures margin pools from silver-ion and zinc-based additive supply chains serving hospital procurement. |
| IoT Sensor Module Development | Enables predictive restocking contracts with ISS and Sodexo facility management standardization programs. |
| Post-Consumer Recycled Content Certification | Opens specification pathways in LEED-targeted federal buildings and CII-IGBC commercial developments. |
| India Manufacturing Footprint Establishment | Positions for Bengaluru and Mumbai Class A office stock expansion under BIS certification requirements. |
| Direct E-Procurement Platform Partnership | Bypasses janitorial supply intermediary markups for mid-size facility operators seeking transparent pricing. |
Research Methodology
Document review covered EPA WaterSense guideline filings, FDA Food Code sanitation standards, ECHA REACH Annex XVII substance restrictions, and facility management contract disclosures, complemented by interviews with injection molding plant managers, antimicrobial compounder technical directors, hospital procurement committee leads, and janitorial supply distribution channel heads. Secondary validation drew from customs trade data, SEC 10-K filings of resin suppliers, and green building certification databases. Bottom-up demand modeling triangulated against top-down facility stock and replacement cycle estimates.
Segment-level projections across product type, end user, installation format, and distribution channel dimensions were generated through elasticity-calibrated extrapolation over the projection horizon. CAGRs were derived from logistic adoption curves for touch-free mechanisms and linear replacement cycle assumptions for mechanical units. Industry-specific forecast inputs incorporated ISS and Sodexo fleet standardization contract velocities, EPA WaterSense federal building mandate penetration rates, and EU Single-Use Plastics Directive compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ABS resin price spike scenarios or accelerated state-level antimicrobial additive disclosure mandates. Forecasts reflect documented assumptions regarding facility management outsourcing growth and green building certification adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Paperboard Bowl Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Liquid Packaging Board Market
Paper & Paperboard Packaging
Disposable Paper Cups Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market