
 Coated Recycled Boxboard Market | 2026-2036
Coated Recycled Boxboard Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Recycled Boxboard Market Outlook
Modular packaging configurations is pivoting buyer preference toward lightweight, foldable coated board structures that cut shipping cube and warehouse footprint. Graphic Packaging International leverages its integrated mill network to sustain coated board supply across North American consumer goods corridors. Smurfit Kappa anchors European demand through recycled fiber specialization and regional converting density. Pratt Industries dominates the US Southeast with vertically controlled recycled pulp streams that feed coated boxboard lines.
Coated recycled boxboard consists of multi-ply paperboard manufactured from recovered fiber, finished with a clay or mineral pigment coating that yields a printable surface with brightness levels typically exceeding 80 percent. This material serves primary packaging applications where structural rigidity, print fidelity, and sustainability credentials must coexist. Folding boxboard captures the dominant volume position across food and beverage end uses, where grease resistance and freezer-grade performance command premium positioning. Solid bleached board occupies specialized pharmaceutical and personal care segments where visual purity and barrier precision justify higher unit economics. Uncoated grades face margin compression as brand owners migrate toward printable coated surfaces that eliminate secondary labeling steps.
The US EPA guides recycled content thresholds for packaging materials through post-consumer fiber minimums, while the EU Green Deal's packaging and packaging waste regulation tightens material recovery obligations across member states. FDA food contact substance notifications govern coating chemistries for direct-contact food applications in the United States. Stakeholders must monitor evolving extended producer responsibility frameworks and coating chemistry restrictions that will determine which substrate-converter combinations retain market access across jurisdictions.
Market Dynamics
EU Green Deal packaging waste directives are compressing plastic substrate demand while accelerating fiber-based substitution across consumer goods supply chains. Converter networks in industrial corridors now compete on just-in-time coated board availability rather than price alone.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory material recovery obligations across member states are forcing brand owners to specify recycled fiber minimums in primary packaging tenders.
- Modular packaging configurations:Consumer electronics manufacturers are specifying lightweight foldable boxboard structures that reduce shipping cube by eliminating void fill requirements.
- Germany's industrial packaging corridor:Dense converter clustering around Düsseldorf and Hamburg enables same-day coated board delivery to food and beverage bottling operations.
Market Restraints
- Recovered fiber price volatility:Post-consumer pulp costs fluctuate with municipal collection program funding levels and export demand from Asian paper mills.
- Clay coating chemistry restrictions:FDA food contact substance notifications and EFSA evaluations are narrowing approved mineral pigment portfolios for direct food contact applications.
- Barrier performance ceiling:Coated recycled boxboard cannot match multilayer plastic oxygen transmission rates required for extended shelf-life meat and dairy packaging.
Strategic Opportunities
- Pharmaceutical serialization mandates:EU Falsified Medicines Directive and US DSCSA track-and-trace requirements are creating demand for printable coated surfaces with integrated authentication features.
- Freezer-grade coated board:Food service distributors are specifying moisture-resistant recycled fiber solutions for frozen meal kit delivery channels.
- Extended producer responsibility frameworks:French and Italian packaging fee structures are incentivizing mono-material fiber designs that simplify post-consumer sorting infrastructure.
Industry Challenges
- Coating line retrofit capex:Converting legacy uncoated board capacity to clay-coated production requires drying section upgrades exceeding typical mid-cap balance sheet thresholds.
- Color consistency across recovered fiber batches:Print buyers in cosmetics and premium confectionery are rejecting lot-to-lot brightness variation that exceeds brand guideline tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Recycled Boxboard Market |
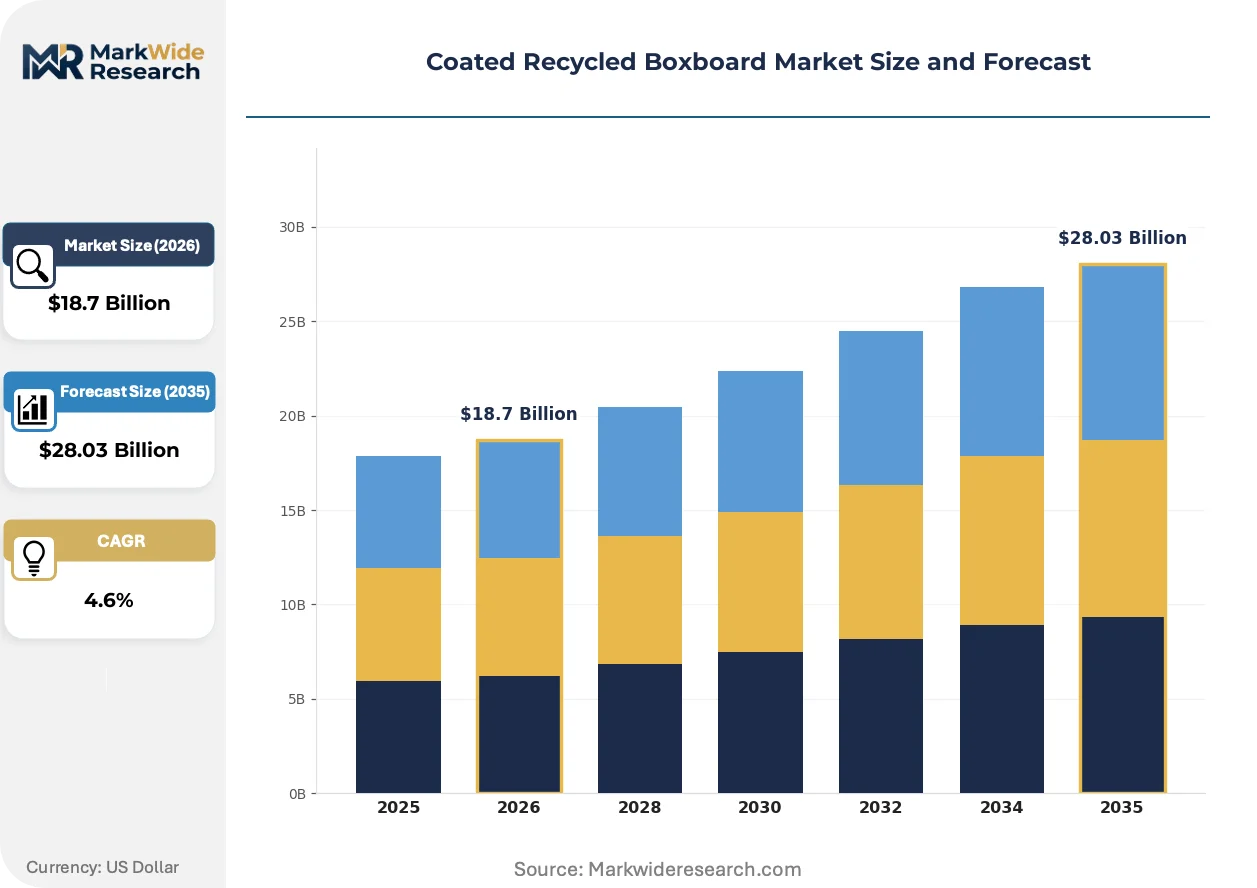
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Board, Uncoated Board, Folding Boxboard, Solid Bleached Board End User: Food & Beverage, Consumer Electronics, Pharmaceuticals, Personal Care Application: Packaging, Display, Graffiti, Crafting Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | WestRock, Graphic Packaging International, Smurfit Kappa, Sonoco, Caraustar Industries, PaperWorks Industries, International Paper Company, Pratt Industries, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Recycled Boxboard Market Strategic Shifts
Digital printing compatibility is reshaping specification criteria as brand owners compress packaging design-to-shelf cycles. Coating chemistries and surface finishes now prioritize ink adhesion and variable-data readability over traditional offset optimization.
Water-based barrier coatings are unifying grease resistance and recyclability in a single substrate layer. Quick-service restaurant chains are specifying these formulations for sandwich clamshells and fry cartons to meet franchise sustainability scorecards. The technology is unifying previously separate plastic liner and paperboard supply chains into single-source fiber procurement.
EU Green Deal packaging waste regulation revisions are tightening recycled content verification requirements through mass-balance accounting standards. Third-party certification bodies are expanding audit capacity to handle brand owner compliance documentation. Food and beverage multinationals with pan-European distribution are most affected and are consolidating supplier bases to reduce audit fragmentation.
Brand owner packaging engineering teams are embedding sustainability metrics into supplier scorecards beyond unit cost. Procurement functions now weight carbon footprint data and post-consumer recovery rates equally with price and lead time. This behavioral shift is most visible in German and French consumer goods headquarters where sustainability-linked compensation structures have taken hold.
Coated Recycled Boxboard Market Segmentation
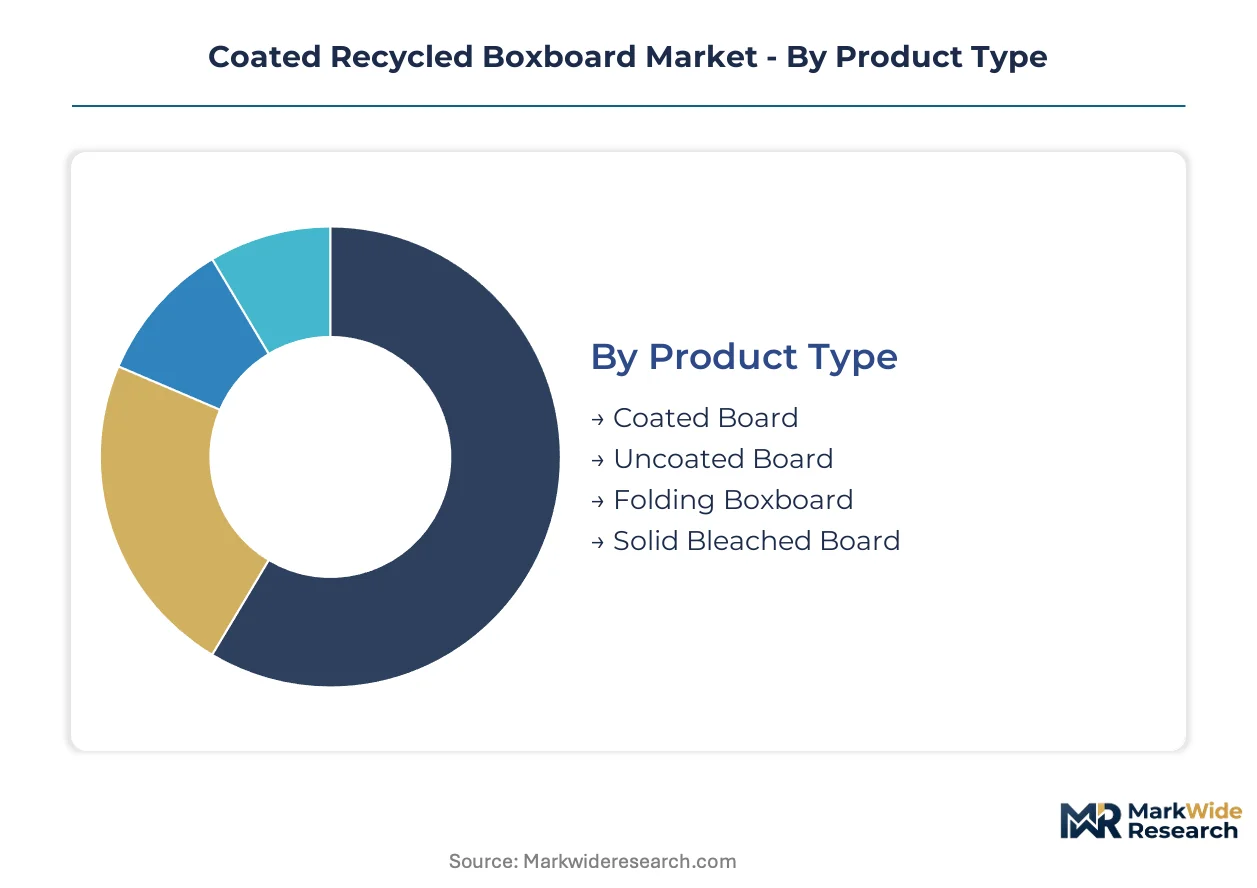
Coated recycled boxboard specifications diverge sharply between high-volume commodity grades and premium performance variants. Brand owners select substrates based on print fidelity requirements, barrier performance, and end-of-life recovery pathways. Converter capabilities and coating line configurations further constrain specification choices across regional supply bases.
Product Type:
Volume applications favor lower-cost uncoated and standard coated constructions, while premium positioning demands folding boxboard and solid bleached alternatives with superior surface characteristics.
- Folding Boxboard:Multi-ply construction with bleached chemical pulp surface layers and mechanical pulp core delivers structural rigidity at reduced grammage. Food and beverage bottling operations in Germany's industrial corridor specify this grade for lightweight secondary packaging that withstands palletization stress. EU Green Deal packaging waste directives are accelerating specification shifts toward this recyclable mono-material substrate.
- Coated Board:Clay or mineral pigment surface coating over recycled fiber base yields brightness levels exceeding 80 percent with optimized ink adhesion. Consumer electronics brands specify this grade for retail-ready packaging where shelf impact and sustainability credentials must coexist. Digital printing compatibility is reshaping coating chemistry specifications toward faster drying and variable-data readability.
- Solid Bleached Board:Virgin fiber construction delivers visual purity and precise barrier performance for pharmaceutical and personal care applications. FDA food contact substance notifications govern coating chemistries for direct-contact uses.
- Uncoated Board:Lower-cost recycled fiber construction without surface coating faces margin compression as brand owners migrate toward printable surfaces that eliminate secondary labeling steps.
Today's leader: Folding Boxboard. Tomorrow's challenger: Solid Bleached Board.
End User:
Application-specific performance requirements create distinct procurement patterns across consumer-facing industries, with regulatory compliance and brand sustainability commitments driving specification divergence.
- Food & Beverage:Grease resistance and freezer-grade performance command premium positioning for folding boxboard in quick-service restaurant chains and frozen meal kit channels. Water-based barrier coatings are unifying grease resistance and recyclability in single-substrate sandwich clamshells and fry cartons.
- Consumer Electronics:Modular packaging configurations specify lightweight foldable boxboard structures that reduce shipping cube by eliminating void fill requirements. Brand engineering teams embed carbon footprint metrics into supplier scorecards alongside unit cost.
- Pharmaceuticals:EU Falsified Medicines Directive and US DSCSA track-and-trace requirements create demand for printable coated surfaces with integrated authentication features.
- Personal Care:Print buyers in cosmetics reject lot-to-lot brightness variation exceeding brand guideline tolerances, forcing coating line investment and process control upgrades.
Food & Beverage commands current volume. Consumer Electronics offers the steepest expansion trajectory as modular packaging gains adoption.
Application:
Functional use cases determine substrate specifications, with packaging applications dominating volume and display applications demanding premium surface characteristics.
- Packaging:Primary and secondary containment applications account for dominant volume consumption across all product grades. Extended producer responsibility frameworks in France and Italy incentivize mono-material fiber designs that simplify post-consumer sorting infrastructure.
- Display:Point-of-sale and retail fixture applications require superior print fidelity and structural integrity for short-run promotional campaigns. Digital printing compatibility enables compressed design-to-shelf cycles for seasonal merchandise.
- Graffiti:Specialized protective backing applications for urban art and temporary surface protection represent niche volume with distinct abrasion resistance requirements.
- Crafting:Hobby and educational market segments prioritize low-cost availability over performance specifications, typically sourcing through wholesale distributors and retail channels.
Packaging absorbs the majority of coated board output. Display applications are gaining specification priority as retail media networks expand.
Distribution Channel:
Supply chain configuration determines lead time reliability and minimum order economics, with converter density and mill proximity shaping channel selection.
- Direct Sales:Large-volume brand owners with predictable demand patterns contract directly with integrated mill-converter operations for just-in-time coated board availability. Pratt Industries and Graphic Packaging International anchor these relationships through captive pulp streams and regional converting density.
- Wholesalers:Mid-cap converters and regional packaging operations source through distribution networks that aggregate fragmented demand and provide technical specification support.
- Online:E-commerce procurement platforms serve small-batch and specialty grade requirements with extended lead times and higher unit economics.
- Offline:Traditional broker and agent networks persist in markets with fragmented converter bases and complex import documentation requirements.
Direct sales dominate strategic accounts. Wholesalers are consolidating as mid-cap buyers seek technical support and inventory pooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coated recycled boxboard manufacturing originated in German industrial corridors during the post-war paperboard consolidation, where converter density and chemical engineering expertise established the sector's technical foundations. European regulatory frameworks subsequently diffused these production standards across member states. Today's geographic footprint reflects pulp availability, converter clustering, and packaging waste policy stringency.
Germany
Food and beverage bottling operations in the Düsseldorf-Hamburg corridor drive specification-grade folding boxboard procurement. EU Green Deal packaging waste directives mandate recycled fiber minimums that German converters meet through integrated mill networks. Dense converter clustering enables same-day coated board delivery to just-in-time manufacturing operations.
United States
Consumer electronics brands in California and Texas specify modular packaging formats that reduce shipping cube through lightweight foldable structures. FDA food contact substance notifications govern coating chemistries for direct-contact food applications across state boundaries. Pratt Industries anchors Southeast supply through vertically controlled recycled pulp streams feeding coated boxboard lines.
China
Export-oriented consumer goods manufacturing in the Yangtze River Delta generates demand for retail-ready coated board with print fidelity and sustainability credentials. The country's national environmental regulator enforces dual carbon goals that accelerate fiber-based substitutions for plastic substrates. Converter networks in Shanghai and Jiangsu province compete on coating line capacity and digital printing compatibility.
France
Extended producer responsibility frameworks in French packaging fee structures incentivize mono-material fiber designs that simplify post-consumer sorting infrastructure. ANSM and national food safety authorities evaluate coating chemistries for pharmaceutical and personal care applications. Industrial packaging corridors around Paris and Lyon concentrate converter operations serving pan-European distribution networks.
India
Quick-service restaurant chains and frozen meal kit channels in Maharashtra and Gujarat specify water-based barrier coatings that unify grease resistance and recyclability. BIS standards and FSSAI regulations govern food contact packaging materials and recycled content thresholds. Converter density in Mumbai-Pune and Ahmedabad industrial belts supports regional coated board supply for domestic consumer goods brands.
Coated Recycled Boxboard Market Competitive Environment
Premium-margin players sit above commodity-margin players across coating technology sophistication and captive pulp integration. The market structure consolidates around integrated mill-converter operations that control recovered fiber streams and regional distribution density. Three archetypes dominate: vertically integrated giants with captive pulp supply, specialty converters focused on premium grades, and regional players serving fragmented local demand. Competitive moves center on coating line retrofit capacity and strategic partnerships with brand owners seeking just-in-time availability.
Within the integrated mill-converter tier, WestRock and Graphic Packaging International exemplify archetypes that anchor North American supply through controlled fiber streams and regional converting density. Smurfit Kappa occupies a position representing European recycled fiber specialization and converter network concentration. These three entities collectively illustrate how geographic pulp sourcing and coating line configuration determine competitive positioning across jurisdictions with diverging packaging waste regulations.
| Leading Market Players |
|---|
| WestRock |
| Graphic Packaging International |
| Smurfit Kappa |
| Sonoco |
| Caraustar Industries |
| PaperWorks Industries |
| International Paper Company |
| Pratt Industries |
| Stora Enso |
| Others |
Value Chain & Pricing Dynamics
Food and beverage brand owners with pan-European distribution networks negotiate contract-based long-term offtake agreements that lock in coated recycled boxboard supply against volatile post-consumer pulp costs. EU Green Deal packaging waste directives compress substitution economics for plastic substrates, shifting procurement priority from unit price to carbon footprint-adjusted total cost of ownership.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs coated recycled boxboard transactions, with solid bleached board commanding premium positioning for pharmaceutical applications while uncoated grades face persistent margin compression. Price differentiation rests on FDA food contact certification tiers and volume scale commitments from converter networks. Cost compression in standard-grade folding boxboard is intensifying because recovered fiber price volatility feeds directly into converter pass-through clauses. Quick-service restaurant chains exhibit highest price sensitivity due to franchisee-owned procurement, whereas pharmaceutical multinationals prioritize barrier precision over unit economics.
Supply Chain Analysis
Freight cost differentials between German industrial corridors and Asian export hubs reshape sourcing decisions for consumer electronics brands with modular packaging specifications. Geographic supply concentrates in Germany, the United States, and China, where integrated mill-converter operations control captive recycled pulp streams. Raw material dependencies center on post-consumer OCC collections, clay mineral pigments, and water-based barrier coating chemistries. Single-source vulnerability pervades specialized coating line capacity for pharmaceutical-grade solid bleached board. Distribution runs through direct sales relationships with large-volume brand owners and wholesaler networks aggregating mid-cap converter demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coated recycled boxboard offers margin expansion through premium-tier solid bleached board substitution for pharmaceutical serialization mandates and water-based barrier coating adoption in frozen meal kit channels.
For Market Incumbents: Acquire specialized coating line capacity in Germany's Düsseldorf-Hamburg corridor to defend against emerging water-based barrier specialists threatening food service distributor relationships. Integrate backward into post-consumer OCC collection infrastructure to neutralize recovered fiber price volatility eroding standard-grade margins. Prioritize FDA food contact substance notification investment for direct-contact food applications where regulatory compliance creates switching costs. For New Entrants and Emerging Players: Regional frozen meal kit distributors with unmet freezer-grade coated board specifications represent the most penetrable buyer archetype for water-based barrier coating specialists. Target Maharashtra and Gujarat industrial belts in India where BIS standards enforcement lags behind EU Green Deal stringency, creating specification arbitrage opportunities. Pursue technical partnership routes with quick-service restaurant chains seeking unified grease-resistant recyclability scorecard compliance. For Investors and Strategic Acquirers: Integrated consumer goods conglomerates with captive packaging engineering teams are the most active acquirer in this space, seeking coating technology capabilities for sustainability-linked procurement scorecards. Long-term viability hinges on mass-balance accounting certification capacity as EU packaging waste regulation tightens verification requirements. Monitor French and Italian extended producer responsibility fee structure revisions as inflection indicators for mono-material fiber design premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Retrofit for Water-Based Barriers | Enables quick-service restaurant chains to meet franchise sustainability scorecards without plastic liner dependency. |
| Backward Integration into OCC Collection | Pratt Industries anchors Southeast US supply through captive recycled pulp streams feeding coated boxboard lines. |
| Pharmaceutical Serialization Certification | EU Falsified Medicines Directive and US DSCSA create demand for printable coated surfaces with authentication features. |
| Regional Converter Network Consolidation | Smurfit Kappa leverages European recycled fiber specialization and dense converter clustering around Düsseldorf. |
| Mass-Balance Accounting Audit Capacity | Third-party certification bodies expand documentation handling for brand owner EU Green Deal compliance requirements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mill operations directors, converter procurement leads, brand owner packaging engineers, and coating chemistry R&D specialists with secondary validation against SEC 10-K filings, EU packaging waste directive documentation, and trade flow data from paperboard industry associations. Bottom-up volume modeling across product grades and end-use segments triangulated against top-down macroeconomic demand indicators.
Comparable-period anchoring linked projection assumptions to historical reference intervals across the analysis window, with segmentation modeling spanning product type, end-use industry, application function, and distribution channel dimensions. CAGRs derived from regression analysis of installed coating line capacity, recovered fiber cost trajectories, and regulatory compliance cost absorption rates. Forecast inputs incorporated EU Green Deal implementation timelines and FDA food contact substance notification approval velocities.
Underlying measurement precision varies by segment; solid bleached board pharmaceutical applications carry tighter precision than commodity uncoated grades due to concentrated buyer transparency. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity for plastic substrates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Kraft Envelopes Market