
 Australia Paper Packaging Market | 2026-2036
Australia Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Paper Packaging Market Outlook
Food and beverage manufacturers is reorganizing procurement priorities toward fiber-based protective formats, pulling demand away from traditional industrial buyers. Visy Industries Holdings Pty Ltd dominates containerboard production across southeastern Australia with integrated pulp-to-box operations. Amcor plc leverages global R&D networks to develop high-barrier paper solutions for chilled protein segments. Orora Limited anchors beverage multipack and wine shipping formats through specialized corrugated engineering.
Australia paper packaging comprises cellulose-fiber structures typically ranging from 150 to 450 gsm, formed through kraft pulping or recycled furnish processing into corrugated board, folding cartons, and flexible wraps designed to contain, protect, and present goods through distribution and retail channels. Recycled paper and kraft paper grades lead volume consumption due to cost positioning and compatibility with existing converting equipment, while duplex board commands premium placement in personal care and electronics end uses where print fidelity and structural rigidity justify higher unit economics. Boxes and cartons represent the mature core of installed capacity, whereas bags and wraps capture accelerated growth from quick-commerce and fresh produce formats requiring lightweight, breathable fiber solutions.
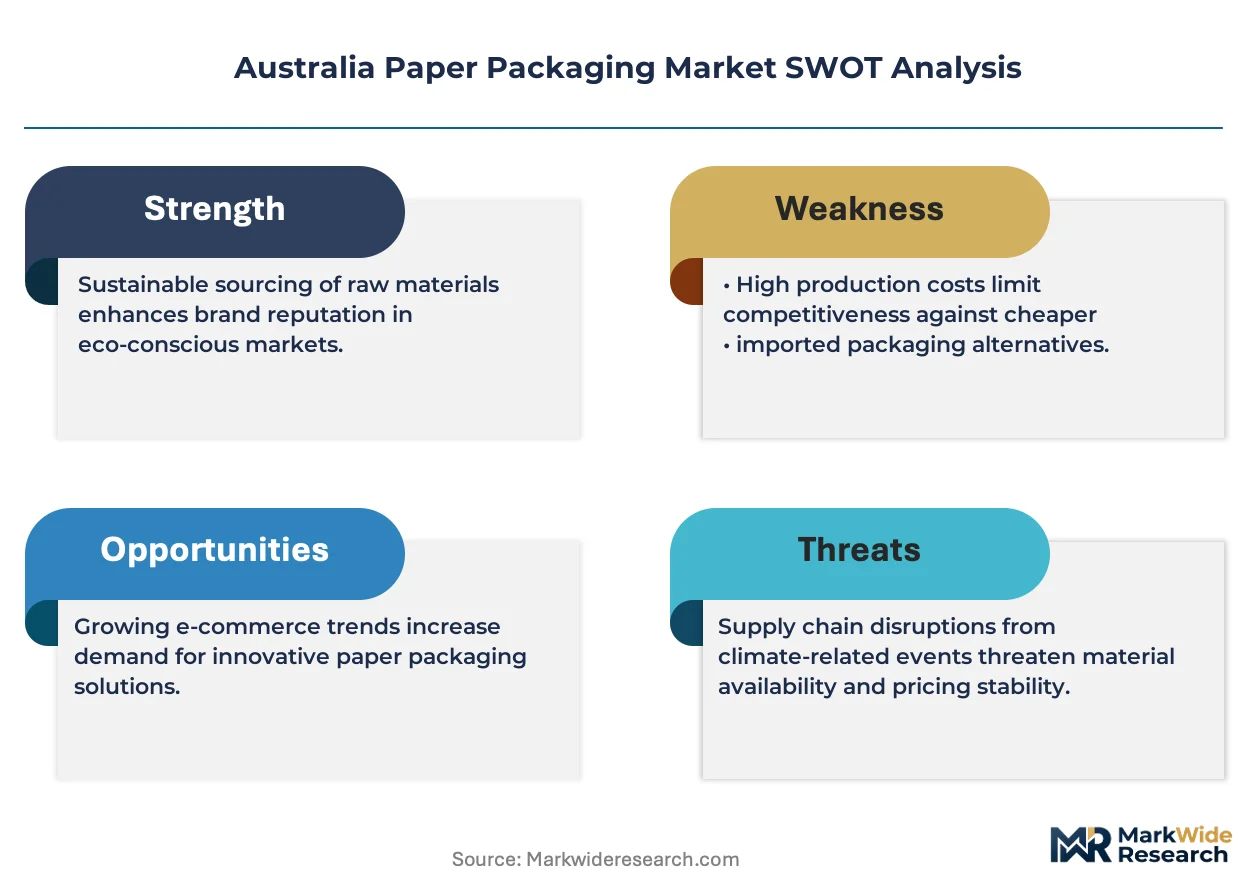
The Australian Packaging Covenant Organisation enforces voluntary industry commitments toward circular design, while the Australian Competition and Consumer Commission monitors environmental claims to prevent greenwashing that distorts buyer decision-making. TGA labeling requirements for pharmaceutical and personal care exports additionally constrain material selection and barrier performance specifications for paper-based primary packaging. Stakeholders must monitor pending state-level plastic phase-out timelines that could abruptly expand addressable demand for fiber substitutes in categories still dependent on polymer films.
Market Dynamics
Food and beverage manufacturers are pulling procurement away from traditional industrial buyers toward fiber-based protective formats, while New South Wales and Victoria concentrate converting capacity and e-commerce fulfillment demand. This demand reorganization is compressing legacy supply relationships and forcing converters to retool for shorter-run, higher-variety production.
Growth Catalysts
- Australia's 2025 National Packaging Targets:The 70% recycling recovery mandate is forcing brand owners to specify recycled-content paper grades, pulling volume toward domestic reprocessors.
- Quick-commerce logistics:Melbourne and Sydney fulfillment networks require lightweight, breathable fiber wraps for fresh produce delivery, opening new demand for 150-200 gsm kraft specifications.
- Kraft pulping technology:Advanced semi-chemical processes are enabling higher-strength board from lower-grade recycled furnish, reducing raw material cost volatility for integrated producers.
Market Restraints
- Recovered fiber price volatility:Old corrugated container (OCC) supply fluctuates with Chinese import policy changes, squeezing converter margins during tight collection periods.
- High-barrier coating limitations:Water-based and bio-based barrier technologies still fail chilled protein shelf-life requirements, blocking full plastic displacement in premium meat segments.
- TGA pharmaceutical labeling:Export packaging for therapeutic goods faces strict stability documentation requirements that paper-based primary packs struggle to satisfy without polymer laminates.
Strategic Opportunities
- Queensland and Western Australia underpenetration:These states lack integrated pulp-to-box capacity, creating white space for regional converting investment serving mining and agricultural equipment markets.
- Wine export cold-chain formats:Specialized insulated corrugated engineering for Asian market shipments commands premium pricing above standard beverage multipacks.
- State-level plastic phase-out timelines:Pending bans on single-use polymer films in fresh produce will abruptly expand addressable demand for fiber-based breathable bags.
Industry Challenges
- Corrugated structural engineering talent:Specialized design for e-commerce damage prevention requires finite element analysis skills scarce in traditional box plants.
- Barrier coating line capex:Water-based high-barrier application equipment demands seven-figure investments with uncertain payback given regulatory approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Paper Packaging Market |
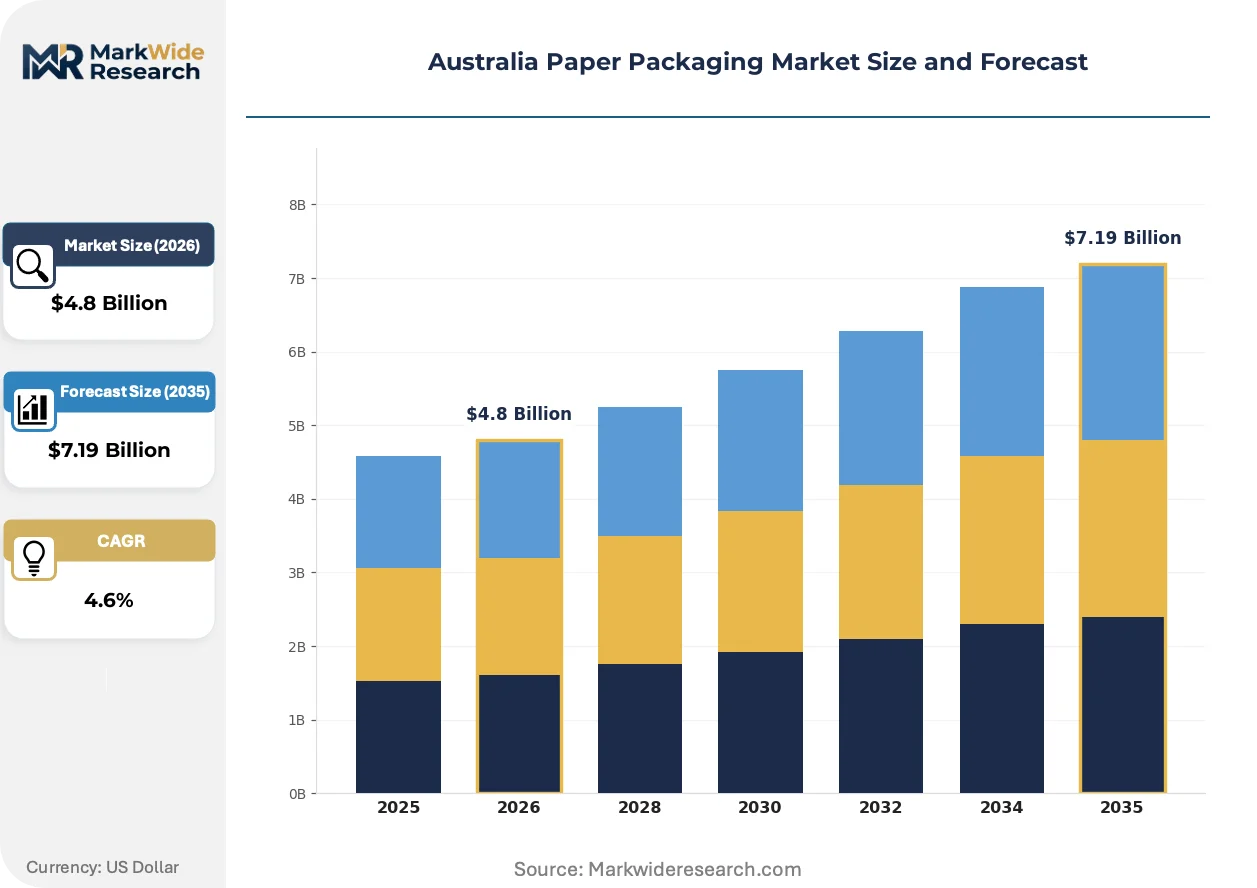
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Cartons, Wraps End User: Food & Beverage, Personal Care, Electronics, Consumer Goods Material Grade: Recycled Paper, Kraft Paper, Virgin Paper, Duplex Board Packaging Type: Flexible, Rigid, Die-Cut, Blister |
| Companies Covered | Pact Group Holdings, Smurfit WestRock, Amcor plc, Nippon Paper Industries Co., Ltd., Mondi plc, Orora Limited, Pro-Pac Packaging Limited, International Paper Company, Visy Industries Holdings Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Paper Packaging Market Strategic Shifts
Active innovation in the Australia paper packaging market centers on three vectors: barrier technology evolution, regulatory compliance automation, and fulfillment-optimized structural design. These forces are compressing product development cycles and rewiring buyer-supplier relationships.
Water-based and bio-based barrier coatings are fragmenting the traditional polymer-laminate monopoly in chilled food applications. Foodservice distributors are piloting these formats for ready-meal trays at accelerating pace. The technology is fragmenting incumbent supply relationships by enabling local converters to compete with imported barrier films.
The Australian Packaging Covenant Organisation is tightening enforcement of circular design commitments while the Australian Competition and Consumer Commission intensifies greenwashing surveillance. Brand owners now face dual compliance pressure: meeting recovery rate targets while substantiating environmental claims with third-party documentation. Pharmaceutical and personal care exporters face the strictest documentation burdens under TGA labeling requirements.
Direct-to-consumer fulfillment is forcing structural redesign of corrugated specifications toward damage-rate metrics rather than stacking strength alone. Quick-commerce platforms in Sydney and Melbourne are specifying custom board grades optimized for courier handling rather than palletized distribution. This behavioral shift is most visible in fresh produce and meal-kit verticals where return rates directly impact platform economics.
Australia Paper Packaging Market Segmentation
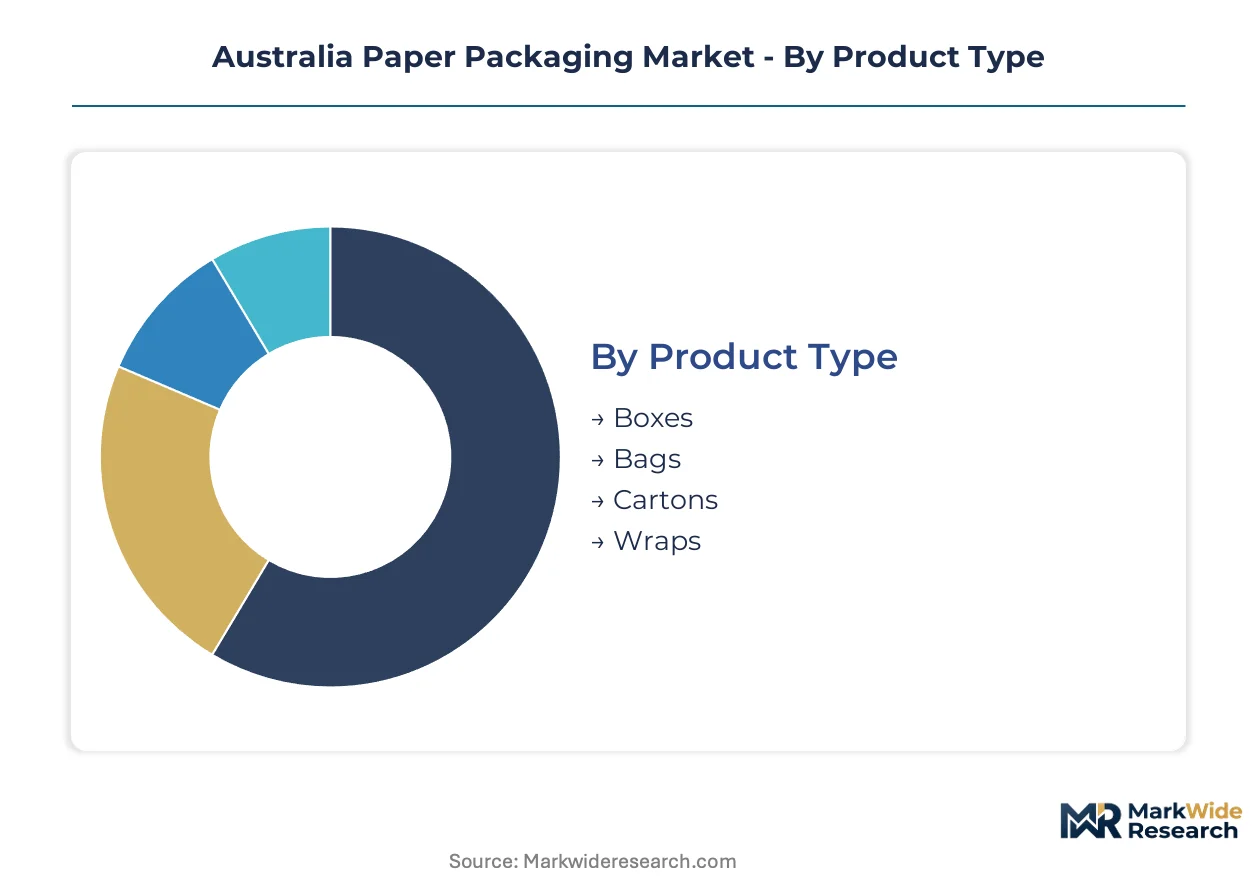
Segmentation in Australia's paper packaging market reveals how procurement patterns split between industrial-scale buyers and fragmented e-commerce channels. Understanding these divides exposes where converters must retool capacity versus defend legacy positions.
Product Type:
Channel mix varies sharply: corrugated boxes flow through palletized distribution to industrial food processors, while bags and wraps penetrate quick-commerce fulfillment networks demanding single-unit handling.
- Boxes:Corrugated fiberboard structures from 200-450 gsm dominate beverage multipacks and industrial food containment. New South Wales and Victoria concentrate converting capacity for this segment, with Visy Industries and Orora Limited anchoring supply to major FMCG accounts.
- Bags:Lightweight 150-200 gsm kraft specifications serve fresh produce and meal-kit verticals where breathability reduces spoilage. Melbourne and Sydney fulfillment networks are pulling procurement toward shorter-run, higher-variety production of these formats.
- Cartons:Folding carton grades command premium placement in personal care and electronics retail packaging where print fidelity drives shelf differentiation.
- Wraps:Flexible fiber wraps capture accelerated growth from quick-commerce platforms specifying damage-rate metrics over traditional stacking strength.
Boxes dominate installed base. Bags and wraps are where expansion concentrates.
End User:
Cost tier segmentation separates commodity procurement from premium specification: food and beverage buyers prioritize unit economics at volume, while electronics and personal care accept higher per-unit costs for structural rigidity and barrier performance.
- Food & Beverage:The largest volume segment spanning chilled protein, ready-meals, and beverage multipacks. Australia's 2025 National Packaging Targets mandate 70% recycling recovery rates, forcing brand owners toward recycled-content specifications and compressing legacy supply relationships.
- Personal Care:Premium folding cartons and duplex board applications where TGA labeling requirements for exports constrain material selection and barrier documentation.
- Electronics:Anti-static corrugated and precision die-cut inserts requiring finite element analysis skills scarce in traditional box plants.
- Consumer Goods:Diverse specifications spanning promotional displays and retail-ready packaging, with demand fragmenting across shorter production runs.
Food and beverage anchors volume throughput. Personal care commands the steepest expansion trajectory for high-barrier paper solutions.
Material Grade:
Volume concentration favors cost-positioned recycled and kraft grades compatible with existing converting equipment, while margin capture shifts toward duplex board in premium export applications.
- Recycled Paper:Post-consumer reclaimed fiber processed into corrugated medium and linerboard. Old corrugated container supply fluctuates with Chinese import policy changes, squeezing converter margins during tight collection periods across southeastern Australia.
- Kraft Paper:Unbleached virgin fiber from semi-chemical pulping delivers superior tear resistance for heavy-duty industrial applications and agricultural equipment markets in Queensland and Western Australia.
- Virgin Paper:Bleached chemical pulp for food-contact primary packaging requiring purity certification under Australian Competition and Consumer Commission surveillance of environmental claims.
- Duplex Board:Coated white-top board combining recycled core with virgin surface ply, justifying higher unit economics in personal care and electronics where print fidelity matters.
Recycled paper and kraft paper dominate installed capacity. Duplex board is where margin expansion concentrates.
Packaging Type:
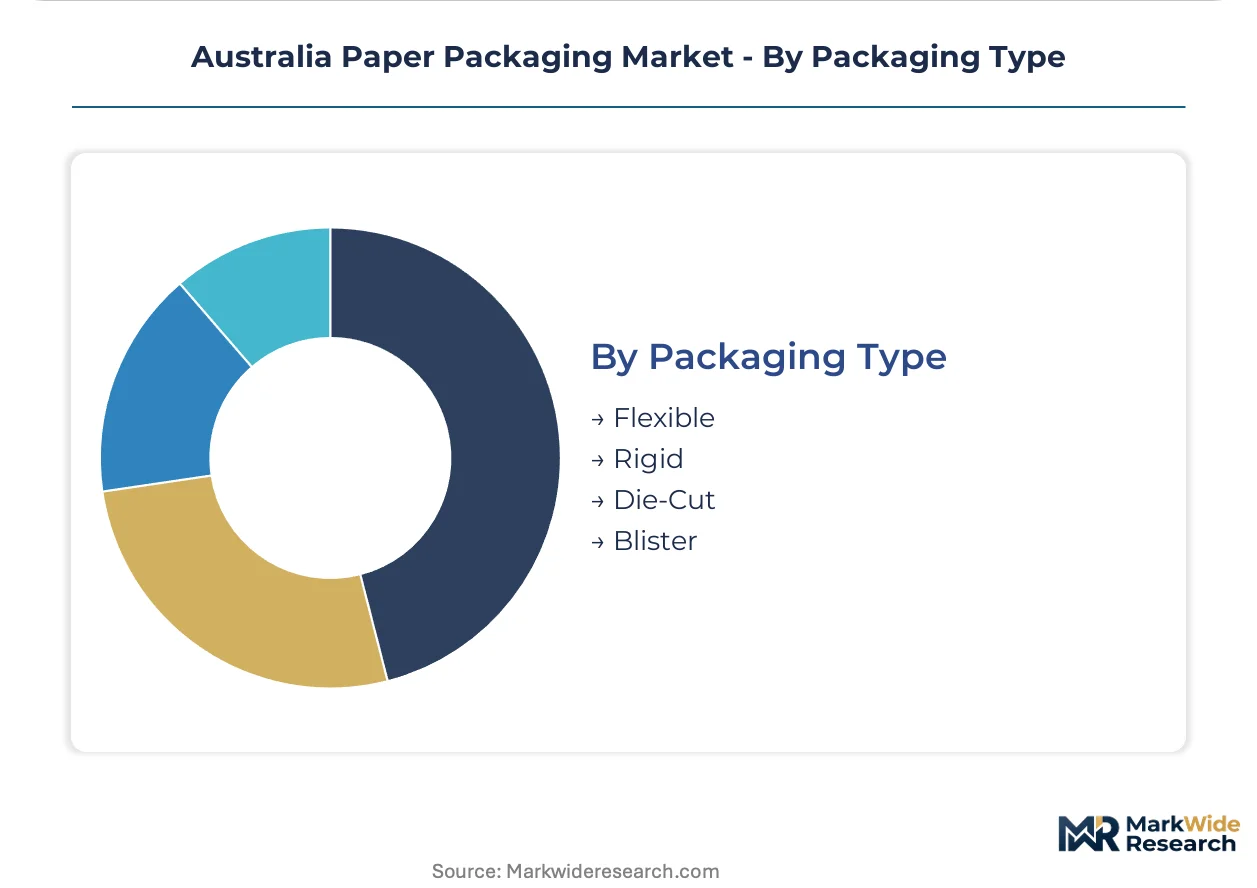
Application requirements dictate structural approach: flexible and rigid formats split between containment function and protection intensity, while die-cut and blister variants serve specialized display and retail-ready needs.
- Flexible:Lightweight fiber wraps and pouches gaining share in fresh produce quick-commerce where breathability reduces return rates. Water-based barrier coatings are fragmenting traditional polymer-laminate supply relationships.
- Rigid:Corrugated and solid board structures for palletized distribution and stacking strength. E-commerce damage prevention is forcing redesign toward courier-handling specifications.
- Die-Cut:Precision-engineered inserts and retail-ready displays requiring CAD structural design capabilities and seven-figure barrier coating line investments.
- Blister:Limited fiber-based penetration due to thermoforming requirements; paper-fiber hybrid formats emerging for pharmaceutical compliance under TGA stability documentation.
Rigid formats dominate installed base. Flexible packaging is where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated pulp-to-box capacity clusters heavily in southeastern states, while converting demand spreads across mining belts and agricultural zones. New South Wales and Victoria host the dominant reprocessing infrastructure and e-commerce fulfillment networks. Queensland and Western Australia present expansion corridors for regional converters serving equipment and produce markets.
New South Wales
Sydney's fulfillment networks drive specification demand for courier-optimized corrugated grades. The Australian Packaging Covenant Organisation enforces circular design commitments that brand owners must document. Parramatta and western Sydney logistics clusters are retooling box plants for shorter-run, higher-variety production to serve quick-commerce platforms.
Victoria
Melbourne anchors beverage multipack and chilled protein packaging demand through specialized corrugated engineering. TGA labeling requirements constrain material selection for pharmaceutical exports from Port of Melbourne. The city's southeastern industrial corridor concentrates die-cutting and high-barrier coating investments for ready-meal applications.
Queensland
Brisbane and regional mining centers generate heavy-duty industrial packaging demand for equipment and machinery. The state's 2025 National Packaging Targets compliance timeline pressures brand owners toward recycled-content specifications. Gold Coast and Sunshine Coast agricultural zones are pulling procurement toward breathable fiber wraps for fresh produce distribution.
Western Australia
Perth's isolation from eastern reprocessors creates supply chain cost premiums for corrugated board. The Australian Competition and Consumer Commission monitors environmental claims to prevent greenwashing in export packaging. Kwinana industrial precinct and Pilbara mining operations represent white space for regional converting investment serving bulk commodity containment.
South Australia
Adelaide's wine export corridor demands specialized insulated corrugated engineering for Asian cold-chain shipments. State-level plastic phase-out timelines are accelerating fiber-based breathable bag trials in fresh produce. The city's northern manufacturing belt is piloting water-based barrier coatings for ready-meal tray applications.
Australia Paper Packaging Market Competitive Environment
Concentration sits with integrated producers controlling pulp supply through captive reprocessing infrastructure. The market structures around three tiers: global diversified packaging conglomerates with Australian subsidiaries, domestic integrated fiberboard specialists, and regional converters serving niche industrial applications. Competitive moves center on backward integration into recovered fiber collection networks and strategic partnerships with quick-commerce platforms for fulfillment-optimized structural design.
Among Australia-based integrated specialists, Visy Industries Holdings Pty Ltd and Orora Limited exemplify the pulp-to-box archetype with southeastern converting dominance. Amcor plc occupies a position representing global R&D-backed barrier technology deployment for premium food segments. Smurfit WestRock and Mondi plc sit within the multinational tier leveraging cross-border scale for kraft linerboard supply security.
| Leading Market Players |
|---|
| Pact Group Holdings |
| Smurfit WestRock |
| Amcor plc |
| Nippon Paper Industries Co., Ltd. |
| Mondi plc |
| Orora Limited |
| Pro-Pac Packaging Limited |
| International Paper Company |
| Visy Industries Holdings Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between integrated producers and FMCG brand owners lock in both recovered fiber supply access and corrugated board price visibility across southeastern Australia. These arrangements insulate converters from Old corrugated container volatility while binding buyers to minimum volume commitments under Australia's 2025 National Packaging Targets compliance timeline.
Pricing Analysis
Australia's 2025 National Packaging Targets dictate the pricing tier structure across the paper packaging value chain. Three-tier pricing structure across premium, standard, and economy levels separates virgin-grade duplex board for personal care exports from recycled-content corrugated for industrial food containment and unbleached kraft for agricultural equipment markets. Price differentiation hinges on certification grade under Australian Competition and Consumer Commission surveillance and volume scale commitments. Pricing pressure stems from Chinese import policy fluctuations on recovered fiber, squeezing converter margins during tight collection periods. Quick-commerce platforms exhibit highest price sensitivity due to damage-rate metric specifications, while wine export cold-chain formats show lowest sensitivity given premium positioning for Asian market shipments.
Supply Chain Analysis
New South Wales and Victoria anchor containerboard production through integrated pulp-to-box operations serving FMCG and beverage multipack demand. Raw material flows draw from domestic Old corrugated container collection networks, semi-chemical kraft pulp processing, and imported bleached chemical pulp for food-contact grades. Supply chain risk centers on single-source vulnerability for high-barrier coating equipment where water-based application technology remains concentrated among limited specialized engineering providers. Distribution runs through palletized industrial channels to food processors alongside direct fulfillment network feeds for Melbourne and Sydney quick-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier coating technical service contracts represent a faster-expanding recurring revenue layer than commodity board production, as converters seek regulatory compliance support alongside equipment installation.
For Market Incumbents: Fortify backward integration into recovered fiber collection networks across southeastern Australia to secure Old corrugated container supply against Chinese import policy volatility. Invest in finite element analysis capability for e-commerce structural engineering to defend against specialized design boutiques capturing quick-commerce platform relationships. Prioritize certification documentation systems that streamline Australian Packaging Covenant Organisation compliance for brand owner accounts. For New Entrants and Emerging Players: Australian Packaging Covenant Organisation fast-track certification enables rapid credibility establishment for regional converters entering Queensland and Western Australia mining equipment markets. Target breathable fiber wrap production for Gold Coast and Sunshine Coast agricultural zones where state-level plastic phase-out timelines are accelerating procurement shifts. Pursue co-development partnerships with quick-commerce platforms seeking courier-optimized corrugated specifications rather than competing on commodity board pricing. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale converters possessing captive recovered fiber supply and established quick-commerce platform relationships over pure-play equipment manufacturers. Long-term viability favors assets with demonstrated barrier coating line operational experience given seven-figure capex requirements and uncertain regulatory approval timelines. Monitor TGA labeling requirement evolution for pharmaceutical exports as inflection indicator for high-barrier paper solution addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Collection | Secures Old corrugated container supply against Chinese import policy volatility squeezing converter margins. |
| High-Barrier Coating Line Investment | Enables water-based barrier technology deployment for chilled protein segments under Australian Competition and Consumer Commission surveillance. |
| Quick-Commerce Platform Partnership | Locks in demand for courier-optimized corrugated specifications specified by Melbourne and Sydney fulfillment networks. |
| Regional Converting Capacity Expansion | Captures mining and agricultural equipment demand in Queensland and Western Australia underpenetrated zones. |
| Finite Element Analysis Capability Buildout | Addresses structural engineering talent scarcity for e-commerce damage prevention specifications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, Australian Packaging Covenant Organisation compliance filings, and SEC disclosures from multinational packaging conglomerates. Primary interviews engaged corrugated plant managers, FMCG procurement leads, quick-commerce logistics directors, and barrier coating equipment specialists across Sydney, Melbourne, and Brisbane industrial corridors. Secondary validation drew from Australian Bureau of Statistics manufacturing output data, state-level environmental regulator enforcement records, and containerboard trade flow databases. Bottom-up volume modeling triangulated against top-down value estimates derived from producer revenue disclosures.
Segmentation dimensions modeled span product type, material grade, end-use industry, packaging format, and state-level regulatory cluster across the analysis window. CAGRs were derived from regression analysis against historical production data and forward projection of compliance-driven specification shifts. Industry-specific forecast inputs incorporated Australian 2025 National Packaging Targets recovery rate mandates and pending state-level plastic phase-out timeline implementation schedules.
Decision-makers should treat outputs as directional under assumptions of stable Chinese recovered fiber import policy and consistent Australian Packaging Covenant Organisation enforcement intensity; material deviation would warrant model refresh. Specific risk factors include abrupt regulatory acceleration on plastic displacement, barrier coating technology performance failures in chilled protein shelf-life testing, and TGA labeling requirement tightening for pharmaceutical exports. Recalibration cycles align with material shifts in national packaging target enforcement and state-level environmental regulation adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Paperboard Bowl Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Foam Cups Market