
 Europe Fireproof Cladding Market | 2026-2036
Europe Fireproof Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fireproof Cladding Market Intelligence
Public infrastructure and commercial building refurbishment is rebalancing the Europe fireproof cladding demand profile away from new residential construction. Rockwool International A/S leverages its stone wool expertise to dominate specification in Nordic public sector tenders. Saint-Gobain Construction Products UK Limited anchors supply relationships with major French social landlords through localized manufacturing.
Europe fireproof cladding encompasses facade systems engineered to resist flame spread and maintain structural integrity under standardized fire exposure, typically incorporating mineral fiber, cementitious, or metal composite substrates with A1 or A2 reaction-to-fire ratings per EN 13501. These assemblies protect building envelopes while managing thermal performance and moisture dynamics across varied European climate zones. Mineral fiber cladding leads specification in high-rise remediation where non-combustibility mandates apply most stringently, while prefabricated panel systems represent the fastest-growing installation method as contractors seek to compress on-site labor hours and reduce weather-dependent scheduling risk.
The EU Green Deal's renovation wave targets interact with ECHA scrutiny of halogenated flame retardants and national implementations of the Construction Products Regulation to reshape material compliance pathways. Etex Group navigates these overlapping requirements through dual certification across BS 476 and EN 13501 frameworks, extending market access across post-Brexit UK and continental procurement channels. Stakeholders must monitor divergence between British and EU conformity assessment procedures as a decisive factor in pan-European product platform economics.
Market Dynamics
The EU Green Deal's building renovation wave is compressing compliance timelines for facade systems across member states. EN 13501 reaction-to-fire classifications now function as gatekeepers for public procurement, forcing material substitutions ahead of schedule.
Growth Catalysts
- France's social housing renovation mandate:National programs targeting tower block remediation are specifying A1-rated mineral fiber cladding at scale. Public landlords face binding deadlines to replace combustible facade materials.
- EN 13501-1 classification tightening:Updated testing protocols for external wall assemblies are disqualifying previously acceptable B-rated materials. Certification bodies are reporting backlog surges for A2-s1,d0 submissions.
- Stone wool manufacturing advances:Continuous fiber production techniques are reducing panel density without sacrificing fire resistance. Nordic producers are capturing specification share in German healthcare construction.
Market Restraints
- Aluminum composite panel stock overhang:Pre-2017 installations of polyethylene-cored ACM continue depressing replacement demand in UK residential towers. Remediation funding gaps delay project starts.
- Baltic basalt supply concentration:Premium stone wool feedstock depends on limited quarry operations in Finland and Lithuania. Geopolitical friction elevates input cost volatility.
- REACH authorization timelines:ECHA scrutiny of halogenated flame retardants is forcing formulation changes mid-certification cycle. Manufacturers face dual compliance costs during transition periods.
Strategic Opportunities
- Polish industrial retrofit pipeline:Warehouse and logistics facility construction is accelerating specification of non-combustible envelope systems. EU cohesion funds are subsidizing facade upgrades in Silesian manufacturing zones.
- Prefabricated panel installation methods:Offsite fabrication of complete facade assemblies is compressing on-site labor hours. Dutch contractors are piloting crane-lifted modules for high-rise remediation.
- EU Taxonomy alignment incentives:Green bond financing for renovation projects favors materials with verified lifecycle carbon data. Manufacturers with EPD certification are securing preferential specification status.
Industry Challenges
- Fire testing laboratory capacity:EN 13823 single-burning item test queues extend beyond twelve months at notified bodies. Manufacturers face launch delays for new substrate formulations.
- Installer certification fragmentation:National schemes for facade system installation vary across Germany, France, and the UK. Cross-border project execution requires redundant workforce credentials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fireproof Cladding Market |
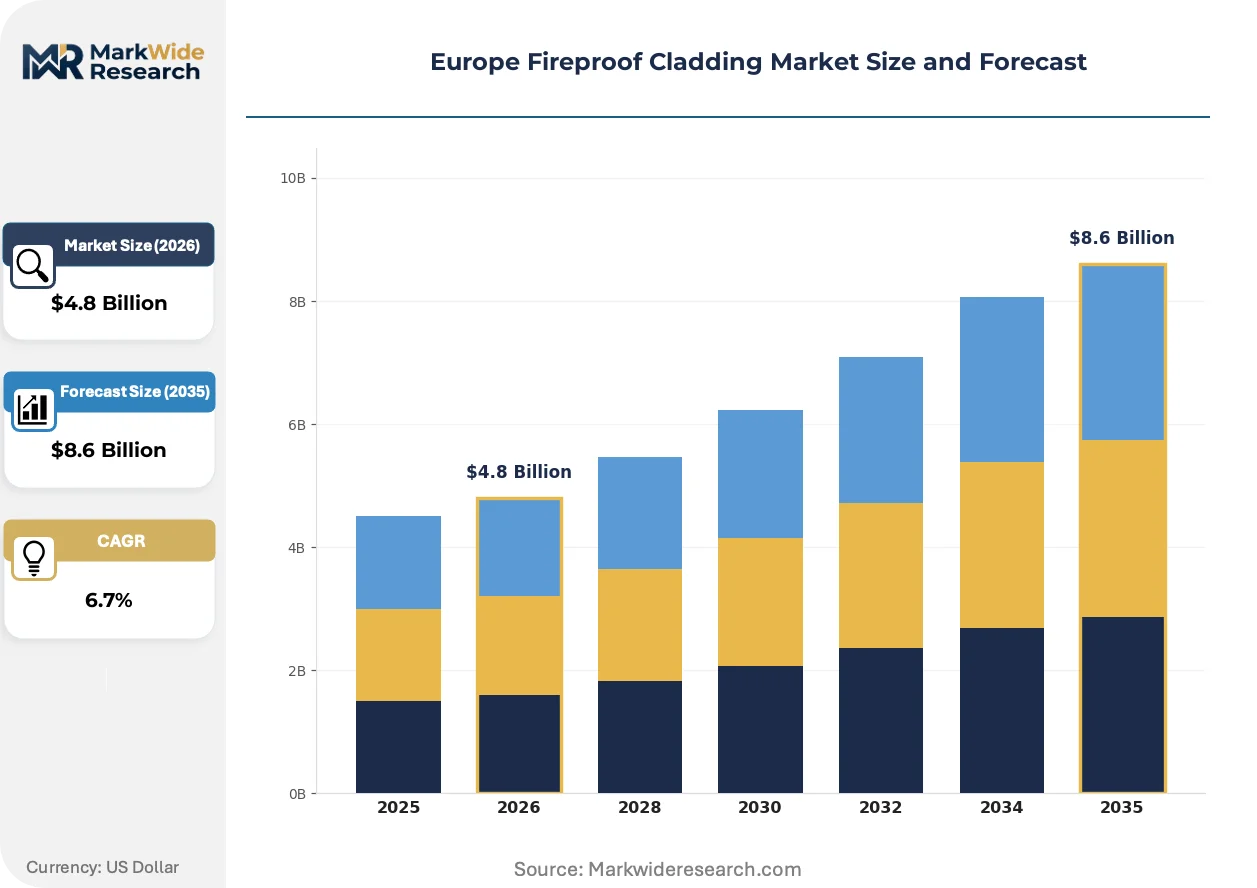
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Fiber, Metal Composite, Cement Board, High-Performance Insulation Installation Method: Mechanical Fastening, Adhesive Bonding, Rain Screen, Prefabricated Panels End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Public Infrastructure Certification Standard: BS 476, EN 13501, ISO 834, ASTM E119 |
| Companies Covered | James Hardie Europe GmbH, Saint-Gobain Construction Products UK Limited, Knauf Gips KG, Rockwool International A/S, Promat, Owens Corning, Kingspan Group, 3A Composites Holding AG, Etex Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fireproof Cladding Market Strategic Shifts & Innovations
Digital fabrication and material science convergence are redefining fireproof cladding performance thresholds. Specification decisions increasingly weight embodied carbon alongside reaction-to-fire ratings.
Aerogel-enhanced mineral fiber composites are integrating silica-based thermal barriers into conventional stone wool matrices. German window-wall manufacturers are specifying these hybrids for passive house retrofits requiring sub-U-value performance. The technology is integrating fire resistance and thermal efficiency into single-source envelope solutions, compressing supplier count per project.
The EU Construction Products Regulation's system 1+ conformity assessment is mandating factory production control audits for A1-classified materials. Spanish cementitious board producers are restructuring quality assurance departments to accommodate annual surveillance visits. High-rise remediation contractors in London are prioritizing suppliers with existing system 1+ certificates to avoid procurement delays.
Social housing landlords are consolidating specification authority at portfolio level rather than project level. French HLM organizations are negotiating framework agreements covering multi-year renovation programs. This concentration is displacing architect-led material selection with procurement-driven standardization, favoring manufacturers with pan-European service networks.
Europe Fireproof Cladding Market Segmentation
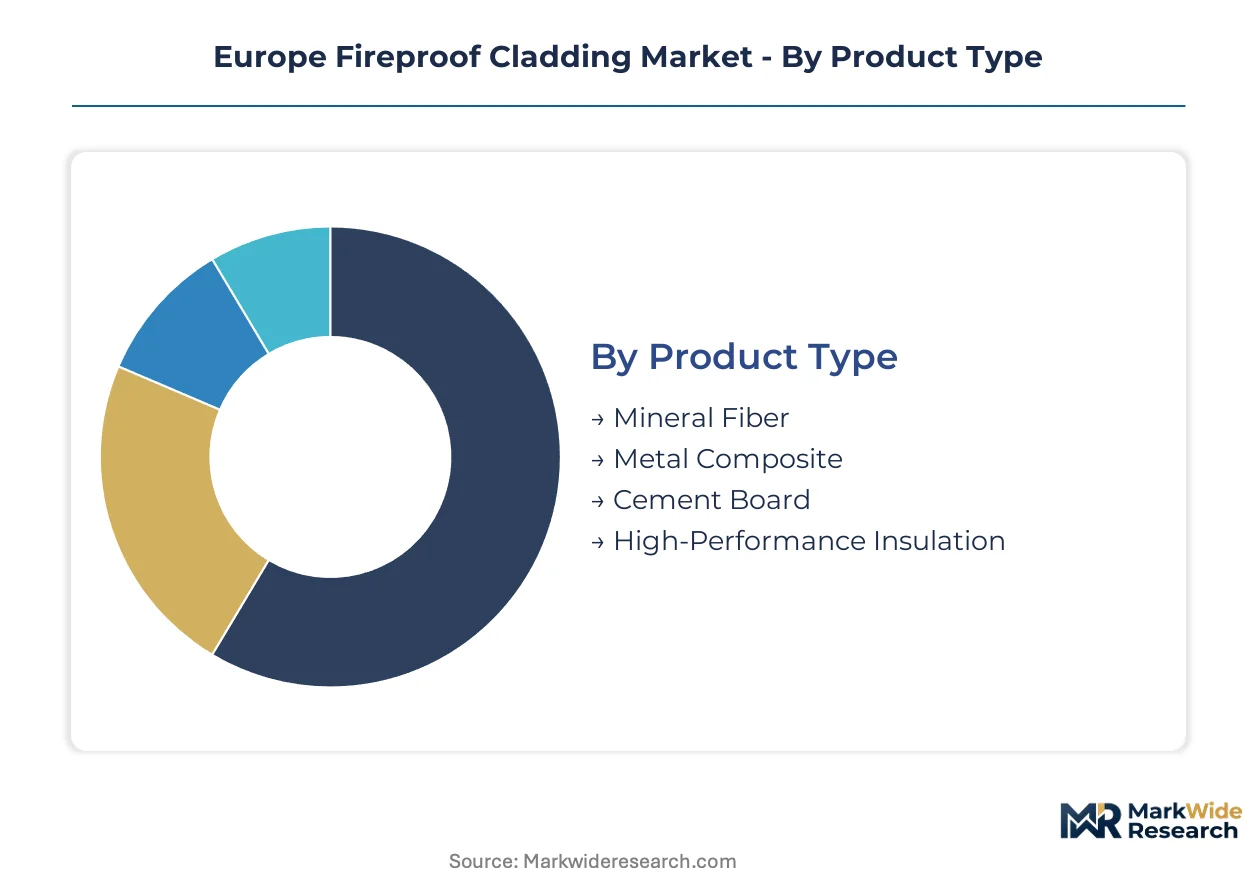
Fireproof cladding procurement in Europe diverges sharply by substrate chemistry and installation logistics. Specification committees weight capital deployment against fire-test certification timelines and facade access constraints.
Product Type:
Mineral fiber and metal composite systems demand the heaviest upfront manufacturing investment in continuous fiber production lines and coil coating infrastructure.
- Mineral Fiber:Stone wool and glass wool matrices achieve A1 non-combustibility ratings through basalt and recycled slag fusion. French social housing renovation mandates specify these systems for tower block remediation where EN 13501-1 compliance is binding.
- Metal Composite:Aluminum-zinc coated steel and aluminum honeycomb assemblies integrate fire-resistant mineral cores between metallic skins. UK high-rise remediation contractors prioritize these for rapid installation in constrained urban sites.
- Cement Board:Fiber-reinforced calcium silicate panels deliver moisture resistance alongside fire ratings. Nordic healthcare construction specifies these for envelope durability in freeze-thaw cycles.
- High-Performance Insulation:Aerogel-enhanced and vacuum-insulated panels compress thermal conductivity while maintaining reaction-to-fire thresholds. German passive house retrofits drive specification of these premium systems.
Mineral fiber absorbs the bulk of installed capacity; high-performance insulation is expanding most quickly.
Installation Method:
Prefabricated panel and rain screen approaches dominate project pipelines where labor scarcity and weather risk compress construction schedules.
- Mechanical Fastening:Visible and concealed clip systems anchor cladding to substrate through stainless steel brackets. German facade contractors favor these for stone wool panel installation in healthcare construction.
- Adhesive Bonding:Cementitious and polymer-modified mortars bond lightweight panels directly to masonry backup. French HLM organizations specify these for social housing retrofits with limited structural capacity.
- Rain Screen:Pressure-equalized cavity systems manage moisture drive while accommodating thermal movement. Dutch high-rise remediation projects deploy these for behind-cladding ventilation.
- Prefabricated Panels:Factory-assembled complete facade units integrate insulation, weather barrier, and finish in single lifts. Polish logistics facility construction is accelerating specification of these systems for speed-to-occupancy.
Mechanical fastening retains the largest installed base; prefabricated panels are climbing the fastest as contractors seek to decouple facade installation from on-site weather exposure.
End User:
Public infrastructure and industrial facility procurement concentrates volume through multi-year framework agreements rather than project-by-project tendering.
- Residential Buildings:Multi-family tower remediation and new mid-rise construction specify A1-rated systems under national fire safety programs. UK building safety regulator enforcement drives replacement of pre-2017 combustible installations.
- Commercial Buildings:Office and retail envelope upgrades prioritize thermal performance alongside fire ratings. German commercial property owners access EU Taxonomy-aligned green bond financing for facade renovation.
- Industrial Facilities:Warehouse and manufacturing envelope systems combine fire resistance with dust and chemical exposure tolerance. Silesian manufacturing zones in Poland deploy EU cohesion fund subsidies for these upgrades.
- Public Infrastructure:Healthcare, education, and transport buildings face stringent public procurement fire standards. Nordic hospital construction specifies stone wool systems through centralized national procurement frameworks.
Residential buildings command the greatest specification volume; industrial facilities are gaining share fastest as logistics construction accelerates across Central Europe.
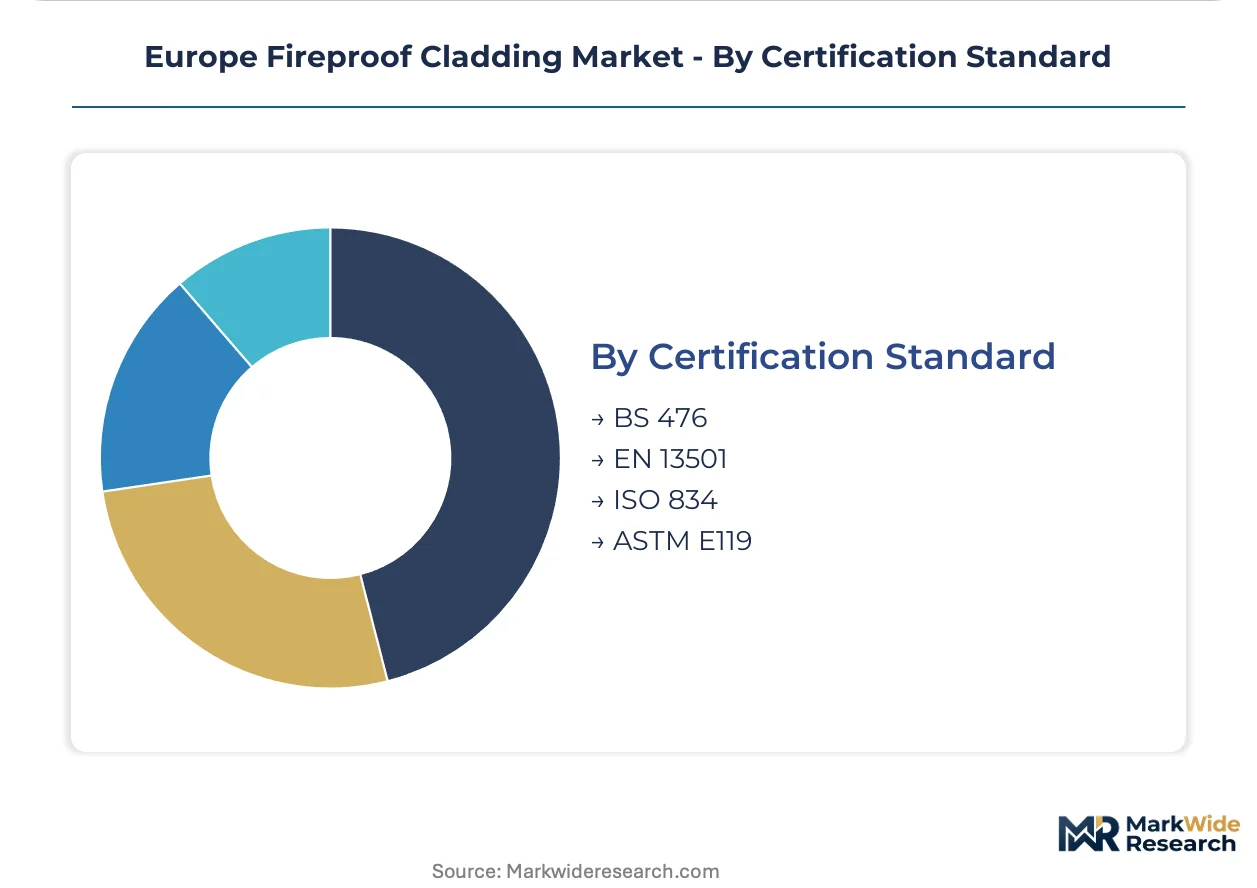
Certification Standard:
Dual certification across British and continental frameworks imposes redundant testing costs on manufacturers serving post-Brexit supply chains.
- BS 476:British fire resistance and reaction-to-fire protocols govern UK building control approval. Post-Grenfell regulatory tightening has elevated Part B compliance scrutiny for external wall systems.
- EN 13501:European classification system for construction products mandates A1 and A2 ratings for high-rise facades. System 1+ conformity assessment requires annual factory production control audits.
- ISO 834:International furnace testing standard provides cross-border equivalence for fire resistance duration claims. Manufacturers seeking Middle Eastern export markets leverage these certificates.
- ASTM E119:North American fire endurance test method supports specification in US-owned European facilities. Data center and pharmaceutical manufacturing investments drive limited demand.
EN 13501 dominates continental specification; BS 476 retains mandatory status in UK procurement despite ongoing alignment discussions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU cohesion funds and national renovation programs are concentrating fireproof cladding demand in designated metropolitan zones. Germany's KfW subsidy corridors and France's ANAH social housing zones channel specification volume toward certified suppliers. Urban remediation pipelines in London, Paris, and Berlin dominate project origination.
Germany
KfW promotional bank subsidies for building envelope upgrades are accelerating specification of A1-rated mineral fiber systems in Rhine-Ruhr metropolitan housing stock. The federal Building Energy Act mandates facade thermal performance improvements that coincide with fire safety retrofits. Munich's healthcare construction cluster specifies stone wool cladding through centralized Bavarian procurement frameworks.
France
ANAH social housing agency programs are binding HLM landlords to tower block remediation deadlines requiring non-combustible facade replacement. The RE2020 environmental regulation tightens reaction-to-fire standards for multi-family residential construction. Lyon-Grenoble corridor industrial zones deploy EU Just Transition funds for logistics facility envelope upgrades.
United Kingdom
Building Safety Regulator enforcement of Part B fire safety standards is mandating replacement of pre-2017 combustible cladding in high-rise residential towers. The Building Safety Levy funds remediation projects concentrated in Greater London and Manchester. Birmingham's social housing associations are consolidating procurement through West Midlands framework agreements.
Poland
EU cohesion fund subsidies for Silesian manufacturing zone modernization are driving warehouse and logistics facility envelope specifications. The National Reconstruction Plan allocates resources to industrial building energy efficiency including fire-resistant facade systems. Warsaw metropolitan construction permits for distribution centers are clustering specification demand in Mazovia province.
Netherlands
Stimulation Scheme for Sustainable Energy Production and Climate Transition (SDE++) subsidies are supporting commercial building facade renovations with integrated fire safety upgrades. The Environment and Planning Act consolidates permitting for high-rise remediation projects. Rotterdam port logistics corridor industrial construction specifies prefabricated non-combustible panel systems for accelerated installation.
Europe Fireproof Cladding Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated material producers dominating public procurement frameworks while regional fabricators capture project-specific installation contracts. Market structure concentrates around mineral fiber and cementitious substrate specialists with established EN 13501 certification portfolios. Three archetypes define competitive positioning: pan-European building materials conglomerates with multi-substrate portfolios, Nordic stone wool specialists leveraging continuous fiber production scale, and regional cement board producers serving climate-specific envelope requirements. Capacity expansion into prefabricated panel fabrication and backward integration into raw basalt sourcing represent the dominant competitive moves.
Among building materials conglomerates, Saint-Gobain Construction Products UK Limited and Etex Group occupy positions spanning mineral fiber, cementitious, and metal composite substrate categories. Rockwool International A/S exemplifies the Nordic stone wool specialist archetype with concentrated expertise in continuous basalt fiber production. These three companies anchor the supplier base for EU Green Deal-aligned renovation procurement.
| Leading Market Players |
|---|
| James Hardie Europe GmbH |
| Saint-Gobain Construction Products UK Limited |
| Knauf Gips KG |
| Rockwool International A/S |
| Promat |
| Owens Corning |
| Kingspan Group |
| 3A Composites Holding AG |
| Etex Group |
| Others |
Cost & Logistics Intelligence
French HLM social housing procurement concentration anchors pricing power with pan-European mineral fiber suppliers, compressing margins for regional cement board producers unable to match framework agreement volumes. The dominance of multi-year public tenders rewards manufacturers with system 1+ EN 13501 certification and pan-continental service networks.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to A1-rated stone wool panels where EN 13823 test backlog extends certification queues beyond twelve months. Project-based contract pricing dominates public infrastructure procurement, with cost differentiation resting on factory production control audit status and basalt feedstock provenance. Cost compression in standard-grade mineral fiber intensifies as Polish and Baltic producers expand continuous fiber capacity. Social housing landlords exhibit highest price sensitivity, while healthcare construction in Germany and the Netherlands tolerates premium positioning for verified lifecycle carbon data.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the Netherlands operate hub-and-spoke patterns serving high-rise remediation contractors with just-in-time panel delivery. Manufacturing concentration centers on Finland, Denmark, and Germany for stone wool, with Spain and Italy anchoring cementitious board production. Raw material portfolios draw from Baltic basalt quarries, recycled steel slag, and aluminum-zinc coated coil. Single-source vulnerability in Finnish and Lithuanian basalt supply elevates input cost volatility. Distribution runs through national building merchant networks and direct-to-contractor channels for prefabricated panel systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal renovation mandates and tightening EN 13501 certification requirements are forcing consolidation, eliminating regional players lacking multi-country service infrastructure.
For Market Incumbents:Hedge against Baltic basalt supply disruption through captive quarry investments or alternative feedstock qualification. Rockwool International A/S and Saint-Gobain Construction Products UK Limited should extend prefabricated panel fabrication capacity into Poland and the Netherlands to capture logistics construction demand. Defensive positioning requires annual system 1+ surveillance audit maintenance to retain public procurement eligibility.
For New Entrants and Emerging Players:EU cohesion fund subsidies in Poland's Silesian manufacturing zones open a window for industrial facility envelope specialists without legacy residential tower remediation exposure. Target warehouse and distribution center construction where speed-to-occupancy prioritizes prefabricated panel installation methods. Go-to-market positioning should emphasize EPD certification and EU Taxonomy alignment for green bond-financed projects.
For Investors and Strategic Acquirers:Distressed-cycle entries favor regional cement board producers in Spain and Italy with established healthcare construction relationships but limited EN 13501-1 A1 rating penetration. Long-term viability over a decade horizon rests on backward integration into raw material sourcing and prefabrication capability. Monitor ECHA REACH authorization timelines for halogenated flame retardants as inflection signal for formulation transition costs and competitive displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Quarrying | Finnish and Lithuanian feedstock control reduces geopolitical cost volatility for Nordic stone wool specialists. |
| Prefabricated Panel Fabrication Expansion | Polish logistics corridor demand rewards offsite assembly capability with compressed installation schedules. |
| Dual EN 13501 and BS 476 Certification | Post-Brexit UK market access requires parallel conformity assessment for continental manufacturers. |
| EPD Certification Investment | EU Taxonomy-aligned green bond financing favors suppliers with verified lifecycle carbon data. |
| System 1+ Factory Production Control Restructuring | Spanish cementitious board producers adapt quality assurance for annual surveillance audits. |
Research Approach
EU construction product databases, national building permit registries, and ECHA REACH authorization records formed the secondary backbone for market sizing and regulatory timeline mapping. Primary interviews with facade system procurement managers at French HLM organizations, German healthcare construction contractors, and EN 13501 certification body technical directors validated demand assumptions and testing capacity constraints. Bottom-up project pipeline analysis across London, Paris, Berlin, and Warsaw triangulated with top-down EU Green Deal renovation spending allocations.
Bottom-up modeling segmented volume and value across mineral fiber, metal composite, cement board, and high-performance insulation substrates, further disaggregated by mechanical fastening, adhesive bonding, rain screen, and prefabricated panel installation methods. End-use splits captured residential remediation, commercial renovation, industrial new-build, and public infrastructure procurement patterns. CAGRs were derived from project origination timelines, subsidy program durations, and regulatory compliance deadline clustering. EN 13823 testing queue lengths and basalt quarry capacity utilization served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for aerogel-enhanced mineral fiber composites would alter the outlook if thermal performance thresholds tighten faster than projected. Forecasts reflect documented assumptions regarding EU cohesion fund disbursement rates and national building safety regulator enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Europe Cement Market
Building Materials
Composite Rebar Market
Building Materials
Qatar Cement Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
China Architectural Coatings Market
Building Materials
Timber Frames Market
Building Materials
East Africa Cement Market
Building Materials
Construction Materials Market
Building Materials
Masonry Cement Market
Building Materials
Global Metal Cladding Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
Concrete Admixtures Market
Building Materials
US Contract Glazing Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Lightweight Precast Wall Panel Market